
 North America Commercial Vehicles Lubricants Market | 2026-2036
North America Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Commercial Vehicles Lubricants Market Analytics
Fleet operators is bifurcating demand away from independent repair shops as centralized procurement and telematics-driven oil-drain optimization gain ground. ExxonMobil Corporation leverages its integrated base oil production network across the Gulf Coast to secure feedstock cost advantages. Chevron Corporation anchors its position through proprietary additive chemistry tailored to severe-duty diesel engines. Valvoline Inc competes via rapid-lube service bays embedded directly at fleet yards and distribution centers.
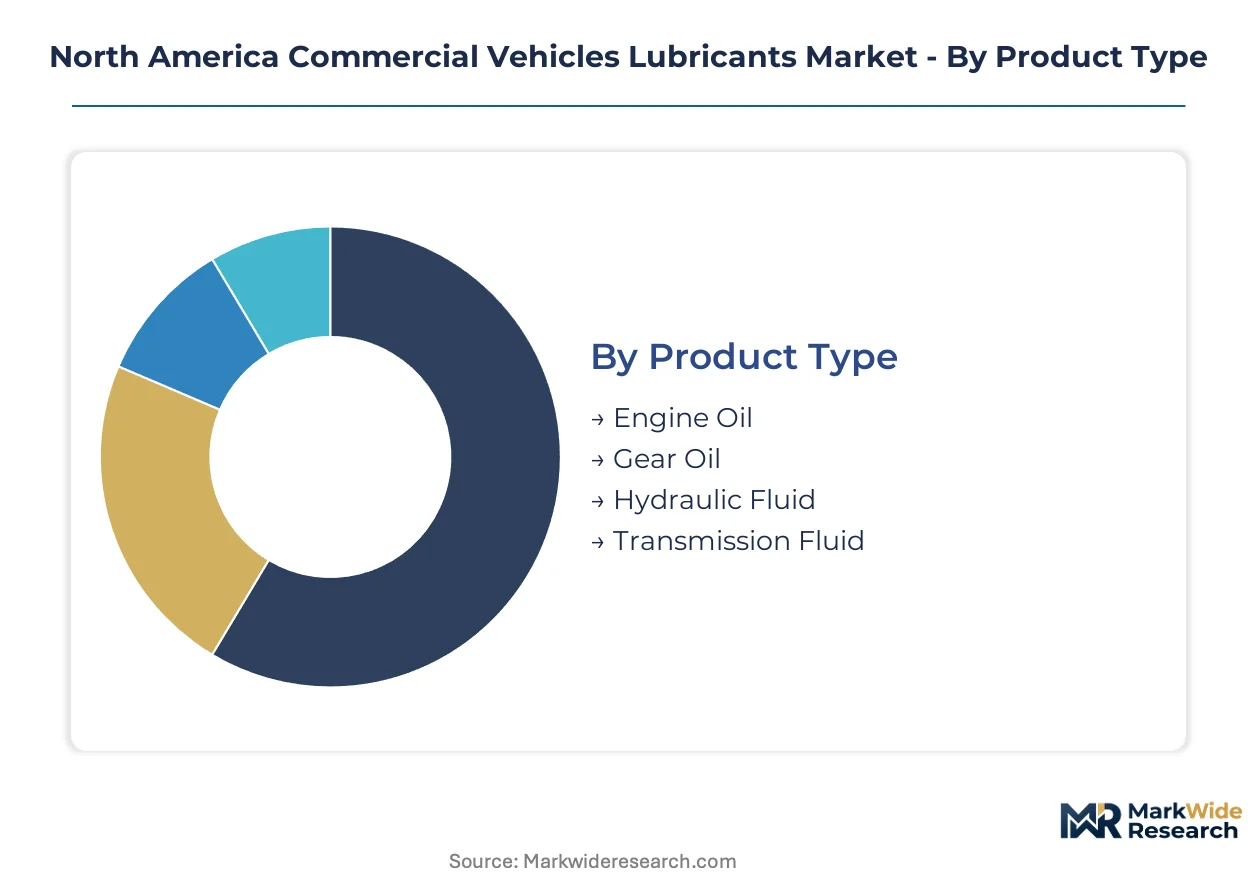
Commercial vehicles lubricants are formulated blends of base oils and performance additives engineered to reduce friction, dissipate heat, and neutralize combustion acids in diesel and natural gas engines operating under severe load cycles. Their primary purpose is extending component life and maintaining fuel efficiency in vehicles subjected to extended drain intervals and stop-start duty patterns. Engine oil commands the largest revenue pool given its high consumption frequency and technical complexity, while transmission fluid represents the fastest-expanding category as automated manual transmissions proliferate across heavy-duty truck lineups. Hydraulic fluid generates stable margins from construction equipment fleets, though agricultural vehicles applications face seasonal demand compression.
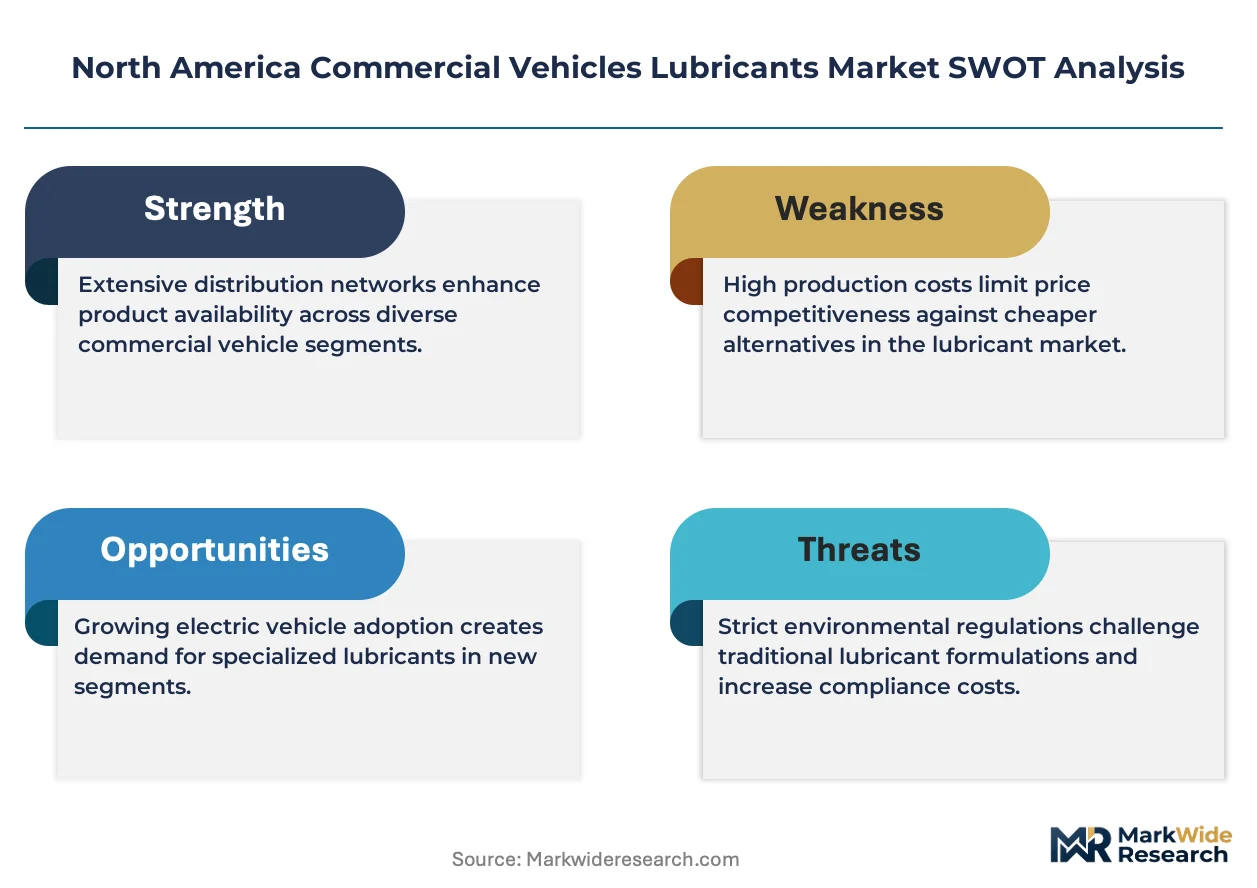
EPA emissions regulations and the California Air Resources Board (CARB) low-NOx standards compel lubricant formulators to develop products compatible with exhaust aftertreatment systems, including diesel particulate filters and selective catalytic reduction hardware. The Department of Transportation's greenhouse gas phase rules for medium- and heavy-duty vehicles further tighten viscosity-grade specifications to capture fuel economy credits. Stakeholders must weigh backward integration into additive manufacturing against specialty blending partnerships as OEM fill specifications fragment across engine platforms.
Market Dynamics
Fleet consolidation across the United States and Canada is compressing the customer base into fewer, larger buyers with centralized lubricant procurement contracts. This concentration amplifies price pressure while rewarding suppliers with telematics-enabled drain-interval optimization and direct-to-yard distribution capabilities.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:The regulation mandates fuel economy improvements that lower-viscosity engine oils help achieve, creating pull for advanced formulations across Class 8 truck lineups.
- Automated manual transmission proliferation:Heavy-duty fleets in Texas and California are retrofitting or specifying AMTs at accelerating rates, expanding addressable demand for specialized transmission fluids.
- Construction equipment electrification readiness:Hybrid hydraulic systems in excavators and wheel loaders require new thermal management fluids, opening adjacent product categories for established blenders.
Market Restraints
- Group II/III base oil supply concentration:Gulf Coast refinery capacity limits create feedstock vulnerability when hurricane disruptions or maintenance turnarounds tighten regional availability.
- Extended drain interval technology:Oil analysis programs and OEM-approved 75,000-mile service cycles reduce per-vehicle lubricant consumption volume despite higher product prices.
- Natural gas engine penetration plateau:Compressed natural gas infrastructure buildout delays in the Midwest and Mountain West constrain demand for specialized natural gas engine oils.
Strategic Opportunities
- Mexico manufacturing corridor expansion:Nearshoring of automotive and heavy equipment production to Nuevo León and Baja California creates greenfield demand for localized blending and technical service.
- CARB clean truck check program:California's enforcement mechanism for in-use vehicle compliance rewards proactive maintenance, directly benefiting premium lubricant positioning.
- Predictive maintenance platform integration:API connections between fleet telematics and lubricant supplier ERP systems enable automated replenishment and usage-based pricing models.
Industry Challenges
- PC-11 and FA-4 certification backlog:OEM approval timelines for next-generation heavy-duty diesel oils lag formulation availability, delaying commercial rollout.
- Additive package sourcing complexity:Multi-component procurement from specialized chemical suppliers requires working capital intensity and inventory risk management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Commercial Vehicles Lubricants Market |
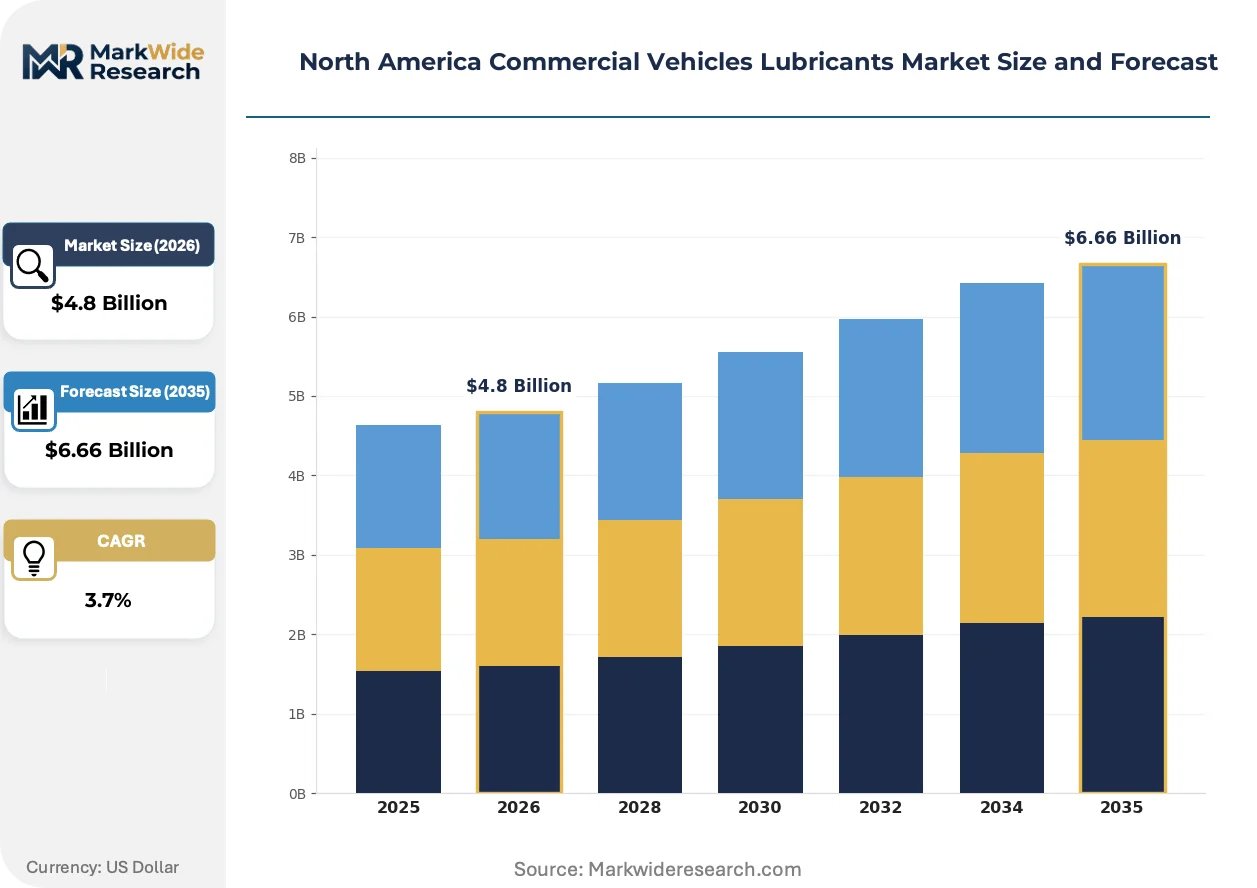
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Fluid, Transmission Fluid End User: Fleet Operators, Independent Repair Shops, Automotive Manufacturers, Service Stations Distribution Channel: Wholesale, Retail, Online, Direct Sales Application: Heavy-Duty Trucks, Buses, Construction Equipment, Agricultural Vehicles |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, Royal Dutch Shell Plc, BP PLC (Castrol), Phillips 66 Lubricants, TotalEnergies, Valvoline Inc, HollyFrontier, Fuchs Petrolub SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Commercial Vehicles Lubricants Market Evolving Landscape
Synthetic base oil technology is redefining performance benchmarks while regulatory compliance requirements fragment specification portfolios. These forces are compressing traditional product lifecycles and redistributing value toward formulation science capabilities.
Lower-viscosity SAE 5W-30 and 0W-20 heavy-duty engine oils are displacing conventional 15W-40 grades in long-haul applications. Large fleet operators with California and Texas terminals have adopted these formulations at the fastest clip. The shift is displacing mineral base oil demand while forcing blenders to reconfigure supply contracts toward Group III and PAO feedstocks.
The EPA's Phase 3 greenhouse gas standards for medium- and heavy-duty vehicles tighten viscosity-grade specifications to capture fuel economy credits. Lubricant formulators must now certify compatibility with exhaust aftertreatment systems including diesel particulate filters and selective catalytic reduction hardware. Engine oil represents the most affected category, with OEM fill specifications fragmenting across Detroit Diesel, Cummins, and PACCAR engine platforms.
Fleet procurement departments are consolidating supplier relationships into single-source or dual-source frameworks with multi-year volume commitments. Independent distributors and jobbers face margin compression as direct manufacturer-to-fleet contracts displace traditional wholesale channels. The pattern is most visible in the dedicated contract carriage segment serving retail and e-commerce distribution centers across the southeastern United States.
North America Commercial Vehicles Lubricants Market Segmentation
Segmentation in North American commercial vehicle lubricants reveals how regulatory pressure and fleet procurement centralization are fragmenting specification portfolios. EPA Phase 3 standards and CARB low-NOx compliance create divergent product requirements across customer types and equipment categories.
Product Type:
EPA emissions regulations and OEM fill specifications fragment formulation requirements across diesel and natural gas engine platforms, with viscosity-grade mandates driving distinct technical development paths.
- Engine Oil:Formulated blends of Group II/III base oils and detergent-dispersant additive packages engineered to neutralize combustion acids and maintain piston cleanliness under extended drain intervals. Heavy-duty fleets operating across Texas and California interstate corridors consume the highest volumes as lower-viscosity SAE 5W-30 and 0W-20 grades displace conventional 15W-40 formulations to capture fuel economy credits under DOT greenhouse gas rules.
- Transmission Fluid:Specialized synthetic formulations with friction modifiers and anti-wear chemistry calibrated for automated manual transmission clutch packs and synchronizer durability. Demand concentrates in Class 8 truck lineups specified by dedicated contract carriage fleets serving retail distribution centers, where AMT proliferation accelerates fastest.
- Gear Oil:High-viscosity lubricants with extreme-pressure additives protecting hypoid and spiral-bevel gear sets in drive axles and differentials.
- Hydraulic Fluid:Anti-wear and synthetic ester-based formulations circulating in construction equipment lift and steering systems.
Engine Oil handles the majority of throughput; Transmission Fluid is expanding most quickly on share as AMT adoption accelerates.
End User:
Customer concentration patterns determine pricing leverage and service-model requirements, with procurement scale dictating whether suppliers deploy direct technical service or distributor networks.
- Fleet Operators:Centralized lubricant procurement departments at trucking companies and logistics providers with 500-plus vehicle counts negotiate multi-year volume contracts. Telematics-enabled oil-drain optimization and direct-to-yard distribution capabilities determine supplier selection, with California and Texas terminals representing the densest opportunity clusters.
- Independent Repair Shops:Small and mid-sized service facilities serving owner-operators and regional carriers through jobber-supplied packaged goods. Margin compression intensifies as manufacturer-to-fleet direct contracts displace traditional wholesale channels, particularly in southeastern United States retail distribution corridors.
- Automotive Manufacturers:OEM fill specifications for new vehicle production and powertrain assembly plant requirements.
- Service Stations:Highway retail locations offering quick-lube services to for-hire trucking and private fleets.
Fleet Operators command the largest contract values; Independent Repair Shops face the steepest margin erosion from channel disintermediation.
Distribution Channel:
Supply chain configuration determines working capital intensity and inventory risk exposure, with hurricane vulnerability in Gulf Coast base oil production shaping regional availability patterns.
- Direct Sales:Manufacturer-to-fleet contracts with dedicated technical service engineers and bulk tank installations at terminal yards. Large fleet operators with California and Texas footprints have consolidated supplier relationships into single-source or dual-source frameworks, displacing traditional wholesale intermediaries.
- Wholesale:Regional distributors and jobbers supplying independent repair shops and smaller fleet accounts through packaged goods and drum deliveries. Gulf Coast refinery capacity limits create feedstock vulnerability when hurricane disruptions tighten regional availability.
- Retail:Consumer-facing packaged lubricant sales through auto parts chains and farm supply stores.
- Online:E-commerce platforms serving maintenance departments with scheduled replenishment and usage-based procurement.
Direct Sales captures the highest volume growth; Wholesale retains the broadest geographic coverage despite margin compression.
Application:
Equipment duty cycles and operating environments dictate formulation durability requirements, with seasonal patterns and electrification readiness creating divergent demand profiles.
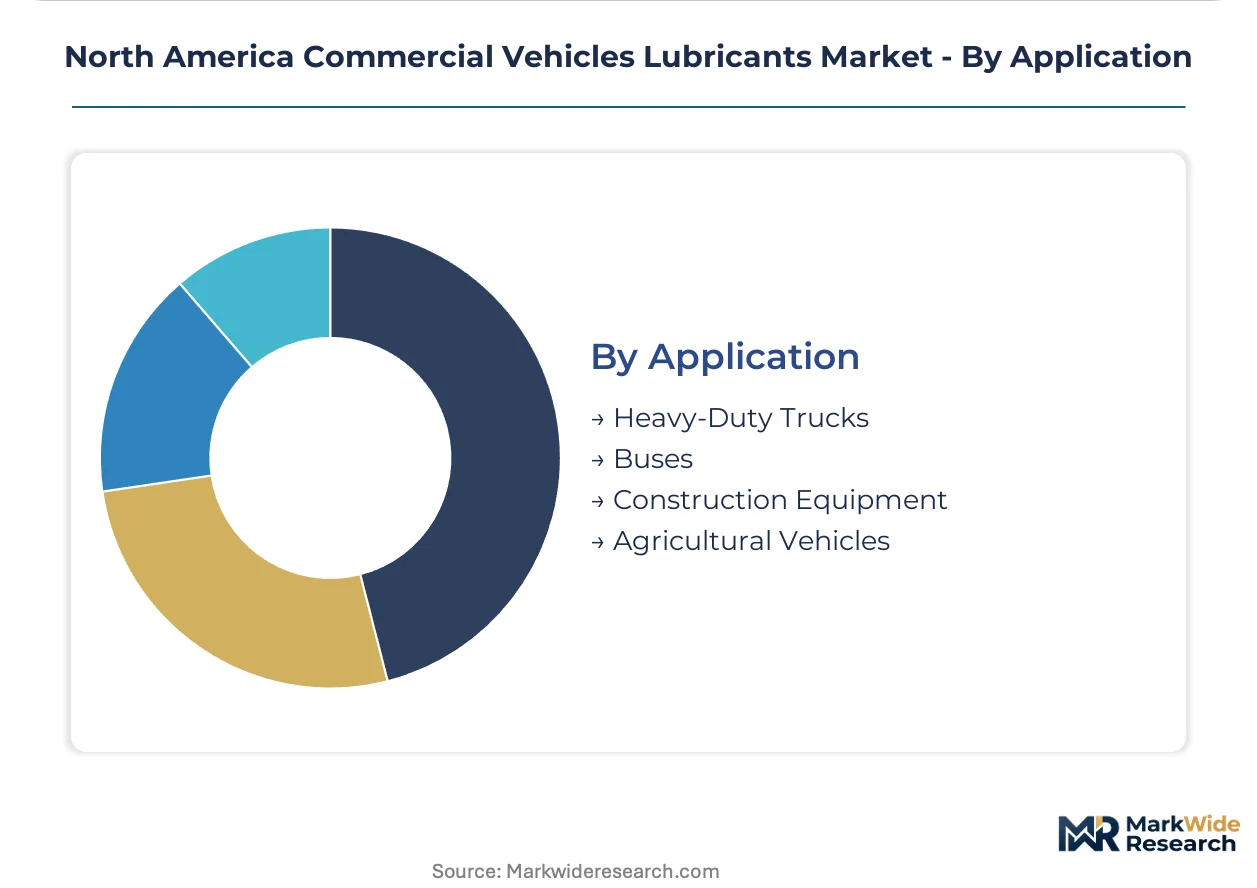
- Heavy-Duty Trucks:Class 8 long-haul and regional haul vehicles subjected to extended interstate operation and stop-start terminal duty. Texas and California corridors concentrate the heaviest lubricant consumption as EPA Phase 3 greenhouse gas standards tighten viscosity-grade specifications to capture fuel economy credits.
- Construction Equipment:Excavators, wheel loaders, and articulated trucks operating in severe dust and temperature conditions. Hybrid hydraulic systems in new equipment platforms require thermal management fluids, opening adjacent product categories for established blenders.
- Buses:Transit and coach applications with frequent stop-start cycles and depot-based maintenance programs.
- Agricultural Vehicles:Seasonal-use tractors and harvesters with compressed demand windows and rural service access challenges.
Heavy-Duty Trucks dominates absolute consumption; Construction Equipment shows the steepest formulation innovation trajectory from electrification readiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Keystone Pipeline network and Gulf Coast petrochemical corridor anchor North America's lubricant production infrastructure, with integrated refineries supplying base stocks to blenders across three national markets.
United States
Texas and California interstate corridors concentrate the heaviest lubricant consumption as long-haul fleets adopt lower-viscosity grades. EPA Phase 3 greenhouse gas standards mandate fuel economy improvements that pull advanced formulations into Class 8 truck lineups. Houston-Galveston and Los Angeles-Long Beach port complexes drive bulk demand from drayage and dedicated contract carriage fleets.
Canada
Alberta's oil sands operations and Ontario's manufacturing belt generate distinct demand profiles for severe-duty engine oils and hydraulic fluids. Environment and Climate Change Canada regulations align with EPA emissions trajectories while preserving colder-climate viscosity requirements. The Toronto-Windsor freight corridor and Vancouver port gateway concentrate fleet lubricant procurement.
Mexico
Nuevo León and Baja California manufacturing corridors attract nearshored automotive and heavy equipment production, creating greenfield blending capacity requirements. SEMARNAT environmental standards phase in Euro VI-equivalent emissions limits, compelling lubricant specification upgrades. Monterrey and Tijuana industrial clusters drive technical service demand from multinational suppliers.
North America Commercial Vehicles Lubricants Market Competitive Landscape
Listed leaders compete with private specialists across formulation capabilities and distribution reach, producing a tiered structure where integrated oil majors hold volume advantages while independent blenders defend niche positions. The vendor base clusters around three strategic archetypes: integrated refiners with captive base oil supply, additive-specialist formulators with proprietary chemistry, and service-embedded rapid-lube operators with fleet-yard presence. Dominant competitive moves include backward integration into additive manufacturing and telematics-enabled direct distribution contracts that displace traditional wholesale channels.
Among integrated oil majors, ExxonMobil Corporation and Chevron Corporation exemplify the refiner-blender archetype with Gulf Coast production footprints. Valvoline Inc occupies a distinct position as a service-embedded specialist with rapid-lube infrastructure. These three anchors illustrate how scale, chemistry control, and distribution proximity compete as alternative bases for market position.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| Royal Dutch Shell Plc |
| BP PLC (Castrol) |
| Phillips 66 Lubricants |
| TotalEnergies |
| Valvoline Inc |
| HollyFrontier |
| Fuchs Petrolub SE |
| Others |
Value Network & Pricing Analysis
Group III synthetic base oil substitution for mineral stocks redraws procurement geography toward Gulf Coast refiners while compressing per-gallon margins across conventional blend tiers. EPA Phase 3 fuel economy mandates accelerate this displacement, forcing reformulation investments that concentrate pricing power with integrated producers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs fleet procurement contracts, with differentiation anchored in API certification grade and telematics-enabled drain interval performance. Price erosion runs through the economy tier as independent distributors lose volume to direct manufacturer-to-fleet agreements. Fleet operators with 500-plus vehicle counts exhibit lowest price sensitivity due to total-cost-of-ownership optimization, while owner-operators served through jobber channels face margin compression without volume leverage.
Supply Chain Analysis
Hurricane Alley transit vulnerability through the Houston Ship Channel underwrites regional feedstock security concerns for North American blenders. Gulf Coast refinery concentration in the United States draws from Canadian oil sands and domestic shale, resting on additive package imports from specialized chemical suppliers. Single-source vulnerability concentrates in detergent-dispersant component procurement. Distribution runs through bulk tank terminals at fleet yards, displacing drum-and-package wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics platform interoperability is transforming lubricant procurement into a data-integrated subscription economy, with API connections between fleet ERP systems and supplier replenishment engines redefining contract value.
For Market Incumbents: Shield market position through captive additive manufacturing investments and direct-to-yard bulk infrastructure expansion. Synthetic base oil backward integration protects margin structure against Gulf Coast feedstock volatility. Telematics-enabled usage-based pricing contracts defend against independent blender price aggression in the long-haul fleet segment. For New Entrants and Emerging Players: Lead with Mexico manufacturing corridor greenfield blending capacity as nearshoring accelerates demand in Nuevo León and Baja California. Hybrid hydraulic thermal management fluids for construction equipment electrification represent the most penetrable white-space category. Technical service partnerships with Monterrey industrial clusters provide go-to-market traction without incumbent distribution baggage. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors additive-specialist formulators with proprietary chemistry and fleet-yard service infrastructure. Long-term viability hinges on formulation science capabilities rather than commodity blending scale. Watch CARB clean truck check program enforcement intensity as the inflection signal for premium lubricant demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captive supply of detergent-dispersant packages insulates margin from specialty chemical supplier concentration. |
| Telematics Platform Integration | API connections with fleet ERP systems enable automated replenishment and usage-based pricing contracts. |
| Mexico Manufacturing Corridor Expansion | Localized blending in Nuevo León captures nearshored automotive and heavy equipment production demand. |
| Lower-Viscosity Grade Certification Investment | SAE 5W-30 and 0W-20 approvals secure EPA Phase 3 fuel economy credit capture for fleet customers. |
| Direct-to-Yard Distribution Infrastructure | Bulk tank installations at Texas and California terminals displace wholesale jobber channels. |
Research Methodology
The analysis maps engine oil, transmission fluid, gear oil, and hydraulic fluid sub-sectors, each validated through fleet procurement directors, lubricant blending plant managers, additive supplier technical leads, and aftermarket distribution channel heads. Primary interview intelligence triangulates against customs trade data, American Petroleum Institute certification registries, SEC 10-K filings, and Department of Transportation greenhouse gas compliance filings. Bottom-up volume builds from fleet operator consumption models cross-check against top-down refinery capacity assessments.
Consistency checks against EPA compliance timelines and OEM fill specification trajectories validated projection outputs across the modeling period. Segmentation dimensions include product viscosity grade, end-use equipment category, procurement channel configuration, and fleet size tier. CAGRs derive from segment-level volume trajectories adjusted for drain interval extension effects and base oil substitution elasticities. Forecast inputs incorporate CARB enforcement intensity assumptions and Mexico SEMARNAT regulatory phase-in schedules.
The analysis sits within stated boundaries; outcomes outside EPA Phase 3 adherence timelines or Gulf Coast hurricane disruption frequencies would require recalibration. Forecasts reflect documented assumptions regarding AMT penetration rates and natural gas engine adoption curves. Revision becomes warranted when telematics platform standardization crosses interoperability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Flexographic Printing Plate Market
Others
Global Tobacco Market
Others
Retail Digital Signage Market
Others
Double Card Mobile Phone Market
Others
Global Molded Plastics Market
Others
Wingboards Market
Others
AC Switchgear Market
Others
Europe Tablet PC Market
Others
High Frequency Vibrator Market
Others
Heavy Duty Vacuum Bottle Market
Others
Over the Top Devices and Services Market
Others
Asia-Pacific Social Media Management Market
Others
Latin America Domestic CEP Market
Others
Global Webinar and Webcast Market
Others
Global Thermally Conductive Grease Market
Others
South America Halal Food and Beverages Market