
 Global Molded Plastics Market | 2026-2036
Global Molded Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molded Plastics Market Foresight
Advanced recycling and bio-based feedstock integration is narrowing the performance gap between virgin and circular polymers. Dow leverages its Gulf Coast manufacturing scale to anchor North American polyethylene supply. LyondellBasell Industries sustains its polypropylene leadership through catalyst technology investments. SABIC competes aggressively in engineering thermoplastics for automotive electrification platforms.
Molded plastics are thermoplastic or thermoset polymers shaped under heat and pressure into precise geometries, typically within tolerances of ±0.1 mm for injection-molded components, serving as structural, protective, or functional elements across industrial and consumer goods. Polypropylene dominates material consumption due to its balance of chemical resistance, processability, and cost structure, though acrylonitrile butadiene styne is displacing conventional polymers in appliance housings requiring impact strength and surface finish. Injection molded plastics command the largest value share given their suitability for complex, high-volume parts, while blow molded plastics retain primacy in liquid packaging and fuel tank applications where hollow forms are essential.
The EPA regulates volatile organic compound emissions from molding operations under Clean Air Act provisions, while REACH restricts phthalate plasticizers and persistent organic pollutants in European-sourced materials. FDA Title 21 compliance governs food-contact applications in the United States, creating certification barriers for imported compounds. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and state-level plastic packaging fees in California and New York, as these mechanisms will reshape cost structures and material selection criteria faster than technical substitution cycles.
Market Dynamics
Automotive electrification and battery housing demand are compressing material qualification cycles while forcing resin suppliers to co-develop flame-retardant formulations with tier-1 molders in Germany and China.
Growth Catalysts
- REACH chemical restrictions:European phthalate bans are accelerating migration to bio-based plasticizers in food-contact applications, opening formulation partnerships between compounders and packaging OEMs.
- Electric vehicle battery housings:Thermal runaway protection requirements are pulling engineering thermoplastics into enclosures previously served by metals, with Chinese OEMs qualifying grades in 12-month windows.
- Injection molding automation:Collaborative robotics and in-mold sensors are cutting cycle times and defect rates in medical device production, expanding addressable volumes for precision molders.
Market Restraints
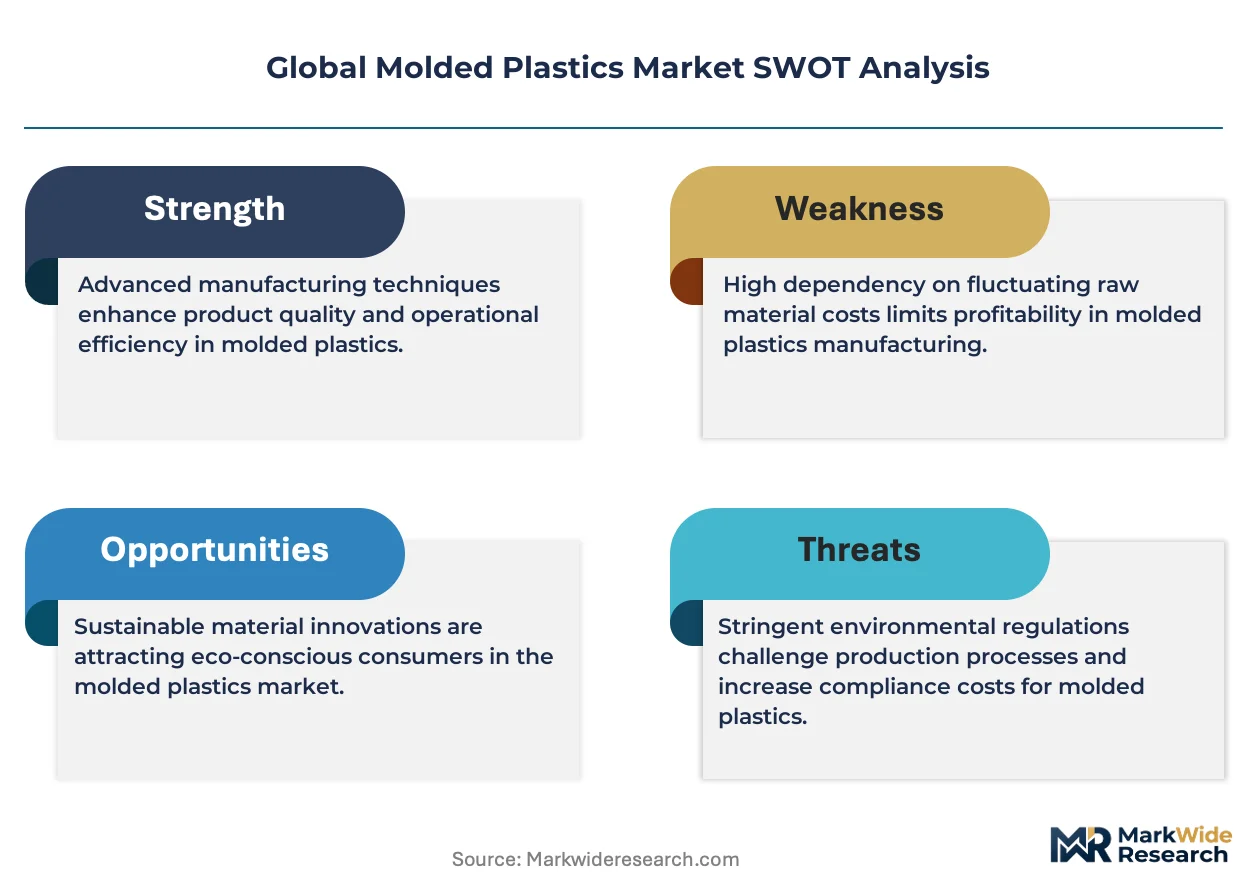
- Propylene feedstock volatility:Crude-oil-linked naphtha costs transmit directly to polypropylene pricing, squeezing compounder margins and discouraging long-term supply contracts.
- Gulf Coast concentration:Over half of North American polyethylene capacity clusters along hurricane-exposed Texas and Louisiana corridors, creating force majeure exposure.
- Metal substitution limits:Structural load-bearing automotive components above 150°C service temperatures remain inaccessible to thermoplastics due to creep resistance ceilings.
Strategic Opportunities
- India packaging conversion:FSSAI food-grade certification gaps in domestic compounding create first-mover advantage for imported pre-colored resins in dairy and edible oil segments.
- Chemical recycling integration:Pyrolysis-derived naphtha is achieving ISCC PLUS certification parity with virgin feedstock, enabling circular claims in EU-sourced automotive interiors.
- Digital mold monitoring:IoT-enabled cavity pressure sensors are enabling predictive maintenance contracts, shifting revenue models from piece-part to uptime-guarantee structures.
Industry Challenges
- Tooling engineer scarcity:Multi-cavity hot-runner design expertise is concentrating among mold-makers in southern Germany and eastern China, inflating lead times for complex medical molds.
- FDA 510(k) synchronization:Device enclosure material changes trigger regulatory resubmission, locking molders into legacy resin grades for 18-24 month qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molded Plastics Market |
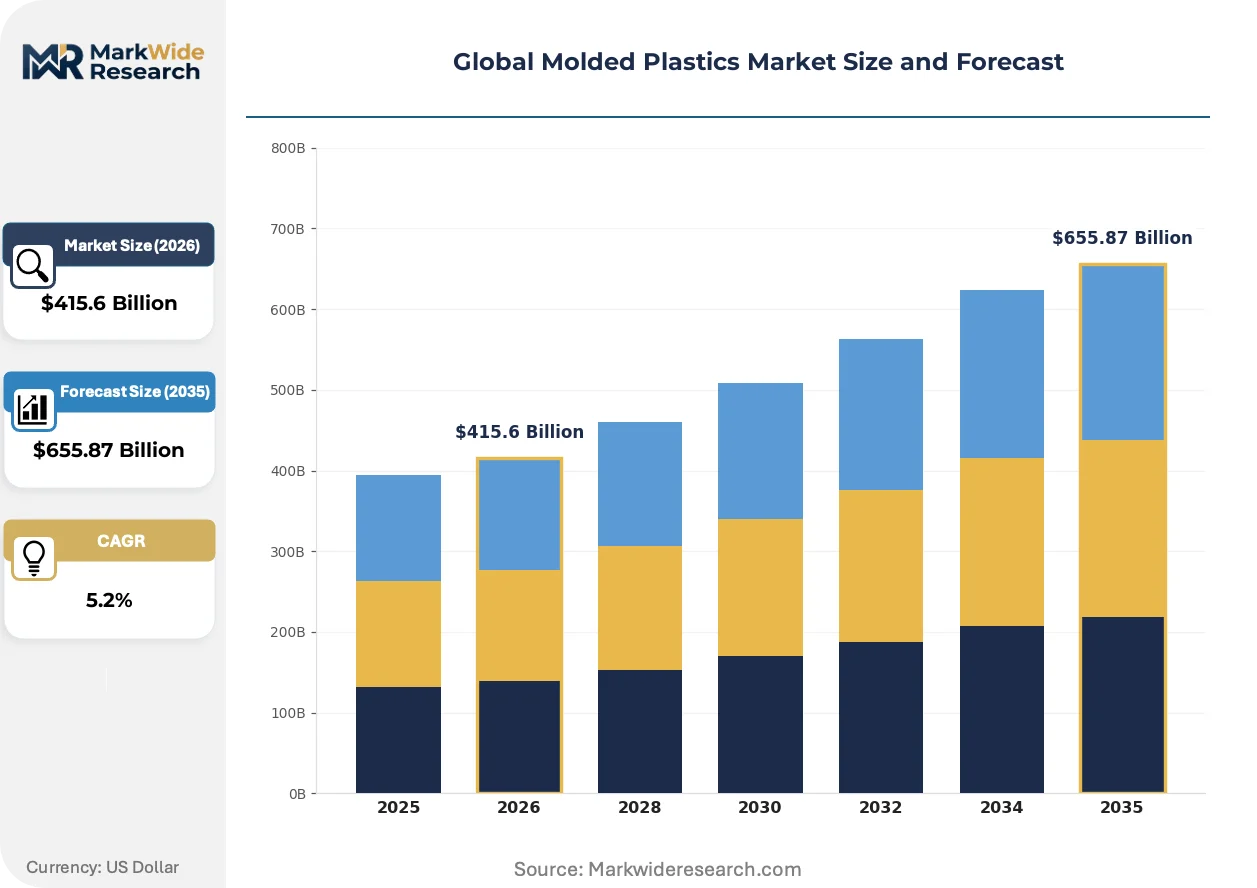
| Market Size in 2026 | $415.6 Billion |
| Market Size in 2035 | $655.87 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molded Plastics, Blow Molded Plastics, Thermoformed Plastics, Compression Molded Plastics, Transfer Molded Plastics Material: Polypropylene, Polyethylene, Polystyrene, Acrylonitrile Butadiene Styrene, Polyvinyl Chloride Application: Packaging, Consumer Appliances, Electrical & Electronics, Construction, Automotive Components End User: Manufacturers, Fabricators, Molders, Assemblers, Distributors |
| Companies Covered | BASF SE, Eastman Chemical Company, LyondellBasell Industries, DuPont, Dow, SABIC, ExxonMobil Corporation, Huntsman Corporation, INEOS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molded Plastics Market Shifts & Advancements
Advanced recycling infrastructure and real-time process control are collapsing the cost and performance gaps between virgin and circular polymers while enabling mass-customization at automotive volumes.
MuCell microcellular foaming is rendering obsolete solid-wall construction in automotive interior panels. German OEMs are qualifying foamed polypropylene door trims for 2025 model-year vehicles. The technology is compressing part weights 15-20% without sacrificing dimensional stability, forcing toolmakers to redesign cooling circuits for gas-injection sequences.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are eliminating legacy flame-retardant options in electrical housings. Compounders are pivoting to phosphorus-nitrogen intumescent systems, though these require 30% higher loadings. Italian appliance manufacturers are absorbing the reformulation costs to maintain CE marking access.
Automotive OEMs are consolidating resin procurement through platform-grade specifications. Tier-1 molders in Michigan and Stuttgart are losing direct compounder relationships as Volkswagen and BMW centralize material approvals. The shift is compressing formulation differentiation and privileging suppliers with captive polymerization assets.
Global Molded Plastics Market Segmentation
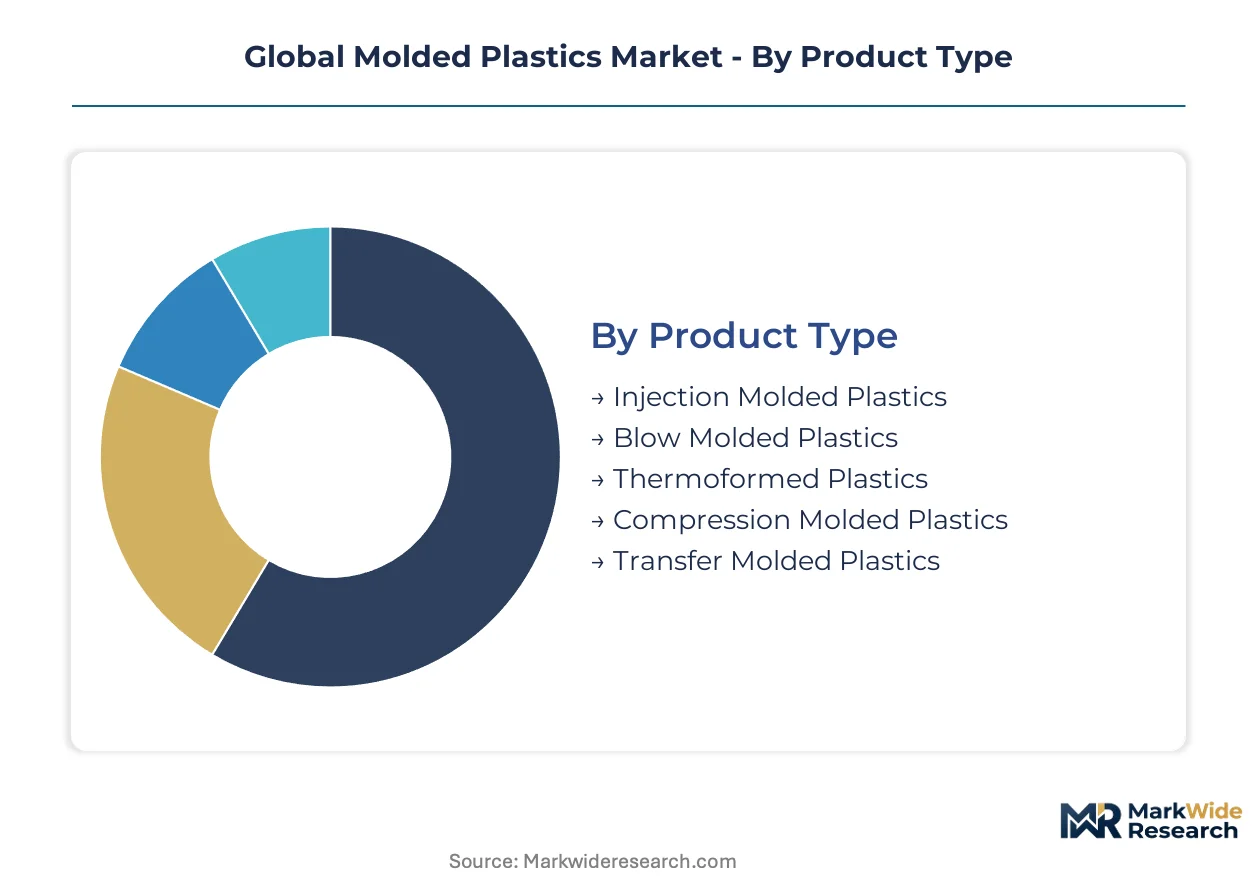
Molded plastics segmentation reveals how process economics, material specifications, and end-use performance requirements fragment supply chains. Each dimension carries distinct margin profiles and qualification barriers that reshape competitive positioning across automotive, medical, and packaging verticals.
Product Type:
Process selection spans from high-precision automotive housings to thin-wall food containers, with cycle time and tooling investment determining addressable volumes.
- Injection Molded Plastics:Thermoplastic polymers forced into precision-engineered cavities under 1,000-30,000 psi pressure yield complex geometries with ±0.1 mm tolerances. Battery enclosure demand from Chinese and German EV platforms is compressing qualification cycles below 12 months.
- Blow Molded Plastics:Parison inflation creates seamless hollow forms for fuel tanks and liquid packaging where structural integrity meets weight minimization. Automotive fuel system manufacturers in Stuttgart and Detroit favor multi-layer coextrusion for permeation resistance.
- Thermoformed Plastics:Heated sheet vacuum-drawn over molds produces shallow trays and blister packs at lower capital intensity than injection systems. Medical device sterile packaging in Massachusetts and Bavaria drives thin-gauge PET specification.
- Compression Molded Plastics:Preheated charge pressing suits thermoset composites requiring dimensional stability above 200°C. Electrical insulator manufacturers favor bulk molding compounds for switchgear housings.
- Transfer Molded Plastics:Plunger-forced resin injection into closed molds enables intricate thermoset parts with minimal flash. Semiconductor encapsulation operations in South Korea and Taiwan specify epoxy transfer for integrated circuit protection.
Established volume favors injection molding; emerging adoption favors blow molding for hydrogen storage tank liners.
Material:
Resin selection balances chemical resistance, processability, and regulatory compliance across temperature and stress regimes.
- Polypropylene:Semi-crystalline polymer with 0.90 g/cm³ density and 160°C melting point dominates automotive interiors and food containers. REACH phthalate restrictions are accelerating bio-based plasticizer formulation partnerships in European dairy packaging.
- Polyethylene:Linear low-density grades offer puncture resistance for stretch film and squeeze tubes. Gulf Coast concentration of North American capacity exposes compounders to hurricane-related force majeure events.
- Polystyrene:Amorphous thermoplastic with 100°C heat deflection serves disposable cutlery and electronics cushioning. Expanded bead foam for appliance packaging faces EPS bans in California and New York state regulations.
- Acrylonitrile Butadiene Styrene:Rubber-toughened styrenic delivers surface gloss and impact strength for appliance housings and cosmetic containers. Japanese appliance OEMs specify high-heat grades for rice cooker enclosures.
- Polyvinyl Chloride:Chlorinated backbone provides inherent flame retardancy and chemical resistance for wire insulation and medical tubing. ECHA restrictions on lead stabilizers are forcing calcium-zinc system migration in European construction profiles.
Polypropylene captures the highest volume share; acrylonitrile butadiene styrene gains share fastest in premium appliance segments.
Application:
End-use performance requirements fragment specifications from food-contact compliance to thermal runaway protection.
- Packaging:Barrier properties and FDA Title 21 compliance govern dairy, edible oil, and pharmaceutical containers. Indian FSSAI certification gaps create first-mover openings for imported pre-colored resins.
- Consumer Appliances:Surface aesthetics and drop-impact resistance define housing specifications for white goods and personal electronics. MuCell microcellular foaming is displacing solid-wall construction in German OEM door trim programs.
- Electrical & Electronics:Flame-retardant formulations meeting UL 94 V-0 ratings protect connectors and enclosures. REACH Annex XVII short-chain chlorinated paraffin bans are forcing phosphorus-nitrogen intumescent system adoption in Italian appliance manufacturing.
- Construction:UV stability and creep resistance specify window profiles, piping, and geomembranes. PVC window frame demand concentrates in German and Polish residential renovation cycles.
- Automotive Components:Lightweighting targets and thermal management requirements reshape material selection for battery housings and underhood applications. OEM platform-grade consolidation is compressing tier-1 molder direct compounder relationships.
Packaging commands the broadest volume base; automotive components present the steepest specification escalation trajectory.
End User:
Value chain position determines technical capability requirements and margin capture potential.
- Manufacturers:Captive resin production and formulation expertise anchor supply security for automotive and medical verticals. Dow's Gulf Coast polyethylene scale exemplifies polymerization-integrated positioning.
- Fabricators:Sheet and profile extrusion operations serve construction and signage applications with lower capital barriers than precision molding.
- Molders:Injection and blow molding specialists face tooling engineer scarcity for multi-cavity hot-runner medical mold design in southern Germany and eastern China.
- Assemblers:Component integration operations source standardized parts from distributed molder networks, prioritizing logistics cost over technical differentiation.
- Distributors:Resin and compound warehousing functions bridge geographic and minimum order quantity gaps for mid-volume processors.
Manufacturers retain margin through captive supply; molders face capability concentration pressures in precision medical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders export engineering thermoplastics to Chinese battery housing manufacturers, while Gulf Coast polyethylene flows to Mexican packaging converters under USMCA tariff preferences.
United States
Automotive lightweighting programs in Michigan and Ohio drive demand for glass-filled polypropylene structural components. EPA Clean Air Act enforcement tightens volatile organic compound limits on molding operations in Texas and Louisiana. Houston-Galveston corridor concentration of polyethylene capacity exposes compounders to hurricane-related supply disruptions.
Germany
BMW and Volkswagen platform-grade specifications consolidate resin procurement through centralized material approval systems. REACH Annex XVII restrictions on short-chain chlorinated paraffins force phosphorus-nitrogen flame-retardant adoption in electrical housings. Stuttgart mold-makers concentrate multi-cavity hot-runner expertise for medical device enclosures.
China
CATL and BYD battery enclosure programs compress engineering thermoplastic qualification cycles below twelve months. MIIT dual carbon goals accelerate pyrolysis-derived naphtha integration into automotive interior supply chains. Yangtze River Delta molders dominate precision injection capacity for electric vehicle battery housings.
India
Dairy and edible oil packaging conversion creates demand for FSSAI-compliant pre-colored polypropylene resins. FSSAI certification gaps in domestic compounding open first-mover advantage for imported resin suppliers. Gujarat petrochemical corridors anchor polyethylene and polypropylene production scale.
Japan
Rice cooker and small appliance OEMs specify high-heat acrylonitrile butadiene styrene grades for premium housing applications. METI circular economy frameworks promote chemical recycling infrastructure development. Kansai region molders specialize in thin-wall precision components for consumer electronics.
Global Molded Plastics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where polymerization-integrated multinationals anchor supply security and regional compounders fill formulation gaps. The vendor base stratifies into three archetypes: captive resin producers with Gulf Coast or European polymerization assets, independent compounders serving medical and automotive qualification pipelines, and distributed molders competing on logistics proximity. Dominant competitive moves include backward integration into pyrolysis feedstock sourcing and strategic partnerships for flame-retardant co-development with tier-1 automotive suppliers.
Within the polymerization-integrated tier, BASF SE and Dow exemplify channel control through captive supply chain positioning, while LyondellBasell Industries occupies a specialist role in polypropylene catalyst technology. SABIC anchors engineering thermoplastic supply for automotive electrification platforms. These four entities represent distinct competitive vectors: European diversified chemicals, North American Gulf Coast scale, catalyst-led polypropylene leadership, and Middle East-European engineering resin specialization.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| LyondellBasell Industries |
| DuPont |
| Dow |
| SABIC |
| ExxonMobil Corporation |
| Huntsman Corporation |
| INEOS Group |
| Others |
Supply & Pricing Matrix
Gulf Coast hurricane exposure concentrates polyethylene capacity along a single geographic corridor, compressing pricing spreads between premium engineering grades and commodity polypropylene while forcing compounders to carry buffer inventory against force majeure disruption.
Pricing Analysis
Current-generation injection molding compounds command premium spreads over legacy blow molding grades, while next-generation pyrolysis-derived circular polymers approach price parity with virgin feedstock. Three-tier pricing structure across premium flame-retardant engineering thermoplastics, standard food-contact polypropylene, and economy construction-grade polyethylene stratifies the market. Cost compression in commodity polyethylene intensifies as naphtha feedstock volatility transmits directly from crude oil markets. Small appliance OEMs in Japan exhibit the least price sensitivity due to surface finish requirements, while Indian dairy packaging converters face acute pressure from FSSAI compliance costs.
Supply Chain Analysis
Extended payment terms from German automotive OEMs to tier-1 molders cascade stress upstream to compounders, compressing working capital cycles throughout the value chain. Raw material sourcing draws from Saudi ethane crackers, Texas Gulf Coast naphtha crackers, and Chinese coal-to-olefins complexes. Polymerization capacity rests on propylene and ethylene monomer flows, with catalyst technology controlled by LyondellBasell and SABIC. Single-source vulnerability concentrates in multi-cavity hot-runner mold fabrication, where Stuttgart and eastern China toolmakers dominate medical-grade production. Distribution runs through regional resin distributors bridging minimum order quantity gaps for mid-volume processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical restrictions and MIIT dual carbon mandates are accelerating feedstock transition timelines, compressing the window for legacy resin suppliers to establish circular polymer credentials.
For Market Incumbents: Harden supply security through backward integration into pyrolysis-derived naphtha sourcing, securing ISCC PLUS certification ahead of EU automotive interior mandates. Expand flame-retardant co-development partnerships with CATL and BYD to lock in battery housing specifications before platform-grade consolidation eliminates direct compounder relationships.
For New Entrants and Emerging Players: FSSAI certification gaps in Indian domestic compounding represent the most penetrable entry point for imported pre-colored polypropylene resins targeting dairy and edible oil packaging. Chemical recycling infrastructure partnerships with Gujarat petrochemical corridors offer asset-light market access. Lead with regulatory compliance as the primary go-to-market wedge against established local compounders.
For Investors and Strategic Acquirers: REACH Annex XVII expansion reshapes the acquisition landscape toward phosphorus-nitrogen flame-retardant formulation specialists and pyrolysis technology platforms. Long-term viability centers on circular polymer integration capabilities rather than virgin resin scale. The signal to watch is OEM platform-grade specification releases from Volkswagen and BMW, which will determine which compounders retain formulation differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis Feedstock | ISCC PLUS certification enables circular claims in EU automotive interiors. |
| Flame-Retardant Co-Development Partnership | Thermal runaway protection specifications lock in battery enclosure supply. |
| Multi-Cavity Hot-Runner Tooling Acquisition | Medical device mold expertise concentrates in southern Germany and eastern China. |
| FSSAI Pre-Certified Resin Import Expansion | First-mover advantage in Indian dairy packaging conversion accelerates volume capture. |
| Platform-Grade Specification Alignment | Centralized OEM material approvals privilege suppliers with captive polymerization assets. |
Research Methodology
A standing panel of polymerization plant managers, automotive tier-1 procurement directors, medical device molders, and packaging OEM technical buyers provided ongoing calibration across primary fieldwork. Secondary validation drew from customs and trade flow databases, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration dossiers. Bottom-up volume modeling triangulated against top-down macroeconomic elasticity estimates to anchor forecast integrity.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling spanning process technology, material grade tier, end-use vertical, and regional production hub. CAGRs derived from elasticity-adjusted volume trajectories incorporating EV battery housing content per vehicle, packaging conversion rates, and medical device enclosure specification escalations. Feedstock cost pass-through assumptions and regulatory compliance timeline probabilities informed sensitivity bounds.
Macroeconomic conditions sit as an overlay; deviation in crude oil price volatility, hurricane frequency along the Gulf Coast, or REACH restriction expansion timelines would shift the trajectory. Forecasts reflect documented assumptions on polymer substitution elasticity and circular polymer adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Laser Hair Removal Market
Others
Connected TV Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Deflectometer Market
Others
Double Card Mobile Phone Market
Others
Land Surveying Equipment Market
Others
Aircraft Exterior Lighting Market
Others
Cathode Battery Material Market
Others
Tripod Market
Others
Automatic Barriers and Bollards Market
Others
Moonstone Market
Others
Gym Wipes Market
Others
Insoluble Sulfur Market
Others
Asia-Pacific Professional Scalp Treatment Products Market
Others
Defense Optronics Market
Others
Rugged Devices Market