
 Gas Radiators Market | 2026-2036
Gas Radiators Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Radiators Market Intelligence
The divide between premium, aesthetically integrated panel radiators and commodity-grade convector units is hardening within the market. Companies like Stelrad and Kermi GmbH compete on manufacturing scale and broad distribution for standard applications. In contrast, Italkero specializes in design-forward, high-end products for specific architectural needs. Vaillant leverages its brand strength in the boiler market to offer integrated heating system packages.
A gas radiator is a self-contained heating appliance that combusts fuel like natural gas or propane to directly warm a space. These units utilize a heat exchanger to transfer thermal energy to the surrounding air, operating independently of a central boiler. Panel radiators command a significant share due to their aesthetic appeal in residential heating applications. The convector type remains a staple in commercial facilities, valued for rapid heat-up times and durability.
Product design and market access are governed by safety and efficiency standards, such as the CE marking requirements under the EU's Gas Appliances Regulation. The Ecodesign Directive further mandates minimum energy performance levels for new installations. In the United States, ANSI Z21 standards ensure operational safety. Future competitiveness will hinge on manufacturers' ability to integrate smart controls and improve performance with alternative fuels like biogas.
Market Dynamics
The imperative to enhance energy efficiency within residential heating systems serves as the central structural force shaping the gas radiators market. This pressure, codified through regulations like the EU's Ecodesign Directive, is compelling a market-wide pivot toward more advanced product designs.
Growth Catalysts
- Energy Efficiency Mandates:Regulations such as the EU's Ecodesign Directive and Gas Appliances Regulation create a replacement cycle by mandating higher energy performance and safety standards for new installations.
- Residential Sector Modernization:Ongoing renovation and upgrade cycles in regions with extensive gas infrastructure, particularly in countries like Poland and Italy, sustain demand for modern, efficient heating units.
- Aesthetic Product Innovation:The development of slim, design-forward panel radiators that integrate seamlessly into modern interiors stimulates demand in the premium residential segment, moving beyond purely functional heating.
Market Restraints
- Substitution by Electrification:A systemic shift towards building electrification, favoring heat pumps and electric resistance heating, presents a significant long-term substitution threat to gas-fired appliances.
- Natural Gas Price Volatility:Fluctuations in the price of natural gas and propane directly impact the total cost of ownership, creating uncertainty for consumers and potentially delaying purchasing decisions.
- Regulatory Headwinds:Increasing policy momentum in some municipalities and regions to phase out or ban new gas connections in residential construction directly curtails market access and growth potential.
Strategic Opportunities
- Smart Home Integration:Incorporating IoT connectivity and smart thermostat compatibility allows for remote control and optimized energy consumption, opening a new value proposition for tech-savvy homeowners.
- Alternative Fuel Compatibility:Engineering radiators to operate with greener fuels, such as biogas or hydrogen-natural gas blends, provides a pathway to decarbonize and future-proof the technology.
- Commercial Retrofit Applications:Targeting under-served commercial spaces like workshops, warehouses, and garages with powerful, standalone convector units offers an avenue for growth outside the competitive residential market.
Industry Challenges
- Complex Compliance Pathways:Manufacturers face significant operational burdens navigating and maintaining compliance with a fragmented landscape of regional standards, including CE marking in Europe and ANSI Z21 in the United States.
- Installer Skill Gaps:The integration of advanced electronics and smart controls requires a higher level of technical expertise for installation and servicing, creating a potential training gap in the HVAC technician workforce.
- Supply Chain Adjustments:The shift from basic mechanical convectors to electronically controlled panel radiators necessitates sourcing new components like sensors and control boards, reconfiguring supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Radiators Market |
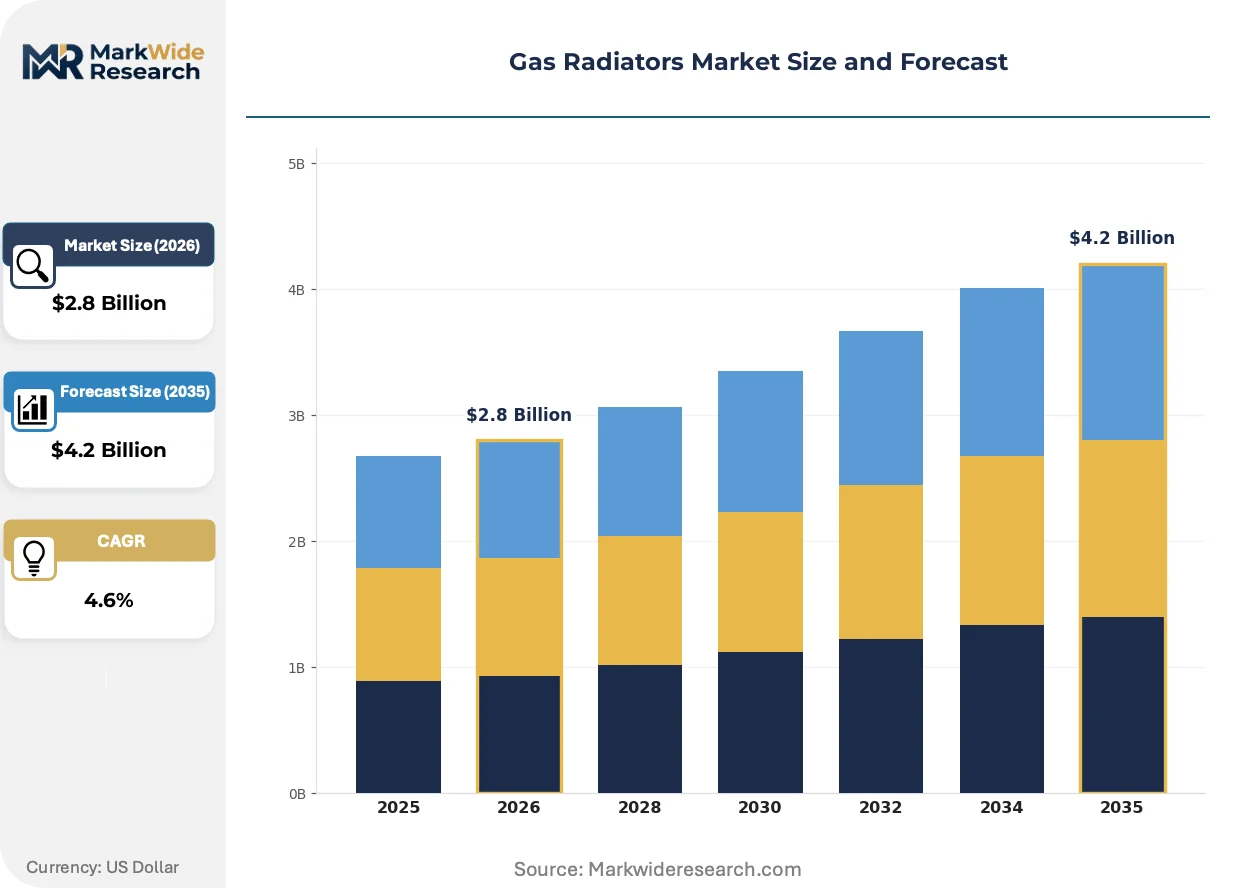
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Convector, Panel, Column, Baseboard, Fan-Assisted Fuel Type: Natural Gas, Propane, Butane, Liquefied Petroleum Gas, Biogas Application: Residential Heating, Commercial Facilities, Institutional Buildings, Hospitality Sector, Public Amenities End User: Homeowners, Property Managers, Facility Operators, Renovation Firms, Construction Contractors |
| Companies Covered | Italkero, Robur, Stelrad, Fondital, Vaillant, Baxi, Kermi GmbH, Myson, Trane Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Radiators Market Strategic Shifts & Innovations
Product evolution is driven by the convergence of efficiency mandates and consumer demand for digital control. This dual pressure accelerates investment in smarter combustion technologies and connected features, fundamentally altering the value proposition from simple heat to managed comfort.
Smart Controls and Connectivity
Integrated Wi-Fi modules and compatibility with smart home ecosystems define the new generation of premium gas radiators. Residential customers in new-build and renovation projects are the primary adopters, seeking zone control and scheduling via mobile applications. The integration of these digital features is overtaking the traditional, manually adjusted radiator as the expected standard in the market, redefining user convenience.
Ecodesign Directive Enforcement
The European Union's Ecodesign Directive continues to be a primary shaper of product development. It establishes strict minimum energy performance standards and lower nitrogen oxide (NOx) emission ceilings, which has forced the obsolescence of older, less efficient models. Manufacturers targeting the vast European residential market are most affected, compelled to innovate in burner and heat exchanger design to meet these non-negotiable thresholds.
Aesthetic Integration as a Priority
A distinct demand-side shift favors radiators that are integrated as intentional architectural elements. This trend disrupts the market for purely utilitarian convector units, especially in residential settings, creating a preference for customizable, low-profile panel designs. This focus on aesthetics is most prominent within high-end residential projects and architect-led specifications in Western European countries like Italy and Germany.
Gas Radiators Market Segmentation
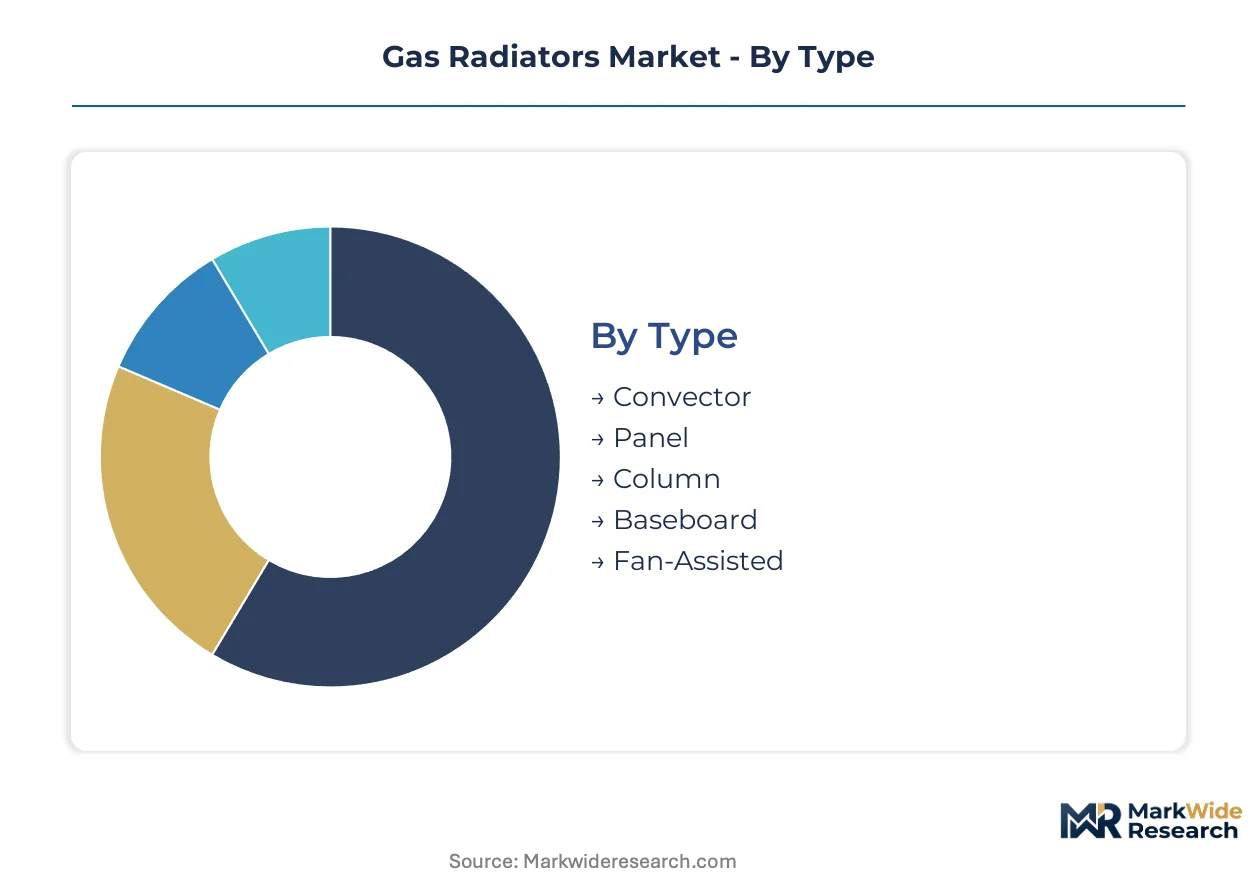
Understanding the market through segmentation reveals distinct demand patterns and competitive landscapes across different product attributes. This detailed breakdown allows manufacturers to tailor product development, marketing strategies, and distribution channels to specific customer needs and operational environments within the gas radiators market.
Type:
Buyer decisions for gas radiator types are heavily influenced by the desired aesthetic integration and functional requirements of the heating solution.
- Convector:These units utilize natural convection to circulate warm air, often featuring rapid heat-up times and robust construction. Demand for convector units remains strong in commercial facilities like workshops and garages, where durability and quick heating are prioritized over visual appeal.
- Panel:Panel radiators offer a sleek, low-profile design that integrates seamlessly into modern interior aesthetics, often used in residential settings for primary heating. Residential upgrades in Western European countries like Italy and Germany heavily favor these design-forward models due to their visual appeal and efficiency.
- Column:Column radiators provide a classic, often decorative appearance, frequently chosen for period properties or as a design statement in contemporary homes.
- Baseboard:These low-profile units are installed along the base of walls, offering discreet heating and even heat distribution, particularly in residential renovations.
- Fan-Assisted:Fan-assisted radiators incorporate a fan to boost heat output and accelerate warm air distribution, suitable for spaces requiring rapid temperature changes.
Volume sits with Convector units for their widespread functional application; growth tilts toward Panel radiators driven by aesthetic preferences in residential construction.
Fuel Type:
The choice of fuel type for gas radiators is primarily dictated by the availability of infrastructure and the operational cost implications for the end-user.
- Natural Gas:This fuel type is the most common for gas radiators, leveraging extensive existing pipeline infrastructure in urban and suburban areas. Markets like Poland and Italy show high adoption due to established natural gas grids, supporting widespread residential heating.
- Biogas:Radiators compatible with biogas offer a pathway for decarbonization, supporting sustainability goals and future-proofing heating systems against fossil fuel phase-outs. Investment in biogas-compatible units is gaining traction in regions with strong environmental policies and agricultural waste streams.
- Propane:Propane-fueled radiators are prevalent in rural areas lacking natural gas infrastructure, providing a versatile off-grid heating solution.
- Butane:Primarily used in portable or smaller heating appliances, butane offers convenience for localized heating needs in specific applications.
- Liquefied Petroleum Gas:LPG, encompassing propane and butane, serves as a flexible fuel source for areas without natural gas access, popular in both residential and commercial applications.
Natural Gas holds the largest market share due to infrastructure dominance; however, Biogas exhibits the steepest expansion trajectory as environmental regulations tighten.
Application:
The application segment reflects how gas radiators are utilized across different building types, influencing product specifications and installation requirements.
- Residential Heating:Gas radiators provide primary or supplementary heating for homes, driven by comfort, energy efficiency, and aesthetic integration. Ongoing renovation cycles in countries with developed gas infrastructure, such as the United States and Germany, sustain demand for modern residential units.
- Commercial Facilities:These applications encompass offices, retail spaces, and workshops, where robust and efficient heating solutions are essential for occupant comfort and operational continuity. Rapid heat-up times and durability are critical features for commercial facilities in colder climates.
- Institutional Buildings:Schools, hospitals, and government buildings utilize gas radiators for reliable, consistent heating across large, multi-zone environments.
- Hospitality Sector:Hotels and restaurants deploy gas radiators to ensure guest comfort and maintain specific ambient temperatures in various spaces.
- Public Amenities:Public spaces like community centers and libraries use gas radiators for general heating, focusing on cost-effectiveness and broad coverage.
Residential Heating accounts for the majority of installations; Commercial Facilities are increasingly investing in advanced convector units for efficiency.
End User:
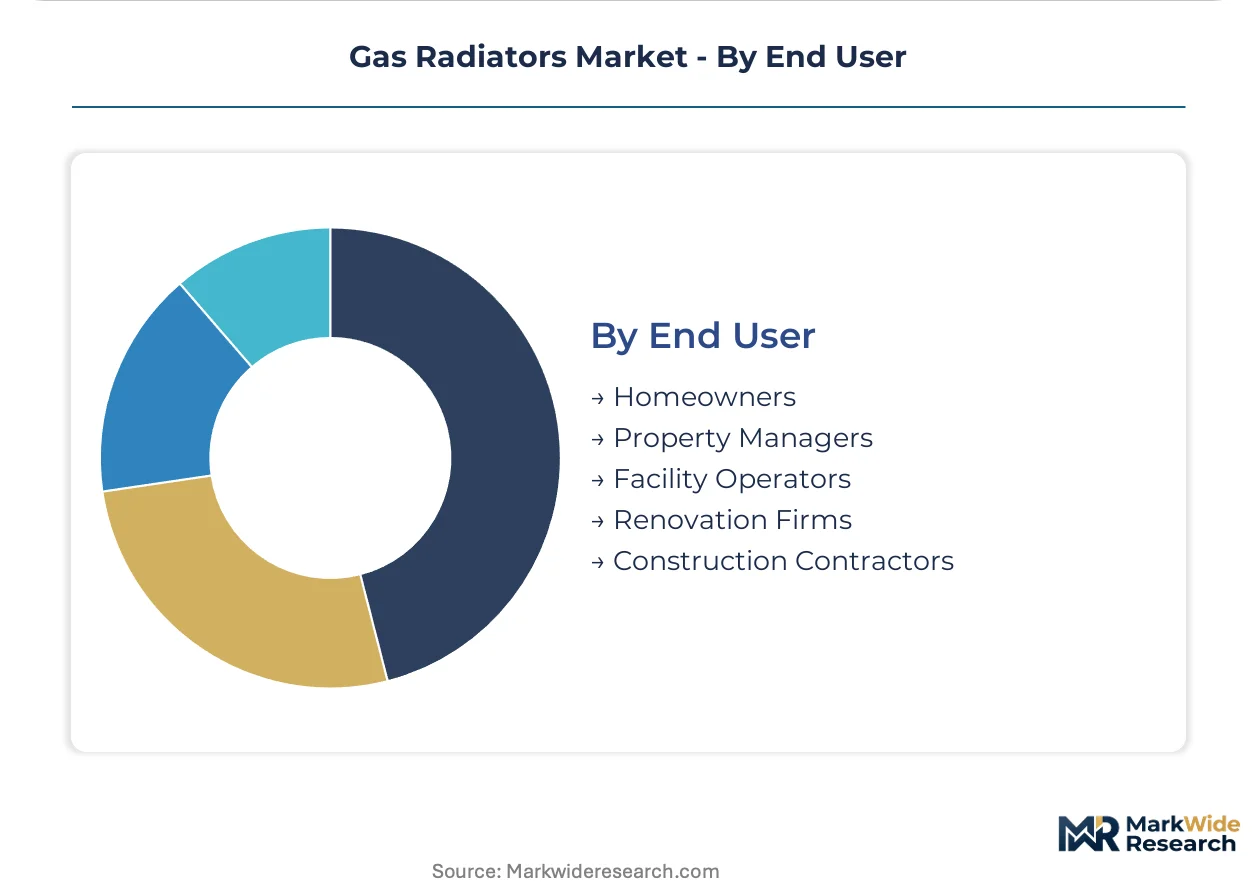
End user segmentation highlights the primary decision-makers and purchasers of gas radiators, influencing sales channels and product features.
- Homeowners:Individual homeowners purchase gas radiators for their residences, often prioritizing aesthetics, energy efficiency, and smart control features. This segment drives demand for premium panel radiators and integrated smart home solutions in renovation projects.
- Construction Contractors:These professionals specify and install gas radiators in new build projects, focusing on compliance with building codes, installation ease, and system integration. Contractors often seek reliable, high-efficiency models that meet Ecodesign Directive standards for new installations.
- Property Managers:Property managers oversee heating systems in rental properties and multi-unit dwellings, valuing durability, low maintenance, and cost-effective operation.
- Facility Operators:Operators of commercial and institutional buildings manage large-scale heating systems, prioritizing robust performance, centralized control, and long-term reliability.
- Renovation Firms:These firms integrate new heating solutions into existing structures, often recommending models that offer improved efficiency and modern design.
Homeowners represent the largest direct purchasing group; Construction Contractors influence significant volume through new developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan, as a central hub for design and residential upgrades, significantly influences gas radiator trends across Europe. The city's architectural focus drives demand for aesthetically integrated panel radiators. This emphasis extends to energy efficiency mandates, shaping product innovation.
Italy
Italian homeowners prioritize sleek panel radiators during residential renovations, seeking both efficiency and modern design. The EU's Ecodesign Directive mandates minimum energy performance levels for these new installations. Northern Italy's manufacturing base, particularly around Brescia, innovates in design-forward, high-efficiency models.
Poland
Poland exhibits sustained demand for modern gas heating units, supported by its extensive gas infrastructure in residential areas. The country's compliance with the EU's Gas Appliances Regulation ensures product safety and market access. Urban centers like Warsaw and Krakow drive volume for standard and advanced convector units.
Germany
German consumers favor efficient gas radiators, particularly design-forward panel models for high-end residential applications. Compliance with the EU's Ecodesign Directive is critical for manufacturers targeting this discerning market. Southern Germany's HVAC manufacturing clusters, such as in Baden-Württemberg, develop advanced heat exchanger technologies.
United States
United States residential heating sustains demand for gas radiators, alongside commercial facilities requiring robust standalone units. ANSI Z21 standards ensure the operational safety of gas-fired appliances across all applications. The Northeast and Midwest regions continue to see significant installations in both new builds and retrofits.
Gas Radiators Market Key Industry Players
Premium-margin players sit above commodity-margin players across product design and aesthetic integration within the gas radiators market. The competitive landscape stratifies between design-focused specialists and large-scale commodity producers. Strategic archetypes include high-end design houses, volume manufacturers, and integrated heating solution providers. Portfolio diversification into smart controls and technology licensing for efficiency improvements are common competitive moves.
On the premium-tier vector, Italkero exemplifies a design-forward approach, focusing on high-end products for specific architectural needs within residential settings and architect-led projects. Stalwart manufacturers like Stelrad, a company known for its broad distribution capabilities, occupy the scale-driven segment, competing primarily on manufacturing volume for standard applications across various markets. Vaillant, leveraging its established brand strength from the boiler market, represents integrated system providers, offering comprehensive heating packages that combine various components for a complete solution. These companies collectively illustrate the diverse strategic positioning across the gas radiators market.
| Leading Market Players |
|---|
| Italkero |
| Robur |
| Stelrad |
| Fondital |
| Vaillant |
| Baxi |
| Kermi GmbH |
| Myson |
| Trane Technologies |
| Others |
Cost & Logistics Intelligence
Specialized manufacturing expertise in Northern Italy and Southern Germany, particularly in design-forward panel radiators, drives labor-cost differentials that feed into premium pricing tiers across the market.
Pricing Analysis
Value-based pricing for gas radiators centers on energy efficiency and aesthetic integration, particularly for premium residential models. The dominant pricing structure is per-unit transactional, with clear differentiation between high-end, design-focused products and commodity-grade units. Price differentiation drivers include compliance with stringent energy efficiency ratings like the EU's Ecodesign Directive and the brand premium associated with established manufacturers. Pricing pressure intensifies within the standard convector segment due to competition on manufacturing scale and broad distribution. Homeowners seeking aesthetic appeal for renovations exhibit lower price sensitivity for panel radiators compared to facility operators purchasing functional convector units for commercial spaces.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks manage the flow of gas radiators from manufacturing sites to end-users across Europe and North America. Geographic supply concentration includes Northern Italy for design-led components and Southern Germany for advanced heat exchanger technologies, alongside broader manufacturing in Poland. Raw material dependencies include steel for radiator bodies, copper for heat exchangers, and specialized electronic controls for smart functionalities. A structural supply chain risk is the volatility of natural gas prices, which impacts overall product attractiveness and consumer demand. Downstream distribution runs through a mix of wholesale HVAC distributors, direct-to-contractor channels, and specialized retail outlets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story, where strict adherence to frameworks like the EU's Ecodesign Directive creates a significant barrier to entry for non-compliant players.
For Market Incumbents: Deepen investment in R&D for alternative fuel compatibility, specifically biogas and hydrogen-natural gas blends, to future-proof product portfolios against the systemic shift towards electrification. Consolidate market share in established regions by leveraging broad distribution networks and brand recognition. Invest in advanced manufacturing processes to reduce per-unit costs for standard applications, countering price erosion from high-volume competitors. Focus on integrating advanced smart controls to maintain a competitive edge against emerging digital solutions.
For New Entrants and Emerging Players: Capture white-space opportunities in commercial retrofit applications, particularly workshops and warehouses, by offering robust, high-efficiency convector units. Target tech-savvy homeowners in urban renovation projects with competitively priced, design-forward panel radiators featuring integrated smart home connectivity. Develop specialized installation and servicing partnerships to overcome installer skill gaps for advanced units. A go-to-market strategy centered on digital channels and specialized HVAC forums can reach niche customer segments effectively.
For Investors and Strategic Acquirers: Re-rating potential sits with companies demonstrating strong intellectual property in smart control technologies and alternative fuel combustion, given the accelerating regulatory push for decarbonization. Long-term viability hinges on a clear pathway to integrate with evolving energy infrastructure and smart home ecosystems. Acquisition targets should include specialized design houses for premium residential products or component manufacturers with expertise in advanced heat exchangers. The signal to watch is the pace of new gas connection bans in key residential markets, indicating a shift in long-term demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate Smart Controls | Enhances user convenience and energy management, driving adoption in premium residential segments. |
| Develop Biogas-Compatible Units | Future-proofs product lines against fossil fuel phase-outs and meets decarbonization mandates. |
| Launch Design-Forward Panel Radiators | Captures demand from homeowners prioritizing aesthetics in modern interior renovations. |
| Expand Commercial Retrofit Channels | Diversifies revenue streams beyond residential new builds, targeting under-served facilities. |
| Invest in Advanced Efficiency Certifications | Ensures market access and compliance with evolving energy performance regulations like the Ecodesign Directive. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this market analysis, complemented by primary interviews. Industry stakeholders included product managers at leading manufacturers, HVAC system installers, procurement managers for commercial facilities, and residential homeowners. Bottom-up and top-down triangulation validated market sizing and growth projections.
Market dimensions were modeled at a granular level across product type, fuel type, application, end-user, and key regional geographies over the projection horizon. The analytical framework integrated historical growth trends with forward-looking assessments of technological advancements and regulatory impacts to derive compound annual growth rates. Key industry-specific forecast inputs included the rate of new gas infrastructure development and the enforcement timelines for energy efficiency mandates.
The model holds under stable regulatory environments and predictable energy price trajectories; deviation in policy shifts towards electrification or significant natural gas supply disruptions would shift market dynamics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Electronic Filters Market
Others
Belt Loader Market
Others
Digital Audio Decoders Market
Others
Allogeneic Human Chondrocyte Market
Others
United States Bean Bags Market
Others
Video Conferencing Hardware Market
Others
Badminton Apparel Market
Others
United States Cigarette Market
Others
Global Hardware As a Service (Haas) Market
Others
Egg Market
Others
Asia Pacific Video Conferencing Hardware Market
Others
North America Micro Market
Others
Latin America Fire Sprinklers Market
Others
Underwater Light Market
Others
Smart Home Service Market
Others
Bamboo Straws Market