
 Digital Tattoos Market | 2026-2036
Digital Tattoos Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Tattoos Market Analysis
Graphene and conductive polymer inks are expanding the functional lifespan of epidermal electronics while cutting unit production costs. MC10 Inc. leverages semiconductor manufacturing techniques to produce stretchable circuit platforms for medical-grade patches. Google sustains development of NFC-integrated dermal interfaces through its advanced technology programs. VivaLNK anchors its position in remote patient monitoring with continuous vital-sign capture systems that clinicians deploy across health networks.
Digital tattoos are ultrathin, skin-conformable electronic devices constructed from biocompatible substrates, conductive traces, and microscale sensors that measure physiological signals or transmit data through near-field communication. These devices typically measure under 100 micrometers in thickness, enabling multi-day wear without irritation while performing functions such as glucose tracking or identity authentication. Healthcare monitoring dominates application value as hospitals integrate biometric sensors into post-surgical recovery protocols, while NFC tattoos are gaining traction in payment solutions where contactless transaction speed matters. Energy harvesting technology remains nascent but holds structural importance for eliminating battery dependence in long-duration wearables.
The FDA regulates digital tattoos as Class II medical devices when they claim diagnostic or therapeutic functions, requiring 510(k) clearance for market entry. ISO 10993 biocompatibility standards govern cytotoxicity and sensitization testing for all skin-contact materials, while FCC certification mandates electromagnetic emissions compliance for RFID and NFC transmission components. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring as payer decisions will determine whether hospital procurement expands beyond pilot programs into standardized clinical workflows.
Market Dynamics
Flexible electronics manufacturing is compressing production timelines for epidermal devices while FDA 510(k) clearance pathways determine which innovations reach hospital procurement systems first.
Growth Catalysts
- ISO 10993 biocompatibility frameworks:Standardized cytotoxicity testing protocols reduce regulatory uncertainty for skin-contact materials, accelerating developer entry into clinical validation phases.
- Remote patient monitoring:Hospital systems in Germany and Japan are embedding digital tattoos into post-surgical recovery protocols, creating institutional demand pull.
- Graphene conductive inks:These materials extend functional lifespan of epidermal sensors while enabling reel-to-reel manufacturing at semiconductor foundries.
Market Restraints
- Silver nanowire supply concentration:Korean and Japanese material suppliers control high-purity conductive substrate production, creating input vulnerability for Western device manufacturers.
- FCC electromagnetic emissions certification:NFC and RFID transmission components face extended testing timelines that delay product launches by 8-14 months.
- Rigid wearable substitution:Smartwatches and continuous glucose monitors retain consumer familiarity and established reimbursement codes that epidermal devices must displace.
Strategic Opportunities
- Energy harvesting convergence:Integration of thermoelectric and piezoelectric generators with flexible substrates eliminates battery dependence for multi-week wearables.
- Payment authentication applications:NFC-integrated dermal interfaces are penetrating transit and retail sectors where contactless transaction speed drives merchant adoption.
- Reimbursement code expansion:CMS remote therapeutic monitoring categories in the United States are creating payment pathways that hospital procurement departments can operationalize.
Industry Challenges
- Stretchable electronics fabrication:Cleanroom technicians with microfluidic patterning expertise remain scarce relative to demand from medical device and consumer electronics sectors.
- Legacy EHR integration:Hospital IT departments face API complexity when connecting biometric tattoo data streams to Epic and Cerner systems without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Tattoos Market |
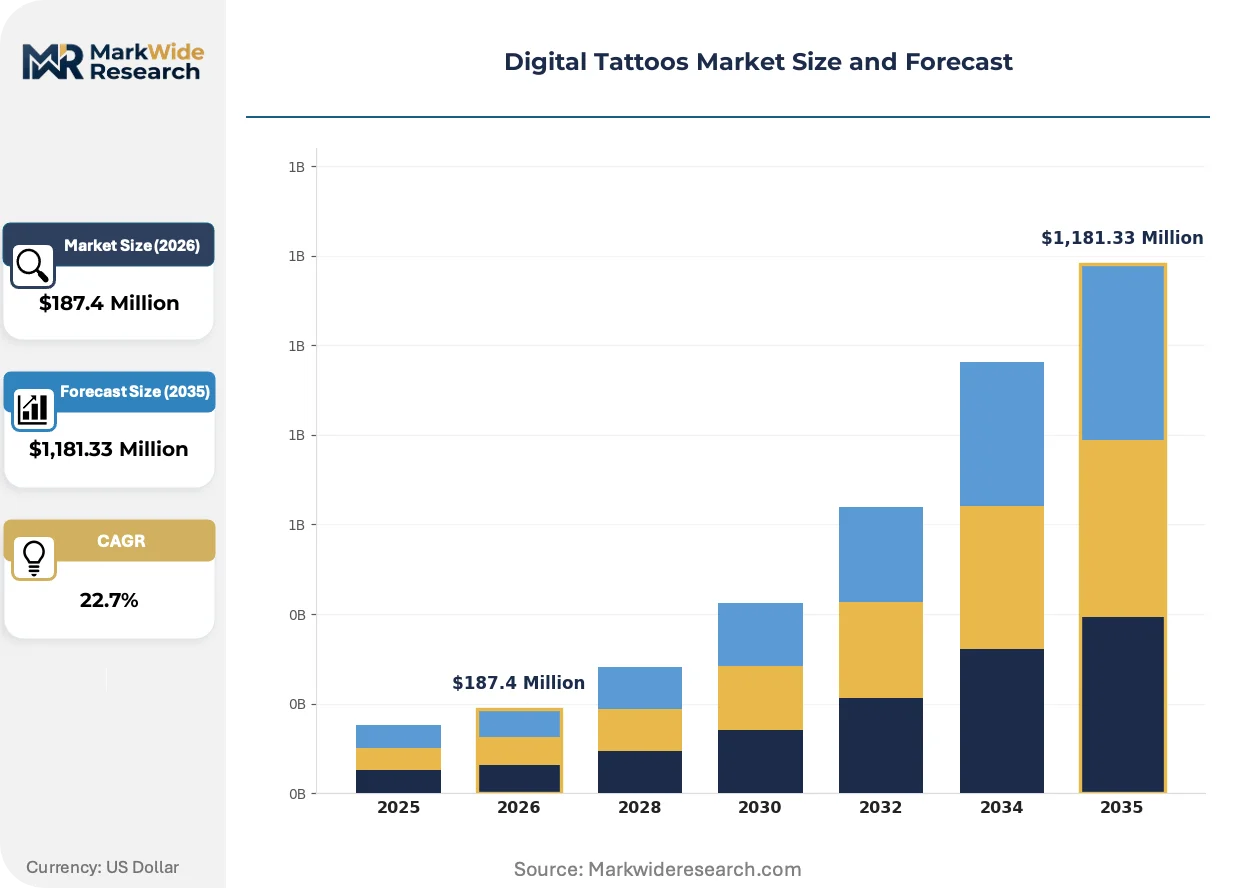
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smart Patches, Biometric Sensors, NFC Tattoos Application: Healthcare Monitoring, Fitness Tracking, Payment Solutions, Identity Verification Technology: RFID, NFC, Biometric Data, Energy Harvesting End User: Hospitals, Sports Organizations, Retailers, Individuals |
| Companies Covered | MC10 Inc., Google, VivaLNK, Chaotic Moon, Prinker, NewDealDesign, Wearable X, Xsensio, Epidermal Electronics Lab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Tattoos Market Emerging Trajectories
Material science breakthroughs and regulatory harmonization efforts are compressing the gap between laboratory demonstration and clinical deployment of epidermal electronics.
Graphene-based conductive traces are unifying mechanical flexibility with electrical performance in ways that silicon substrates cannot match. Hospital procurement teams in the United States and Germany are evaluating these platforms for continuous cardiac monitoring applications. This unification of semiconductor-grade conductivity with skin-conformable form factors is collapsing the traditional separation between diagnostic accuracy and patient comfort.
MDR Article 117 in Europe now mandates notified body involvement for all medical devices incorporating medicinal substances, including drug-releasing digital tattoos. This regulatory expansion is forcing developers to restructure quality management systems earlier in product lifecycles. Wound-care and transdermal delivery segments face the steepest compliance cost increases as they navigate both pharmaceutical and medical device regulatory frameworks simultaneously.
Hospital supply chains are consolidating vendor relationships for remote monitoring hardware around platforms that integrate directly with existing telemetry infrastructure. Integrated delivery networks in Japan and the United States are displacing standalone device purchases with multi-year service agreements that bundle hardware, data analytics, and clinical decision support. This procurement compression favors manufacturers with established health IT partnerships and penalizes point-solution specialists lacking enterprise-scale integration capabilities.
Digital Tattoos Market Segmentation
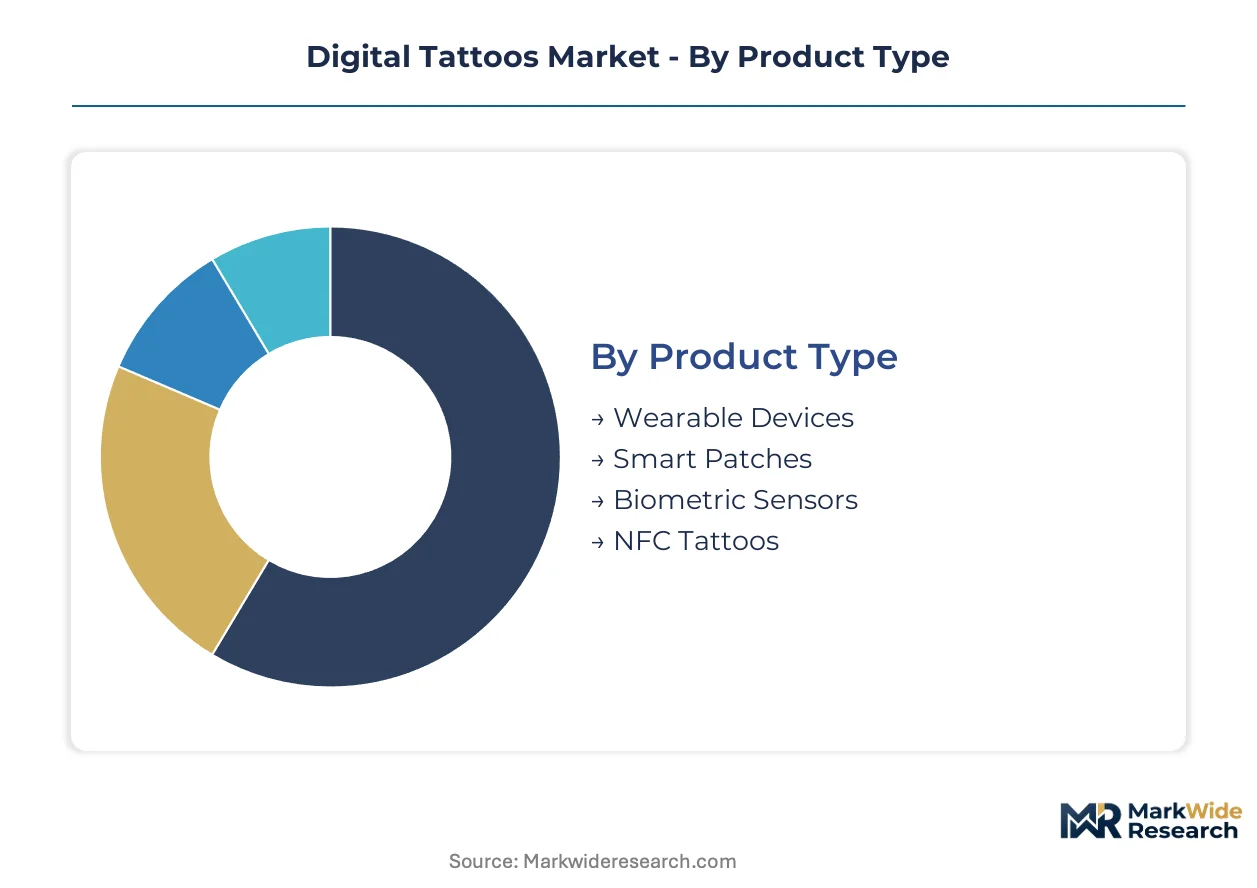
Digital tattoos fragment across four distinct category axes, each reflecting divergent buyer priorities from clinical procurement officers to consumer electronics retailers. Hospital systems prioritize biocompatibility certifications and EHR integration, while payment providers emphasize transaction speed and electromagnetic compliance.
Product Type:
Procurement departments weight total cost of ownership against functional lifespan when selecting epidermal device formats.
- Biometric Sensors:These devices integrate photoplethysmography and impedance spectroscopy for continuous vital-sign capture. Hospital systems in Germany embed these into post-surgical recovery wards where ISO 10993 compliance determines vendor selection.
- Smart Patches:Multi-sensor platforms combine temperature, hydration, and strain gauges on flexible polymer substrates. MC10 Inc. manufactures these through semiconductor foundry partnerships, cutting unit costs while extending wear duration.
- Wearable Devices:General-purpose epidermal electronics with modular sensor configurations serve fitness and wellness applications.
- NFC Tattoos:Near-field communication interfaces enable contactless data exchange for identity and payment authentication.
Volume sits with Smart Patches; growth tilts toward Biometric Sensors.
Application:
End-use economics separate institutional buyers with multi-year service contracts from individual consumers seeking disposable solutions.
- Healthcare Monitoring:Continuous glucose, cardiac, and hydration tracking drives hospital procurement budgets. VivaLNK deploys these across United States health networks where CMS reimbursement codes now cover remote therapeutic monitoring.
- Payment Solutions:NFC-integrated dermal interfaces accelerate transit and retail transactions where millisecond latency matters. Google advances this segment through advanced technology programs targeting merchant adoption.
- Fitness Tracking:Athletic performance metrics and recovery optimization for sports organizations and individual consumers.
- Identity Verification:Secure authentication for access control and personal identification applications.
Revenue concentrates in Healthcare Monitoring; Payment Solutions are expanding most quickly.
Technology:
Transmission protocol selection constrains both electromagnetic compliance pathways and integration complexity with existing infrastructure.
- NFC:Short-range communication at 13.56 MHz enables secure payment and identity transactions. FCC certification timelines extend product launches by 8-14 months, favoring established players with regulatory expertise.
- Biometric Data:Signal processing algorithms extract physiological parameters from skin-contact sensors. Graphene conductive inks from Korean and Japanese suppliers enhance signal fidelity while enabling reel-to-reel manufacturing.
- RFID:Passive identification tags for inventory and access control without power requirements.
- Energy Harvesting:Thermoelectric and piezoelectric generators eliminate battery dependence for extended wear duration.
Deployment volume favors NFC; Energy Harvesting holds the steepest expansion trajectory.
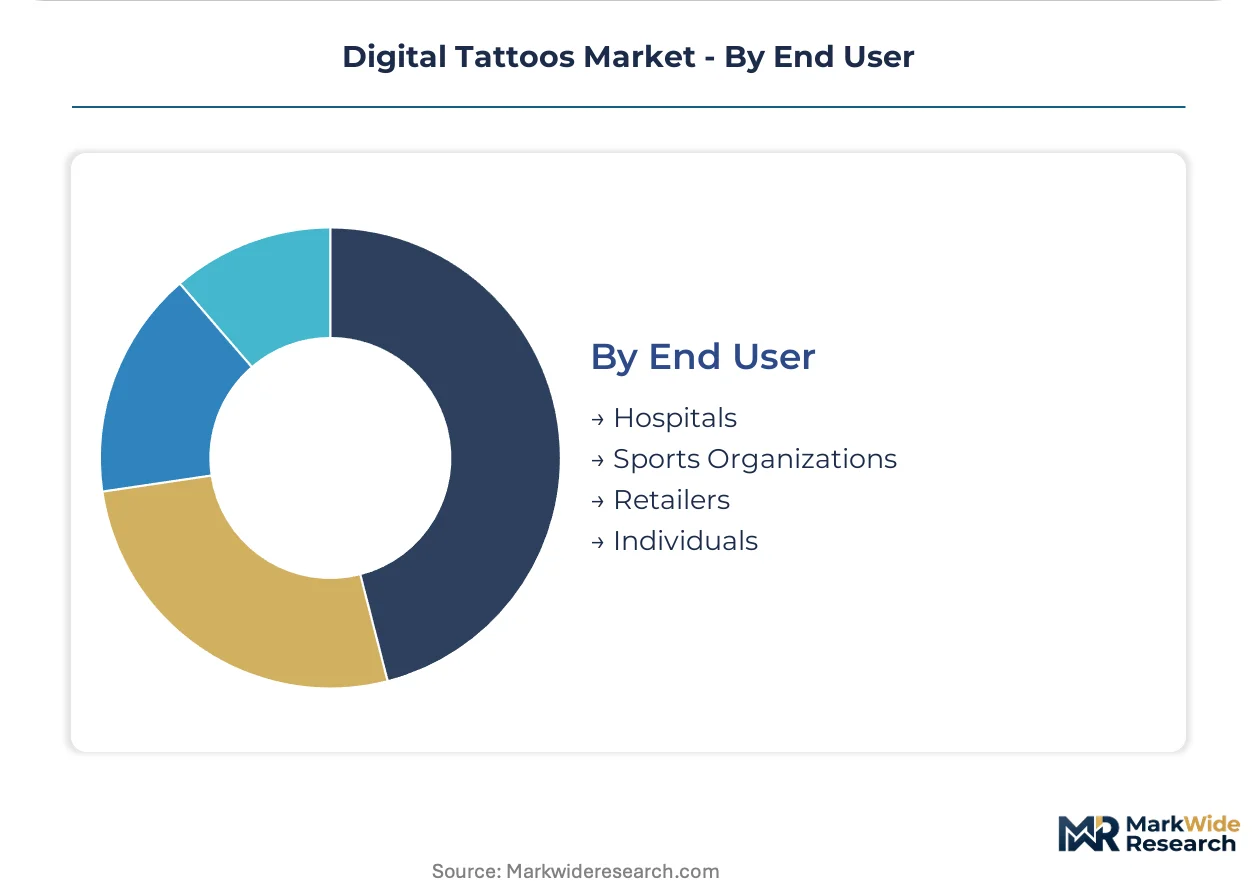
End User:
Customer scale determines whether vendors pursue enterprise integration partnerships or direct-to-consumer distribution channels.
- Hospitals:Integrated delivery networks in Japan and the United States consolidate procurement around platforms with direct Epic and Cerner connectivity. MDR Article 117 in Europe adds notified body requirements for drug-releasing variants.
- Sports Organizations:Professional teams and leagues adopt hydration and strain monitoring for athlete performance optimization.
- Retailers:Payment terminal networks and loyalty program operators pilot NFC tattoo acceptance infrastructure.
- Individuals:Consumer wellness applications and experimental early adopters drive niche demand outside institutional channels.
Procurement volume aggregates at Hospitals; Sports Organizations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement budgets for remote patient monitoring concentrate in the United States, Germany, and Japan where reimbursement pathways and consumer electronics ecosystems intersect most favorably.
United States
Integrated delivery networks in California and Texas are embedding biometric sensors into post-surgical recovery protocols at scale. FDA 510(k) clearance pathways determine which epidermal device innovations reach hospital procurement systems first, with CMS remote therapeutic monitoring categories now creating operational payment pathways that procurement departments can execute against. The Boston-Cambridge corridor anchors semiconductor manufacturing partnerships for stretchable circuit platforms.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia are standardizing digital tattoo deployments for continuous cardiac monitoring applications. MDR Article 117 mandates notified body involvement for drug-releasing variants, forcing developers to restructure quality management systems earlier in product lifecycles. The Stuttgart region concentrates flexible electronics manufacturing expertise alongside automotive sensor supply chains.
Japan
Metropolitan Tokyo and Osaka-based health networks are consolidating vendor relationships around platforms with direct telemetry infrastructure integration. METI funding programs support energy harvesting research for battery-eliminating wearables. The Kansai industrial corridor hosts reel-to-reel manufacturing partnerships for graphene conductive inks.
South Korea
Seoul Capital Area electronics conglomerates control high-purity silver nanowire substrate production, creating supply leverage for Western device manufacturers seeking input security. MFDS biocompatibility standards align with ISO 10993 frameworks while adding domestic testing requirements. The Suwon-Gwangmyeong cluster specializes in NFC component fabrication for payment authentication applications.
Switzerland
Zurich and Basel-based pharmaceutical device developers are navigating dual regulatory frameworks for drug-releasing epidermal platforms. Swissmedic quality standards exceed baseline EU requirements, creating certification premiums that filter market entrants. The Lake Geneva region concentrates microfluidic patterning expertise for stretchable electronics fabrication.
Digital Tattoos Market Vendor Landscape
Strategic partnerships dominate the current landscape as device developers seek health IT integration capabilities and semiconductor manufacturing scale. The vendor base fragments across medical-grade specialists, consumer electronics entrants, and materials science platforms, with consolidation pressure intensifying around hospital procurement consolidation. Three archetypes define positioning: FDA-cleared medical device platforms, NFC-integrated consumer authentication systems, and flexible electronics foundry services. M&A activity targets health IT connectivity assets, while capacity expansion concentrates in semiconductor foundry partnerships for reel-to-reel manufacturing.
Within the medical-grade platform tier, MC10 Inc. and VivaLNK exemplify archetypes of FDA-cleared device developers with hospital network penetration. Google occupies a position on the consumer authentication vector through advanced technology program investments. These three anchors illustrate the divergence between clinical procurement requirements and merchant-facing payment infrastructure development.
| Leading Market Players |
|---|
| MC10 Inc. |
| VivaLNK |
| Chaotic Moon |
| Prinker |
| NewDealDesign |
| Wearable X |
| Xsensio |
| Epidermal Electronics Lab |
| Others |
Supply Flow & Price Mechanics
Venture-backed flexible electronics specialists with semiconductor foundry partnerships anchor supply-side discipline while FDA 510(k) clearance timelines create pricing premiums for certified platforms. Hospital procurement departments in the United States and Germany absorb these premiums because ISO 10993 biocompatibility testing eliminates lower-cost uncertified alternatives from vendor pools.
Pricing Analysis
Volume concentrates in disposable smart patches where reel-to-reel manufacturing drives unit economics toward commodity levels; margins persist only in multi-sensor biometric platforms with embedded clinical decision support. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared hospital-grade devices from fitness-oriented consumer variants. Pricing pressure stems from smartwatch substitution in wellness applications where reimbursement codes favor established wearable form factors. Hospital systems show lowest price sensitivity due to bundled service contracts, while individual consumers in fitness segments migrate to lowest-cost disposable options.
Supply Chain Analysis
Single-source vulnerability sits with Korean and Japanese suppliers of high-purity silver nanowire substrates that Western device manufacturers cannot easily duplicate. Graphene conductive inks and flexible polymer substrates draw from South Korea, Japan, and the United States in roughly equal measure. Supply chain risk centers on tariff exposure for semiconductor-grade materials crossing Pacific trade routes. Distribution runs through integrated delivery networks that consolidate multi-year service agreements around platforms with direct Epic and Cerner connectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA 510(k) clearance pathways and ISO 10993 biocompatibility frameworks erect barrier-to-entry moats that filter out undercapitalized entrants. Hospital procurement consolidation favors players with established regulatory dossiers and health IT integration capabilities.
For Market Incumbents: Anchor hospital network relationships through multi-year remote therapeutic monitoring service contracts that bundle hardware, data analytics, and clinical decision support. Defend against smartwatch substitution by deepening EHR integration capabilities that rigid wearables cannot match. Prioritize backward integration into graphene ink production to reduce exposure to Korean and Japanese material suppliers. For New Entrants and Emerging Players: Capture white-space in payment authentication applications where NFC-integrated dermal interfaces face lower regulatory barriers than medical-grade platforms. Target transit and retail merchant networks in Japan and Germany where contactless transaction speed drives infrastructure investment. Pursue foundry partnerships with established semiconductor manufacturers rather than building captive fabrication capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor FDA-cleared device developers with existing hospital procurement relationships and incomplete health IT integration roadmaps. Long-term viability hinges on reimbursement code expansion that operationalizes remote therapeutic monitoring across United States integrated delivery networks. Watch CMS category decisions as the inflection signal determining whether hospital procurement expands beyond pilot programs.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathways determine hospital procurement eligibility and pricing tier placement. |
| Hospital System Partnership | Epic and Cerner integration capabilities filter vendor selection at integrated delivery networks. |
| Reimbursement Strategy | CMS remote therapeutic monitoring categories operationalize payment for clinical deployments. |
| Semiconductor Foundry Partnership | Reel-to-reel manufacturing partnerships compress unit costs for smart patch production. |
| Energy Harvesting R&D | Thermoelectric and piezoelectric integration eliminates battery dependence for multi-week wearables. |
Methodological Framework
SEC filings, FDA 510(k) clearance databases, and hospital procurement contract records formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and flexible electronics manufacturing executives validated demand assumptions and pricing dynamics. Bottom-up unit economics modeling triangulated against top-down hospital budget allocation analysis across the United States, Germany, and Japan.
Historical trendline analysis of FDA clearance timelines, reimbursement code expansions, and semiconductor foundry capacity utilization informed projection mechanics across the analysis window. Segmentation modeling incorporated product type, application, transmission protocol, and end-user archetype dimensions. CAGR derivation rested on patient monitoring penetration rates in post-surgical recovery wards and NFC payment terminal deployment trajectories in transit networks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA regulatory shifts, CMS reimbursement decisions, and silver nanowire supply disruptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Car Wax Market
Others
Surface Green Mining Market
Others
Latin America Fire Sprinklers Market
Others
Allogeneic T Cell Therapies Market
Others
Global Smart Kitchen Market
Others
Global Augmented Reality in Retail Market
Others
Bio-Based Leather Market
Others
Europe Legal Services Market
Others
Europe Electric Forklift Market
Others
Hotel Wardrobe Market
Others
Motor Grader Market
Others
Heat Treatment Furnace Market
Others
One-Way Degassing Valve Market
Others
Nutricosmetics Market
Others
Cremation Furnace Market
Others
Global Pregnancy Tracker Apps Market