
 Global Hardware As a Service (Haas) Market | 2026-2036
Global Hardware As a Service (Haas) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hardware As a Service (Haas) Market Foresight
Mid-market enterprises is bifurcating from large-cap buyers as the dominant growth archetype in hardware subscription uptake. Dell Technologies Inc. leverages direct-to-business configuration tools to sustain recurring revenue attachment rates. Hewlett Packard Enterprise Company anchors its edge-to-cloud narrative through as-a-service consumption models for servers and storage.
Hardware As a Service denotes a contractual arrangement where physical IT assets—typically servers with defined compute thresholds, networking equipment meeting SLA-bound latency parameters, and storage devices with specified IOPS ratings—are provisioned, maintained, and refreshed by vendors in exchange for periodic fees rather than outright purchase. The model shifts balance-sheet liability to vendors while guaranteeing performance benchmarks and end-of-life disposition. Servers and networking equipment command the largest installed base under subscription terms, though IoT devices represent the fastest-expanding product category as industrial sensor networks proliferate. Cloud-based and hybrid deployment modes capture disproportionate margin pools relative to on-premises legacy arrangements due to bundled management overhead and multi-tenant efficiencies.
The EU AI Act, GDPR data-localization mandates, and SEC climate-disclosure rules collectively elevate hardware lifecycle accountability and auditability requirements for vendors and subscribers alike. FDA cybersecurity guidance for connected medical devices and FCC equipment authorization standards further constrain which hardware configurations qualify for regulated sector deployments. Stakeholders must weigh residual-value modeling against regulatory refresh obligations as subscription terms lengthen and circular-economy compliance tightens.
Market Dynamics
Mid-market enterprises are migrating from capital expenditure models to operational expenditure frameworks for IT infrastructure, compressing refresh cycles and forcing vendors to restructure pricing around utilization metrics rather than depreciation schedules.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises face accelerated hardware refresh obligations to meet algorithmic accountability and data sovereignty requirements, expanding subscription demand for auditable, compliant infrastructure.
- Industrial IoT sensor networks:Manufacturing facilities across Germany, Japan, and the United States are deploying connected device fleets that require continuous hardware refresh and remote management under subscription terms.
- Circular economy frameworks:Germany's mature e-waste directives and Japan's resource recycling laws create regulatory tailwinds that favor vendor-managed lifecycle disposition over enterprise-owned disposal.
Market Restraints
- Residual value volatility:Semiconductor component price swings and secondary market demand uncertainty compress vendor margins on returned server and storage hardware.
- Supply concentration in East Asian fabrication:Taiwan and South Korea dominate advanced chip manufacturing, exposing HaaS providers to geopolitical disruption and capacity allocation constraints.
- FCC equipment authorization timelines:Networking hardware deployments face extended certification delays that lengthen time-to-revenue for subscription rollouts in regulated sectors.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives are attracting server and networking assembly capacity, creating localized subscription provisioning for South Asian mid-market demand.
- Edge-to-cloud workload convergence:Hybrid deployment models that combine on-premises edge nodes with centralized cloud orchestration represent an underpenetrated configuration tier with premium pricing potential.
- SEC climate-disclosure rules:Scope 3 emissions reporting requirements are pushing Fortune 500 firms toward vendor-managed hardware with certified circular-economy disposition chains.
Industry Challenges
- Embedded firmware security expertise:HaaS providers face acute shortages of engineers capable of maintaining SBOM documentation and vulnerability patching across heterogeneous device fleets.
- Legacy ERP integration complexity:Enterprise subscribers require API bridges between vendor management platforms and incumbent SAP or Oracle systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hardware As a Service (Haas) Market |
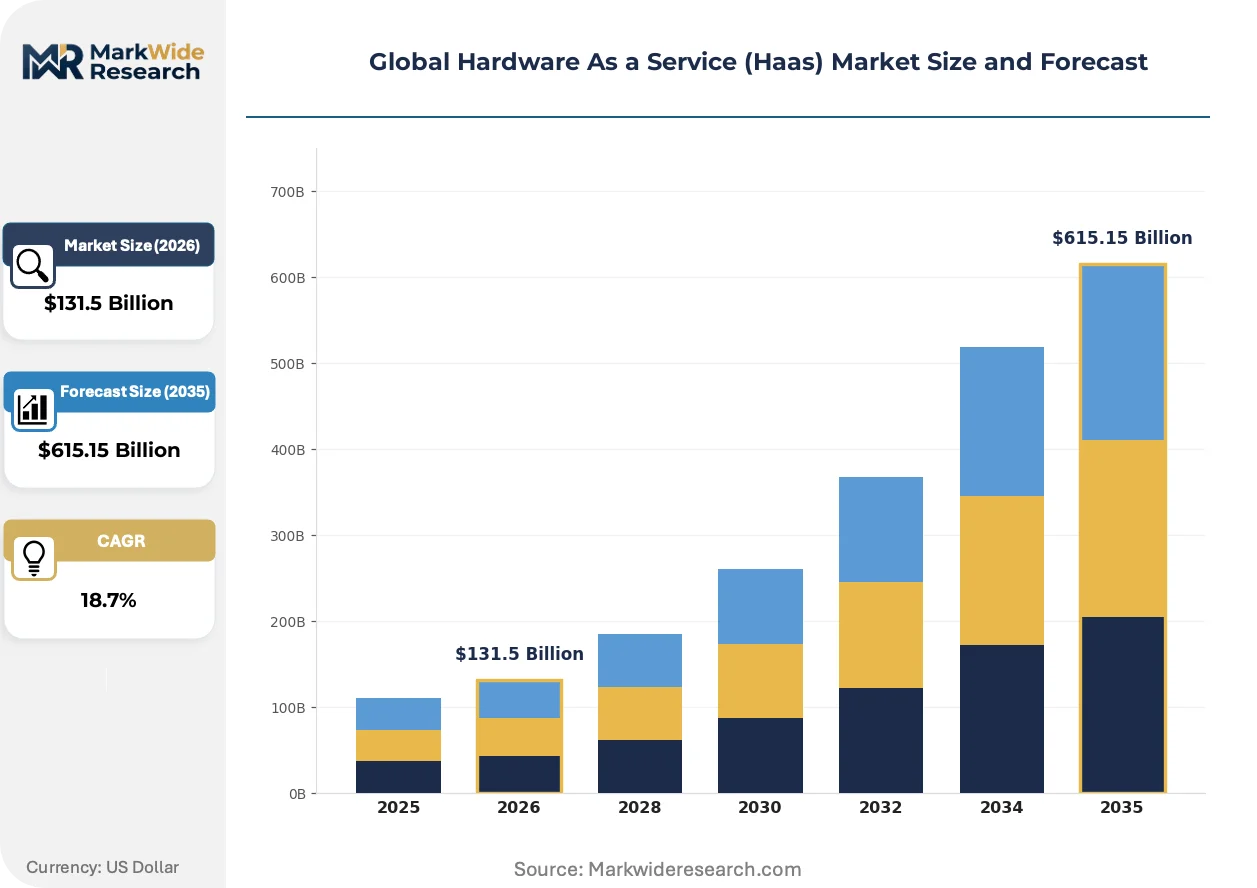
| Market Size in 2026 | $131.5 Billion |
| Market Size in 2035 | $615.15 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Servers, Networking Equipment, Storage Devices, Computer Peripherals, IoT Devices Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Telecommunications, Government Agencies, Educational Institutions, Manufacturing Firms, Financial Services Service Model: Managed Services, Pay-As-You-Go, Subscription-Based, Custom Contract |
| Companies Covered | Hewlett Packard Enterprise Company, Dell Technologies Inc., HP Inc., Cisco Systems, Inc., Lenovo Group Limited, Microsoft Corporation, Amazon Web Services, IBM Corporation, Fujitsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hardware As a Service (Haas) Market Shifts & Advancements
Subscription-based infrastructure provisioning is fragmenting along deployment-mode lines, with hybrid configurations capturing disproportionate margin pools through bundled orchestration services that pure on-premises or cloud-native alternatives cannot replicate.
Composable disaggregated infrastructure is bifurcating the server market between fixed-configuration rack units and fluid resource pools that allocate compute, memory, and storage independently via software-defined fabrics. Financial services and healthcare providers in Singapore and Switzerland are adopting these architectures fastest, compressing traditional three-year refresh cycles into continuous, non-disruptive upgrades that eliminate forklift migrations.
The EU AI Act's risk-based classification system is forcing hardware vendors to pre-certify server configurations for high-risk AI training workloads before subscription deployment. German automotive manufacturers and French pharmaceutical firms now require documented hardware audit trails that trace component provenance through installation, operation, and end-of-life recovery, shifting competitive advantage toward vendors with embedded compliance tooling.
Consumption-based contracting is displacing fixed-fee subscriptions among cloud-native enterprises that demand granular billing tied to actual CPU cycles, storage IOPS, and network throughput. This metering precision is most advanced among SaaS providers in the San Francisco Bay Area and Bangalore, who negotiate rate cards that penalize underutilization and reward burst capacity elasticity through dynamic pricing algorithms.
Global Hardware As a Service (Haas) Market Segmentation
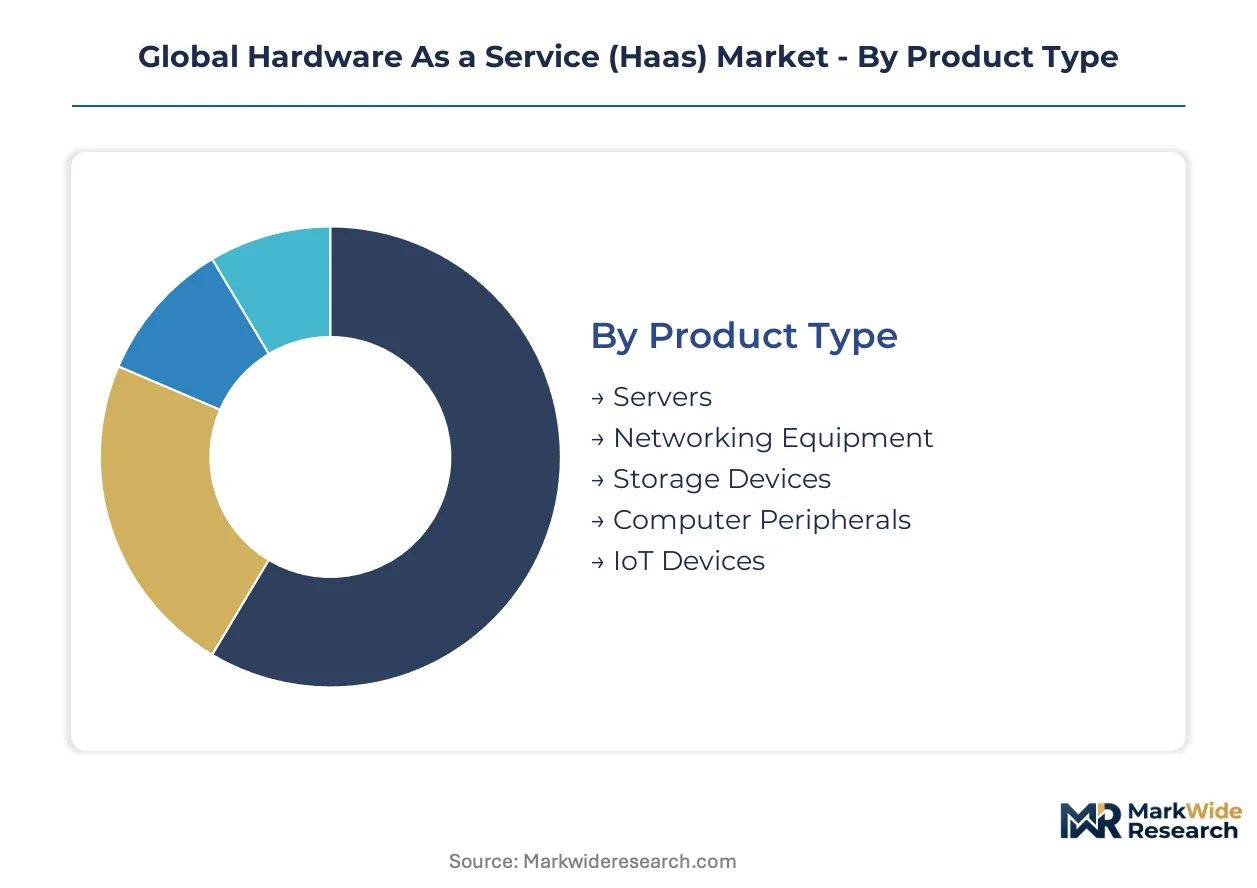
HaaS segmentation reflects divergent procurement logics across infrastructure layers. Product mix and deployment mode determine vendor margin structures, while end-user verticals and service models dictate contract duration and refresh velocity.
Product Type:
Servers and networking equipment dominate domestic provisioning in Germany, Japan, and the United States, while IoT device subscriptions increasingly serve export-oriented manufacturing networks.
- Servers:Compute units with defined thermal design power and memory bandwidth specifications anchor enterprise data center refresh cycles. German automotive manufacturers and US financial services firms drive subscription uptake for high-availability rack configurations under EU AI Act audit requirements.
- Networking Equipment:SLA-bound switches and routers with guaranteed latency parameters concentrate in telecommunications and cloud provider deployments. FCC equipment authorization timelines constrain US rollout velocity, compressing vendor working capital cycles.
- Storage Devices:IOPS-rated arrays for structured and unstructured data workloads.
- Computer Peripherals:Endpoint accessories under centralized fleet management in educational and government sectors.
- IoT Devices:Industrial sensor networks expanding fastest across Japanese and German factory automation deployments.
Servers hold the largest share; momentum sits with IoT devices.
Deployment:
Hybrid configurations command premium pricing through bundled orchestration overhead, while pure cloud-based deployments scale fastest among SaaS-native enterprises.
- Hybrid:Combined on-premises edge nodes with centralized cloud orchestration capture disproportionate margin pools. Singaporean financial services and Swiss healthcare providers adopt these architectures fastest, eliminating forklift migrations through continuous upgrades.
- Cloud-Based:Fully vendor-hosted infrastructure with multi-tenant efficiencies. Bangalore and San Francisco Bay Area SaaS providers negotiate granular CPU cycle and IOPS billing, rewarding burst elasticity through dynamic rate cards.
- On-Premises:Legacy single-tenant arrangements with higher management overhead.
- Edge Computing:Distributed processing nodes for latency-sensitive workloads in manufacturing and telecommunications.
Hybrid deployments generate the highest margins; cloud-based configurations are climbing the fastest.
End User:
Financial services and telecommunications concentrate subscription value in mature markets, while manufacturing firms drive volume expansion across industrializing economies.
- Financial Services:Risk-averse institutions in Singapore and Switzerland demand composable disaggregated infrastructure with documented hardware audit trails. SEC climate-disclosure rules push Fortune 500 firms toward vendor-managed circular-economy disposition chains.
- Telecommunications:Network operators require continuous refresh of routing and switching hardware under stringent uptime SLAs. Indian mid-market demand attracts localized assembly capacity through PLI scheme incentives.
- Government Agencies:Public sector procurement with extended compliance and security certification cycles.
- Educational Institutions:Budget-constrained fleets prioritizing total cost of ownership over performance density.
- Manufacturing Firms:Industrial IoT sensor network deployments across German and Japanese facilities.
Financial services commands premium contract values; manufacturing firms show the steepest expansion trajectory.
Service Model:
Subscription-based contracting dominates stable enterprise relationships, while consumption-based models penetrate cloud-native segments with variable workload patterns.
- Subscription-Based:Fixed periodic fees with guaranteed refresh cycles and end-of-life disposition. German automotive and French pharmaceutical firms require documented component provenance through installation, operation, and recovery phases under EU AI Act mandates.
- Managed Services:Comprehensive vendor oversight including firmware maintenance, SBOM documentation, and vulnerability patching. Acute engineer shortages constrain provider scaling across heterogeneous device fleets.
- Pay-As-You-Go:Granular billing tied to actual utilization metrics.
- Custom Contract:Bespoke terms for regulated sector deployments with specialized compliance requirements.
Subscription-based models anchor recurring revenue; managed services are gaining share fastest through compliance bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision server configurations to automotive manufacturers across France and Italy, establishing the Rhine-Main corridor as Europe's primary HaaS provisioning hub for regulated AI workloads.
United States
Financial services firms in Manhattan and cloud-native enterprises across the San Francisco Bay Area drive consumption-based contracting with granular CPU cycle billing. SEC climate-disclosure rules push Fortune 500 companies toward vendor-managed circular-economy disposition chains. Dallas-Fort Worth hosts expanding edge-to-cloud orchestration facilities serving mid-market manufacturing clients.
Germany
Automotive manufacturers in Stuttgart and pharmaceutical firms in Frankfurt require documented hardware audit trails under EU AI Act mandates. The country's e-waste directives create regulatory tailwinds favoring vendor-managed lifecycle disposition. Munich anchors server subscription provisioning for high-risk AI training workloads across the DACH region.
Japan
Factory automation networks in Nagoya and Osaka deploy industrial IoT sensor fleets requiring continuous hardware refresh under subscription terms. METI resource recycling laws mandate certified end-of-life recovery chains. Tokyo hosts the region's largest concentration of edge computing nodes for latency-sensitive manufacturing workloads.
India
Telecommunications operators in Mumbai and Bangalore seek localized server assembly capacity under the PLI scheme for electronics manufacturing. TRAI spectrum allocation policies accelerate 5G networking hardware deployments. Hyderabad emerges as a provisioning hub for South Asian mid-market subscription demand.
Singapore
Wealth management institutions and healthcare providers adopt composable disaggregated infrastructure with documented component provenance. The Monetary Authority of Singapore's digital banking framework elevates hardware auditability requirements. The city-state's data center cluster serves as Asia-Pacific orchestration gateway for hybrid edge-to-cloud configurations.
Global Hardware As a Service (Haas) Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with captive server manufacturing and cloud orchestration platforms. Market structure concentrates around three tiers: premium vendors with direct-to-business configuration tools, scale operators leveraging multi-tenant efficiencies, and regional assemblers capitalizing on localized PLI incentives. Strategic archetypes include edge-to-cloud narrators, consumption-based pricing innovators, and compliance-bundled lifecycle managers. Dominant competitive moves encompass backward integration into semiconductor sourcing and strategic partnerships with industrial IoT platform providers.
Within the diversified technology tier, Hewlett Packard Enterprise Company and Dell Technologies Inc. exemplify archetypes anchored in enterprise server provisioning with recurring revenue frameworks. HP Inc. occupies a position representing endpoint fleet management specialization. These entities sit within a competitive set where direct configuration tooling and compliance-embedded service bundling differentiate positioning across German automotive, US financial services, and Japanese manufacturing verticals.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise Company |
| Dell Technologies Inc. |
| HP Inc. |
| Cisco Systems, Inc. |
| Lenovo Group Limited |
| Microsoft Corporation |
| Amazon Web Services |
| IBM Corporation |
| Fujitsu Limited |
| Others |
Supply & Pricing Matrix
FCC equipment authorization standards and EU AI Act certification tiers simultaneously gate supply qualification and stratify price levels across subscription contracts. Vendors must pre-certify server configurations for regulated sector deployments, creating pricing premiums for audit-ready hardware that generic configurations cannot command.
Pricing Analysis
Current-generation servers with EU AI Act pre-certification command substantial premiums over prior-generation units and next-generation prototypes still undergoing validation. Three-tier pricing structure across premium certified, standard compliant, and economy non-audited levels separates German automotive manufacturers from US mid-market SaaS providers from budget-constrained educational fleets. Price differentiation hinges on embedded compliance tooling and documented component provenance. Cost compression in economy tiers is intensifying because Indian PLI scheme incentives attract localized assembly capacity. Educational institutions exhibit highest price sensitivity; Singaporean financial services firms show least.
Supply Chain Analysis
Taiwan and South Korea anchor advanced chip fabrication for HaaS server and networking hardware, while China and Vietnam concentrate PCB assembly and component integration. Advanced node semiconductors, high-bandwidth memory modules, and precision thermal management components feed from East Asian fabrication clusters. Single-source vulnerability around Taiwan Strait capacity allocation exposes providers to geopolitical disruption. Distribution runs through vendor-direct configuration portals for enterprise accounts and regional systems integrators for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: EU AI Act audit requirements and SEC climate-disclosure rules create switching costs that lock subscribers into vendor-managed lifecycle relationships.
For Market Incumbents: Fortify compliance-embedded service bundling by deepening backward integration into semiconductor sourcing and acquiring industrial IoT platform capabilities. Dell Technologies and HPE face margin pressure from consumption-based pricing innovators in Bangalore and San Francisco Bay Area SaaS segments. Certification investment in FDA cybersecurity guidance for medical device deployments creates channel control leverage. For New Entrants and Emerging Players: Lead with edge-to-cloud hybrid orchestration for South Asian mid-market telecommunications operators underserved by premium vendor direct sales. India's PLI scheme electronics manufacturing incentives create localized provisioning white space. Target consumption-based metering with granular CPU cycle billing as go-to-market angle against fixed-fee incumbents. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward vendors with embedded SBOM documentation and vulnerability patching capabilities. Long-term viability centers on circular-economy compliance infrastructure with certified end-of-life recovery chains. Acquire managed services specialists with firmware security expertise. Watch India's PLI scheme capacity buildout as inflection signal for regional pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Taiwan and South Korea fabrication exposure demands captive supply arrangements for margin defense. |
| EU AI Act Pre-Certification Investment | German automotive and French pharmaceutical procurement now requires documented hardware audit trails. |
| Industrial IoT Platform Partnership | Japanese and German factory automation networks drive fastest-expanding device subscription category. |
| Consumption-Based Metering Development | San Francisco Bay Area SaaS providers negotiate granular CPU cycle billing with burst elasticity rewards. |
| India PLI Scheme Localization | Hyderabad and Mumbai telecommunications demand attracts server assembly capacity for South Asian provisioning. |
Research Methodology
Initial hypotheses were tested against primary input from HaaS vendor sales executives, enterprise IT procurement officers, data center operations managers, and industrial IoT platform engineers and refined through secondary validation against SEC 10-K filings, hyperscaler capex disclosures, EU regulatory filings, and customs trade data. Bottom-up subscription contract analysis triangulated with top-down market sizing across deployment modes.
Variance decomposition across product type, deployment architecture, end-user vertical, and geographic regulatory cluster shaped analytical framework throughout the projection horizon. CAGRs derived from fitted growth curves applied to installed base refresh velocity and new subscription origination rates. Semiconductor capacity allocation constraints and circular-economy compliance cost trajectories fed industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU AI Act implementation, SEC climate-disclosure enforcement, and India's PLI scheme incentive structures; material policy shifts would require re-modeling subscription demand elasticity and vendor margin structures. Recalibration cycles align with material shifts in chip fabrication capacity allocation and compliance regime enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Stand-Up Pouch Valves Market
Others
Digital Transformation of Maritime Freight Market
Others
North America 3D Printing Construction Market
Others
Liquid Density Meters Market
Others
Infant Positioning Aids Market
Others
Tripod Market
Others
Global Luxury High End Furniture Market
Others
5G Enabled Healthcare Services Market
Others
Cashew Kernel Market
Others
Global Snow Sports Apparel Market
Others
Smart Home Service Market
Others
ASEAN Agricultural Logistics Market
Others
Air Separation Unit Market
Others
Embedded Computer Market
Others
5G Tester Market
Others
Global Learning Analytics Market