
 Magnetic Stripe Readers Market | 2026-2036
Magnetic Stripe Readers Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Stripe Readers Market Foresight
Reseller and distributor networks is reconfiguring how magnetic stripe readers reach mid-market merchants across fragmented retail landscapes. MagTek leverages direct OEM relationships to sustain its position in encryption-enabled reader modules. ID Tech specializes in compact USB-connected designs that anchor its presence in point-of-sale integration projects. Verifone competes through embedded reader solutions that extend its terminal ecosystem control into hospitality and transit verticals.
Magnetic stripe readers decode data encoded in iron oxide particles arranged on polyester-based stripe substrates using electromagnetic induction principles, with coercivity ratings of 300 Oe (low) or 2750 Oe (high) determining read head compatibility and swipe reliability. These devices translate analog magnetic flux reversals into digital track data for transaction authentication, access control, and identity verification workflows across commercial and institutional settings. Stationary readers dominate financial institution deployments where countertop permanence and high-duty cycles justify fixed installations, while handheld and Bluetooth-enabled variants capture growth in mobile point-of-sale and field service applications where tethered connectivity limits operational flexibility. NFC-capable hybrid units concentrate margin pools as merchants seek consolidated hardware that bridges legacy magnetic acceptance with contactless payment rails.
PCI DSS requirements enforced by the PCI Security Standards Council mandate encrypted data transmission from reader to processor, shaping product development roadmaps for all hardware vendors serving card-present environments. FCC Part 15 regulations in the United States govern electromagnetic emissions from Bluetooth and NFC-integrated reader models, while EU REACH and RoHS directives constrain substance composition in devices distributed across European member states. Stakeholders must monitor EMV migration timelines and contactless adoption curves in key economies to calibrate production mix between pure magnetic readers and multi-technology hybrid platforms.
Market Dynamics
The coexistence of legacy magnetic infrastructure and contactless payment migration is compressing product lifecycles while forcing hybrid hardware architectures that serve dual-rail transaction environments.
Growth Catalysts
- PCI DSS encryption mandates:Card-present environments in the United States must deploy end-to-end encrypted readers, sustaining replacement demand for compliant hardware modules.
- Transit authority modernization:Municipal fare collection systems in Germany and France retain magnetic fallback for unbanked riders, preserving reader volume in public infrastructure.
- EMV fallback protocols:Chip-read failures at point-of-sale terminals trigger magnetic stripe contingency processing, requiring functional backup readers alongside primary contactless units.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and samarium sourcing dependencies in China create input cost volatility for read head manufacturers.
- Contactless payment substitution:NFC-enabled smartphones and wearable devices displace card-present transactions, eroding addressable volume for pure magnetic hardware.
- REACH substance restrictions:EU RoHS constraints on lead and cadmium in electronic components increase compliance costs for European-bound reader shipments.
Strategic Opportunities
- India POS infrastructure buildout:The RBI-mandated card acceptance push in tier-2 and tier-3 cities creates demand for cost-optimized magnetic readers in merchant acquiring.
- Bluetooth-NFC convergence:Dual-radio handheld units enable mobile point-of-sale flexibility for field service and delivery verticals previously tethered to countertop hardware.
- Access control retrofit cycles:Corporate campus security upgrades in Japan integrate magnetic credential readers with biometric second-factor authentication systems.
Industry Challenges
- Firmware certification timelines:PCI PTS approval processes for encryption modules extend product launch windows by 8-14 months, compressing revenue realization.
- Legacy system integration friction:Decades-old property management and hospitality software stacks resist API connectivity with modern encrypted reader protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Stripe Readers Market |
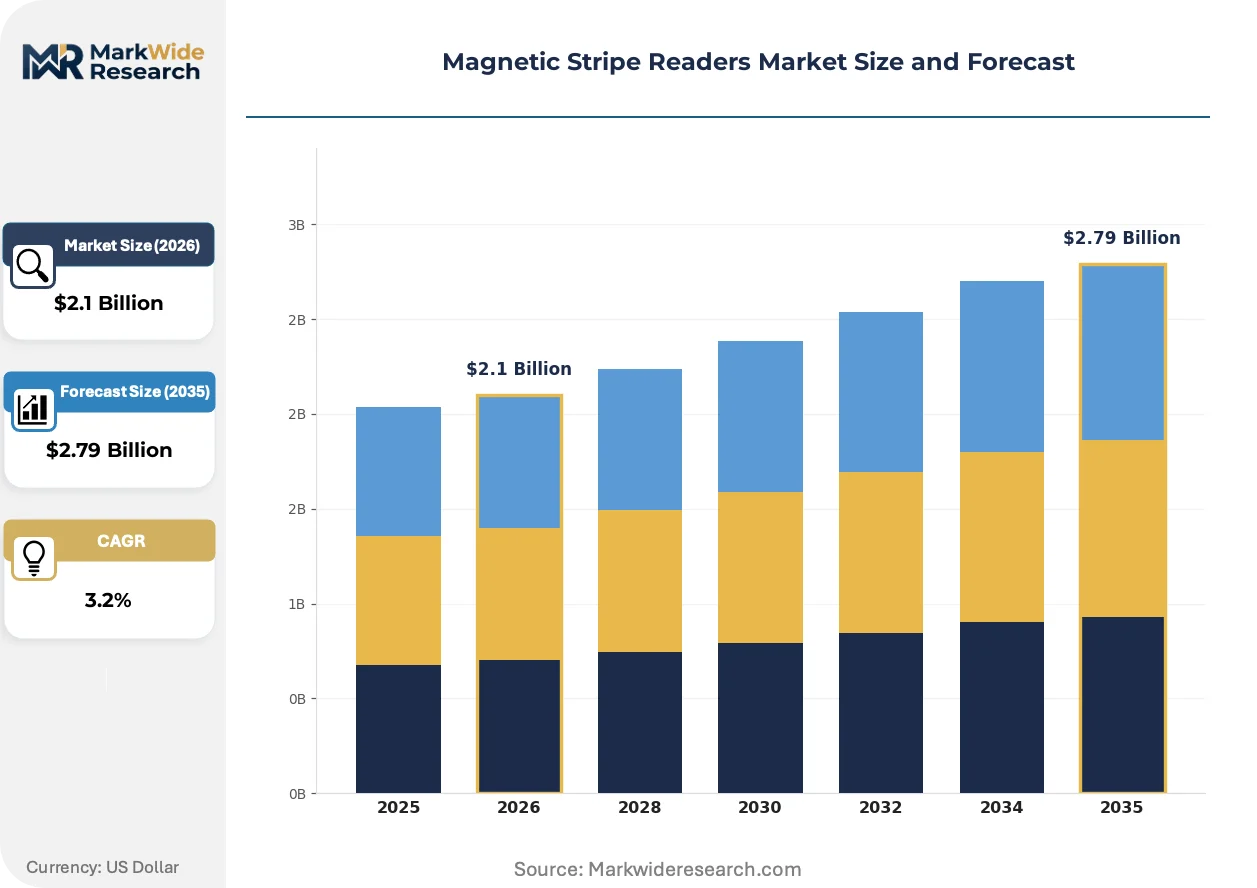
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Readers, Stationary Readers, Integrated Readers, USB Readers End User: Retail Businesses, Hospitality, Transportation Services, Financial Institutions Technology: Magnetic, Bluetooth, NFC, Wired Installation: Onsite, Cloud-Based, Integrated, Standalone |
| Companies Covered | MagTek, ID Tech, Ingenico, Verifone, Square, Zebra Technologies, Honeywell, HID Global, NCR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Stripe Readers Market Shifts & Advancements
Hardware vendors are converging multiple payment rails into single devices while regulatory pressure accelerates security architecture upgrades across card-present infrastructure.
Triple-track magnetic head assemblies with integrated encryption engines are collapsing the distinction between entry-level and enterprise-grade reader categories. Mid-market merchants in the United States now demand AES-256 encryption as standard equipment, eroding the premium tier that previously separated basic swipe readers from PCI-certified modules. This compression is forcing component suppliers to consolidate firmware development across price bands.
EU REACH substance restrictions on hexavalent chromium in metal plating processes are compelling Asian contract manufacturers to retool electroplating lines for European-bound reader housings. The industrial consequence is a bifurcation in production runs: REACH-compliant batches for EU distribution and legacy-process units for other markets. German automotive suppliers embedding readers in fleet fueling systems face the strictest enforcement timelines.
Merchant acquiring banks are unbundling hardware provisioning from processing contracts, enabling direct procurement of certified readers through distributor channels. ISOs and independent software vendors in Brazil now source MagTek and ID Tech units separately from payment gateway relationships, compressing equipment margins while expanding addressable touchpoints. This channel fragmentation is most visible in Latin American markets where acquiring competition has intensified.
Magnetic Stripe Readers Market Segmentation
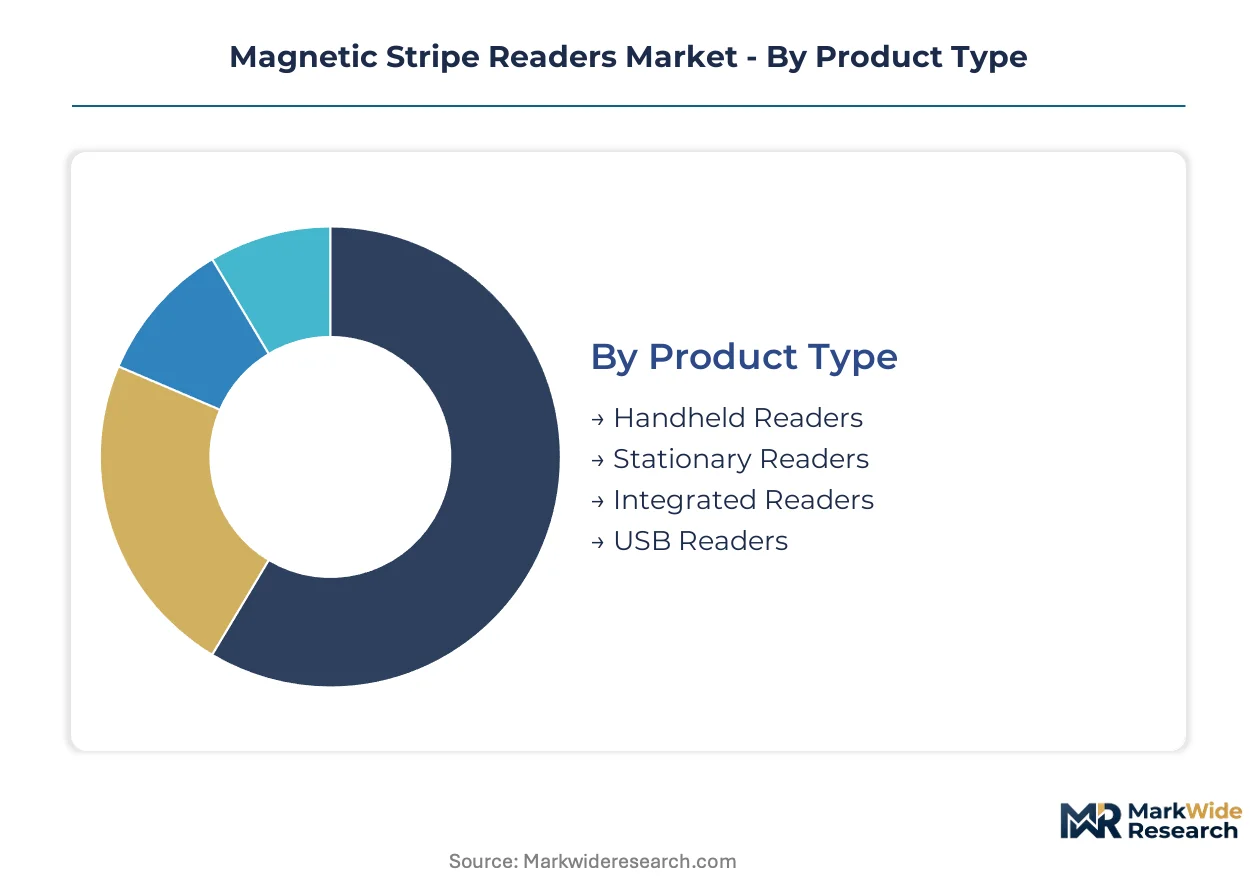
Magnetic stripe reader procurement patterns diverge sharply across hardware configurations and deployment contexts. Understanding these segment boundaries clarifies where PCI DSS compliance investments concentrate versus where cost minimization dominates purchasing decisions.
Product Type:
Hardware refresh cycles vary from 18 months for mobile units to 7-10 years for fixed countertop installations, creating distinct revenue recognition patterns across the category.
- Handheld Readers:Battery-powered units with Bluetooth or USB-C tethering support field service and delivery workflows. Demand clusters with mobile point-of-sale adopters in Brazil and India where merchant acquiring expansion prioritizes portability over countertop permanence.
- Stationary Readers:Fixed-mount devices with heavy-duty read heads and continuous power supply anchor financial institution teller stations and high-volume retail lanes. United States banks and supermarket chains sustain replacement demand through PCI DSS encryption upgrade mandates.
- Integrated Readers:Embedded modules within Verifone or Ingenico terminal ecosystems dominate hospitality and transit verticals where space constraints favor consolidated hardware.
- USB Readers:Compact plug-and-play units from ID Tech and MagTek serve small merchants and software integration projects requiring minimal installation overhead.
Stationary readers anchor the volume base while handheld readers gain share at the steepest rate.
End User:
Customer procurement sophistication spans three tiers: regulated financial entities with dedicated compliance teams, mid-market chains with standardized IT governance, and fragmented small merchants prioritizing upfront cost.
- Retail Businesses:Supermarket chains and big-box stores in the United States deploy hybrid magnetic-NFC readers at checkout lanes to handle EMV fallback scenarios. PCI DSS audit schedules drive synchronized hardware refresh cycles across store networks.
- Hospitality:Hotels and restaurants favor integrated terminal solutions where magnetic readers serve as backup to contactless primary rails. Property management system integration requirements complicate standalone reader procurement.
- Transportation Services:Municipal transit authorities in Germany and France retain magnetic stripe fallback for unbanked ridership segments, preserving dedicated reader infrastructure alongside contactless primary systems.
- Financial Institutions:Banks and credit unions maintain the strictest encryption requirements, mandating end-to-end encrypted readers for all card-present environments regardless of transaction volume.
Financial institutions anchor the volume base while retail businesses gain share at the steepest rate.
Technology:
Radio integration costs and certification burdens stratify pricing across connectivity architectures, with pure magnetic units at the low end and triple-radio hybrids commanding premiums.
- Magnetic:Single-track to triple-track read heads decode ISO/IEC 7811 encoded data through electromagnetic induction. Pure magnetic units retain relevance in cost-sensitive Indian tier-3 city deployments and legacy system extensions.
- Bluetooth:Wireless connectivity enables tablet-based point-of-sale configurations for food delivery and field service applications. FCC Part 15 certification requirements add 3-4 months to product launch timelines for United States-bound shipments.
- NFC:Contactless radio integration supports EMVCo-compliant tap-to-pay transactions, with hybrid NFC-magnetic units capturing merchant preference for consolidated acceptance infrastructure.
- Wired:RS-232 and USB-A connectivity persists in industrial access control and legacy hospitality property management system environments resistant to wireless protocol migration.
Pure magnetic technology anchors the volume base while Bluetooth-enabled configurations expand most quickly.
Installation:
Deployment architecture determines ongoing service revenue potential and customer switching costs, with cloud-connected units enabling recurring firmware management fees.
- Onsite:Locally hosted transaction processing with direct POS system integration dominates high-security financial and government deployments where data sovereignty requirements preclude cloud transmission.
- Cloud-Based:Remote configuration management and over-the-air encryption key rotation appeal to distributed retail chains with limited on-site IT support across multiple locations.
- Integrated:Embedded within broader payment platform ecosystems, these installations lock merchants into specific acquiring relationships through proprietary hardware-software binding.
- Standalone:Independent units with minimal external dependencies serve temporary event commerce and small merchants without integrated POS infrastructure.
Onsite installation anchors the volume base while cloud-based deployment climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PCI DSS mandates enforced by the PCI Security Standards Council anchor the United States as the dominant geography, compelling encrypted reader deployments across card-present environments while transit authorities in Germany and France preserve magnetic fallback infrastructure.
United States
Legacy infrastructure replacement and EMV fallback requirements sustain magnetic stripe reader relevance alongside contactless adoption. FCC Part 15 regulations govern electromagnetic emissions from Bluetooth and NFC-integrated models. Dallas and Atlanta host major payment hardware distribution hubs serving nationwide retail chains.
Germany
Municipal fare collection systems retain magnetic fallback for unbanked riders, preserving dedicated reader volume in public infrastructure. EU REACH and RoHS directives constrain substance composition in devices distributed across German member states. Stuttgart's automotive supplier cluster embeds readers in fleet fueling systems facing strict enforcement timelines.
France
Transit authority modernization programs maintain magnetic stripe contingency processing for accessibility compliance. ANSM and CNIL oversight intersects with payment data handling requirements in healthcare-adjacent deployments. Paris hosts concentrated acquiring bank procurement operations unbundling hardware from processing contracts.
India
RBI-mandated card acceptance expansion in tier-2 and tier-3 cities generates demand for cost-optimized magnetic readers in merchant acquiring. BIS certification requirements shape import compliance for hardware vendors. Mumbai and Bengaluru anchor distributor networks reaching fragmented retail landscapes.
Brazil
ISOs and independent software vendors source encrypted reader modules separately from payment gateway relationships, compressing equipment margins. ANVISA regulations govern devices deployed in healthcare payment contexts. São Paulo concentrates acquiring competition driving channel fragmentation.
Magnetic Stripe Readers Market Competitive Landscape
Encryption-specialist component suppliers and terminal-integrated platform providers split the market between modular hardware and ecosystem-controlled deployments. The vendor base concentrates around three strategic archetypes: firmware-certified encryption engine suppliers, terminal ecosystem integrators, and mobile-first connectivity specialists. Competitive dynamics center on PCI PTS certification speed and acquiring bank channel access rather than manufacturing scale.
Within the encryption-specialist tier, MagTek and ID Tech exemplify divergent hardware philosophies. MagTek represents the OEM-direct archetype sustaining position through certified module relationships with terminal manufacturers. ID Tech occupies the compact USB-connected niche anchoring software integration projects requiring minimal installation overhead. Verifone sits within the ecosystem-control archetype, embedding reader solutions that extend terminal platform reach into hospitality and transit verticals where space constraints favor consolidated hardware.
| Leading Market Players |
|---|
| MagTek |
| ID Tech |
| Ingenico |
| Verifone |
| Square |
| Zebra Technologies |
| Honeywell |
| HID Global |
| NCR Corporation |
| Others |
Supply & Pricing Matrix
Trans-Pacific container freight corridors from Shenzhen and Hong Kong to Long Beach anchor cost dynamics for reader manufacturers sourcing encryption modules from Asian contract manufacturers, with freight rate volatility compressing margins on standard USB readers while configured-to-order units with AES-256 engines retain pricing power through certification scarcity.
Pricing Analysis
The customization-premium spread separates PCI PTS-certified encryption modules from basic swipe readers by a factor reflecting firmware development amortization and audit trail documentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with financial institutions absorbing premium tiers while Indian tier-3 merchants drive cost compression in economy segments. Price differentiation hinges on encryption engine integration and after-sales key management services. Margins are tightening in standard USB-connected units as Brazilian ISOs unbundle hardware from processing contracts.
Supply Chain Analysis
Supplier-financing facilities extended by Taiwanese and South Korean semiconductor foundries ease working capital constraints for encryption chip procurement, though 90-day payment terms strain smaller module assemblers. Read head manufacturing concentrates in China and Japan, with neodymium magnet sourcing dependencies creating input cost volatility. Supply chain risk centers on single-source vulnerability for triple-track head assemblies. Distribution runs through Dallas and Atlanta hubs serving North American retail chains, with Mumbai and São Paulo anchoring emerging market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as merchant acquiring banks unbundle hardware provisioning, creating niches for specialized encryption module suppliers alongside terminal-integrated platform providers.
For Market Incumbents: Entrench position by accelerating PCI PTS certification pipelines to compress 8-14 month approval windows, while securing captive supply of neodymium-based read heads against Chinese export constraint risks. Deepen backward integration into encryption firmware development to defend margin position against modular competitors. For New Entrants and Emerging Players: Pursue white-space opportunity in India's tier-2 and tier-3 city POS infrastructure buildout, where RBI-mandated card acceptance expansion outpaces established vendor coverage. Target Bluetooth-NFC convergence configurations for Brazilian food delivery and field service verticals previously tethered to countertop hardware. For Investors and Strategic Acquirers: Carve-out targets emerge from payment terminal manufacturers seeking to divest non-core reader module operations as hardware-software binding loosens. Long-term viability favors encryption-specialist component suppliers with established OEM-direct relationships over pure-play terminal integrators facing contactless substitution pressure. Monitor EMV fallback transaction volume as inflection indicator for magnetic reader demand persistence.| Strategic Initiative | Industry Significance |
|---|---|
| PCI PTS Certification Acceleration | Compresses 8-14 month firmware approval timelines for encrypted reader modules. |
| Backward Integration into Encryption Engines | Captures margin pools collapsing between entry-level and enterprise reader categories. |
| Bluetooth-NFC Dual-Radio Development | Enables mobile point-of-sale flexibility for field service and delivery verticals. |
| REACH-Compliant Production Bifurcation | Retools Asian contract manufacturing for EU-bound reader housings facing hexavalent chromium restrictions. |
| Channel Unbundling Partnership Structure | Aligns with Brazilian and Indian ISOs sourcing hardware separately from processing relationships. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with payment hardware procurement managers at acquiring banks, firmware engineering leads at encryption module suppliers, and distribution channel partners in Dallas, Mumbai, and São Paulo. Secondary validation drew from PCI Security Standards Council certification databases, FCC Part 15 equipment authorization filings, SEC 10-K disclosures from listed terminal manufacturers, and customs trade data for read head component flows. Bottom-up unit shipment estimates triangulated against top-down payment transaction volume projections across the analysis window.
Calibration against historical PCI DSS mandate implementation curves and EMV migration timelines shaped the analytical framework. Segmentation dimensions modeled include product configuration, end-user vertical, connectivity technology, and installation architecture alongside regional regulatory cluster differentiation. CAGRs derived from slope-consistent trajectory fitting across the projection horizon. Industry-specific forecast inputs encompassed transit authority modernization spend in Germany and France, plus RBI-mandated POS terminal deployment schedules in Indian tier-2 and tier-3 cities.
The forecast holds incumbent behavior within observed patterns; aggressive moves by contactless-only terminal manufacturers or rapid NFC smartphone penetration would shift outcomes. Macroeconomic contraction affecting retail transaction volumes, accelerated REACH substance restriction enforcement, or breakthrough biometric authentication adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Advertising Intelligence Solution Market
Others
Powder Coating Equipment Market
Others
Global Video Processing Platform Market
Others
Workbench Tanks Market
Others
Global Drug Discovery Informatics Market
Others
Linseed Oil Market
Others
Caster Wheels Market
Others
Latin America Smart Home Market
Others
Military Sensors Market
Others
Corn Fiber Market
Others
Edible Insects for Animal Feed Market
Others
Smart Home As a Service Market
Others
Gym Wipes Market
Others
Ultrasonic Flow Meter Market
Others
US Automotive LED Lighting Market
Others
Europe Postal Services Market