
 Evidence Management Market | 2026-2036
Evidence Management Market Size, Share, and Industry Trends Forecast 2026-2036
Evidence Management Market Analysis
Platform bundling is expanding as vendors combine body-worn camera hardware with cloud storage, redaction tools, and prosecution-ready case management into single procurement contracts. Motorola Solutions leverages its LMR infrastructure footprint to anchor integrated evidence suites across municipal police departments. NICE Ltd. competes through specialized digital evidence management for emergency communications and 911 call integration. Genetec Inc. differentiates via open-architecture video management that extends into unified physical security and evidence workflows.
Evidence management encompasses the systematic collection, storage, retrieval, and chain-of-custody tracking of digital and physical evidence across criminal justice and civil proceedings, requiring tamper-proof audit trails, cryptographic hashing for integrity verification, and role-based access controls that satisfy legal admissibility standards. Software solutions dominate revenue as agencies migrate from on-premise servers to SaaS platforms with automatic compliance patching. Cloud services represent the fastest-expanding segment, driven by elastic storage pricing and disaster recovery requirements that on-premise arrays cannot match at equivalent cost.
FBI CJIS Security Policy and state-level evidence retention statutes shape product requirements, mandating encryption standards and access logging that vendors must architect into core platform design. The SEC's recordkeeping rules for financial crimes evidence and EU GDPR data-protection obligations for cross-border evidence transfers add overlapping compliance layers for multinational deployments. Stakeholders must monitor accelerating AI-generated evidence authentication challenges that will strain existing chain-of-custody frameworks and force platform redesigns.
Market Dynamics
Cloud-native evidence platforms are compressing procurement cycles as law enforcement agencies abandon on-premise server arrays for subscription-based SaaS architectures with automatic CJIS compliance patching.
Growth Catalysts
- FBI CJIS Security Policy updates:Federal mandates for digital chain-of-custody documentation are compelling municipal police departments to replace paper-based evidence logs with cryptographically hashed audit trails.
- Body-worn camera infrastructure grants:Federal funding programs are bundling hardware procurement with integrated evidence management software, accelerating platform consolidation.
- Elastic cloud storage pricing:Disaster recovery requirements that on-premise disk arrays cannot satisfy at equivalent cost are pulling agencies toward vendor-hosted solutions with geographic redundancy.
Market Restraints
- Encryption standard fragmentation:Divergent state-level evidence retention statutes create compliance engineering overhead that elongates product development timelines.
- Legacy system integration friction:Decades-old records management databases in county prosecutor offices resist API-based interoperability with modern evidence platforms.
- AI-generated evidence authentication gaps:Deepfake detection capabilities lag behind synthetic media generation tools, straining existing chain-of-custody frameworks.
Strategic Opportunities
- GDPR cross-border evidence protocols:European data-protection obligations for transnational criminal investigations create demand for jurisdictional partitioning features in cloud platforms.
- 911 call center integration:Emergency communications centers seek unified workflows that merge dispatch audio with downstream prosecution case files.
- Rural agency digitization:Smaller sheriff departments with limited IT staffing represent an underpenetrated segment for fully managed evidence services.
Industry Challenges
- Digital forensics talent scarcity:Law enforcement agencies compete with private sector cybersecurity firms for personnel capable of validating cryptographic evidence integrity.
- Multi-jurisdictional access control complexity:Role-based permission schemes must satisfy conflicting municipal, county, state, and federal evidentiary standards simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Evidence Management Market |
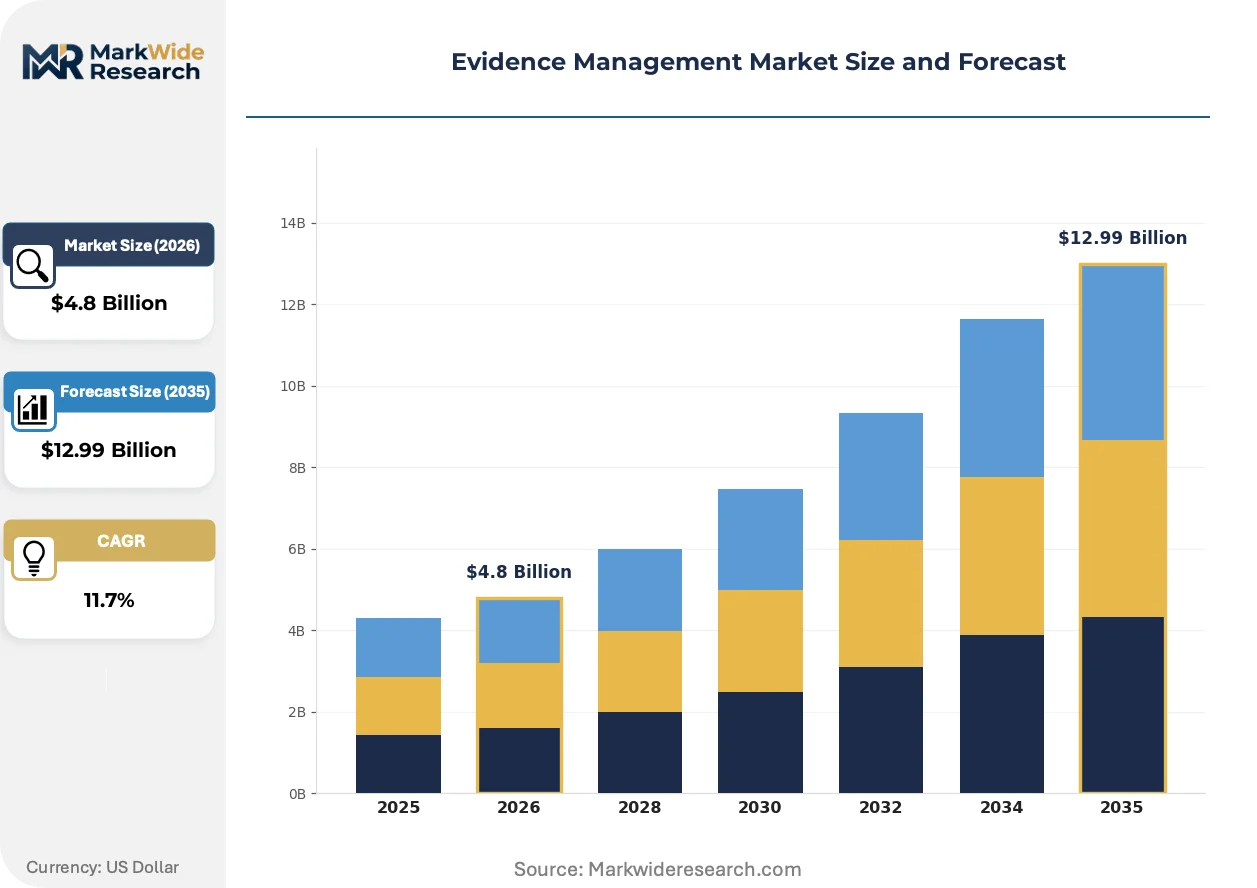
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Cloud Services, Hardware Systems, Mobile Applications End User: Law Enforcement, Legal Firms, Courts, Forensic Labs Technology: Blockchain, AI Analytics, GPS Tracking, Digital Storage Service Type: Consulting, Installation, Maintenance, Training |
| Companies Covered | Axon Enterprise, Inc., Motorola Solutions, NICE Ltd., Genetec Inc., Panasonic Corporation, Oracle Corporation, Cellebrite, OpenText Corporation, Hitachi Vantara Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Evidence Management Market Emerging Trajectories
Blockchain-based audit architectures and automated redaction algorithms are restructuring how evidence integrity gets proven in court, compressing the gap between capture and admissibility.
Hash-based distributed ledger technology is decentralizing custody verification by replacing centralized database logs with immutable timestamp records across redundant nodes. State-level fusion centers are piloting these architectures for multi-agency task force evidence sharing. The shift is compressing discovery dispute timelines by providing cryptographic proof of file integrity without third-party notarization.
EU GDPR Article 48 restrictions on cross-border data transfers are forcing vendors to architect regional data residency options into core platform design. Evidence platforms must now maintain geographically isolated storage clusters with jurisdiction-specific encryption key management. Multinational deployments are responding by segmenting infrastructure between EU and non-EU availability zones.
Subscription-based platform procurement is displacing perpetual license purchases as agencies prioritize operational expenditure predictability over capital asset ownership. Municipal finance departments favor monthly SaaS fees that align with grant reimbursement cycles. This pattern is most visible in mid-sized police departments consolidating previously siloed evidence systems into unified cloud contracts.
Evidence Management Market Segmentation
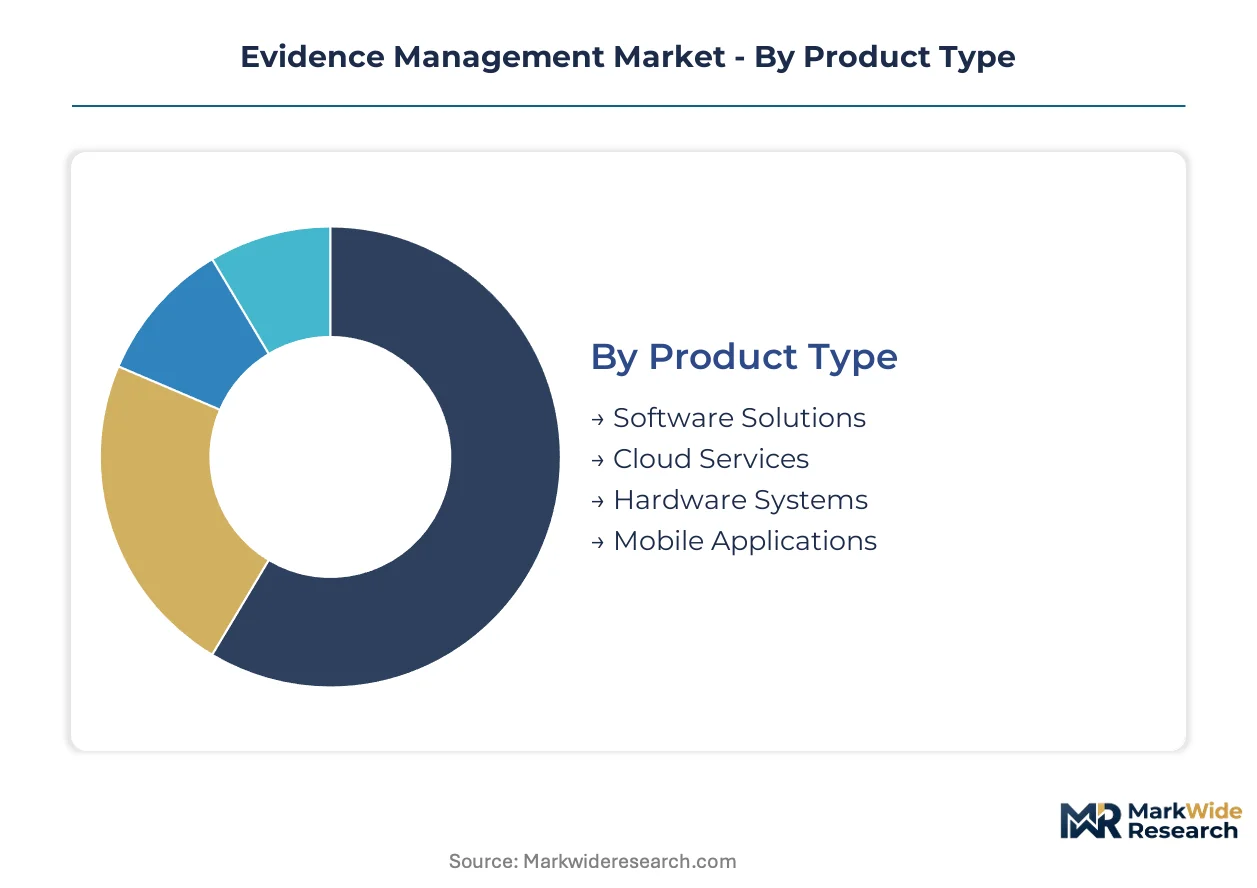
Evidence management segmentation reveals how procurement priorities split between capital-intensive hardware deployments and recurring SaaS subscriptions. Vendors must architect pricing and service models that address divergent compliance requirements across criminal justice, civil litigation, and forensic science workflows.
Product Type:
Software Solutions command premium pricing through CJIS-compliant audit architectures, while Cloud Services compete on elastic storage economics that undercut on-premise total cost of ownership.
- Software Solutions:On-premise and hybrid platforms with cryptographic hashing, role-based access controls, and automated chain-of-custody documentation. Municipal police departments in the United States concentrate procurement here, driven by FBI CJIS Security Policy mandates for tamper-proof audit trails and encryption standards.
- Cloud Services:Vendor-hosted SaaS architectures with geographic redundancy, automatic compliance patching, and subscription-based pricing. Mid-sized agencies across Texas, Florida, and California are migrating fastest, attracted by disaster recovery capabilities and zero capital expenditure models.
- Hardware Systems:Body-worn cameras, in-car video systems, and on-premise storage arrays with specialized evidence-grade encryption.
- Mobile Applications:Field evidence capture tools for smartphones and tablets with offline sync and GPS-tagged metadata.
Today's leader: Software Solutions. Tomorrow's challenger: Cloud Services.
End User:
Law Enforcement absorbs the majority of procurement volume through federal grant programs, while Forensic Labs represent specialized high-margin demand for advanced authentication capabilities.
- Law Enforcement:Municipal police departments, county sheriff offices, and state highway patrol agencies managing body-worn camera footage, digital interviews, and crime scene photography. Agencies in Illinois, Pennsylvania, and Ohio are consolidating previously siloed systems into unified platforms.
- Forensic Labs:State and regional crime laboratories requiring deepfake detection, AI-generated media authentication, and advanced cryptographic validation for court admissibility. These facilities command premium pricing for specialized integrity verification tools.
- Legal Firms:Defense attorneys and prosecutors managing discovery, case preparation, and evidence presentation workflows.
- Courts:Judicial administrators overseeing evidence submission, access control, and retention compliance for active and archived cases.
Law Enforcement dominates current procurement volumes; Forensic Labs are climbing the fastest as AI-generated evidence authentication strains existing frameworks.
Technology:
Digital Storage anchors current infrastructure investments, while Blockchain pilots promise to decentralize custody verification for multi-agency task forces.
- Digital Storage:Encrypted disk arrays, object storage architectures, and hierarchical data management with automated lifecycle policies. County prosecutor offices in Georgia, Michigan, and Arizona rely on these systems for high-volume video evidence retention.
- Blockchain:Distributed ledger architectures providing immutable timestamp records and decentralized custody verification. State-level fusion centers in Virginia and Colorado are piloting these systems for multi-jurisdictional evidence sharing.
- AI Analytics:Automated redaction, object recognition, and pattern detection for efficient evidence review and PII protection.
- GPS Tracking:Geolocation metadata capture and chain-of-custody mapping for mobile evidence collection.
Digital Storage holds installed base dominance; Blockchain represents the steepest expansion trajectory among emerging authentication architectures.
Service Type:
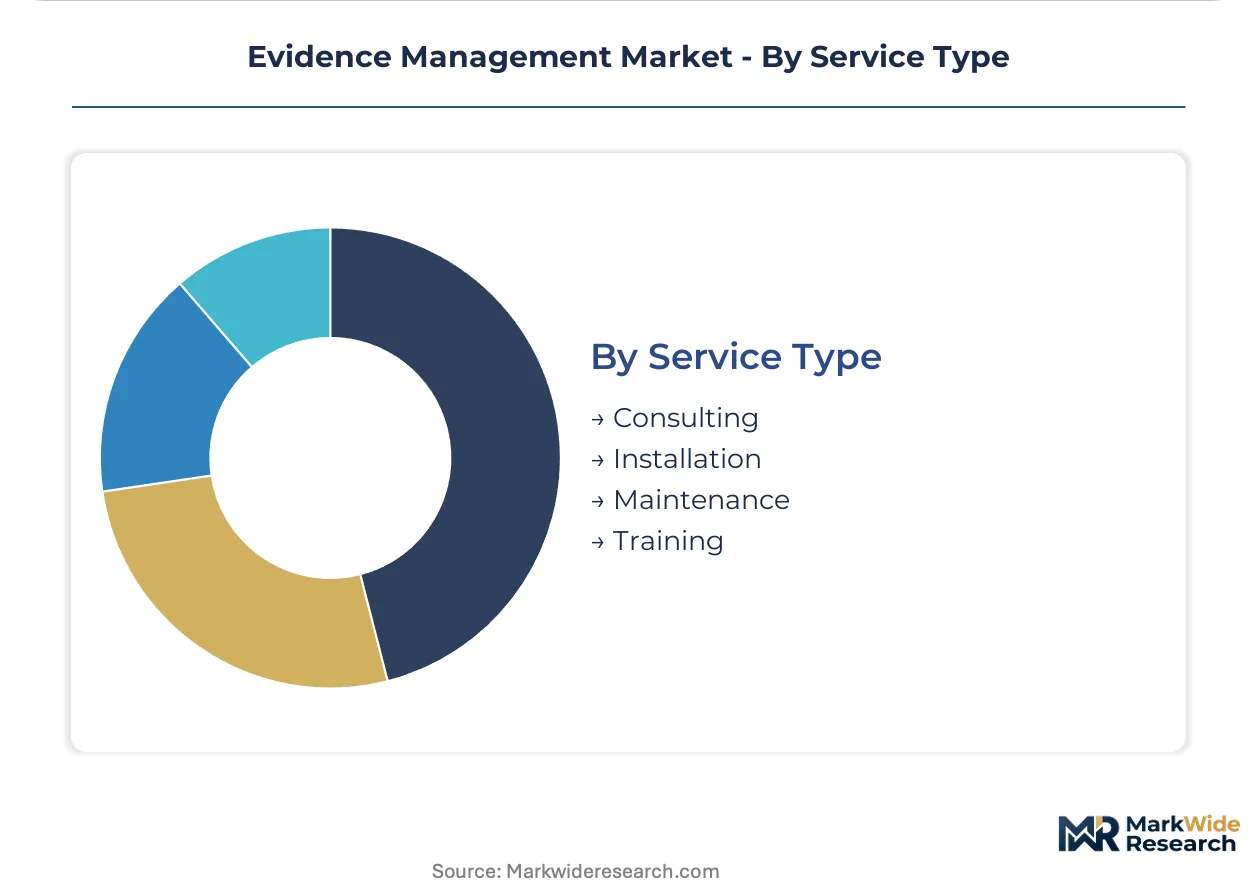
Installation and Maintenance generate recurring revenue streams, while Training commands premium pricing as agencies confront digital forensics talent scarcity.
- Maintenance:Ongoing system updates, security patching, and compliance certification renewals. Rural sheriff departments in Montana, Wyoming, and New Mexico favor fully managed maintenance contracts to compensate for limited internal IT staffing.
- Training:User certification programs, administrator courses, and courtroom testimony preparation for digital evidence specialists. These services address acute talent competition between law enforcement and private sector cybersecurity employers.
- Consulting:Workflow optimization, compliance gap analysis, and migration planning for legacy system transitions.
- Installation:Physical deployment, network integration, and initial configuration of evidence management infrastructure.
Maintenance secures the largest recurring revenue share; Training is gaining share fastest as authentication complexity outpaces agency skill development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Evidence management systems first achieved commercial scale in the United States through federal law enforcement digitization programs during the early 2000s. The technology subsequently diffused to allied jurisdictions with similar common-law evidentiary requirements. Procurement patterns now concentrate in five national markets where CJIS-equivalent standards or GDPR-class data protection regimes govern criminal justice data handling.
United States
Federal grant programs for body-worn camera infrastructure and CJIS Security Policy compliance mandates drive municipal procurement. The FBI's Criminal Justice Information Services division updates encryption and access logging requirements quarterly. Chicago, Los Angeles, and New York metropolitan police departments anchor demand for integrated evidence suites combining hardware and cloud storage subscriptions.
Germany
State-level police modernization budgets and federal constitutional court rulings on digital evidence admissibility accelerate platform adoption. The Federal Criminal Police Office (BKA) coordinates interoperability standards across Länder jurisdictions. Bavarian and North Rhine-Westphalian police forces lead deployment of EU-compliant evidence systems with automated chain-of-custody documentation.
United Kingdom
Home Office digital policing strategies and Crown Prosecution Service evidence disclosure reforms reshape procurement specifications. The National Police Chiefs' Council mandates common data standards for multi-force investigations. London's Metropolitan Police and Greater Manchester Police operate the largest integrated digital evidence repositories outside North America.
Canada
Provincial police service integration initiatives and federal privacy commissioner guidance on law enforcement data retention expand addressable demand. The Royal Canadian Mounted Police sets technical standards adopted by municipal forces. Ontario Provincial Police and Vancouver Police Department pilot cloud-native architectures with geographic redundancy for disaster recovery.
Australia
State-based law enforcement digitization programs and federal attorney-general department evidence management guidelines stimulate market development. The Australian Criminal Intelligence Commission promulgates data exchange protocols for cross-border investigations. New South Wales Police Force and Victoria Police deploy the most extensive body-worn camera fleets in the Asia-Pacific region.
Evidence Management Market Vendor Landscape
The competitive structure tilts toward integrated platform providers with established public safety infrastructure footprints. Tier-one vendors bundle hardware, software, and cloud services into single procurement contracts that displace point-solution competitors. Three archetypes dominate: legacy safety communications integrators extending into evidence workflows, specialized digital forensics software developers, and diversified technology conglomerates repurposing enterprise content management architectures. Consolidation through strategic acquisitions and exclusive municipal infrastructure partnerships constitute the primary competitive moves.
Within the integrated platform tier, Axon Enterprise, Motorola Solutions, and NICE Ltd. occupy positions defined by their adjacent public safety technology foundations. Axon represents the body-worn camera-to-cloud vertical integration archetype. Motorola exemplifies land-mobile radio infrastructure leverage for municipal evidence ecosystem anchoring. NICE sits within the emergency communications and dispatch audio specialization vector. These three entities collectively illustrate how vendor positioning derives from pre-existing agency relationships rather than de novo evidence management capabilities.
| Leading Market Players |
|---|
| Axon Enterprise, Inc. |
| Motorola Solutions |
| NICE Ltd. |
| Genetec Inc. |
| Panasonic Corporation |
| Oracle Corporation |
| Cellebrite |
| OpenText Corporation |
| Hitachi Vantara Corporation |
| Others |
Supply Flow & Price Mechanics
Digital forensics specialists concentrated in Virginia, Texas, and California command salary premiums that compress margins at the mid-market tier while enabling pricing spreads between fully managed SaaS suites and self-hosted software licenses. Labor-cost differentials between coastal tech hubs and inland municipal markets directly shape the three-tier pricing architecture vendors deploy across law enforcement procurement cycles.
Pricing Analysis
Subscription-based platform procurement anchors vendor revenue models, with CJIS-compliant cloud tiers separating premium managed-security packages from standard self-administered configurations. Price differentiation hinges on encryption certification levels and geographic redundancy guarantees, with rural sheriff departments exhibiting highest sensitivity to per-officer monthly fees. Cost compression in the standard tier intensifies as Motorola Solutions and Axon Enterprise bundle hardware subsidies into multi-year SaaS contracts.
Supply Chain Analysis
Direct-to-agency sales channels handle municipal police department demand, while value-added resellers serve smaller county prosecutor offices with limited procurement staff. Hardware component manufacturing concentrates in Taiwan, South Korea, and Mexico for body-worn camera assemblies and encrypted storage arrays. Semiconductor supply for cryptographic processors draws from TSMC's foundry network and Samsung's logic chip facilities. Single-source vulnerability in advanced encryption chip fabrication represents the dominant supply risk. Distribution runs through exclusive municipal infrastructure partnerships and public safety technology integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Evidence Management Market functions as a stable compounder, with federal CJIS compliance mandates providing recurring revenue visibility that insulates vendors from discretionary budget cycles.
For Market Incumbents: To counter cloud-native entrants with zero-capex pricing, Axon and Motorola must deepen backward integration into body-worn camera sensor production while anchoring exclusive municipal LMR infrastructure renewal contracts. Certification investment in FBI CJIS Security Policy pre-approval workflows creates switching costs that protect installed-base pricing power. For New Entrants and Emerging Players: Blockchain-based custody verification offers a technology-first wedge against legacy database architectures, with Virginia and Colorado fusion centers representing the most penetrable pilot customer segment. Target rural sheriff departments in Montana and Wyoming with fully managed evidence services that eliminate internal IT staffing requirements. For Investors and Strategic Acquirers: Public safety technology conglomerates are the most active acquirer in this space, with platform integration capabilities commanding premium multiples. Acquisition candidates with pre-existing CJIS certification and state-level procurement contracts offer the strongest long-term viability within a five-to-ten year holding window. Monitor FBI quarterly policy updates as the critical inflection signal for compliance-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| CJIS Pre-Certification Investment | FBI policy alignment accelerates municipal procurement approval timelines and reduces sales friction. |
| Body-Worn Camera Vertical Integration | In-house sensor production captures hardware margin and tightens cloud subscription bundling control. |
| Blockchain Custody Pilot Deployment | State fusion center validation creates reference architecture for multi-jurisdictional evidence sharing. |
| Rural Agency Managed Services Launch | Fully staffed IT outsourcing addresses Montana and Wyoming sheriff department talent scarcity. |
| GDPR Regional Data Residency Buildout | EU-isolated storage clusters enable German and UK law enforcement contract expansion. |
Methodological Framework
Multiple input streams — interviews with municipal police CIOs, county prosecutor IT directors, and state forensic lab administrators, alongside FBI CJIS policy documentation, federal grant award databases, and vendor SEC filings — were reconciled through bottom-up agency procurement tracking and top-down market sizing validation. Secondary sources included CJIS Security Policy quarterly updates, Bureau of Justice Statistics technology surveys, and municipal budget appropriation records. Cross-referencing primary stakeholder assessments against disclosed contract values ensured triangulation integrity.
Historical spending patterns were cross-referenced against expert panel inputs to construct the projection framework across the analysis window. Segmentation dimensions modeled include deployment architecture, agency size tier, evidence type volume, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted replacement cycle analysis and federal grant funding trajectory assessment. Blockchain adoption curves and AI-generated evidence authentication requirements served as scenario-weighted forecast inputs.
The model holds under stable CJIS policy evolution and continued federal grant appropriations; deviation in encryption standard mandates or grant funding suspension would shift replacement timelines and vendor market share distributions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Solar Lighting Tower Market
Others
North America Micro Market
Others
Moveable Water Tap Market
Others
Global Pregnancy Tracker Apps Market
Others
Astrology Market
Others
Edible Insects for Animal Feed Market
Others
Germany 3D Printing Construction Market
Others
Billet Market
Others
Digital Audio Decoders Market
Others
Indoor LBS Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
UK Cat Food Market
Others
Global Alpha Cypermethrin Market
Others
Czech Republic Market
Others
Hypermarket Market
Others
Cat Food and Snacks Market