
 Citrus Alcohol Market | 2026-2036
Citrus Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Alcohol Market Analysis
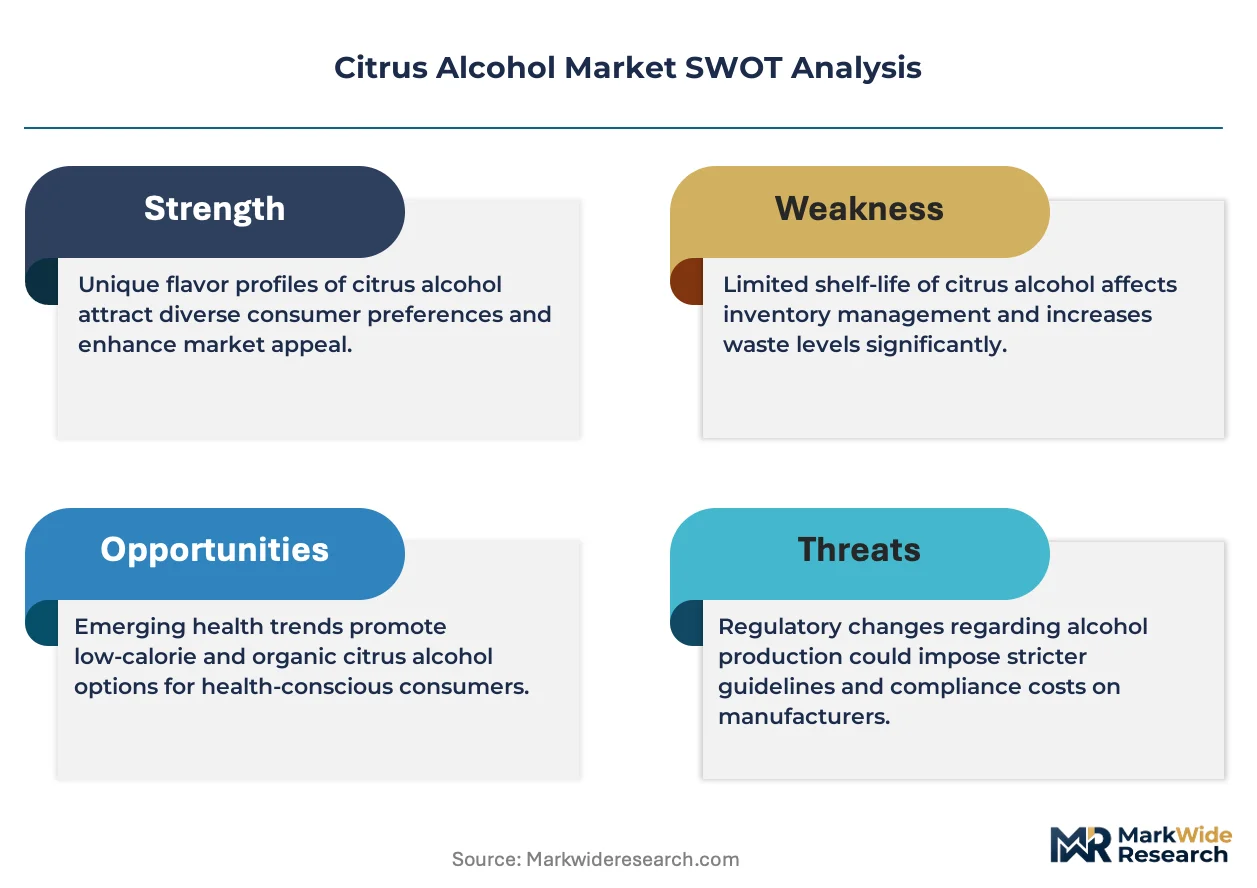
The premium bar and restaurant channel is decoupling from mass-market vodka consumption as mixologists prioritize terroir-specific citrus botanicals. Diageo leverages its global distillation network to secure proprietary citrus varietals across multiple hemispheres. Bacardi Limited anchors Caribbean grapefruit and lime sourcing through long-term grower partnerships in specific island terroirs. Pernod Ricard competes in the artisan gin segment with small-batch lemon and bergamot expressions that command shelf-space premiums in on-premise accounts.
Citrus alcohol denotes ethyl alcohol distilled or compounded with essential oils, peel macerates, or natural extracts from Citrus genus fruits, typically achieving 37.5–47% ABV for gins and 15–40% ABV for liqueurs, with terpene profiles dictating aromatic intensity and oxidation stability during maturation. Gin occupies the dominant value position due to juniper-citrus botanical synergy and premium pricing elasticity, while grapefruit-flavored vodka represents the fastest-expanding flavor profile as health-conscious consumers migrate toward lower-sugar, brighter-tasting clear spirits. The distribution channel structure concentrates margin capture in direct wholesale-to-bar relationships, though online platforms are eroding traditional three-tier control in deregulated jurisdictions.
The EU Spirits Regulation governs geographic indication protection and minimum alcohol content for citrus-distilled products sold across member states, while the FDA enforces flavor additive disclosure and GRAS status for imported citrus oils used in American bottling facilities. India's FSSAI mandates separate licensing for fruit-based distilled beverages, creating compliance thresholds for exporters targeting emerging urban consumption clusters. Stakeholders must monitor evolving excise tax treatments for flavored spirits in key producing states and assess whether captive citrus farming or contracted peel supply delivers superior cost predictability across volatile harvest cycles.
Market Dynamics
Mixology-driven consumption in premium on-premise venues is restructuring procurement relationships, forcing suppliers to bypass traditional wholesale tiers and establish direct-to-bar contracts that guarantee terroir-specific citrus provenance.
Growth Catalysts
- EU Spirits Regulation GI protections:Geographic indication enforcement for citrus-distilled products creates premium pricing corridors for verified-origin botanicals across member states.
- Direct-to-consumer channel expansion:E-commerce platforms in deregulated US jurisdictions erode three-tier distribution control, enabling craft distillers to capture margin previously lost to intermediaries.
- Grapefruit vodka demand surge:Health-conscious clear-spirit consumers migrate from sugar-heavy liqueurs toward bright, lower-calorie flavor profiles in urban cocktail bars.
Market Restraints
- Citrus peel supply volatility:Weather-dependent harvest cycles in Mediterranean and Caribbean growing regions create input cost unpredictability for macerate-dependent producers.
- FDA GRAS compliance costs:Flavor additive disclosure requirements for imported citrus oils impose testing burdens on American bottling facilities sourcing from non-US terroirs.
- Terpene oxidation limitations:Aromatic compound instability during extended maturation constrains shelf-life extension strategies for high-intensity citrus expressions.
Strategic Opportunities
- India FSSAI licensing pathway:Separate fruit-based distilled beverage regulations create first-mover advantages for exporters targeting emerging urban consumption clusters in Mumbai and Bangalore.
- Cold-pressed oil extraction convergence:Integration of supercritical CO2 processing with traditional copper-pot distillation preserves volatile aromatic compounds lost in conventional heat methods.
- Subscription cocktail kit channels:Direct-to-home mixology platforms bypass on-premise gatekeepers, capturing consumer data and building brand loyalty outside bar-controlled discovery.
Industry Challenges
- Master distiller talent scarcity:Specialized expertise in terpene preservation and oxidation management commands premium compensation, constraining mid-tier producer expansion.
- Excise tax classification complexity:Evolving flavored-spirit tax treatments across US state lines create compliance fragmentation and pricing inconsistency for multi-state distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Alcohol Market |
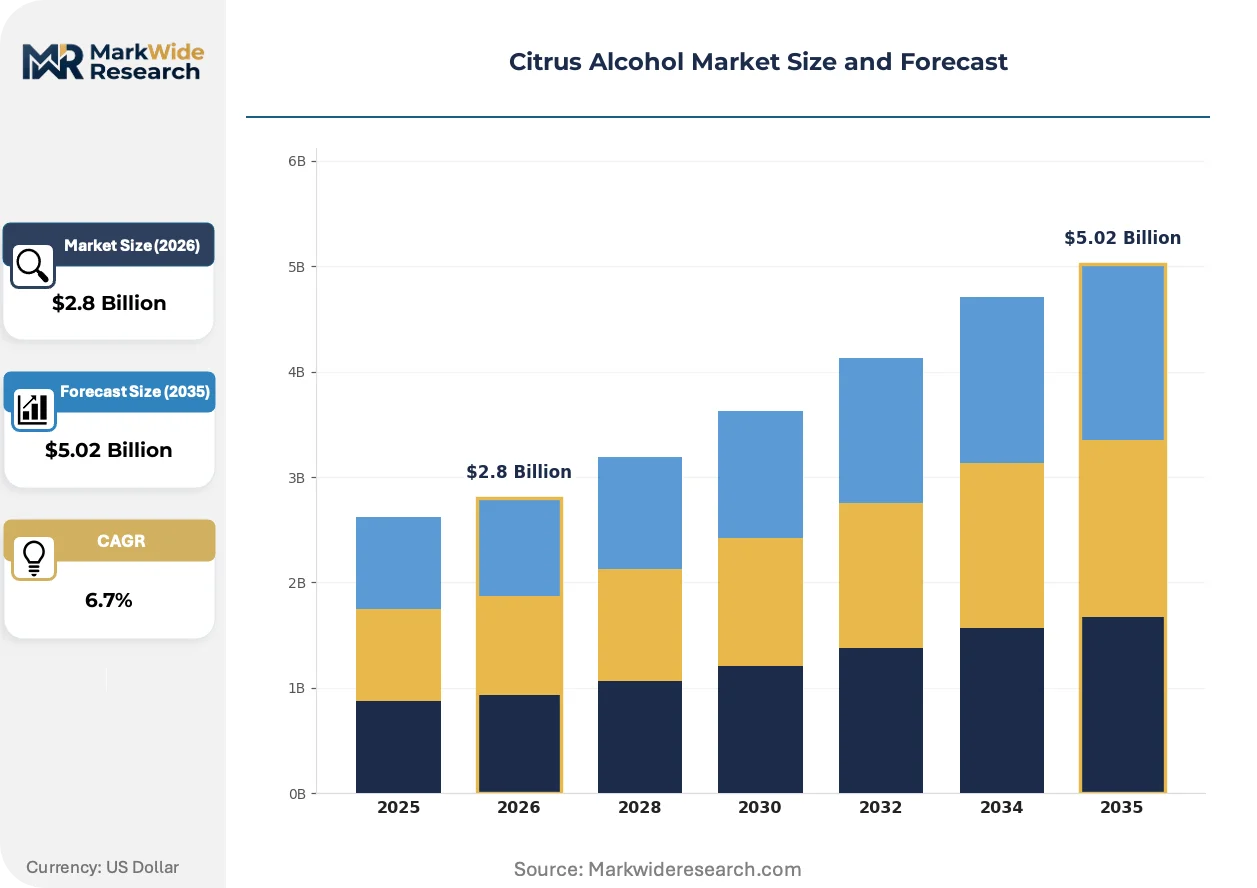
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gin, Vodka, Liqueurs, Schnapps Flavor Profile: Orange, Lemon, Grapefruit, Lime Distribution Channel: Retail Stores, Online, Wholesalers, Supermarkets End User: Bars, Restaurants, Households, Events |
| Companies Covered | Diageo, Bacardi Limited, Pernod Ricard, Beam Suntory, Davide Campari-Milano N.V., Sipsmith, Constellation Brands, E. & J. Gallo Winery, Brown-Forman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Alcohol Market Emerging Trajectories
Distillation technology and distribution architecture are converging to compress time-to-market for terroir-specific expressions while regulatory frameworks harden provenance verification requirements.
Supercritical CO2 extraction is unifying citrus oil recovery with precision terpene fractionation, enabling distillers to isolate specific aromatic compounds without thermal degradation. Premium gin producers in London and New York are adopting these systems at accelerating pace. The technology is unifying quality control with batch consistency, compressing the traditional maceration-to-bottling timeline from months to weeks.
REACH chemical safety assessments are tightening disclosure requirements for imported botanical extracts entering European bottling facilities. Industrial consequence includes mandatory substance registration for non-EU citrus oil suppliers. Small-batch distillers in Scotland and Netherlands are responding by consolidating supplier bases to reduce compliance documentation burden.
On-premise buyer consolidation is reshaping procurement leverage as hotel and restaurant groups centralize beverage purchasing decisions. Independent craft distillers lose shelf-space autonomy to corporate mixology directors specifying approved vendor lists. This concentration is most visible in Los Angeles, Miami, and Austin, where hospitality group scale dominates premium bar openings.
Citrus Alcohol Market Segmentation
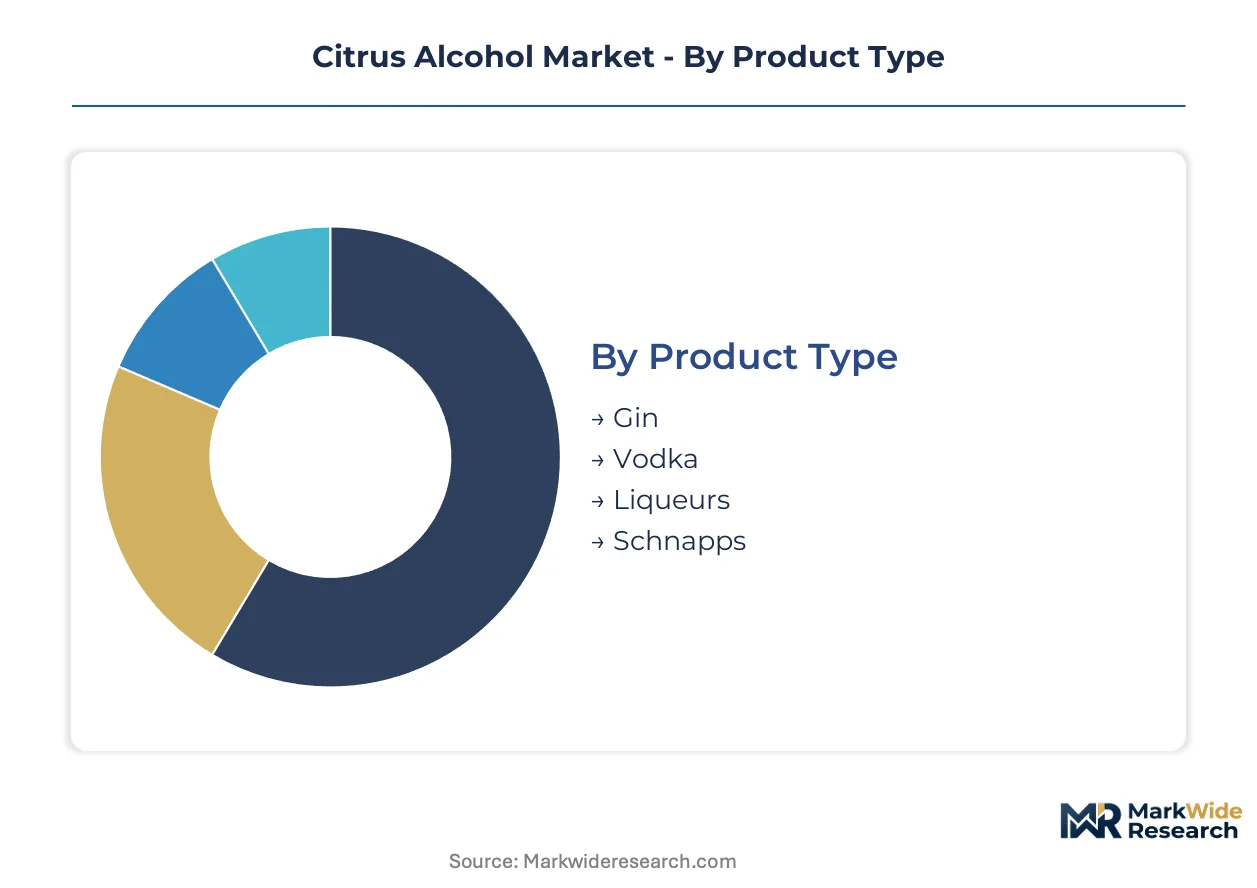
Citrus alcohol producers navigate four intersecting segmentation axes that determine formulation priorities, channel economics, and margin capture. Product type dictates base spirit selection and botanical synergy requirements. Flavor profile governs sourcing geography and terpene stability challenges. Distribution channel and end-user segmentation together determine pricing architecture and regulatory exposure.
Product Type:
Distillation method and botanical loading specifications differentiate competitive positioning across spirit categories.
- Gin:Juniper-citrus botanical synergy defines this category, with London Dry specifications mandating natural flavoring and minimum 37.5% ABV. Premium on-premise accounts in the United States and United Kingdom concentrate demand for terroir-specific citrus expressions that command shelf-space premiums.
- Vodka:Neutral grain or potato bases accept citrus infusion through post-distillation flavoring, with grapefruit variants expanding most quickly among health-conscious clear-spirit consumers seeking lower-calorie alternatives to sugar-heavy liqueurs.
- Liqueurs:Sugar-dosed formulations at 15-40% ABV rely on peel macerates and essential oil compounding for aromatic intensity, with oxidation stability constraining extended maturation strategies.
- Schnapps:Germanic traditions of fruit brandy distillation produce higher-ABV expressions with less residual sugar, appealing to specialized import markets and heritage cocktail programs.
Gin leads on scale; grapefruit vodka leads on momentum.
Flavor Profile:
Sourcing geography and harvest volatility create divergent supply economics across citrus varietals.
- Orange:Sweet orange peel from Mediterranean and Florida groves supplies bitter curacao traditions and triple-sec liqueur formulations, with Valencia and Seville varietals commanding premium positioning in craft distilling.
- Lemon:Amalfi and Sicilian lemon expressions anchor Italian spirits heritage, with bergamot-crossover products gaining traction in artisan gin portfolios targeting mixology-driven urban markets.
- Grapefruit:Caribbean and Texas Rio Star sourcing supports the fastest-expanding flavor trajectory as consumers migrate from sugar-heavy alternatives toward bright, lower-calorie profiles in cocktail bars.
- Lime:Mexican Key lime and Persian lime peel supplies dominate tequila-adjacent and tropical cocktail formulations, with weather-dependent harvest cycles in Veracruz creating input cost unpredictability.
Orange maintains volume leadership; grapefruit climbs fastest.
Distribution Channel:
Channel selection determines margin capture, regulatory burden, and consumer data access.
- Retail Stores:State-controlled liquor outlets and independent bottle shops concentrate mass-market volume, with three-tier compliance costs and excise tax fragmentation constraining multi-state craft distribution.
- Online:E-commerce platforms in deregulated US jurisdictions erode traditional wholesale control, enabling direct-to-consumer margin capture and subscription cocktail kit expansion.
- Wholesalers:Traditional tier-one distributors retain leverage in controlled states, though on-premise buyer consolidation is compressing independent craft shelf-space autonomy.
- Supermarkets:Grocery alcohol sales in select states and European markets prioritize volume velocity and promotional pricing, favoring established brands with production scale.
Wholesalers dominate volume; online channels expand most rapidly.
End User:
Consumption occasion and procurement authority shape formulation and packaging decisions.
- Bars:Mixology-driven premium venues prioritize terroir-specific provenance and direct supplier relationships, with corporate hospitality group purchasing centralizing vendor selection in Los Angeles, Miami, and Austin.
- Restaurants:Beverage program integration demands versatile citrus expressions that pair across menu categories, with wine-and-spirits directors specifying approved vendor lists that constrain independent craft access.
- Households:At-home cocktail experimentation surged through direct-to-home subscription platforms, capturing consumer data and building brand loyalty outside on-premise gatekeepers.
- Events:Catering and wedding markets favor volume-efficient formats and recognizable flavor profiles, with procurement typically routed through wholesale distributors rather than direct craft relationships.
Bars command premium pricing; households show steepest channel shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors the premium citrus spirits trade through its concentration of mixology-driven hospitality groups and direct-to-bar procurement networks. The United States, United Kingdom, Germany, India, and Australia represent the five principal demand centers where regulatory frameworks and consumption patterns diverge sharply.
United States
Mixology-driven consumption in premium venues accelerates demand for terroir-specific citrus botanicals. The FDA enforces GRAS status requirements for imported citrus oils, imposing testing burdens on bottling facilities sourcing from non-US terroirs. Los Angeles, Miami, and Austin concentrate corporate hospitality purchasing power that centralizes vendor selection and constrains independent craft shelf-space autonomy.
United Kingdom
London Dry gin specifications mandate natural flavoring and minimum ABV thresholds, preserving heritage distillation standards. REACH chemical safety assessments tighten disclosure requirements for imported botanical extracts entering English and Scottish bottling facilities. Premium gin producers in London and Edinburgh adopt supercritical CO2 extraction systems to isolate aromatic compounds without thermal degradation.
Germany
Schnapps traditions of fruit brandy distillation sustain specialized import markets and heritage cocktail programs. The EU Spirits Regulation governs geographic indication protection for citrus-distilled products sold across member states. Bavaria and Baden-Württemberg concentrate craft distilling capacity where small-batch producers consolidate supplier bases to reduce compliance documentation burden.
India
Emerging urban consumption clusters in Mumbai and Bangalore create first-mover advantages for exporters navigating separate fruit-based distilled beverage licensing. The FSSAI mandates distinct regulatory pathways for citrus alcohol imports, creating compliance thresholds for foreign suppliers. Maharashtra and Karnataka host the fastest-expanding metropolitan bar cultures where mixology education programs accelerate premium spirits adoption.
Australia
Direct-to-consumer channel expansion through e-commerce platforms erodes traditional wholesale control in deregulated jurisdictions. The country's national food standards regulator enforces labeling requirements for flavored spirits entering retail distribution. Sydney and Melbourne concentrate craft distilling innovation where subscription cocktail kit platforms capture consumer data and build brand loyalty outside on-premise gatekeepers.
Citrus Alcohol Market Vendor Landscape
Direct-to-bar contract establishment dominates the current landscape as suppliers bypass traditional wholesale tiers to guarantee terroir-specific citrus provenance. The market structure concentrates around multinational spirits conglomerates with global distillation networks, mid-tier craft specialists with regional botanical sourcing, and emerging direct-to-consumer brands with subscription distribution models. Three strategic archetypes prevail: scale-driven portfolio diversifiers, terroir-focused craft distillers, and technology-enabled direct brands. Geographic expansion and cold-pressed oil extraction convergence represent the two dominant competitive moves reshaping procurement relationships.
Within the scale-driven tier, Diageo, Bacardi Limited, and Pernod Ricard exemplify multinational positioning through proprietary citrus varietal networks and long-term grower partnerships. These London-based, Bermuda-headquartered, and Paris-based entities occupy positions that leverage global distillation infrastructure to secure supply continuity across volatile harvest cycles. Their collective presence anchors the premium on-premise channel where mixologists prioritize verified-origin botanicals.
| Leading Market Players |
|---|
| Diageo |
| Bacardi Limited |
| Pernod Ricard |
| Beam Suntory |
| Davide Campari-Milano N.V. |
| Sipsmith |
| Constellation Brands |
| E. & J. Gallo Winery |
| Brown-Forman Corporation |
| Others |
Supply Flow & Price Mechanics
Supercritical CO2 extraction adoption is compressing production timelines from months to weeks while simultaneously elevating capital requirements and concentrating technical capability among producers with distillation-network scale. This technology shift feeds directly into pricing power asymmetries between craft specialists and multinational spirits conglomerates.
Pricing Analysis
Input-cost pass-through from volatile citrus peel harvests dominates pricing dynamics across terroir-specific expressions. Three-tier pricing structure across premium, standard, and economy levels separates verified-origin botanical gins from commodity-flavored vodkas and mass-market liqueurs. Price differentiation hinges on geographic indication certification and direct-to-bar contract exclusivity. Cost compression in the mid-tier is intensifying because weather-dependent Mediterranean and Caribbean harvest cycles create margin unpredictability for macerate-dependent producers. Corporate hospitality groups show lowest price sensitivity, while independent retail consumers demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Mexican Key lime and Persian lime peel supplies that anchor tequila-adjacent and tropical cocktail formulations. Geographic supply concentration clusters in Spain, Italy, and Mexico for sweet orange and lemon varietals, with Caribbean islands dominating grapefruit sourcing. Raw material dependencies encompass cold-pressed essential oils, copper-pot distillation equipment, and supercritical CO2 processing systems. Tariff exposure on imported citrus oils entering American bottling facilities creates compliance cost unpredictability. Distribution runs through direct wholesale-to-bar relationships in premium channels, with e-commerce platforms eroding traditional three-tier control in deregulated US jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Spirits Regulation geographic indication enforcement creates premium pricing corridors that accelerate with each provenance verification tightening.
For Market Incumbents: Cement proprietary citrus varietal networks through long-term grower partnerships in specific island terroirs and Mediterranean groves. Secure master distiller talent pools through specialized compensation structures that address terpene preservation expertise scarcity. Vertical integration into captive peel supply or contracted harvest agreements delivers superior cost predictability across volatile growing cycles than spot-market sourcing. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable route for bypassing on-premise gatekeepers and corporate hospitality vendor lists that constrain independent craft shelf-space autonomy. Target emerging urban consumption clusters in Mumbai and Bangalore where FSSAI licensing pathways create first-mover structural advantages. Subscription cocktail kit platforms capture consumer data and build brand loyalty outside bar-controlled discovery mechanisms. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier craft distillers with regional botanical sourcing because on-premise buyer consolidation is compressing independent shelf-space autonomy and forcing scale-dependent procurement leverage. Long-term viability favors entities with cold-pressed oil extraction convergence and direct-to-bar contract infrastructure. The signal to monitor is corporate hospitality group purchasing centralization in Los Angeles, Miami, and Austin as an inflection indicator for vendor-list consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressed Oil Extraction Convergence | Supercritical CO2 processing preserves volatile aromatic compounds lost in conventional heat methods. |
| Direct-to-Bar Contract Establishment | Bypassing wholesale tiers guarantees terroir-specific citrus provenance for mixology-driven venues. |
| Geographic Indication Certification Investment | EU Spirits Regulation enforcement creates premium pricing corridors for verified-origin botanicals. |
| Subscription Cocktail Kit Channel Launch | Direct-to-home platforms capture consumer data outside bar-controlled discovery mechanisms. |
| Captive Citrus Farming Integration | In-house peel supply delivers cost predictability across volatile Mediterranean harvest cycles. |
Methodological Framework
Direct dialogue with master distillers, citrus grower cooperative managers, corporate beverage directors at hospitality groups, and regulatory affairs specialists at spirits bottling facilities grounded qualitative insights. Secondary validation drew from EU Spirits Regulation filings, FDA GRAS status determinations, FSSAI licensing records, and customs trade data on citrus oil imports. Bottom-up and top-down triangulation reconciled producer capacity disclosures with channel shipment patterns.
Bottom-up modeling anchored volume and value outputs across the analysis window through product-type, flavor-profile, distribution-channel, and end-user segmentation dimensions. CAGRs were derived from trend-line extrapolation of mixology-driven consumption patterns and direct-to-consumer channel penetration curves. Forecast inputs incorporated harvest cycle volatility indices and excise tax treatment evolution across US state jurisdictions.
Weather-induced harvest disruption, regulatory licensing delays in emerging markets, and master distiller talent scarcity are the dominant revision risks that could compress or extend projected trajectory bands. Forecasts reflect documented assumptions on consumer migration patterns from sugar-heavy liqueurs toward bright, lower-calorie clear spirits. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
Decanter Market
Alcoholic Beverages
Lager Market
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
Germany Wine Coolers Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Rose Wine Market
Alcoholic Beverages
Global Food-Grade Alcohol Market
Alcoholic Beverages
Germany Alcohol E-Commerce Market
Alcoholic Beverages
Alcoholic Beverages Market
Alcoholic Beverages
Global Bars and Nightclubs Market
Alcoholic Beverages
White Wine Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Rice Wine Market
Alcoholic Beverages
North America Soju Market