
 Cognac Brandy Market | 2026-2036
Cognac Brandy Market Size, Share, and Industry Trends Forecast 2026-2036
Cognac Brandy Market Insights
Aftermarket service revenue from cask finishing and private barrel programs is narrowing the margin gap between distillation and direct-to-consumer sales. Hennessy leverages its Charente-based distillery network to sustain volume leadership across VSOP and XO tiers. Rémy Martin anchors its position through extended aging commitments in Grande Champagne vineyards. Martell competes aggressively in Asian travel retail through controlled allocation to duty-free operators.
Cognac brandy denotes a grape-derived spirit double-distilled in copper pot stills and aged a minimum of two years in French oak barrels from Limousin or Tronçais forests, producing eaux-de-vie blended to specified age statements. The product type spectrum spans VS, VSOP, XO, and Extra classifications, with XO commanding concentrated margin pools following the minimum age threshold elevation to ten years. Duty-free shops within the distribution channel channel represent the fastest-growing value corridor, while glass bottles dominate packaging type due to premium positioning requirements and regulatory prohibitions on alternative formats for aged spirits.
The Bureau National Interprofessionnel du Cognac enforces appellation standards alongside EU GI protections that restrict geographic production to six designated crus, directly constraining supply expansion and reinforcing scarcity premiums. French customs and excise authorities, coordinated with EU-wide excise duty frameworks, shape cross-border pricing architecture and travel retail economics. Stakeholders must monitor evolving EU-UK spirits trade arrangements and Asian import tariff negotiations that could restructure competitive access across the most valuable consumption corridors.
Market Dynamics
EU appellation d'origine contrôlée enforcement is tightening supply constraints across six designated crus, forcing producers to compete through aging depth and cask finishing rather than volume expansion.
Growth Catalysts
- Grande Champagne vineyard scarcity:Extended aging commitments in premier cru zones concentrate collector demand and justify premium tier pricing.
- REACH-compliant oak sourcing:French cooperage standards for Limousin and Tronçais forest timber reinforce terroir authenticity claims in export markets.
- Asian duty-free corridor expansion:Controlled allocation strategies to travel retail operators in China and South Korea unlock high-margin direct-to-consumer channels.
Market Restraints
- Ugni Blanc grape supply concentration:Single-variety dependency across Charente and Charente-Maritime departments creates vintage vulnerability and input cost volatility.
- Copper pot still fabrication bottlenecks:Artisanal distillation equipment from specialized French metalworkers limits capacity scaling for new market entrants.
- EU-UK spirits trade friction:Post-Brexit excise duty harmonization gaps complicate cross-channel pricing architecture and inventory positioning.
Strategic Opportunities
- Private barrel programs:Cask finishing services for ultra-high-net-worth collectors generate aftermarket revenue streams beyond standard bottling margins.
- CSRD-aligned sustainability disclosure:Carbon footprint transparency in vineyard and distillation operations attracts ESG-mandated institutional capital.
- Digital provenance authentication:Blockchain-based eaux-de-vie tracking from cru to bottle combats counterfeiting in Asian luxury retail channels.
Industry Challenges
- Master blender succession gaps:Generational transfer of organoleptic expertise for eaux-de-vie selection and marriage protocols faces demographic compression.
- Aged inventory carrying costs:XO minimum ten-year maturation requirements demand sustained capital commitment through interest rate cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognac Brandy Market |
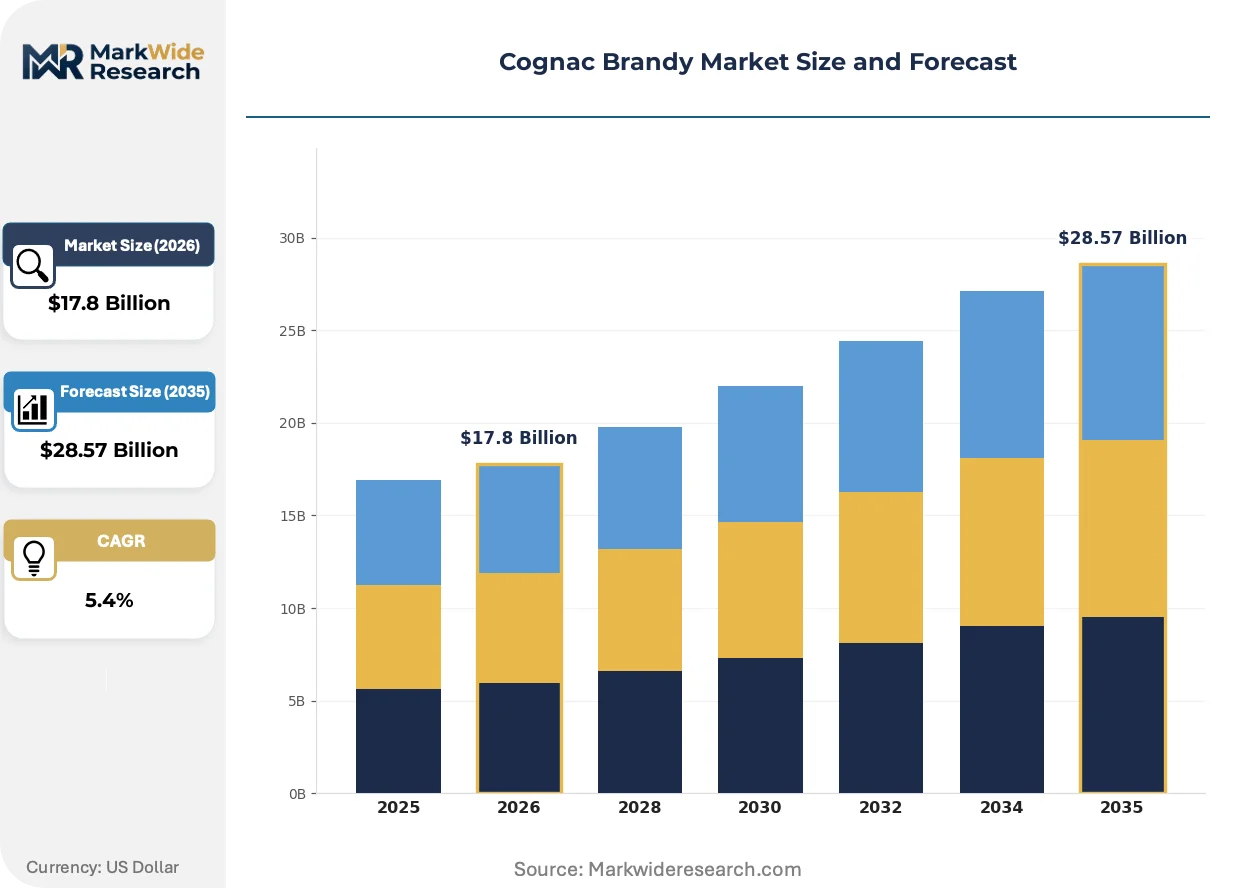
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $28.57 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VS, VSOP, XO, Extra End User: Bars, Restaurants, Retailers, Private Consumers Packaging Type: Glass Bottles, Tetra Packs, Kegs, Cans Distribution Channel: Online, Offline, Wholesalers, Duty-Free Shops |
| Companies Covered | Hennessy, Rémy Martin, Martell, Courvoisier, D'Ussé, Pierre Ferrand, Ferrand Cognac, Augier, Gautier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognac Brandy Market Trends and Innovations
Copper pot still telemetry and climate-adaptive viticulture are compressing traditional craft cycles while EU sustainability mandates reshape compliance investment priorities across the value chain.
Spectroscopic analysis is digitizing eaux-de-vie quality assessment during distillation and blending operations. Large houses deploy real-time chemical profiling to accelerate batch consistency decisions. This instrumentation is digitizing organoleptic judgment that previously required decades of apprenticeship, compressing quality assurance timelines.
EU F-Gas Regulation phase-down schedules are pressuring refrigeration-dependent cellar operations to retrofit climate control systems. Producers face capital allocation trade-offs between energy efficiency upgrades and cask inventory expansion. Grande Champagne houses with deep aged stock reserves absorb these retrofit costs more readily than newer entrants.
Collector procurement now favors verified provenance over distributor relationships. Asian auction houses and direct-to-consumer platforms displace traditional import-wholesale-retail hierarchies. This channel disintermediation concentrates margin capture with producers who control allocation to Shanghai, Hong Kong, and Singapore private client programs.
Cognac Brandy Market Segmentation
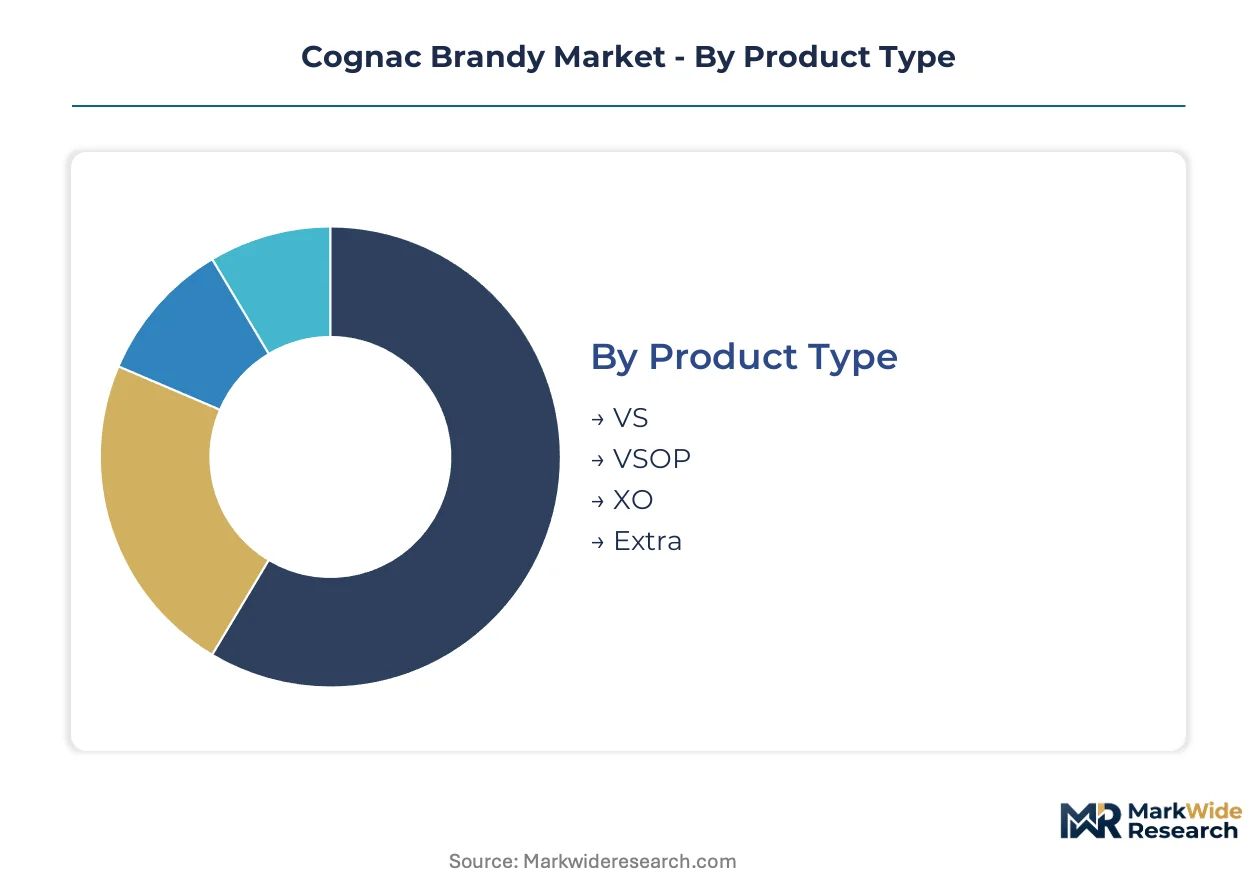
Cognac brandy segmentation reveals stark inventory velocity differences across age tiers, with maturation cycles directly constraining working capital deployment and margin capture strategies. Understanding these turnover patterns allows producers to optimize barrel allocation and channel pricing.
Product Type:
Maturation timelines create the most pronounced cycle-time stratification in cognac, with minimum aging requirements spanning two to ten years across classifications.
- VS (Very Special):Minimum two-year aging in French oak produces the highest-volume, fastest-turning inventory tier. Bars in the United States absorb the majority of VS volume for cocktail applications where oak character remains subtle.
- VSOP (Very Superior Old Pale):Four-year minimum maturation balances accessibility with developed complexity. Restaurants in China concentrate demand here for banquet service where bottle presentation carries social signaling weight.
- XO (Extra Old):Ten-year minimum aging creates the longest capital lock-up cycle. Collector demand in Asian duty-free corridors absorbs allocated XO releases despite premium positioning.
- Extra:Extended aging beyond XO thresholds targets ultra-high-net-worth private clients. Limited releases through direct-to-consumer programs bypass traditional wholesale channels.
VS anchors the volume base while XO gains share at the steepest rate.
End User:
Consumption occasion and purchase authority divide end users across on-premise, off-premise, and direct channels with distinct margin profiles.
- Bars:Mixology-forward venues in the United States drive VS and VSOP volume through cocktail programs. Bartender education investments from major houses sustain brand visibility in this channel.
- Restaurants:Fine dining establishments in China and South Korea concentrate XO and Extra consumption for celebratory meals. Sommelier relationships determine allocation access for limited releases.
- Retailers:Specialty spirits merchants in France and the United Kingdom curate aged stock for enthusiast collectors. Shelf space negotiations favor houses with provenance documentation capabilities.
- Private Consumers:Direct procurement through estate visits and private client programs bypasses margin-stacking intermediaries. Asian collectors dominate this segment through auction participation and allocation relationships.
Restaurants command the highest per-bottle margins while private consumers expand most quickly.
Packaging Type:
Regulatory frameworks and premium positioning requirements constrain format innovation, concentrating volume in traditional glass presentations.
- Glass Bottles:Mandatory for all aged cognac under EU appellation standards. Limousin oak cask finishing references on labels reinforce terroir authenticity claims.
- Tetra Packs:Prohibited for AOC-protected cognac; limited to brandy-style products outside protected designation. No significant volume in authentic cognac.
- Kegs:Emerging format for high-volume on-premise accounts in the United States. Dispense systems reduce per-serve labor costs for busy bars.
- Cans:Regulatory exclusion from aged spirit categories; absent from legitimate cognac distribution. Alternative spirits occupy this format.
Glass bottles dominate absolute volume while kegs climb the fastest among permissible alternatives.
Distribution Channel:
Channel selection determines tax treatment, margin retention, and consumer access to verified provenance documentation.
- Online:Direct-to-consumer platforms in China and Singapore displace traditional import hierarchies. Blockchain verification capabilities attract collector procurement.
- Offline:Brick-and-mortar retail in France maintains heritage positioning through chateau visitation programs. Tasting room conversions sustain margin capture.
- Wholesalers:Traditional three-tier distribution in the United States constrains producer pricing power. State-by-state licensing fragments market access.
- Duty-Free Shops:Travel retail operators in Shanghai, Hong Kong, and Seoul control allocation to Asian collectors. Controlled scarcity drives premium realization.
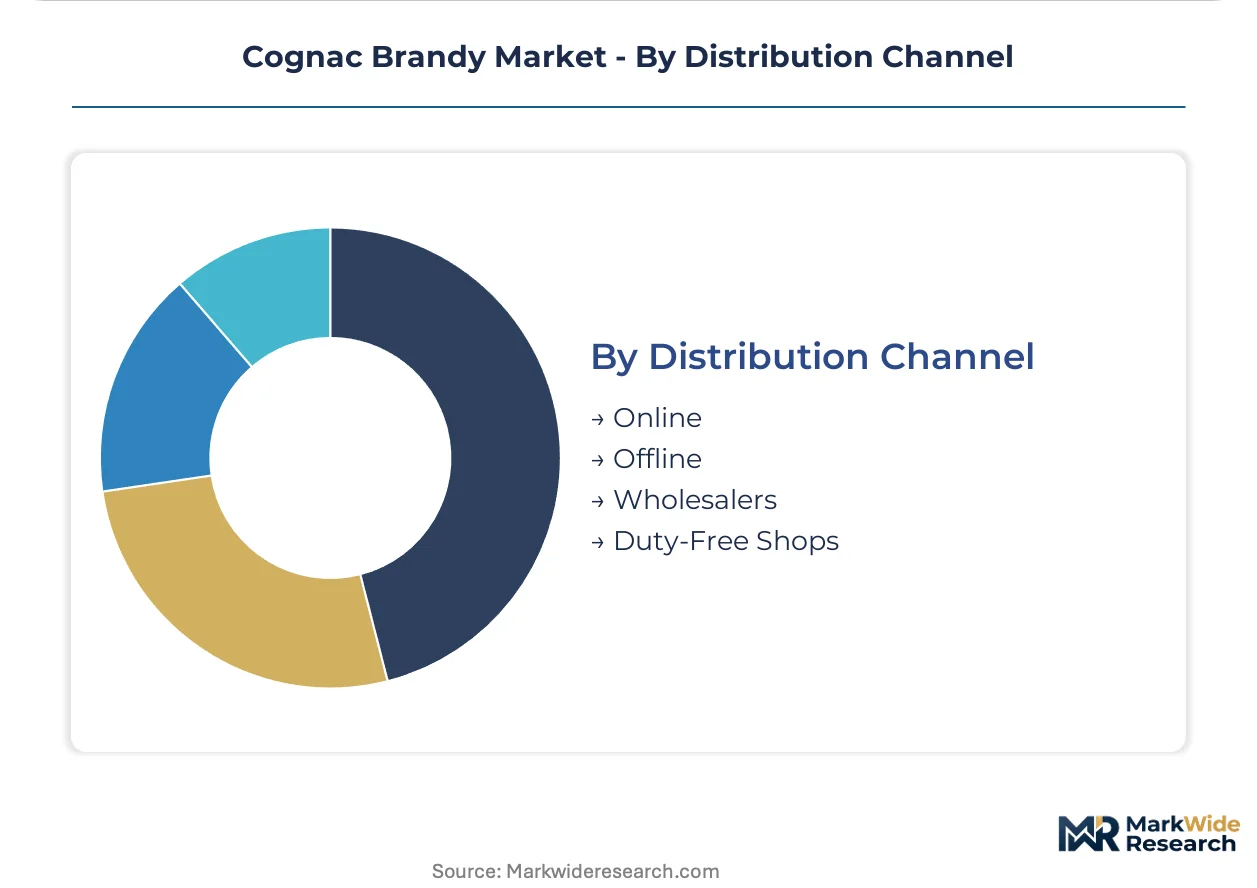
Offline channels anchor the volume base while duty-free shops gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across borders. The United States absorbs younger classifications for cocktail applications while China concentrates demand in aged tiers for ceremonial gifting. European markets sustain heritage positioning through chateau visitation and direct estate relationships.
United States
Mixology-forward bars in New York and Los Angeles drive VS and VSOP volume through cocktail programs. State-by-state licensing under the three-tier system fragments producer pricing power. Kentucky and Tennessee hospitality clusters absorb allocated releases for bourbon-cognac crossover events.
China
Banquet culture in Shanghai and Beijing concentrates XO and Extra consumption for social signaling. NMPA import registration requirements shape cross-border pricing architecture. Hainan duty-free operators control allocation to ultra-high-net-worth collectors through private client programs.
France
Charente and Charente-Maritime departments anchor production under EU GI protection. ANSM coordinates with the Bureau National Interprofessionnel du Cognac on appellation enforcement. Cognac city tourism infrastructure sustains direct-to-consumer conversion through estate visitation programs.
United Kingdom
London specialty merchants curate aged stock for enthusiast collectors seeking verified provenance. Post-Brexit excise duty harmonization gaps complicate cross-channel inventory positioning. Edinburgh and Glasgow hospitality clusters maintain independent allocation relationships with Grande Champagne houses.
South Korea
Seoul luxury retail corridors absorb premium tier releases for corporate gifting occasions. MFDS import clearance timelines shape seasonal availability for duty-free operators. Incheon International Airport travel retail operators control scarcity-driven allocation to Asian collectors.
Cognac Brandy Market Competitive Landscape
Capability concentration sits with heritage houses commanding aged inventory reserves; scale advantage sits with diversified spirits conglomerates distributing across multiple channels. The market structure consolidates around a handful of established producers with century-plus maturation stockpiles. Three archetypes dominate: vineyard-integrated houses controlling cru-specific supply, luxury group subsidiaries leveraging global distribution networks, and independent distilleries pursuing collector-direct relationships. Competitive moves center on cask finishing program expansion and controlled allocation to travel retail operators.
Within the heritage house tier, Hennessy, Rémy Martin, and Martell exemplify contrasting strategic positions. Hennessy represents scale-driven distribution dominance across multiple age tiers. Rémy Martin occupies a position anchored in Grande Champagne vineyard integration and extended aging commitments. Martell exemplifies aggressive travel retail allocation strategies targeting Asian duty-free corridors. These three houses collectively illustrate the competitive tension between terroir authenticity claims and channel control priorities that defines the market structure.
| Leading Market Players |
|---|
| Hennessy |
| Rémy Martin |
| Martell |
| Courvoisier |
| D'Ussé |
| Pierre Ferrand |
| Ferrand Cognac |
| Augier |
| Gautier |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp barge freight corridors shape working capital cycles for Limousin oak cooperage deliveries, concentrating cost leverage with Grande Champagne houses that negotiate volume commitments across distillation seasons while VS-tier producers absorb spot-market volatility in glass and cork procurement.
Pricing Analysis
Long-term offtake contracts between heritage houses and French cooperage suppliers anchor pricing stability for XO-tier inventory, while spot-market exposure dominates VS procurement where Ugni Blanc grape costs fluctuate with vintage conditions. Price differentiation separates estate-bottled Grande Champagne releases from bulk-blended alternatives through appellation tier and verified provenance documentation. Cost compression in the VS tier is intensifying because cocktail-forward bars in the United States negotiate volume rebates aggressively. Private collectors in Asian duty-free corridors show the least price sensitivity, absorbing allocated releases regardless of tariff-adjusted premiums.
Supply Chain Analysis
Ugni Blanc grape cultivation draws from the Charente and Charente-Maritime departments exclusively, with no alternative sourcing permitted under EU GI protections. French oak from Limousin and Tronçais forests, copper pot stills fabricated by specialized Charentais metalworkers, and glass bottles from domestic manufacturers constitute the core input trinity. Single-source vulnerability concentrates in master blender expertise, where generational transfer gaps threaten batch consistency. Distribution runs through controlled allocation to travel retail operators in China and South Korea, bypassing traditional wholesale margin stacking for premium tier releases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cyclical recovery in aged spirits inventory velocity is underway, driven by collector restocking in Asian duty-free corridors following pandemic-era depletion of mature stock reserves.
For Market Incumbents: Pre-empt private barrel program saturation by locking ultra-high-net-worth collectors into multi-year cask finishing commitments before competitor capacity expansion. Secure backward integration into Limousin oak forest management to hedge cooperage cost inflation. Channel control through direct-to-consumer platform investment defends margin capture against disintermediation by Asian auction houses. For New Entrants and Emerging Players: Pursue keg-format penetration in high-volume United States bars where labor cost reduction drives format experimentation. White-space concentrates in CSRD-aligned sustainability disclosure services for ESG-mandated institutional capital allocation. Target private client programs in Singapore and Hong Kong through blockchain-based provenance authentication as the go-to-market wedge. For Investors and Strategic Acquirers: Vineyard-integrated houses with century-plus aged stock reserves offer the most defensible acquisition profile for long-term viability assessment. Master blender succession planning depth serves as the critical inflection indicator for inventory quality trajectory. Cross-checking against Bureau National Interprofessionnel du Cognac export volume disclosures is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Cask Finishing Program Expansion | Captures aftermarket revenue from ultra-high-net-worth collectors seeking personalized eaux-de-vie maturation. |
| Blockchain Provenance Authentication | Combats counterfeiting in Shanghai and Hong Kong luxury retail through verified cru-to-bottle tracking. |
| CSRD-Aligned Sustainability Disclosure | Attracts ESG-mandated institutional capital through carbon footprint transparency in vineyard operations. |
| Controlled Duty-Free Allocation | Concentrates margin capture with producers who manage scarcity-driven releases to Incheon and Hainan operators. |
| Master Blender Succession Investment | Preserves organoleptic expertise for eaux-de-vie selection through structured apprenticeship pipeline development. |
Research Methodology
Operator-level perspectives from master blenders, cooperage suppliers, duty-free allocation managers, and Asian private client directors anchored the qualitative base for this analysis. Secondary validation drew from Bureau National Interprofessionnel du Cognac export statistics, EU GI registry filings, French customs excise records, and MFDS import clearance databases. Bottom-up inventory velocity modeling triangulated against top-down consumption surveys across the analysis window.
Scenario-bracketing framed volume and value projections across the modeling period, with segmentation dimensions spanning age classification tiers, end-user channel types, packaging format constraints, and regional regulatory clusters. CAGRs derived from historical inventory turnover ratios, vintage yield variability, and channel mix shift assumptions. Climate-adaptive viticulture adoption rates and REACH-compliant oak sourcing compliance timelines served as industry-specific forecast inputs.
Sensitivities concentrate around EU-UK spirits trade arrangement evolution, Asian import tariff negotiation outcomes, and interest rate cycle impacts on aged inventory carrying costs. Cross-checking against IWSR spirits consumption tracking data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Spirits Miniatures Market
Alcoholic Beverages
Middle East and Africa Fermented Drinks Market
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market
Alcoholic Beverages
Brazil Alcohol E-Commerce Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Beer Brewing Machine Market
Alcoholic Beverages
Liquor Flavored Ice Cream Market
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
Alcohol Gummies Market