
 Germany Wine Coolers Market | 2026-2036
Germany Wine Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Wine Coolers Market Insights
Premium dual-zone specification tiers is collapsing the gap between built-in and freestanding categories as German consumers prioritize precise temperature control for mixed wine portfolios. EuroCave leverages its heritage compressor engineering to sustain dominance in the built-in segment. Caso Design anchors its position through compact countertop specialization for urban apartments. Gaggenau competes on integrated kitchen aesthetics, extending its reach into high-end residential renovations.
Wine coolers are thermoelectric or compressor-driven refrigeration appliances engineered to maintain stable temperatures between 5°C and 18°C with humidity control, designed for optimal wine preservation and maturation. Freestanding units occupy the largest volume tier due to lower installation barriers, while built-in configurations command the strongest margin pools from kitchen renovation projects. Dual-zone technology leads growth as consumers segment red and white storage requirements within single appliances. Online Retail channels are gaining ground against Specialty Stores by offering expanded size and material configurations.
Germany's Ecodesign Directive and Energy Labelling Framework mandate minimum efficiency standards for refrigeration appliances, compressing demand toward inverter compressor models and away from thermoelectric alternatives. The KBA does not regulate this category, but Germany's Federal Environment Agency enforces refrigerant phase-down schedules under F-Gas Regulation alignment, pushing manufacturers toward R600a hydrocarbon transitions. Stakeholders must monitor whether pending EU right-to-repair mandates reshape warranty and component replacement economics for premium units.
Market Dynamics
Germany's Ecodesign Directive and Energy Labelling Framework compress demand toward inverter compressor architectures while thermoelectric alternatives face obsolescence. This regulatory pressure intersects with southern German metropolitan demand concentration to reshape competitive positioning across built-in and freestanding categories.
Growth Catalysts
- F-Gas Regulation alignment:Germany's Federal Environment Agency enforces refrigerant phase-down schedules, accelerating manufacturer transitions to R600a hydrocarbon systems that improve efficiency ratings.
- Dual-zone specification tiers:Premium residential collectors in Berlin and Munich expand purchases of units enabling precise temperature segmentation for mixed wine portfolios.
- Kitchen renovation cycles:High-end residential renovations in southern German corridors drive built-in configuration demand with integrated aesthetics requirements.
Market Restraints
- Copper and aluminum input volatility:Compressor manufacturing faces raw material cost pressure that constrains margin expansion for mid-tier manufacturers.
- Thermoelectric technical ceiling:Peltier cooling systems hit thermal efficiency limits above 100-liter capacities, blocking adoption in collector-grade segments.
- Specialty Store channel concentration:Dependence on kitchen retail networks in Bavaria and Baden-Württemberg creates geographic demand vulnerability.
Strategic Opportunities
- Online Retail channel expansion:Digital platforms offering expanded size and material configurations capture share from traditional kitchen showrooms.
- Right-to-repair mandate preparation:Pending EU legislation reshapes warranty economics and component replacement service models for premium units.
- Compact countertop specialization:Urban apartment segments in Frankfurt and Hamburg drive demand for sub-50-liter units with minimal installation requirements.
Industry Challenges
- Hydrocarbon handling certification:R600a transitions require technician retraining and facility upgrades that compress installation network capacity.
- Dual-zone calibration complexity:Precision temperature control systems demand specialized quality assurance protocols that extend production cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Wine Coolers Market |
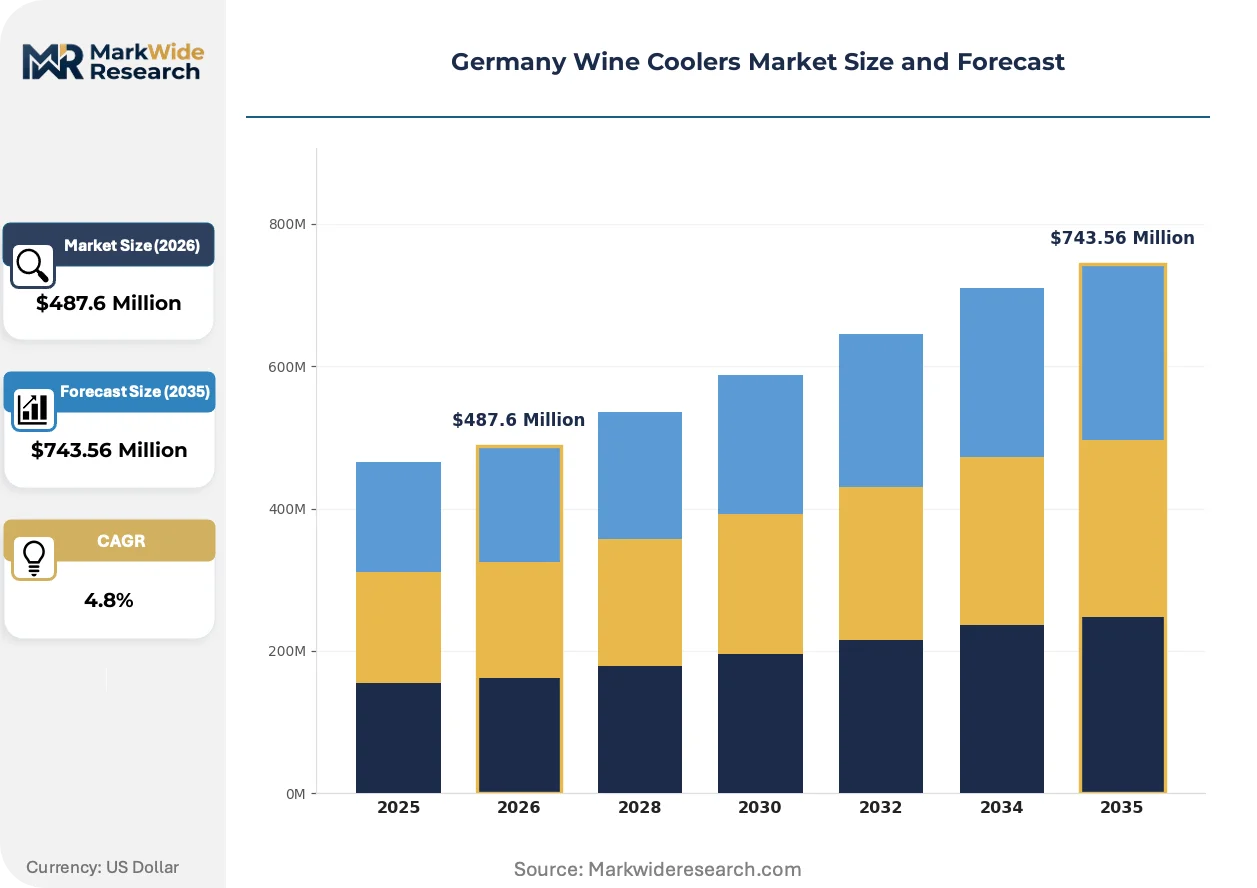
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Built-in, Countertop, Dual Zone Size: Small, Medium, Large, Extra Large Material: Stainless Steel, Glass, Wood, Plastic Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Others |
| Companies Covered | Danby Appliances, Caso Design, Cavecool, ArteVino, EuroCave, Gaggenau, La Sommeliere, Coolkombinat, Electrolux, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Wine Coolers Market Trends and Innovations
Compressor engineering advances and regulatory efficiency mandates are restructuring Germany's wine cooler competitive landscape. Three distinct forces reshape product architecture, compliance requirements, and channel economics.
Inverter compressor technology with variable-speed drives optimizes energy consumption across partial-load conditions. Premium residential collectors in Munich and Stuttgart adopt these systems for cellar-grade installations. Thermoelectric cooling is supplanting older fixed-speed compressor models in sub-75-liter segments as efficiency thresholds tighten.
Germany's Ecodesign Directive mandates minimum efficiency standards for refrigeration appliances sold domestically. This compresses demand toward A+++ rated units and accelerates phase-out of thermoelectric alternatives in larger capacities. Manufacturers redesign heat exchanger geometries and insulation specifications to maintain compliance.
Specialty kitchen retailers face disintermediation pressure from direct-to-consumer digital platforms. Online channels in Berlin and Hamburg offer expanded stainless steel and glass door configurations with shorter fulfillment windows. Urban apartment buyers increasingly bypass showroom consultations for specification-driven digital purchases.
Germany Wine Coolers Market Segmentation
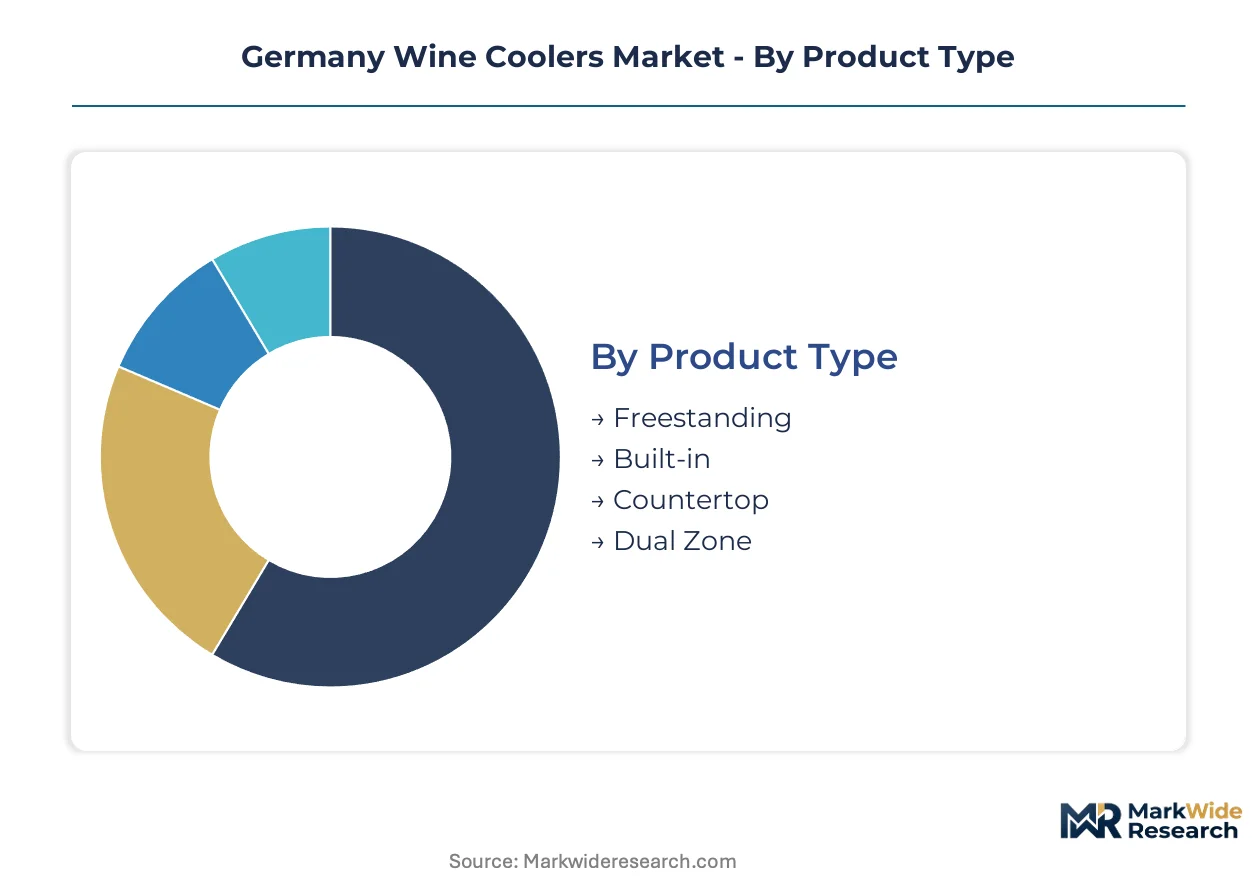
Germany's wine cooler market fragments across four distinct dimensions that interact with regulatory efficiency mandates and regional consumption patterns. Each segmentation layer reveals divergent margin structures and channel economics that manufacturers must navigate under Ecodesign Directive compliance requirements.
Product Type:
Germany's Ecodesign Directive and Energy Labelling Framework create divergent compliance pathways across cooling architectures, compressing demand toward compressor-driven configurations in larger capacities while preserving niche thermoelectric viability in compact formats.
- Freestanding:These floor-standing units with rear ventilation systems dominate volume throughput due to minimal installation requirements and flexible placement options. Southern German metropolitan corridors in Bavaria and Baden-Württemberg concentrate demand as residential collectors prioritize capacity scalability without kitchen renovation commitments.
- Built-in:Front-ventilated appliances engineered for seamless cabinetry integration command the strongest margin pools from high-end kitchen renovation cycles. Berlin and Munich renovation markets drive specification intensity as integrated aesthetics requirements displace freestanding alternatives in premium residential segments.
- Countertop:Sub-20-liter compact units target urban apartment constraints with Peltier cooling systems that avoid compressor noise profiles.
- Dual Zone:Independent temperature compartments enabling simultaneous red and white storage represent the specification tier reshaping competitive positioning across all product formats.
Freestanding handles the majority of throughput; Dual Zone is gaining share fastest as collectors segment mixed portfolios within single appliances.
Size:
Capacity tiers correlate directly with customer archetypes and installation complexity, creating distinct competitive arenas that thermoelectric technology cannot penetrate above threshold volumes.
- Small:Under-50-liter capacities serve countertop and under-counter placement scenarios in Frankfurt and Hamburg urban apartments where space constraints override collection scale ambitions.
- Medium:50-150 liter ranges balance capacity expansion with residential footprint limitations, capturing the core enthusiast segment in Stuttgart and Cologne metropolitan zones.
- Large:Collector-grade installations exceeding 150 liters require inverter compressor architectures to maintain temperature stability across partial-load conditions during seasonal inventory fluctuations.
- Extra Large:Commercial-scale units above 300 liters serve restaurant and hospitality procurement channels with heavy-duty compressor cycling and reinforced insulation specifications.
Medium capacities anchor the revenue base; Large formats are expanding most quickly as residential collectors upgrade from enthusiast to cellar-grade storage.
Material:
Surface finish selection intersects with kitchen design trends and durability requirements, creating tiered pricing structures that stainless steel dominates at premium levels.
- Stainless Steel:Brushed and polished finishes command specification preference in integrated kitchen renovations across Munich and Düsseldorf high-end residential markets, with fingerprint-resistant coatings adding marginal cost premiums.
- Glass:UV-protected door panels enable collection display while blocking light degradation, appealing to design-conscious buyers in Berlin's contemporary housing stock.
- Wood:Veneer and solid wood enclosures serve traditional kitchen aesthetics in rural Bavarian and Black Forest renovation projects where cabinetry matching overrides modern minimalism.
- Plastic:ABS and polycarbonate housings compress manufacturing costs for entry-tier countertop units targeting price-sensitive first-time buyers.
Stainless Steel generates the highest margin contribution; Glass is climbing the fastest as display functionality gains specification weight in urban markets.
Distribution Channel:
Channel economics are restructuring as digital platforms disintermediate traditional kitchen retail networks, compressing fulfillment windows while expanding configuration variety.
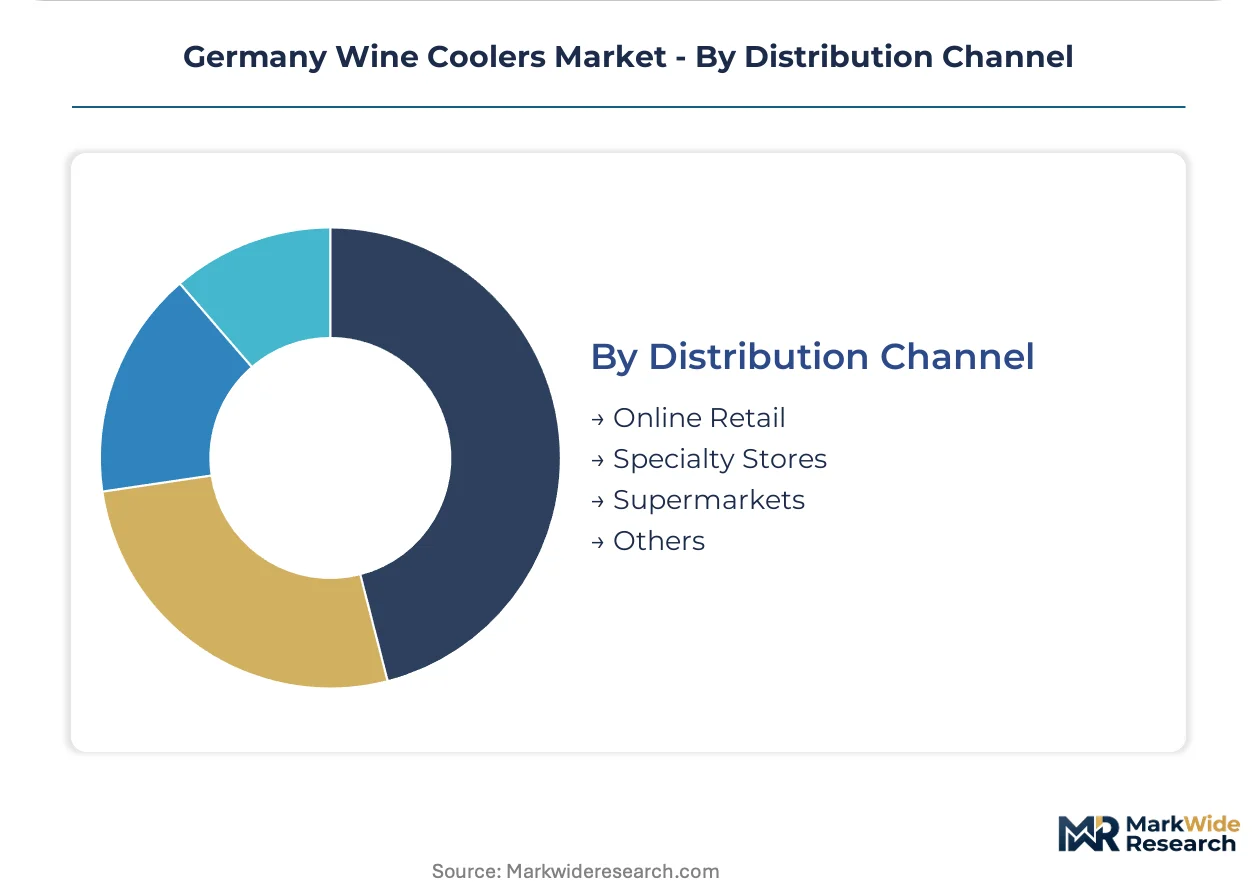
- Online Retail:Direct-to-consumer platforms in Berlin and Hamburg offer expanded size and material configurations with specification-driven purchasing that bypasses showroom consultations, capturing share fastest from traditional channels.
- Specialty Stores:Kitchen and appliance showrooms in Bavaria and Baden-Württemberg maintain relevance for built-in configuration sales requiring installation coordination and aesthetic consultation.
- Supermarkets:Mass retail placement targets impulse and gift purchases for compact countertop formats with simplified feature sets and aggressive promotional pricing.
- Others:Direct contractor supply and hospitality procurement channels serve commercial-scale installations with volume pricing and extended warranty terms.
Specialty Stores retain the built-in installation anchor; Online Retail is expanding most quickly as urban buyers prioritize specification breadth over tactile evaluation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German wine cooler exports flow primarily toward neighboring European markets, with Austria, Switzerland, and the Netherlands serving as key destination corridors for premium built-in configurations manufactured in southern industrial clusters.
Bavaria
Munich and Nuremberg metropolitan zones anchor collector-grade demand for dual-zone units exceeding 150 liters. The Federal Environment Agency enforces F-Gas Regulation alignment, accelerating transitions to R600a hydrocarbon refrigerants among local manufacturers. Kitchen renovation cycles in Bavaria's high-end residential corridors drive built-in specification intensity.
Baden-Württemberg
Stuttgart's affluent suburbs concentrate enthusiast-tier purchases of medium-capacity freestanding models. Germany's Ecodesign Directive mandates A+++ efficiency ratings, compressing demand toward inverter compressor architectures. The Black Forest renovation belt sustains demand for wood-finish integrated units matching traditional cabinetry aesthetics.
North Rhine-Westphalia
Düsseldorf and Cologne urban cores generate specification-driven demand for glass-door display units in contemporary housing stock. Energy Labelling Framework compliance requirements reshape procurement criteria across specialty retail networks. The Ruhr industrial legacy supports compressor component supply chains serving domestic assembly operations.
Berlin-Brandenburg
Berlin's dense apartment market drives compact countertop adoption for sub-50-liter Peltier-cooled configurations. Pending EU right-to-repair mandates reshape warranty economics for premium units sold through digital channels. The capital's online retail penetration exceeds national averages, accelerating showroom disintermediation.
Hamburg
Port city logistics advantages position Hamburg as a distribution hub for imported premium brands serving northern German markets. Federal Environment Agency refrigerant phase-down schedules compress thermoelectric viability above threshold capacities. Urban apartment constraints in Hamburg's core sustain demand for minimal-installation formats.
Germany Wine Coolers Market Competitive Landscape
Listed appliance conglomerates compete with private specialists across compressor engineering and kitchen integration capabilities. Market structure tilts toward consolidation at the premium tier, with heritage brands commanding specification loyalty in built-in segments. Three archetypes dominate: European heritage compressor engineers, compact-format specialists, and integrated-kitchen aesthetics providers. Competitive moves center on hydrocarbon refrigerant transitions and direct-to-consumer channel expansion.
Within the heritage engineering tier, EuroCave exemplifies compressor-technology lineage, while Gaggenau occupies a position anchored in integrated-kitchen renovation channels. Caso Design represents the compact-format specialist archetype targeting urban apartment constraints. These three players illustrate how divergent positioning vectors—technical heritage, aesthetic integration, and spatial efficiency—sustain parallel competitive ecosystems without direct feature-for-feature confrontation.
| Leading Market Players |
|---|
| Danby Appliances |
| Caso Design |
| Cavecool |
| ArteVino |
| EuroCave |
| Gaggenau |
| La Sommeliere |
| Coolkombinat |
| Electrolux |
| Others |
Pricing and Supply Chain Analysis
R600a hydrocarbon refrigerant substitution for legacy HFC systems simultaneously compresses manufacturing cost structures and redraws procurement geography toward compressor suppliers with flammable-gas handling certifications. This input transition feeds into pricing power concentration among inverter-engineering specialists while squeezing margin pools for thermoelectric assemblers.
Pricing Analysis
Current-generation inverter compressor units command substantial premiums over fixed-speed legacy models, while next-generation variable-speed drives with AI load-balancing sit at the apex of the pricing pyramid. Pricing stratifies across premium, standard, and economy tiers based on A+++ energy certification status and dual-zone calibration precision. Cost compression in the thermoelectric tier is intensifying because Ecodesign Directive efficiency thresholds render Peltier systems uncompetitive above 75-liter capacities. First-time urban apartment buyers in Berlin and Hamburg exhibit highest price sensitivity, whereas collector-grade purchasers in Munich demonstrate minimal elasticity for cellar-grade specifications.
Supply Chain Analysis
Strategic stockpile preferences dominate among compressor manufacturers buffering against copper and aluminum price volatility, while just-in-time coordination prevails downstream for finished goods distribution. Component sourcing draws from China for electronic control modules, Italy for precision thermostats, and Poland for stamped steel enclosures. Single-source vulnerability concentrates in inverter drive controller chips from Taiwanese foundries. Distribution runs through specialty kitchen retailers in Bavaria and Baden-Württemberg for built-in configurations, with direct-to-consumer platforms capturing freestanding volume in northern metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proficiency in hydrocarbon refrigerant system engineering represents the decisive capability gap separating viable competitors from obsolescent assemblers. Manufacturers lacking certified R600a handling infrastructure face exclusion from premium tier qualification.
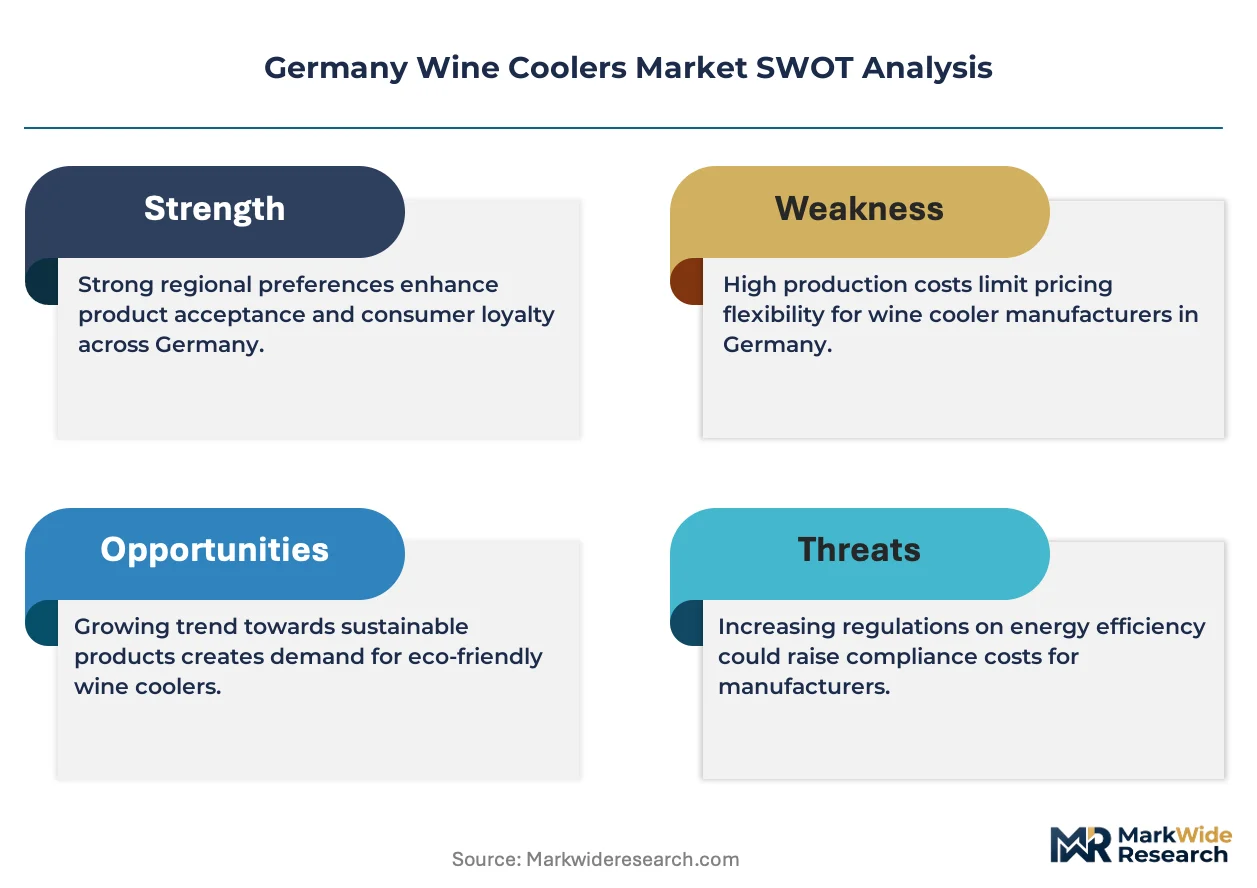
For Market Incumbents: Shield margin pools in the built-in segment through captive compressor engineering capabilities and exclusive distribution lock-ups with southern German kitchen renovation contractors. Thermoelectric specialist entrants from Asia threaten the sub-75-liter tier with price-aggressive Peltier alternatives. Vertical integration into inverter drive controller design preserves specification autonomy against semiconductor supply constraints. For New Entrants and Emerging Players: CE marking fast-track for R600a-compliant compact units opens immediate channel access without heritage brand discounting requirements. The countertop segment in Frankfurt and Hamburg offers lowest penetration barriers given minimal installation coordination and specification-driven digital purchasing behavior. Direct-to-consumer platform partnerships with Berlin-based online retailers bypass showroom capital requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European kitchen appliance platforms seeking refrigeration capability bolt-ons. Five-to-ten year viability hinges on hydrocarbon transition completion and right-to-repair mandate compliance infrastructure. Monitor EU F-Gas Regulation phase-down acceleration as the critical inflection signal for thermoelectric obsolescence timing.| Strategic Initiative | Industry Significance |
|---|---|
| R600a Hydrocarbon Transition | Federal Environment Agency enforcement accelerates refrigerant system redesign across domestic manufacturing facilities. |
| Dual-Zone Calibration Investment | Precise temperature segmentation capabilities capture collector-grade demand in Munich and Stuttgart renovation markets. |
| Direct-to-Consumer Channel Expansion | Berlin and Hamburg digital platforms disintermediate specialty kitchen retailers with shortened fulfillment windows. |
| Inverter Compressor Backward Integration | Captive variable-speed drive production insulates against Taiwanese semiconductor supply bottlenecks. |
| Right-to-Repair Compliance Infrastructure | Pending EU mandates reshape warranty economics and component replacement service models for premium units. |
Research Methodology
A spread of perspectives from compressor engineering directors, specialty kitchen retail buyers, Federal Environment Agency regulatory officers, and residential collector focus groups converged on the working assumptions underpinning demand segmentation. Primary fieldwork combined structured interviews with aftermarket service technicians and channel inventory managers. Secondary validation drew from Umweltbundesamt enforcement bulletins, Bundesamt für Wirtschaft und Ausfuhrkontrolle trade flow data, EU Ecodesign Directive compliance registries, and manufacturer technical documentation. Bottom-up capacity utilization analysis and top-down expenditure flow modeling were cross-referenced for triangulation.
Segmentation dimensions modeled include cooling architecture type, capacity tier, surface material finish, and distribution channel format across the projection horizon. CAGRs were derived from installed base growth rates, replacement cycle compression, and efficiency upgrade propensity indices. Forecast inputs incorporated kitchen renovation cycle timing from German construction permit data and online retail penetration trajectories specific to northern metropolitan corridors.
The analysis sits within stated boundaries; outcomes outside sustained Ecodesign Directive enforcement stringency or accelerated F-Gas phase-down schedules would require recalibration. Forecasts reflect documented assumptions regarding copper price stability and semiconductor supply normalization. Revision becomes warranted when hydrocarbon handling certification backlog crosses thresholds that constrain installation network capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Ethanol Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Champagne Market
Alcoholic Beverages
Cider and Perry Market
Alcoholic Beverages
France Alcohol E-Commerce Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Europe Craft Spirits Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Europe Wine Coolers Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
Asia-Pacific Wine Market
Alcoholic Beverages
Ready to Serve Cocktails Market
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Moscato Wine Market