
 Global Hard Seltzers Market | 2026-2036
Global Hard Seltzers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hard Seltzers Market Foresight
Cane sugar is realigning product economics as malt-based formulations lose cost advantage across production networks. Mark Anthony Brands International leverages its dedicated hard seltzer infrastructure to sustain volume leadership in North American retail channels. Boston Beer Company anchors its competitive stance through R&D intensity in flavor innovation systems. Anheuser-Busch InBev competes via manufacturing scale and existing distributor relationships in mainstream beverage markets.
Hard seltzers constitute carbonated water-based beverages infused with alcohol derived from fermented cane sugar, malted barley, or distilled spirits, typically containing 4-6% alcohol by volume with caloric content below 100 calories per serving. The category serves consumers seeking sessionable alternatives to beer and cocktails in casual social occasions. Alcoholic hard seltzers dominate current revenue pools while low-calorie and gluten-free variants capture the fastest expansion in health-conscious segments. Cans anchor packaging economics through portability and recycling infrastructure compatibility, though multipacks generate disproportionate margin contribution in club and e-commerce channels.
The FDA governs alcohol beverage labeling and health claim permissibility, while TTB regulations dictate formula approval and tax classification that directly affect production cost structures. EFSA and national regulators across Germany, the United Kingdom, and France impose varying additive restrictions and marketing limitations that fragment European go-to-market requirements. Stakeholders must monitor evolving low-alcohol taxation frameworks and sugar-content thresholds as these policy levers increasingly determine regional profitability and portfolio prioritization.
Market Dynamics
Cane sugar fermentation is displacing malt-based production economics across hard seltzer manufacturing networks, compressing input costs while triggering TTB tax reclassification debates that reshape regional profit pools.
Growth Catalysts
- Low-alcohol taxation frameworks:Brazil and select European jurisdictions are recalibrating excise structures to favor sub-6% ABV beverages, directly lowering shelf-price premiums versus beer and spirits.
- Gluten-free certification demand:Health-conscious consumers in recreational and social settings are pivoting toward certified gluten-free alternatives, pulling cane sugar-derived formulations ahead of malt-based competitors.
- Recycling infrastructure maturation:Advanced aluminum can recovery systems in Germany and France are reducing packaging compliance costs while supporting sustainability claims in club and e-commerce channels.
Market Restraints
- Cane sugar price volatility:Brazilian harvest fluctuations and biofuel diversion pressures are injecting input cost uncertainty into fermentation-based production models.
- EFSA additive restrictions:Varying permitted flavor compound thresholds across Germany, France, and the United Kingdom are fragmenting European formulation requirements and inflating SKU complexity.
- Ready-to-drink cocktails:Premium canned cocktail formats are capturing overlapping occasion-based consumption moments, particularly among urban young adult demographics.
Strategic Opportunities
- India's emerging urban centers:Underpenetrated metro markets present white space for sessionable, low-calorie alcoholic beverages as licensed retail expands.
- E-commerce subscription models:Direct-to-consumer multipack delivery is bypassing traditional distributor markups while capturing recurring revenue pools.
- FSSAI clarity on flavored malt beverages:Anticipated regulatory guidance on alcohol-adjacent product classifications may unlock formal market entry for hard seltzer variants.
Industry Challenges
- Flavor chemist scarcity:Formulation expertise spanning alcohol stability, carbonation retention, and clean-label compliance remains concentrated among a narrow specialist pool.
- TTB formula approval timelines:Multi-month federal review cycles for novel flavor systems are compressing seasonal product launch windows.
- Cross-border labeling harmonization:Divergent health claim permissibility between FDA and EFSA frameworks is forcing redundant packaging runs for global portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hard Seltzers Market |
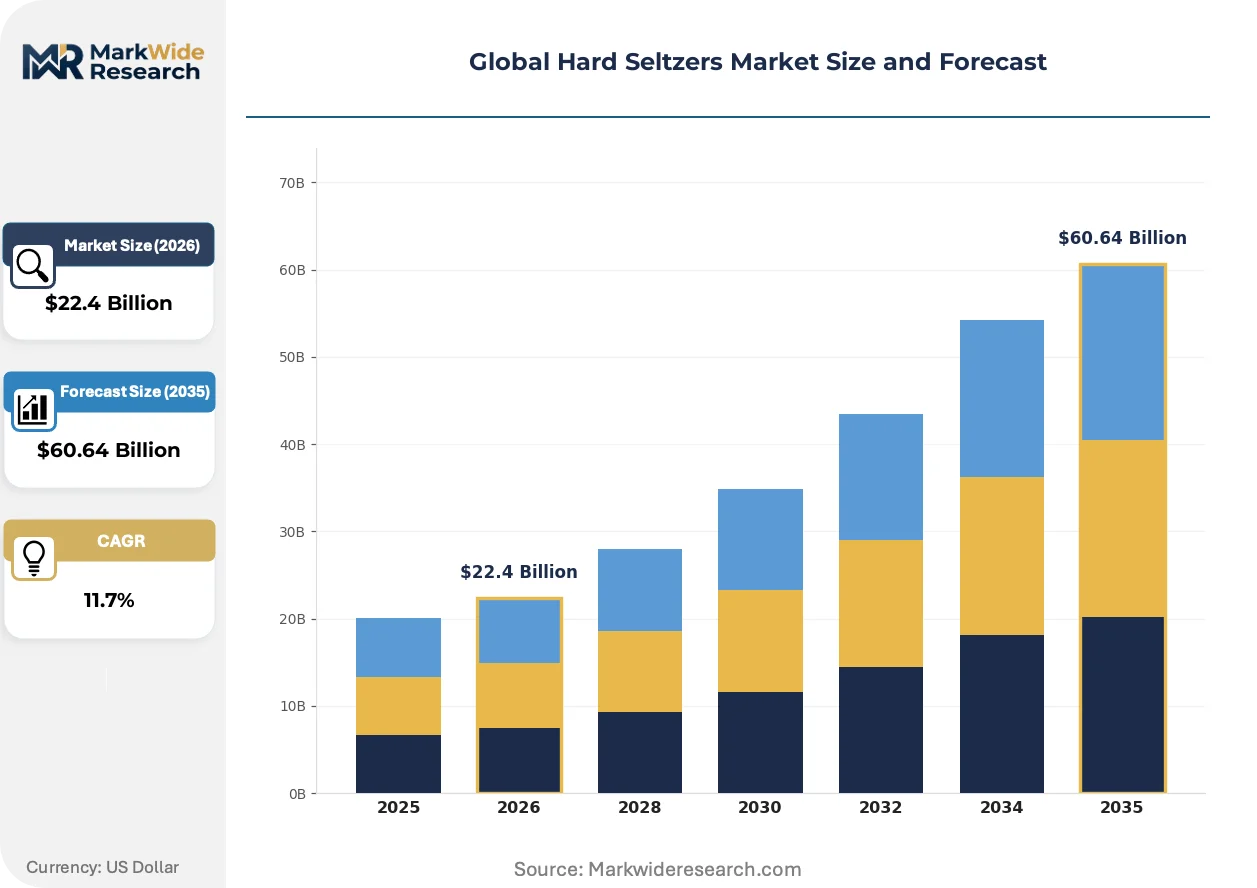
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $60.64 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcoholic Hard Seltzers, Non-Alcoholic Flavored Seltzers, Low-Calorie Seltzers, Gluten-Free Seltzers, Organic Hard Seltzers Flavor Profile: Citrus, Tropical, Berry, Mint, Spiced, Herbal Packaging Format: Cans, Bottles, Multipacks, Kegs, PET Bottles Distribution Channel: Supermarkets & Hypermarkets, Convenience Stores, Online Retailers, Liquor Stores, On-Trade Outlets |
| Companies Covered | Mark Anthony Brands International, Boston Beer Company, Anheuser-Busch InBev, Molson Coors Beverage Company, The Coca-Cola Company, Diageo plc, Constellation Brands, Inc., Heineken N.V., Carlsberg Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hard Seltzers Market Shifts & Advancements
Carbonation engineering and fermentation science are converging to redefine product stability standards, while regulatory clarity and channel fragmentation are simultaneously opening and complicating market entry pathways.
Continuous fermentation technology is consolidating production economics for cane sugar-derived alcohol bases. Mid-scale manufacturers in Texas and São Paulo are adopting these systems to match the unit-cost profiles of legacy malt facilities. The technology is consolidating competitive advantage around dedicated hard seltzer infrastructure versus repurposed beer brewing assets.
REACH additive disclosure requirements are forcing reformulation of natural flavor extracts used in European-bound products. EFSA's tightened scrutiny on uncharacterized flavor compounds is extending product development timelines by six to twelve months. German and French producers are responding by accelerating partnerships with certified clean-label flavor houses.
Young adult buyers are fragmenting their alcohol purchases across multiple channels rather than consolidating with single retailers. Convenience store grab-and-go occasions are separating from planned club-store stock-up trips, which are themselves diverging from curated e-commerce discovery. This behavioral split is most pronounced in US coastal metros and São Paulo's urban core, where subscription services are capturing planning-oriented consumers.
Global Hard Seltzers Market Segmentation
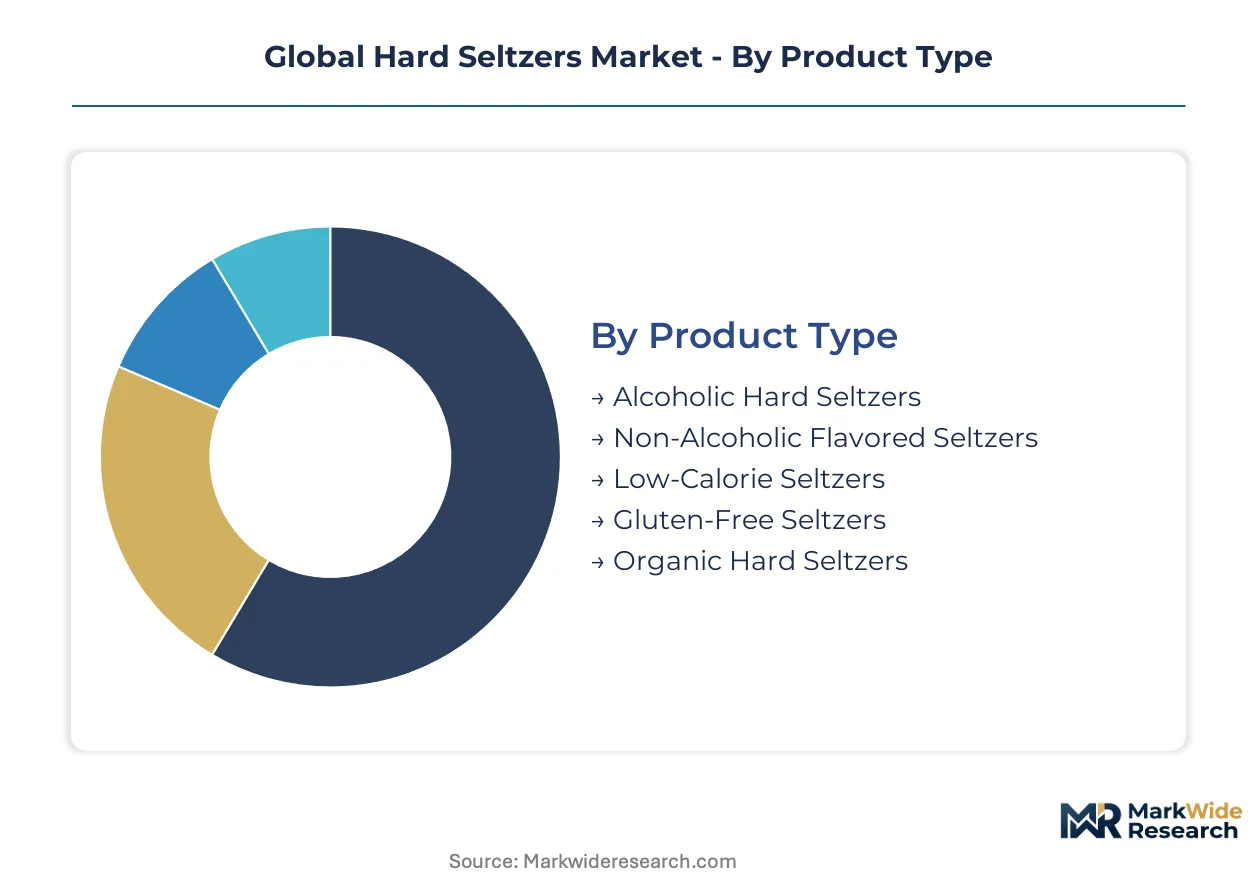
Hard seltzer segmentation reflects divergent consumer priorities across health positioning, occasion-based consumption, and channel accessibility. Manufacturers configure portfolios around alcohol content thresholds, caloric density, and certification claims to capture distinct buyer cohorts without cannibalizing core revenue streams.
Product Type:
Buyers in this category separate by alcohol tolerance, dietary restriction severity, and willingness to pay premium for certified ingredients.
- Alcoholic Hard Seltzers:Carbonated water bases carry 4-6% ABV from fermented cane sugar or malted barley. United States convenience retail and Brazil's licensed on-trade outlets concentrate demand as young adult consumers prioritize sessionable alternatives to beer.
- Gluten-Free Seltzers:Cane sugar fermentation eliminates barley proteins, achieving sub-20ppm gluten thresholds for certified labeling. Health-conscious segments in Germany and France are pulling these formulations ahead of malt-based competitors as coeliac awareness expands.
- Non-Alcoholic Flavored Seltzers:Zero-ABV carbonated waters target designated drivers and wellness-focused buyers seeking social ritual without intoxication.
- Low-Calorie Seltzers:Sub-100 calorie per serving formulations appeal to weight-management consumers replacing sugary mixers.
- Organic Hard Seltzers:USDA Organic or EU Organic certified inputs command shelf price premiums in natural grocery channels.
Volume sits with Alcoholic Hard Seltzers; growth tilts toward Gluten-Free Seltzers.
Flavor Profile:
Flavor selection signals occasion type and social context, with buyers gravitating toward familiar fruit categories for casual settings and experimental profiles for curated discovery.
- Citrus:Lemon, lime, and grapefruit variants dominate baseline portfolio construction for their broad palate compatibility and mixing versatility.
- Berry:Raspberry, black cherry, and mixed berry formulations capture repeat purchase loyalty in United States club store multipacks.
- Tropical:Mango, pineapple, and coconut profiles target summer seasonal programming and beach occasion marketing.
- Mint:Refreshing botanical notes serve as palate cleansers and differentiate from mainstream fruit saturation.
- Spiced:Cinnamon, ginger, and seasonal spice limited releases drive scarcity-based purchase urgency.
- Herbal:Lavender, basil, and rosemary infusions attract craft cocktail crossover consumers seeking complexity.
Revenue concentrates in Citrus; Berry is expanding most quickly in multipack formats.
Packaging Format:
Format choice tracks consumption velocity, storage constraints, and recycling infrastructure maturity in target markets.
- Cans:Aluminum 12oz and 16oz formats anchor portability and chilled rapid consumption. Germany and France's advanced recovery systems are reducing compliance costs while supporting sustainability claims.
- Multipacks:6-pack, 12-pack, and variety pack configurations generate disproportionate margin contribution in club and e-commerce channels through planned stock-up behavior.
- Bottles:Glass formats serve premium positioning and on-trade presentation requirements.
- PET Bottles:Lightweight plastic targets markets with limited aluminum recycling or price-sensitive mass retail.
- Kegs:Draft dispensing systems capture high-volume on-trade accounts and event catering.
Shipment volume clusters in Cans; margin expansion tilts toward Multipacks.
Distribution Channel:
Channel selection determines price realization, brand control, and consumer data access, with manufacturers balancing margin protection against volume scale.
- Supermarkets & Hypermarkets:Mass retail placement drives brand awareness and trial conversion through endcap displays and seasonal promotions. São Paulo's urban retail expansion is concentrating volume in Brazilian hypermarket chains.
- Online Retailers:Direct-to-consumer and third-party platforms enable subscription models and bypass traditional distributor markups. United States coastal metros show pronounced channel fragmentation between planned e-commerce discovery and impulse convenience purchasing.
- Convenience Stores:Grab-and-go chilled single-serve occasions dominate immediate consumption moments.
- Liquor Stores:Licensed alcohol specialists provide educated staff recommendation and premium assortment depth.
- On-Trade Outlets:Bars, restaurants, and entertainment venues deliver brand experience and occasion-based trial.
Transaction volume flows through Supermarkets & Hypermarkets; Online Retailers show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young adult consumers in the United States, Brazil, and Germany account for the majority of hard seltzer volume, with regulatory frameworks and retail infrastructure determining regional profitability trajectories.
United States
Sessionable alcohol alternatives dominate convenience retail and club stock-up occasions as young adults fragment purchases across channels. The FDA governs labeling while the TTB dictates formula approval timelines that compress seasonal launch windows. Texas and California production clusters are adopting continuous fermentation systems to match cane sugar-derived cost structures.
Brazil
Licensed on-trade expansion in São Paulo and Rio de Janeiro metro areas is pulling sessionable beverage demand. Recalibrating excise structures favor sub-6% ABV beverages, lowering shelf-price premiums versus beer. São Paulo's urban core is seeing pronounced channel fragmentation between impulse convenience purchasing and planned e-commerce discovery.
Germany
Health-conscious segments are pivoting toward certified gluten-free alternatives as coeliac awareness expands. EFSA additive restrictions and REACH disclosure requirements are extending product development timelines by six to twelve months. Bavaria and North Rhine-Westphalia production networks are accelerating partnerships with certified clean-label flavor houses to meet tightened scrutiny.
France
Advanced aluminum can recovery systems are reducing packaging compliance costs while supporting sustainability claims in club channels. National regulators impose varying additive restrictions that fragment European go-to-market requirements. Paris and Lyon metropolitan retail corridors are concentrating demand for low-calorie variants in hypermarket chains.
United Kingdom
Multipack configurations generate disproportionate margin contribution in club and e-commerce channels through planned stock-up behavior. Divergent health claim permissibility between FDA and EFSA frameworks is forcing redundant packaging runs for global portfolios. London and Southeast England distribution hubs are capturing recurring revenue pools through subscription service models.
Global Hard Seltzers Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers retrofit brewing assets and build dedicated hard seltzer infrastructure. The vendor base clusters around three strategic archetypes: beverage conglomerates with existing distributor relationships, craft-scale specialists with flavor innovation intensity, and private-label manufacturers serving retail-owned brands. M&A activity and vertical integration into fermentation technology represent the dominant competitive moves as firms seek to compress unit costs and secure input supply.
Among North American specialists, Mark Anthony Brands International and Boston Beer Company exemplify divergent infrastructure strategies—dedicated facilities versus R&D-intensive flavor systems. Anheuser-Busch InBev represents the scale-driven multinational archetype, leveraging manufacturing breadth and distributor networks across mainstream beverage markets.
| Leading Market Players |
|---|
| Mark Anthony Brands International |
| Boston Beer Company |
| Anheuser-Busch InBev |
| Molson Coors Beverage Company |
| The Coca-Cola Company |
| Diageo plc |
| Constellation Brands, Inc. |
| Heineken N.V. |
| Carlsberg Group |
| Others |
Supply & Pricing Matrix
Flavor chemist concentration in Texas and São Paulo production clusters compresses labor-cost differentials into premium-mid-economy pricing spreads across cane sugar and malt-based formulation tiers.
Pricing Analysis
Volume sits with mass-market multipacks while margin expansion tilts toward premium certified variants. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified inputs from conventional cane sugar bases from malt-based economy lines. Price differentiation hinges on gluten-free certification and clean-label flavor house partnerships. Pricing pressure stems from Brazilian harvest volatility feeding into fermentation input costs, with club-channel buyers showing highest price sensitivity versus e-commerce subscribers.
Supply Chain Analysis
Cane sugar supply rests on Brazilian agricultural networks and Indian processing capacity, with aluminum sheet feeding from Chinese and German smelters. Fermentation bases, natural flavor extracts, and recyclable aluminum cans constitute the critical input trinity. Single-source vulnerability concentrates in Brazilian sucrose supply exposed to biofuel diversion mandates. Distribution runs through Anheuser-Busch InBev and Molson Coors distributor networks anchored in mainstream beverage retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as players pursue captive supply of fermentation capacity to escape malt-based cost disadvantages.
For Market Incumbents: Acquire continuous fermentation systems in Texas and São Paulo to lock in cane sugar-derived unit economics ahead of TTB tax reclassification debates. Secure partnerships with certified clean-label flavor houses in Germany and France to deflect EFSA additive restriction compliance costs. Capacity addition in dedicated hard seltzer infrastructure—not repurposed beer assets—anchors margin defense against Boston Beer Company's R&D intensity. For New Entrants and Emerging Players: FSSAI guidance anticipation in India opens a window for early-mover positioning in licensed retail expansion across Mumbai and Bangalore metro corridors. Target gluten-free certification gaps in German and French health-conscious segments through direct-to-consumer subscription models. White space sits with organic hard seltzer variants in natural grocery channels where USDA and EU Organic premiums sustain shelf-price separation. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale specialists possessing dedicated fermentation infrastructure given cane sugar displacement of malt-based economics. Long-term viability over the next decade hinges on regulatory clarity in low-alcohol taxation frameworks and additive disclosure requirements. The inflection signal to watch is TTB formula approval timeline compression enabling seasonal launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Capacity Buildout | Texas and São Paulo facilities match legacy malt unit-cost profiles through cane sugar-derived alcohol bases. |
| Clean-Label Flavor House Partnership | German and French producers accelerate EFSA-compliant formulation to bypass REACH disclosure delays. |
| E-Commerce Subscription Model Launch | Direct-to-consumer multipack delivery captures recurring revenue pools in US coastal metros and São Paulo. |
| Gluten-Free Certification Investment | Coeliac awareness expansion in Germany and France pulls cane sugar formulations ahead of malt competitors. |
| Recycling Infrastructure Alignment | German and French aluminum recovery systems reduce packaging compliance costs for club-channel sustainability claims. |
Research Methodology
Trade publications, customs records, and TTB formula approval databases formed the secondary backbone, supplemented by primary interviews with fermentation technology suppliers, flavor chemists, beverage category buyers at club retailers, and regulatory affairs specialists at multinational alcohol conglomerates. Bottom-up volume estimates triangulated against top-down excise revenue data across the United States, Brazil, Germany, France, and the United Kingdom.
Historical trendline analysis tracked continuous fermentation adoption rates and cane sugar price volatility patterns across the analysis window. Segmentation dimensions modeled include product type, flavor profile, packaging format, and distribution channel, with regional regulatory clusters capturing FDA, TTB, EFSA, and FSSAI framework variations. CAGRs derived from alcohol volume displacement trends and health-conscious segment expansion assumptions.
The model assumes a particular technology adoption path; alternative pathways for continuous fermentation scale-up would alter the outlook. Forecasts reflect assumptions on low-alcohol taxation framework evolution and Brazilian harvest stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Oak Barrel Alternatives Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
Cigar Market
Alcoholic Beverages
Dark Spirits Market
Alcoholic Beverages
Fermented Beverages Market
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
United States Tequila Market
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Malt Beverages Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
Gluten-Free Beer Market
Alcoholic Beverages
GCC Beer Market
Alcoholic Beverages
Chocolate Liqueur Market