
 Rose Wine Market | 2026-2036
Rose Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Rose Wine Market Outlook
Natural cork closures are rebalancing toward technical cork and screw cap alternatives as producers manage supply volatility and taint risk. Treasury Wine Estates leverages vertical integration across Australian and Californian vineyards to secure consistent Grenache supply. Moët Hennessy anchors its premium positioning through controlled distribution in European duty-free channels. E. & J. Gallo Winery dominates mass-market retail placement with volume-scaled Central Coast sourcing.
Rosé wine is a pink-hued still or sparkling wine produced through limited skin contact of red grape varieties, typically hours to days, yielding color intensity measured at 4-12 mg/L anthocyanin content and primary commercial purpose as a chilled, food-versatile beverage. Dry Rosé leads volume share across European and North American markets, while Sparkling Rosé generates disproportionate margin concentration in on-premise and celebratory segments. Glass Bottle packaging maintains structural dominance in premium tiers, though Boxed Wine extends reach in casual outdoor and poolside consumption occasions.
The European Union's EFSA wine labeling directives and Appellation d'Origine Contrôlée standards shape product formulation, geographic sourcing claims, and export market access protocols. The US TTB and FDA exercise joint oversight on alcohol content disclosure, sulfite labeling, and import certificate requirements. Stakeholders must monitor evolving low- and no-alcohol regulatory thresholds as reformulation investments alter competitive positioning across core consumption demographics.
Market Dynamics
Provence's Appellation d'Origine Contrôlée framework is tightening color extraction standards, forcing producers to retool maceration protocols and reshaping competitive advantage toward terroir-certified estates with established Grenache-Cinsault sourcing.
Growth Catalysts
- Brunch and aperitif category expansion:Premium on-trade venues in New York and London are dedicating expanded shelf space to chilled rosé service, creating sustained pull-through for dry Provence-style blends.
- EFSA wine labeling alignment:The European Union's harmonized disclosure standards are streamlining cross-border export certification, reducing administrative friction for AOC-certified producers entering multiple member-state markets.
- Terroir-specific Grenache cultivation:Controlled vineyard sites in Provence-Alpes-Côte d'Azur are commanding sustained price premiums through geographic indication protections and limited-yield protocols.
Market Restraints
- Natural cork supply volatility:Portuguese cork forest harvest fluctuations are elevating closure costs and forcing producers toward technical cork or screw cap alternatives with associated retooling expenses.
- Anthocyanin extraction precision requirements:The narrow 4-12 mg/L color band specified under tightening AOC standards is rejecting significant batch volumes and compressing yields for non-compliant producers.
- Sparkling rosé production concentration:Disproportionate margin capture in celebratory segments is concentrating supply chain leverage among established Champagne houses, limiting access for new entrants.
Strategic Opportunities
- Boxed wine channel development:Alternative packaging formats are extending reach into casual outdoor and poolside consumption occasions where glass bottle breakage risk constrains traditional placement.
- Low-alcohol reformulation thresholds:Evolving regulatory definitions for reduced-alcohol wine categories are creating white space for producers investing in partial dealcoholization technology ahead of competitor repositioning.
- Duty-free channel premiumization:European airport retail corridors are expanding controlled-distribution placements for higher-margin rosé expressions targeting transient affluent demographics.
Industry Challenges
- Sulfite labeling compliance complexity:Joint US TTB and FDA disclosure requirements are demanding reformulated back-label designs and import certificate documentation that delay market entry timelines.
- Skin-contact technician scarcity:The precision timing required for color extraction without tannin overshoot is creating hiring competition for experienced cellar masters across competing Provence estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rose Wine Market |
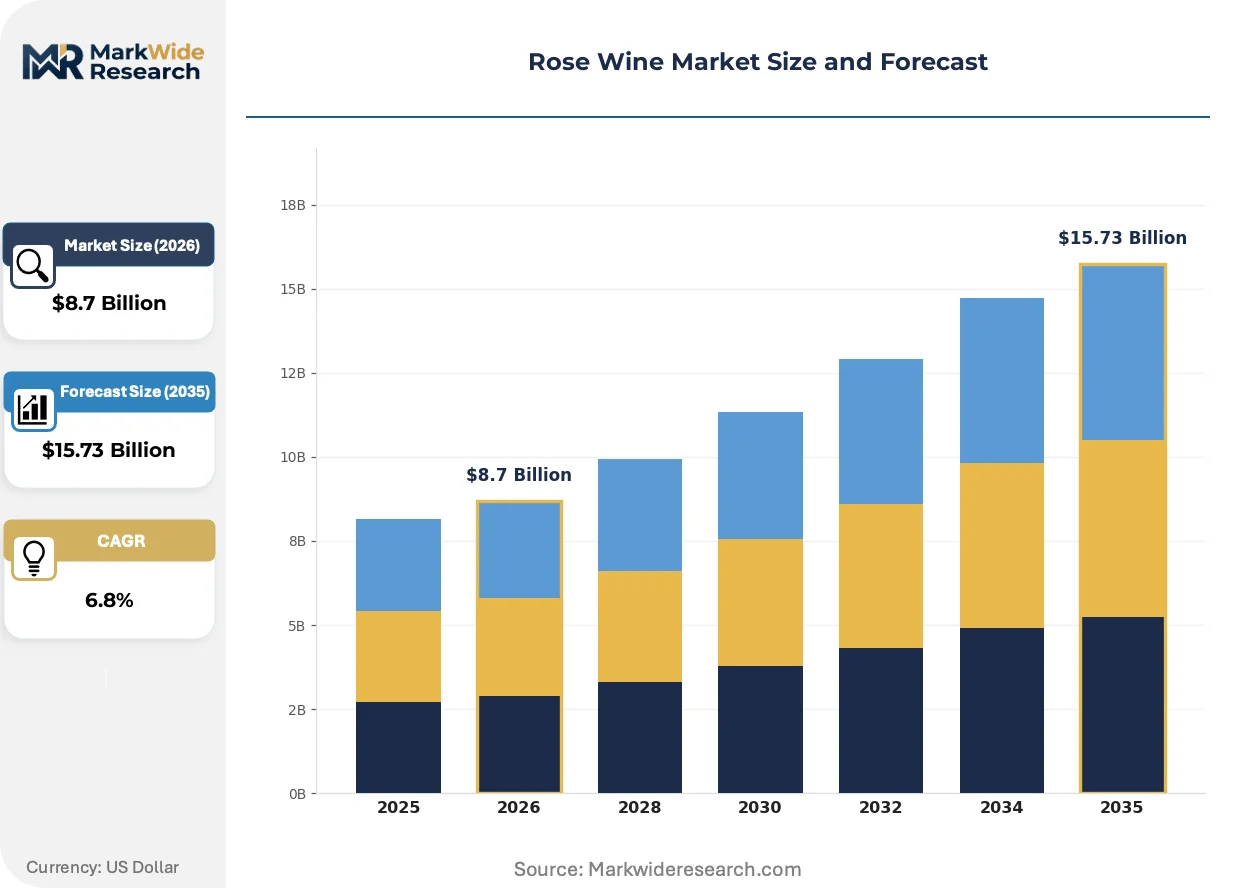
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Rose, Sweet Rose, Sparkling Rose, Semi-Sweet Rose Grape Variety: Grenache, Syrah, Pinot Noir, Zinfandel Packaging Type: Glass Bottle, Boxed Wine, Tetra Pack, Keg Sales Channel: Retail Stores, Online Stores, Restaurants, Distributors |
| Companies Covered | Treasury Wine Estates, Moët Hennessy, Pernod Ricard, Gérard Bertrand Wines, Domaines Ott, Constellation Brands, Château Miraval, Sula Vineyards Private Limited, E. & J. Gallo Winery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rose Wine Market Strategic Shifts
Production technology and packaging formats are converging to reshape rosé's accessibility and margin structure. Three developments are compressing traditional competitive advantages while opening new consumption occasions.
Precision temperature-controlled maceration systems are converging with optical sorting technology to enable real-time anthocyanin monitoring during skin contact. Mid-tier producers in Languedoc and California's Central Coast are adopting these systems to achieve AOC-comparable color consistency without estate-level terroir premiums. This technology convergence is compressing the quality gap between appellation-certified and technique-optimized production.
The European Union's EFSA wine labeling directives are mandating expanded allergen and nutritional disclosure on export-bound bottles. This regulatory shift is forcing reformulation investments in sulfite management and back-label redesign across producers targeting multiple member-state markets. French AOC estates with established compliance infrastructure are capturing accelerated shelf space approvals versus newer entrants facing certification delays.
Poolside and outdoor consumption patterns are elevating demand for shatter-resistant packaging alternatives to traditional glass. Boxed wine and aluminum can formats are displacing bottle placement in casual retail channels and music festival venues. This channel rotation is most visible in Australian and Californian mass-market distribution where volume-scaled Grenache sourcing supports margin-positive alternative format production.
Rose Wine Market Segmentation
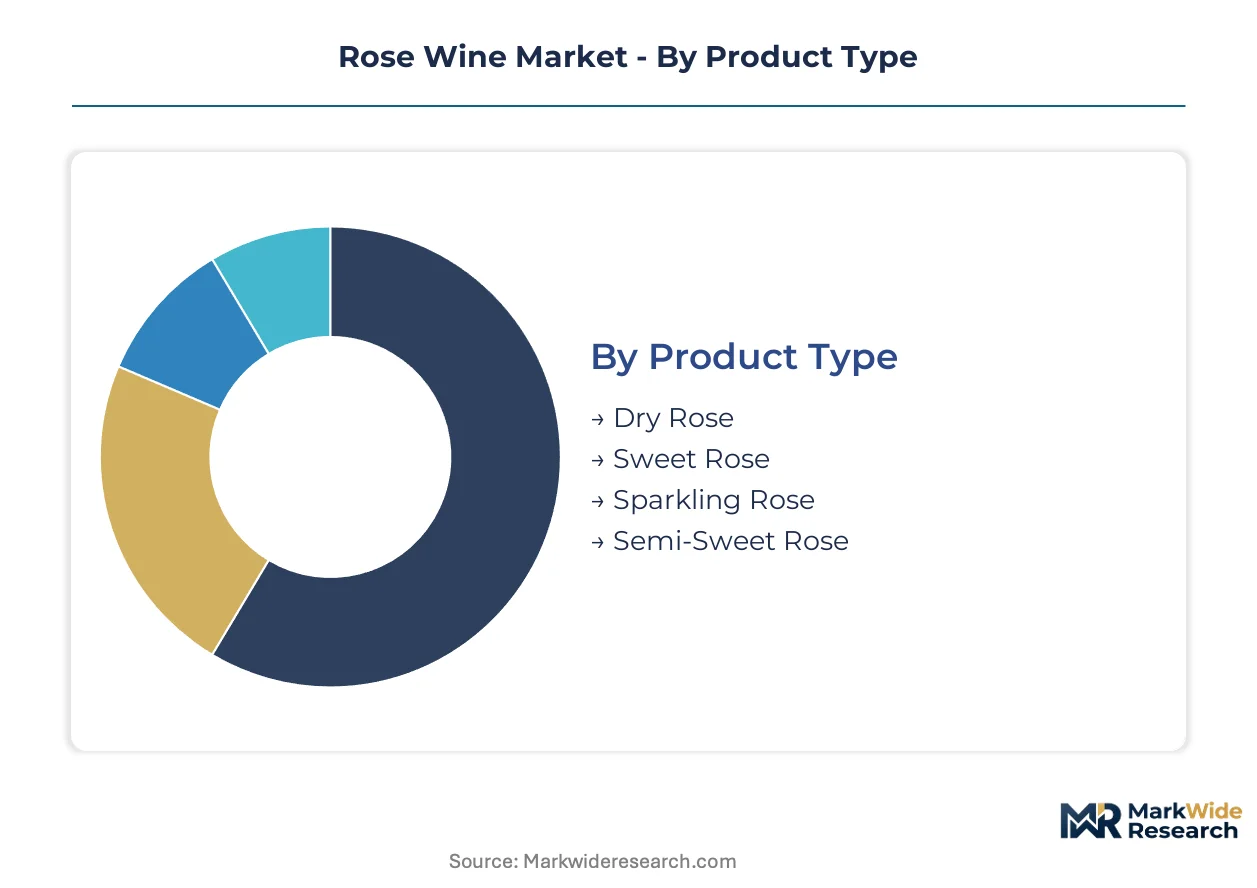
Rosé wine segmentation reflects divergent certification burdens across product types and the technical precision required for AOC-compliant color extraction. Grape variety and packaging format choices determine which regulatory frameworks govern market access and margin capture.
Product Type:
Dry Rosé carries the heaviest AOC compliance burden in France, requiring EFSA-aligned sulfite disclosure and precise anthocyanin documentation for export into EU member states.
- Dry Rose:Still wine with residual sugar below 4 g/L, produced through 4-12 hour skin contact of Grenache and Cinsault. Demand concentrates in Provence-Alpes-Côte d'Azur, where Appellation d'Origine Contrôlée standards command sustained price premiums across US and UK export channels. Tightening color extraction protocols are rejecting non-compliant batches and compressing yields for producers lacking estate-level terroir certification.
- Sparkling Rose:Carbonated through traditional method or Charmat process, with anthocyanin content typically at the lower end of the 4-12 mg/L band to preserve bubble clarity. Margin capture disproportionately concentrates in on-premise celebratory occasions across New York and London, where Champagne houses leverage controlled distribution to limit new entrant access.
- Sweet Rose:Residual sugar exceeding 12 g/L, common in bulk production from California's Central Coast.
- Semi-Sweet Rose:Mid-range residual sugar positioning, bridging mass-market accessibility with food-pairing versatility.
Leading the category by volume: Dry Rosé. Growing fastest: Sparkling Rosé.
Grape Variety:
Variety selection determines terroir certification eligibility and the supply chain leverage available through controlled vineyard ownership.
- Grenache:Thin-skinned Rhône variety yielding pale salmon hues with minimal tannin extraction, the dominant grape in Provence AOC blends. Treasury Wine Estates secures consistent supply through backward integration across Australian and Californian vineyard holdings.
- Pinot Noir:Burgundy-origin variety requiring precise temperature-controlled maceration to achieve color without structural heaviness. Demand concentrates in premium-tier sparkling rosé production, where optical sorting technology enables real-time anthocyanin monitoring.
- Syrah:Deeper pigment load demands shortened skin contact to remain within AOC color bands.
- Zinfandel:California-dominant variety supporting volume-scaled mass-market production with higher sugar ripeness potential.
Volume leadership: Grenache. Steepest expansion trajectory: Pinot Noir in premium sparkling applications.
Packaging Type:
Format choice shapes distribution economics and the regulatory documentation required for cross-border shipment.
- Glass Bottle:Traditional 750ml format maintaining structural dominance in premium tiers, requiring EFSA-compliant back-label redesign for EU export. Moët Hennessy anchors positioning through controlled placement in European duty-free channels where affluent transient demographics drive margin.
- Boxed Wine:Bag-in-box format extending reach into poolside and outdoor consumption occasions where breakage risk constrains glass placement. E. & J. Gallo Winery leverages Central Coast volume scaling to support margin-positive alternative format production for casual retail channels.
- Tetra Pack:Aseptic carton format with lighter shipping weight, gaining traction in festival and event venues.
- Keg:On-premise draft format reducing packaging waste, concentrated in restaurant and bar placements with high turnover velocity.
Revenue concentration: Glass Bottle. Gaining share fastest: Boxed Wine in casual outdoor channels.
Sales Channel:
Channel selection determines pricing architecture and the joint regulatory oversight applicable to alcohol content disclosure.
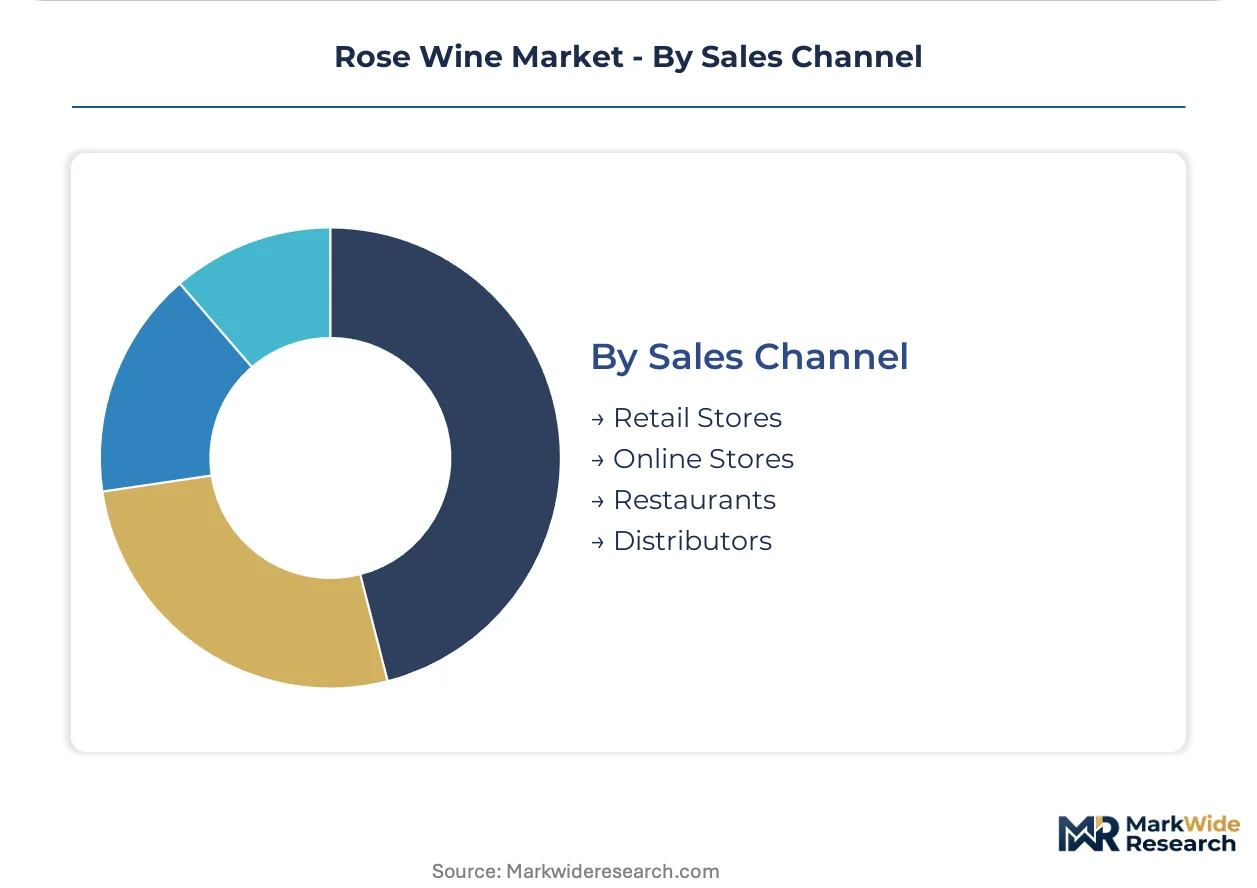
- Restaurants:On-premise venues in New York and London dedicating expanded shelf space to chilled rosé service, creating sustained pull-through for dry Provence-style blends. Brunch and aperitif category expansion drives premium placement, though sommelier education requirements elevate training costs.
- Online Stores:Direct-to-consumer platforms streamlining access across state and national borders, requiring TTB-compliant import certificate documentation. E-commerce growth is accelerating for boxed wine formats where shipping weight economics favor alternative packaging.
- Retail Stores:Mass-market placement dominated by volume-scaled producers with consistent supply chains.
- Distributors:Three-tier system intermediaries controlling access to on-premise accounts in regulated US markets.
Highest margin capture: Restaurants. Expanding most quickly: Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provence-Alpes-Côte d'Azur's Appellation d'Origine Contrôlée tax advantages and subsidized export certification programs concentrate production gravity in southeastern France's designated wine zones.
France
Provence's Grenache-Cinsault blends command sustained price premiums through geographic indication protections. EFSA wine labeling directives mandate expanded allergen disclosure on export-bound bottles. The Côtes de Provence sub-region tightens color extraction standards, forcing retooling investments among non-certified producers.
United States
TTB and FDA joint oversight on alcohol content disclosure shapes import certificate requirements for European rosé entry. Central Coast volume-scaled Grenache sourcing supports mass-market boxed wine production. New York City's brunch and aperitif category expansion drives premium on-premise placement for chilled Provence-style blends.
United Kingdom
London's premium on-trade venues dedicate expanded shelf space to dry rosé service. Post-Brexit import documentation requirements create administrative friction for AOC-certified producers. The city's duty-free retail corridors expand controlled-distribution placements targeting transient affluent demographics.
Australia
Treasury Wine Estates leverages backward integration across Australian vineyard holdings to secure consistent Grenache supply. The country's national wine regulator enforces sulfite labeling standards aligned with export market requirements. South Australia's Barossa Valley clusters precision temperature-controlled maceration technology adoption for color consistency optimization.
India
Sula Vineyards Private Limited anchors domestic production through Maharashtra vineyard concentration. FSSAI food safety standards govern sulfite thresholds and labeling disclosure for alcoholic beverages. Nashik's emerging wine corridor attracts technology investments in optical sorting systems for anthocyanin monitoring during skin contact.
Rose Wine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with estate-certified producers capturing disproportionate margin in premium tiers while volume-scaled operators dominate mass-market retail placement. The vendor base organizes around three strategic archetypes: terroir-certified AOC estates with controlled vineyard ownership, backward-integrated multinational portfolios securing consistent grape supply, and regional specialists leveraging local distribution relationships. Competitive dynamics center on M&A activity consolidating vineyard assets and technology licensing agreements transferring precision maceration capabilities across production zones.
Among French AOC-certified estates, Domaines Ott and Château Miraval exemplify the terroir-premium archetype through Provence-based production concentration. Treasury Wine Estates represents the multinational integrated model, securing supply chain leverage through vineyard ownership across multiple hemispheres.
| Leading Market Players |
|---|
| Treasury Wine Estates |
| Moët Hennessy |
| Pernod Ricard |
| Gérard Bertrand Wines |
| Domaines Ott |
| Constellation Brands |
| Château Miraval |
| Sula Vineyards Private Limited |
| E. & J. Gallo Winery |
| Others |
Value Chain & Pricing Dynamics
Brunch and aperitif category expansion across New York and London is pulling supply toward premium Provence-style Grenache blends, compressing margins for non-certified producers while elevating price premiums for AOC-compliant estates with controlled vineyard ownership.
Pricing Analysis
Short lead-time premiums dominate pricing for terroir-certified Provence estates supplying on-premise venues, while spot inventory discounts characterize mass-market Central Coast sourcing. Three-tier pricing structure across AOC-certified premium, technique-optimized mid-tier, and volume-scaled economy levels separates estates by certification grade and Grenache supply control. Pricing pressure stems from natural cork supply volatility forcing closure cost absorption. Mass-market retail buyers exhibit highest price sensitivity, while European duty-free channels show least.
Supply Chain Analysis
Freight cost differentials between glass bottle and alternative packaging formats are reshaping distribution economics for outdoor consumption channels. Supply concentrates in France, Australia, and California, with raw material dependencies on Portuguese cork, Rhône Valley Grenache rootstock, and optical sorting equipment. Single-source vulnerability runs through Portuguese cork forest harvest fluctuations. Distribution runs through three-tier intermediaries in regulated US markets, direct-to-consumer platforms, and controlled duty-free corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as tightening AOC color extraction standards and precision maceration technology costs force sub-scale producers toward exit or acquisition.
For Market Incumbents: Anticipate margin compression from mid-tier Languedoc and Central Coast producers adopting precision temperature-controlled maceration systems to achieve AOC-comparable color consistency. Defend positioning through backward integration into Provence-Alpes-Côte d'Azur vineyard assets and accelerated EFSA compliance infrastructure investment to capture shelf space approvals ahead of certification-delayed competitors. For New Entrants and Emerging Players: Launch via boxed wine and aluminum can distribution models targeting poolside and music festival venues where glass breakage risk constrains incumbent placement. White-space targets include casual outdoor consumption occasions in Australian and Californian mass-market channels, plus low-alcohol reformulation categories ahead of evolving regulatory threshold definitions. Prioritize volume-scaled Grenache sourcing partnerships to achieve margin-positive alternative format production. For Investors and Strategic Acquirers: The window for entry favors terroir-certified AOC estates with established Grenache-Cinsault vineyard ownership and compliant export certification infrastructure. Long-term viability hinges on geographic indication protections and limited-yield protocols sustaining price premiums across export channels. Watch for M&A activity consolidating precision maceration technology licensing agreements as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vineyard Assets | Treasury Wine Estates secures consistent Grenache supply across Australian and Californian holdings. |
| EFSA Compliance Infrastructure Investment | French AOC estates capture accelerated EU shelf space approvals versus certification-delayed entrants. |
| Alternative Packaging Format Expansion | E. & J. Gallo Winery extends reach into poolside channels through Central Coast volume scaling. |
| Precision Maceration Technology Licensing | Mid-tier producers in Languedoc compress quality gaps through optical sorting system adoption. |
| Duty-Free Channel Premiumization | Moët Hennessy anchors positioning through controlled placement in European airport retail corridors. |
Study Parameters
Document review covered customs and trade data, SEC filings from publicly traded wine portfolios, EFSA regulatory directives, and appellation certification records, complemented by interviews with cellar masters at Provence AOC estates, procurement leads at Treasury Wine Estates and Moët Hennessy, US TTB compliance officers, and category buyers at London and New York on-premise venues. Bottom-up volume modeling triangulated against top-down value estimates from export certification databases and duty-free retail audit data.
Segment-level outputs across product type, grape variety, packaging format, and sales channel dimensions were generated through the analysis window, with CAGRs derived from historical shipment trajectories and projected brunch and aperitif category expansion rates. Forecast inputs incorporated EFSA labeling directive implementation timelines, Portuguese cork harvest yield assumptions, and precision maceration technology adoption curves across Languedoc and Central Coast production zones.
Portuguese cork supply volatility, AOC color extraction standard tightening, and low-alcohol regulatory threshold evolution are the dominant revision risks to modeled projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Rice Wine Market
Alcoholic Beverages
North America Beer Market
Alcoholic Beverages
Industrial Alcohol Market
Alcoholic Beverages
Gluten Free Alcoholic Drinks Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Bayberry Wine Market
Alcoholic Beverages
RTD Cocktails Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
Craft Beer Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Asia-Pacific Alcohol E-Commerce Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
Japan Tequila Market