
 Europe and Asia Juniper Berries Market | 2026-2036
Europe and Asia Juniper Berries Market Size, Share, and Industry Trends Forecast 2026-2036
Europe and Asia Juniper Berries Market Analysis
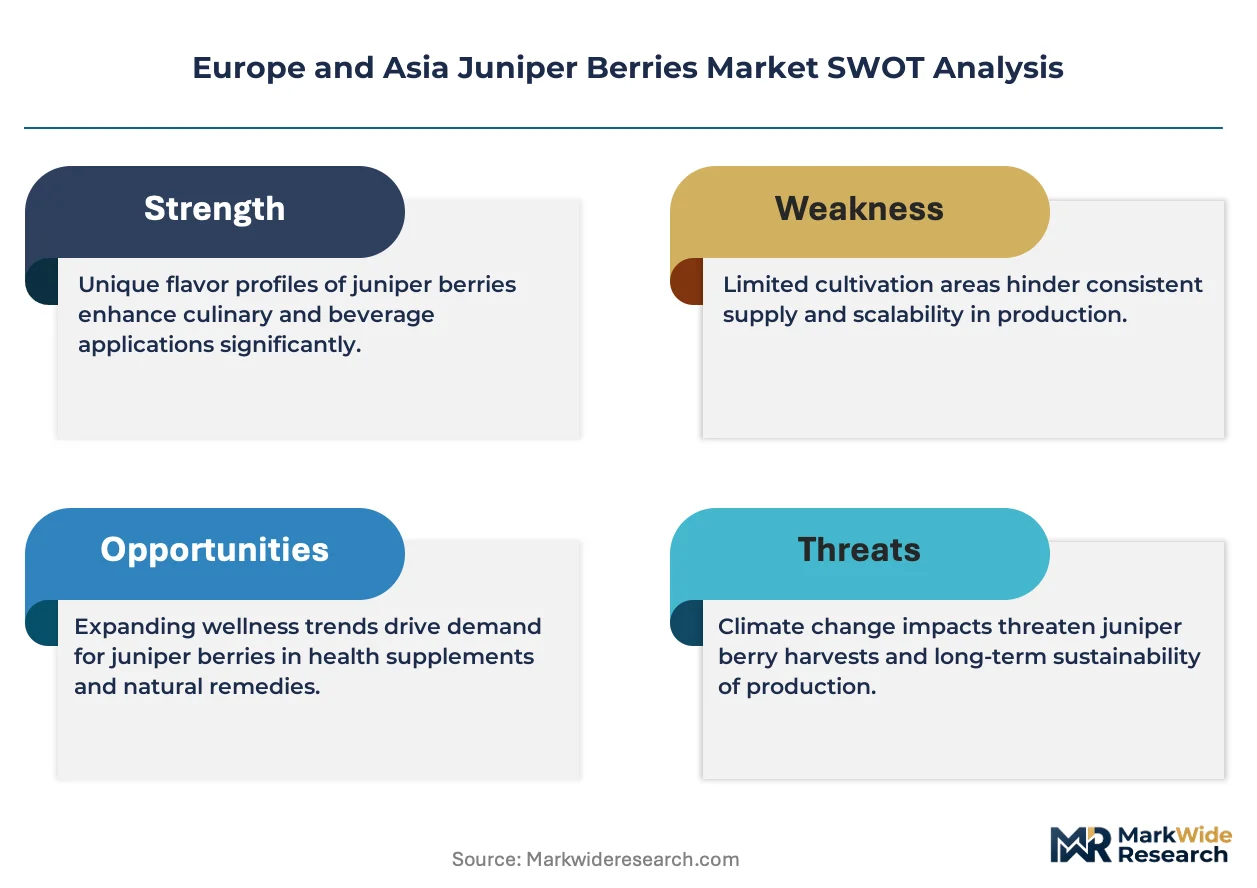
The gap between wild-harvested premium juniper berries and cultivated commodity grades is expanding as distillers and pharmaceutical buyers diverge on alpha-pinene content and provenance documentation. Jean Gazignaire - Groupe Mul anchors its position through backward integration into French alpine foraging cooperatives. Herbera leverages certified organic extraction capabilities to serve cosmetics formulators in South Korea. Beacon Commodities Ltd dominates bulk wholesale channels across British botanical supply houses.
Juniper berries constitute the dried female seed cones of Juniperus communis, containing essential oil profiles typically ranging from 0.5% to 2.0% by weight with alpha-pinene, myrcene, and sabinene as dominant terpenes, primarily serving flavoring, fragrance, and traditional medicine applications. Extracts command the highest margin pools within product type categories due to concentrated active compounds and stringent solvent residue protocols. The aromatherapy application segment leads growth velocity across distribution channels, while offline retail sustains the largest transaction volume among food manufacturers and herbalists.
EMA guidelines on herbal medicinal products and Japan's MHLW Food Sanitation Act shape extract standardization requirements, with REACH compliance adding cost layers for EU-bound oil shipments. China's SAMR and GB standards for edible botanicals govern import thresholds for Yunnan-sourced materials entering European processing facilities. Stakeholders must monitor divergence between EU organic certification and China's green food labeling protocols as cross-border sourcing complexity intensifies.
Market Dynamics
The divergence between wild-harvested alpine juniper and cultivated commodity grades is reshaping procurement strategies across European distillers and Asian cosmetics formulators, as alpha-pinene content thresholds and provenance documentation requirements harden.
Growth Catalysts
- EU Novel Food Regulation:Standardized extract purity protocols are opening pharmaceutical-grade applications for juniper-derived compounds in German and French herbal medicine manufacturing.
- Craft gin distillation:Botanical sourcing intensity from small-batch producers across Japan's Honshu island and England's Lake District is pulling premium wild-harvested volumes.
- Steam distillation automation:Continuous extraction systems are reducing solvent residue variability, enabling South Korean cosmetics houses to qualify European-sourced oils under MFDS cosmetic safety standards.
Market Restraints
- Wild harvest dependency:Alpine foraging cooperatives in France's Provence-Alpes-Côte d'Azur face yield volatility from climate stress on Juniperus communis stands.
- REACH compliance costs:Essential oil shipments into EU processing facilities require extensive substance registration documentation, compressing margins for Yunnan-based raw material exporters.
- Synthetic terpene substitution:Laboratory-produced alpha-pinene and sabinene are displacing natural extracts in industrial fragrance applications below premium tiers.
Strategic Opportunities
- Certified organic channel expansion:Herbera's extraction capabilities position suppliers to capture South Korean clean beauty formulators seeking EU-organic certified inputs.
- Aromatherapy retail growth:Direct-to-consumer essential oil brands in Japan's urban centers are building captive demand for traceable alpine provenance.
- China's green food labeling:Divergence from EU organic protocols creates arbitrage potential for processors mastering dual-certification documentation.
Industry Challenges
- Skilled forager scarcity:Traditional alpine harvesting knowledge is concentrating among aging cooperative members in French alpine zones.
- Dual certification timelines:Parallel EU organic and China green food approval processes extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe and Asia Juniper Berries Market |
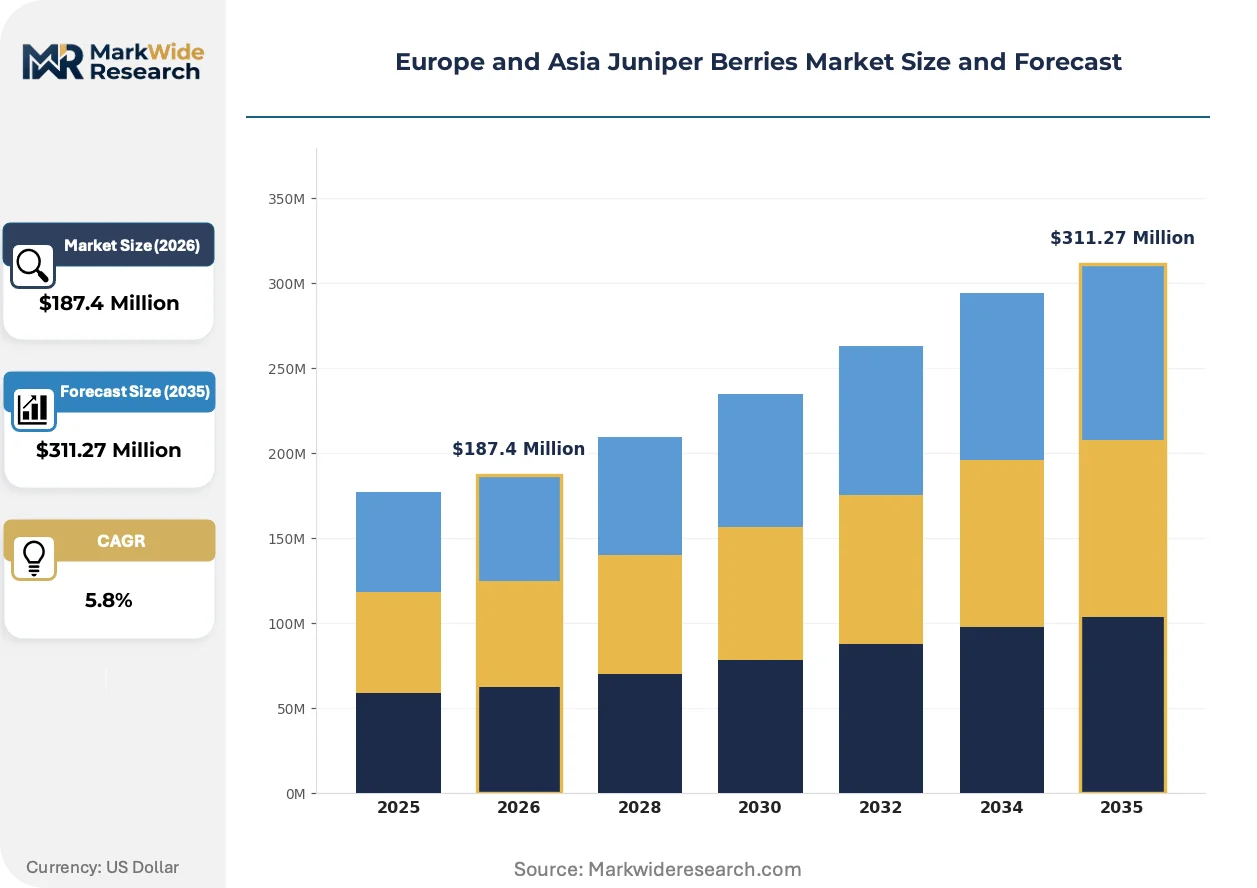
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Berries, Ground Berries, Extracts, Oils Application: Food & Beverages, Cosmetics, Pharmaceutical, Aromatherapy Distribution Channel: Offline Retail, E-commerce, Direct Sales, Wholesale End User: Food Manufacturers, Retailers, Herbalists, Distillers |
| Companies Covered | Jean Gazignaire - Groupe Mul, Herbera, Pure Herbs, Beacon Commodities Ltd, Secrets of The Tribe, Health and Herbs, Best Botanicals, Amazon Forest Inc, Indigo Herbs Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe and Asia Juniper Berries Market Emerging Trajectories
Supercritical CO2 extraction is converging with blockchain traceability systems, compressing the gap between raw botanical harvest and certified finished extract while enabling real-time provenance verification for premium buyers.
Supercritical CO2 extraction technology replaces steam distillation for high-value juniper oil production. French pharmaceutical extractors and Japanese flavor houses are adopting these systems at accelerating rates. The technology is converging with automated terpene profiling, enabling batch-level alpha-pinene standardization previously unattainable through conventional methods.
Japan's MHLW Food Sanitation Act amendments are tightening residual solvent limits for botanical extracts entering cosmetic and food applications. Domestic processors must retrofit extraction facilities or source from compliant overseas suppliers. Premium distillers in Germany and craft cosmetics manufacturers in South Korea are absorbing compliance premiums to maintain market access.
Direct sourcing contracts are replacing spot market purchases among large-volume cosmetics formulators. Long-term offtake agreements with French alpine cooperatives and Yunnan cultivation collectives are displacing traditional wholesale channels. This pattern concentrates most visibly in South Korea's Seoul-Incheon cosmetics manufacturing corridor, where MFDS audit requirements favor documented supply chain relationships over commodity procurement.
Europe and Asia Juniper Berries Market Segmentation
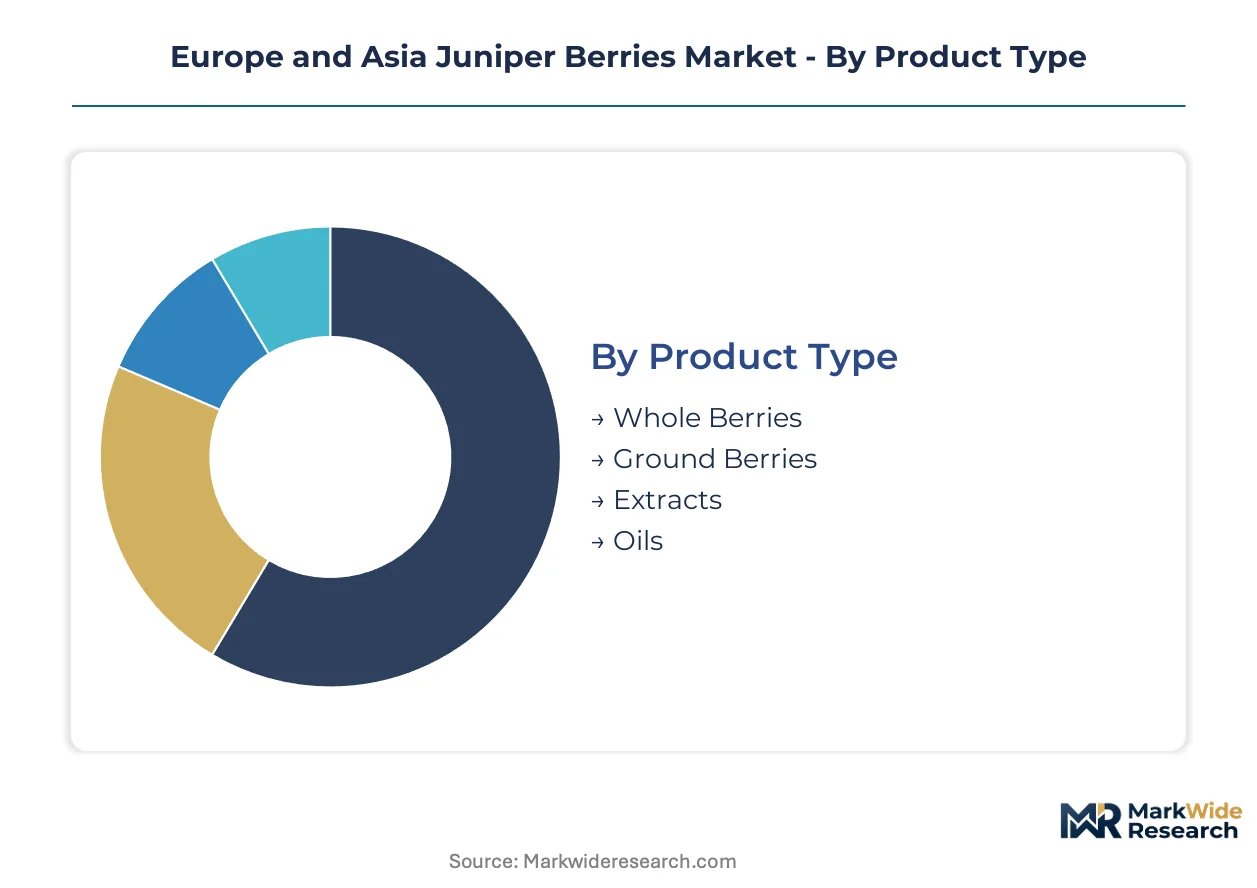
Juniper berry value chains bifurcate sharply between raw botanical commodities and processed derivatives, with each tier commanding distinct margin pools and compliance burdens. Distillers and pharmaceutical extractors drive specification divergence across product categories.
Product Type:
Standalone whole berries serve traditional culinary and distillation uses, while extracts and oils embed into complex formulation systems requiring standardization.
- Whole Berries:Dried female seed cones of Juniperus communis retain essential oil content between 0.5% and 2.0% by weight. French alpine foraging cooperatives in Provence-Alpes-Côte d'Azur supply premium wild-harvested volumes to gin distillers across Germany and Japan's Honshu island, where provenance documentation commands sourcing premiums.
- Extracts:Concentrated active compounds deliver the highest margin pools within the category, though EMA herbal medicinal guidelines and Japan's MHLW Food Sanitation Act impose stringent solvent residue protocols. South Korean cosmetics formulators absorb compliance premiums to secure EU-organic certified inputs from specialized extractors.
- Ground Berries:Commodity-grade milling serves spice blenders and food manufacturers with less stringent terpene profiling requirements.
- Oils:Steam-distilled or supercritical CO2-extracted essential oils face REACH registration costs for EU-bound shipments, compressing margins for Yunnan-based exporters.
Whole berries lead volumes today; extracts are gaining share fastest.
Application:
End-use specifications range from sensory-driven flavoring to therapeutic compound standardization, with regulatory intensity escalating across the spectrum.
- Food & Beverages:Craft gin distillation pulls premium wild-harvested volumes as botanical sourcing intensity rises among small-batch producers. EFSA flavoring substance regulations govern juniper-derived compounds in EU food applications.
- Aromatherapy:Direct-to-consumer essential oil brands in Japan's urban centers build captive demand for traceable alpine provenance, expanding most quickly among application segments.
- Cosmetics:MFDS cosmetic safety standards in South Korea favor documented supply chain relationships over commodity procurement, driving long-term offtake agreements with French cooperatives.
- Pharmaceutical:EMA herbal medicinal product guidelines require batch-level alpha-pinene standardization, favoring supercritical CO2 extraction over conventional steam distillation.
Food and beverages anchor current demand; aromatherapy climbs the fastest.
Distribution Channel:
Channel selection reflects buyer scale and documentation requirements, with institutional procurement displacing spot markets.
- Offline Retail:Physical storefronts sustain the largest transaction volume among food manufacturers and herbalists seeking immediate tactile quality assessment.
- Wholesale:British botanical supply houses move bulk volumes through established distributor networks, though direct sourcing contracts are eroding this channel's share.
- Direct Sales:Long-term offtake agreements with French alpine cooperatives and Yunnan cultivation collectives concentrate in South Korea's Seoul-Incheon cosmetics manufacturing corridor.
- E-commerce:Digital platforms serve small-scale distillers and aromatherapy retailers with lower minimum order quantities.
Offline retail dominates transaction volume; direct sales expands most rapidly.
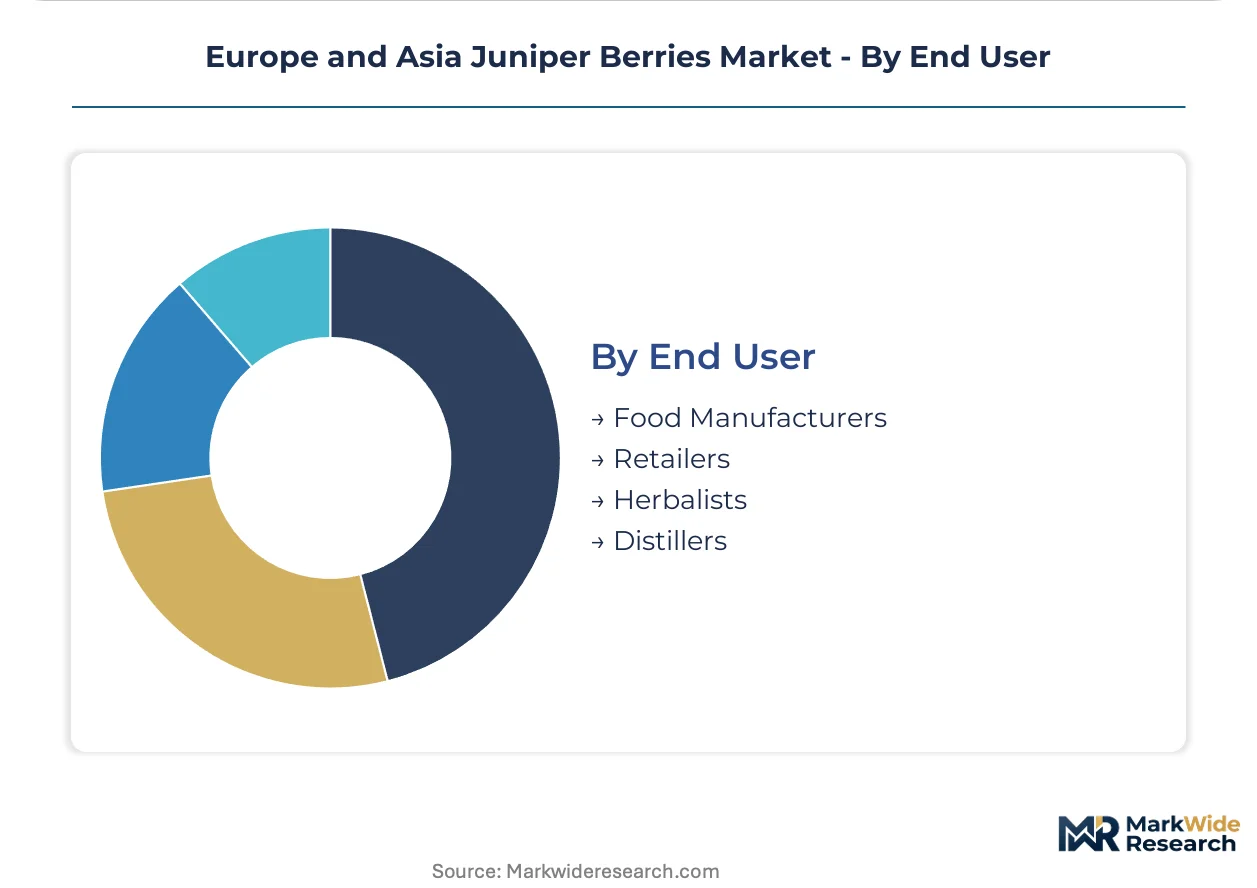
End User:
User sophistication varies from commodity procurement to captive supply integration, with backward integration strategies concentrating among volume buyers.
- Distillers:German and Japanese craft gin producers scale botanical sourcing intensity, prioritizing alpha-pinene content thresholds and provenance documentation.
- Food Manufacturers:Industrial flavoring applications face synthetic terpene substitution pressure below premium tiers.
- Herbalists:Traditional medicine practitioners favor whole berries with documented wild-harvest origins.
- Retailers:Consumer-facing channels absorb compliance premiums for certified organic and EU-organic labeled products.
Distillers command premium tier volumes; cosmetics-facing supply chains show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alpine foraging cooperatives in France's Provence-Alpes-Côte d'Azur region anchor the skilled harvester base sustaining premium wild-harvested supply chains across Europe and Asia.
Germany
Craft gin distillers in Bavaria and Baden-Württemberg scale botanical sourcing intensity for small-batch production. EMA herbal medicinal product guidelines govern extract standardization for pharmaceutical applications. The Black Forest region concentrates supercritical CO2 extraction facilities serving cosmetics formulators.
France
Wild-harvested juniper from alpine zones commands provenance premiums among Japanese and South Korean buyers. EU Novel Food Regulation shapes extract purity protocols opening pharmaceutical-grade applications. Provence-Alpes-Côte d'Azur foraging cooperatives supply premium volumes to distillers across Honshu island.
Japan
Urban aromatherapy retailers in Tokyo and Osaka build captive demand for traceable alpine provenance. MHLW Food Sanitation Act amendments tighten residual solvent limits for botanical extracts. Craft gin producers on Honshu island pull premium wild-harvested volumes through direct sourcing contracts.
South Korea
Cosmetics manufacturers in the Seoul-Incheon corridor absorb compliance premiums for EU-organic certified inputs. MFDS cosmetic safety standards favor documented supply chain relationships over commodity procurement. Clean beauty formulators drive long-term offtake agreements with French alpine cooperatives.
China
Yunnan province cultivation collectives face margin compression from REACH registration costs for EU-bound oil shipments. SAMR and GB standards for edible botanicals govern import thresholds entering European processing facilities. Dual-certification timelines for EU organic and China green food labeling extend product launch cycles.
Europe and Asia Juniper Berries Market Vendor Landscape
Top-tier vendors anchor premium wild-harvested supply chains, while mid-tier processors compete on extraction standardization and certification compliance. The vendor base clusters around three strategic archetypes: alpine foraging cooperatives with backward integration into harvest networks, certified organic extractors serving cosmetics formulators, and bulk wholesale distributors moving commodity volumes through established channels. Dominant competitive moves include direct sourcing contracts displacing spot market purchases and supercritical CO2 extraction technology licensing to meet tightening solvent residue protocols.
Within the premium provenance tier, Jean Gazignaire - Groupe Mul represents the alpine cooperative archetype with French alpine harvest network integration. Herbera exemplifies the certified organic extraction specialist serving South Korean cosmetics houses. Beacon Commodities Ltd occupies the bulk wholesale distributor position across British botanical supply channels. These three anchors illustrate the market's tripartite structure: harvester-integrated, processor-certified, and distribution-scaled.
| Leading Market Players |
|---|
| Jean Gazignaire - Groupe Mul |
| Herbera |
| Pure Herbs |
| Beacon Commodities Ltd |
| Secrets of The Tribe |
| Health and Herbs |
| Best Botanicals |
| Amazon Forest Inc |
| Indigo Herbs Ltd |
| Others |
Supply Flow & Price Mechanics
Backward integration into French alpine foraging cooperatives anchors premium pricing power for harvester-integrated suppliers, while spot-market commodity traders face margin compression from REACH compliance costs and synthetic terpene substitution. This structural divide separates captive supply chains commanding provenance premiums from wholesale distributors competing on volume scale.
Pricing Analysis
Bundled certification-plus-extraction services command substantial premiums over unbundled raw botanical procurement, with EU-organic certification and supercritical CO2 processing sold as integrated packages to South Korean cosmetics formulators. Three-tier pricing structure across premium wild-harvested, standard cultivated, and economy commodity grades reflects alpha-pinene content thresholds and documentation depth. Pricing pressure stems from laboratory-produced terpenes displacing natural extracts in industrial fragrance applications below premium tiers. Craft gin distillers show lowest price sensitivity due to provenance requirements, while spice blenders and food manufacturers face highest substitution elasticity.
Supply Chain Analysis
Direct-to-cosmetics-manufacturer channels handle high-compliance buyer demand from Seoul-Incheon formulators seeking documented EU-organic inputs, while traditional wholesale networks serve British botanical supply houses with lower documentation burdens. Supply concentrates in France's Provence-Alpes-Côte d'Azur region, Germany's Black Forest extraction corridor, and China's Yunnan province cultivation zones. Raw material flows draw from wild-harvested alpine Juniperus communis stands, cultivated plantation berries, and imported dried botanicals. Single-source vulnerability runs through aging French alpine forager networks where traditional harvesting knowledge concentrates. Distribution runs through long-term offtake agreements displacing spot market purchases among volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA herbal medicinal guidelines and Japan's MHLW Food Sanitation Act amendments continuously tighten extract purity thresholds, driving sustained demand for certified processing capabilities.
For Market Incumbents: Hedge synthetic terpene substitution risk by deepening captive supply relationships with French alpine cooperatives before skilled forager scarcity intensifies. Anchor defensibility through supercritical CO2 extraction technology licensing to smaller processors seeking compliance with tightening solvent residue protocols. Prioritize dual-certification capabilities spanning EU organic and China green food labeling to capture arbitrage opportunities as cross-border sourcing complexity rises. For New Entrants and Emerging Players: The mid-tier price-point gap between premium wild-harvested and economy commodity grades creates white-space opportunity for traceable cultivated supply with documented terpene profiles. Target South Korean clean beauty formulators seeking EU-organic certified inputs with streamlined certification pathways. Enter through specialized extraction services rather than raw botanical procurement, leveraging automated terpene profiling to meet batch-level standardization requirements. For Investors and Strategic Acquirers: Roll-up economics work for certified organic extraction specialists because fragmentation among French alpine cooperatives and Yunnan cultivation collectives creates consolidation opportunity with compliance scale advantages. Target processors with established MFDS audit relationships and dual-certification capabilities. Watch for inflection where Japan's MHLW amendments trigger facility retrofitting requirements that smaller domestic processors cannot absorb.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpine Cooperatives | Secures provenance documentation for German and Japanese craft gin distillers. |
| Supercritical CO2 Extraction Licensing | Enables batch-level alpha-pinene standardization under EMA herbal guidelines. |
| Dual-Certification Program | Captures arbitrage between EU organic and China green food labeling protocols. |
| Long-Term Offtake Agreements | Builds documented supply chains qualifying under South Korea's MFDS standards. |
| Blockchain Traceability Implementation | Compresses harvest-to-extract verification for Japanese aromatherapy retailers. |
Methodological Framework
Direct dialogue with alpine foraging cooperative managers, supercritical CO2 extraction facility operators, cosmetics formulators in Seoul-Incheon, and regulatory affairs specialists at EMA and Japan's MHLW grounded qualitative findings. Secondary validation drew from EU Novel Food Regulation filings, REACH substance registration databases, SAMR import threshold documentation, and customs records for Yunnan-sourced botanicals. Bottom-up volume estimates from processor capacity and top-down demand calibration from end-use consumption patterns were triangulated.
Bottom-up modeling tracked product type flows across whole berries, extracts, ground berries, and oils through application segments, while top-down analysis cross-checked against regional consumption patterns. Segmentation dimensions included product type, application, distribution channel, and end user archetype across the analysis window. CAGRs were derived from regression against historical trade flows and regulatory milestone impacts. Industry-specific inputs incorporated foraging yield volatility from climate stress and dual-certification timeline delays.
Caveats apply where EMA guideline revisions, MHLW solvent limit amendments, or REACH registration cost escalations could materially shift the outlook for extract profitability and trade flow patterns. Forecasts reflect assumptions about sustained craft gin demand and clean beauty formulation trends. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Peppermint Extract Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
Organic Saffron Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Serrata Extract Market
Spices and Seasonings
Ginger Oil Market
Spices and Seasonings
Sriracha Market
Spices and Seasonings
Dill Oil Market
Spices and Seasonings
Mint Oils Market
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Bay Leaf Market
Spices and Seasonings
North America Spice and Herb Extracts Market
Spices and Seasonings
Ginger Market
Spices and Seasonings
Spices Market