
 Global Bars and Nightclubs Market | 2026-2036
Global Bars and Nightclubs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bars and Nightclubs Market Analysis
Mobile-first reservation and payment platforms is reconfiguring how nightlife venues manage capacity, personalize service, and capture repeat visits. Stonegate Group leverages its estate scale to deploy integrated table-management systems across British pub networks. Hakkasan Group anchors its competitive edge in VIP hospitality through proprietary guest-data analytics. JD Wetherspoon plc sustains cost leadership by controlling in-house supply chains for food and beverage procurement.
Bars and nightclubs constitute licensed premises offering alcoholic beverages, food preparation, and live entertainment within regulated operating hours, typically requiring sound-dampening infrastructure, ventilation systems meeting decibel and air-quality thresholds, and occupancy limits tied to fire-safety codes. Their commercial purpose centers on facilitating social consumption experiences that generate per-visit revenue through drink markup, cover charges, and ancillary event sales. Beverage Service dominates margin pools given alcohol's high markup elasticity, while Entertainment segments attract premium pricing in dance-floor and rooftop formats. Facility Size reveals structural divergence: micro bars capture urban real-estate scarcity with minimal staff overhead, whereas large venues absorb fixed costs through corporate event contracts.
FDA guidelines on food-safety protocols, EPA standards for commercial ventilation emissions, and local alcohol-licensing boards in the United States, United Kingdom, and Germany collectively shape permissible operating models and capital requirements for venue operators. The EU F-Gas Regulation and REACH chemical standards further constrain refrigeration equipment choices and cleaning-product specifications across European establishments. Stakeholders must monitor evolving noise-ordinance enforcement and digital-payment compliance mandates as municipalities tighten quality-of-life regulations and tax-collection transparency.
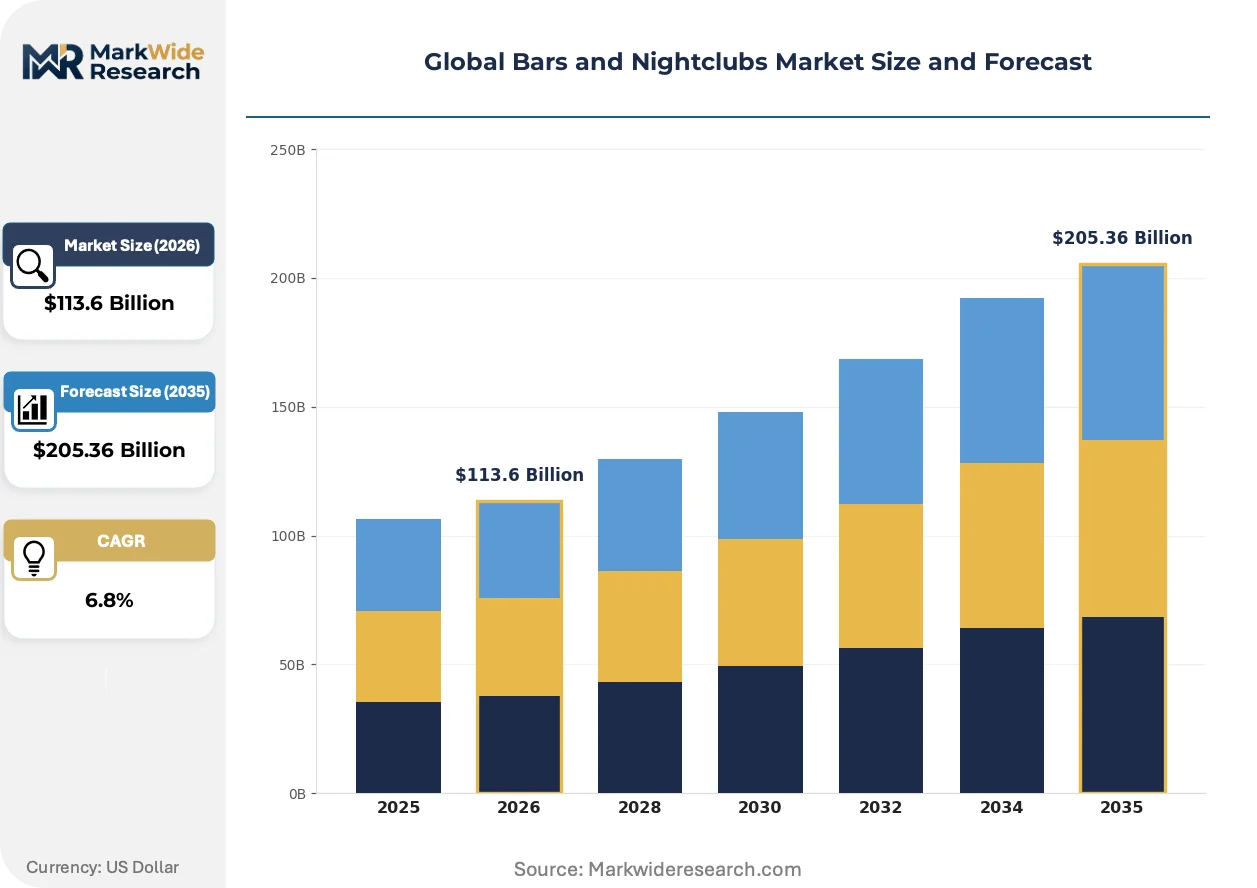
Market Dynamics
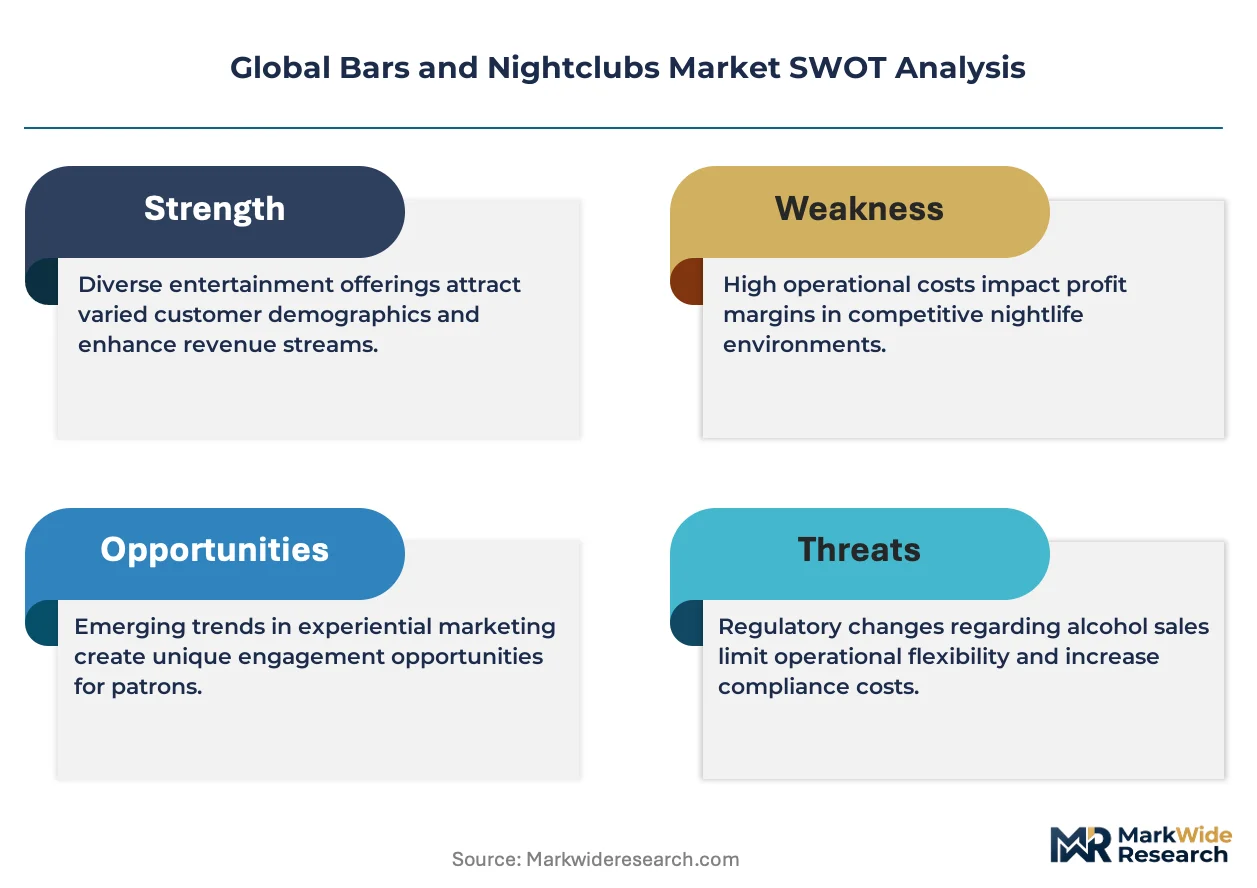
Mobile-first reservation platforms and EU F-Gas refrigeration mandates are compressing operating margins while forcing capital redeployment into digital infrastructure and compliant equipment across licensed premises worldwide.
Growth Catalysts
- Urban young professionals:Dense metropolitan clusters in Barcelona, Madrid, and London generate concentrated demand for premium cocktail experiences and extended-hours venues.
- EU F-Gas Regulation:Phasedown schedules for hydrofluorocarbon refrigerants accelerate equipment replacement cycles and create aftermarket service revenue pools for compliant cold-chain installations.
- Contactless payment rails:Near-field communication and QR-code settlement systems reduce transaction friction, shrink cash-handling labor, and improve tax-audit transparency for municipal licensing boards.
Market Restraints
- Commercial real estate scarcity:Central business district rents in London, New York, and Tokyo consume 25-35% of venue revenue, compressing returns on micro-bar formats with limited seating capacity.
- Input cost volatility:Glass bottle supply concentrates in China and Mexico, exposing operators to freight-rate swings and tariff uncertainty on imported spirits packaging.
- Sound-dampening infrastructure mandates:Municipal noise ordinances in Berlin, Amsterdam, and Sydney require expensive acoustic retrofitting for dance-floor venues near residential zones.
Strategic Opportunities
- Rooftop and outdoor formats:Underutilized urban air rights in São Paulo, Mexico City, and Bangkok offer expansion vectors with lower per-square-meter occupancy costs than street-level leases.
- Corporate event contracts:Technology and financial services sectors in Singapore and Dubai purchase block bookings for product launches and team entertainment, stabilizing midweek revenue.
- GDPR-compliant guest analytics:Consent-based data collection enables personalized service recovery and predictive inventory management without violating European privacy frameworks.
Industry Challenges
- Mixology talent scarcity:Certified craft-cocktail specialists command premium wages in competitive labor markets like New York and London, inflating staff costs for independent operators.
- Fire-safety certification timelines:Occupancy-permit approvals from local authorities in Germany and France extend venue-opening schedules by 4-8 months, delaying revenue recognition.
- Legacy POS integration:Proprietary table-management systems from dominant vendors resist interoperability with emerging reservation platforms, fragmenting guest-data repositories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bars and Nightclubs Market |
| Market Size in 2026 | $113.6 Billion |
| Market Size in 2035 | $205.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Food Service, Beverage Service, Entertainment, Event Management Customer Type: Millennials, Gen Z, Professionals, Tourists Atmosphere: Lounge, Dance Floor, Rooftop, Sports Bar Facility Size: Small Venues, Medium Venues, Large Venues, Micro Bars |
| Companies Covered | Stonegate Group, Hakkasan Group, Mitchells and Butlers plc, Applebee's Restaurants LLC, Dave & Buster's Entertainment Inc., JD Wetherspoon plc, Fuller's Group, Revolution Bars Group plc, Greene King plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bars and Nightclubs Market Emerging Trajectories
Digital infrastructure and sustainability mandates are rewriting operational standards for licensed premises, compressing legacy cost structures while opening new revenue architectures.
Artificial intelligence-driven demand forecasting is hybridizing static inventory management with dynamic pricing algorithms. High-volume nightclub operators in Miami and Ibiza deploy machine-learning models to predict bottle-service consumption patterns hour-by-hour. This capability compresses working-capital requirements and reduces spoilage on premium spirits.
REACH chemical standards and EU F-Gas Regulation are forcing equipment procurement shifts across European venues. Cleaning-product formulations and refrigeration hardware must now demonstrate reduced environmental impact through certified lifecycle assessments. Spanish and Italian operators face compressed replacement windows for non-compliant ice machines and draft systems.
Experience-driven consumption patterns are displacing transaction-focused nightlife visits. Young professionals in Seoul, Melbourne, and São Paulo prioritize Instagrammable environments and participatory entertainment over pure beverage consumption. This behavioral pivot rewards venues investing in immersive design and shareable moment engineering.
Global Bars and Nightclubs Market Segmentation
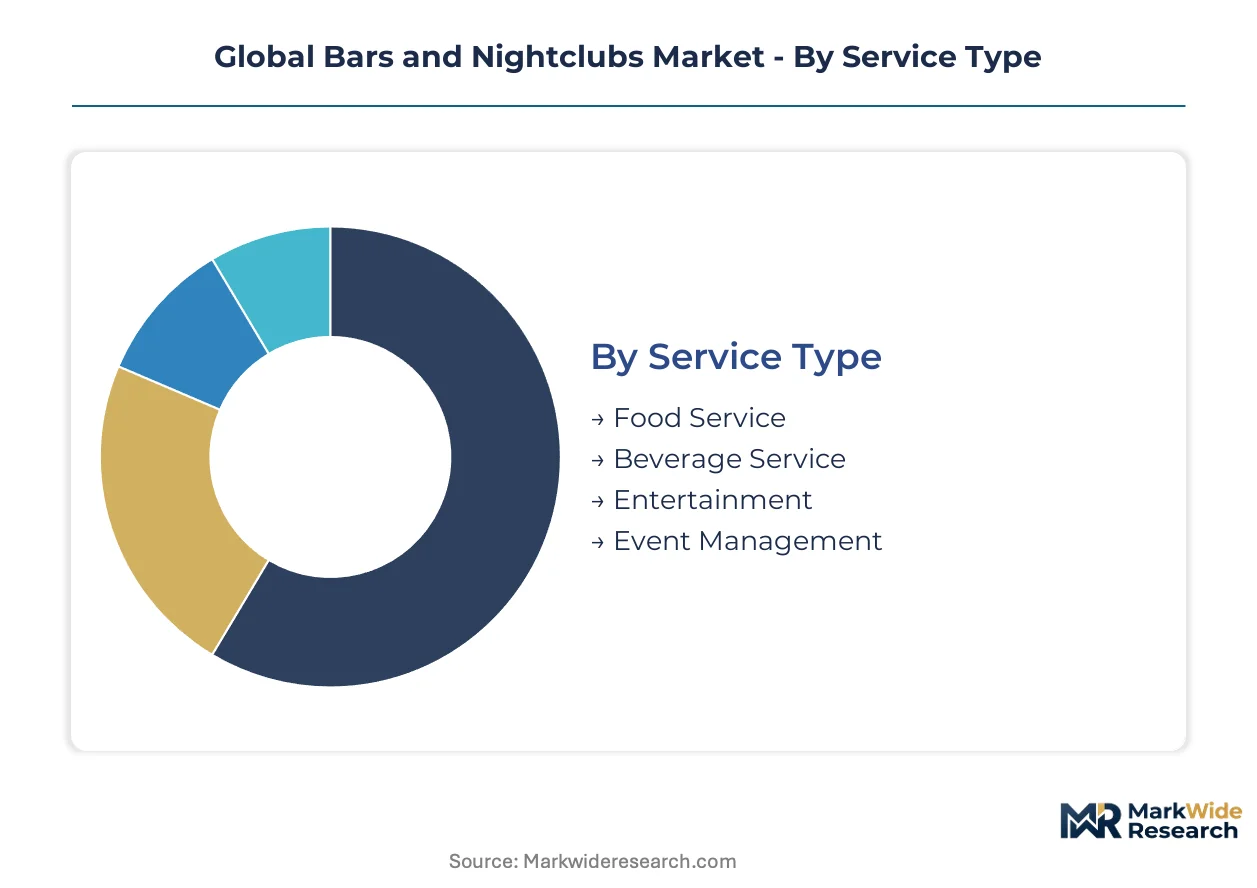
Segmentation in the bars and nightclubs market determines capital allocation, staffing models, and regulatory compliance pathways. Distinct service configurations, customer cohorts, and physical formats each carry divergent margin profiles and occupancy constraints.
Service Type:
Service configurations span consumption-only visits through full-service hospitality experiences, each demanding different labor intensity and licensing frameworks.
- Beverage Service:Alcohol-focused operations generate the highest markup elasticity through spirits, wine, and craft beer programs. Concentrated demand in Barcelona and Madrid nightlife clusters drives premium cocktail investments, though EU F-Gas refrigeration mandates compress equipment replacement cycles.
- Entertainment:Live music, DJ performances, and immersive environments command cover charges and VIP table minimums. Dance-floor venues in Berlin and Amsterdam absorb heavy sound-dampening infrastructure costs to satisfy municipal noise ordinances near residential zones.
- Food Service:Kitchen-equipped operations diversify revenue streams beyond alcohol dependency. FDA protocols and local health-department inspections govern preparation standards across US establishments.
- Event Management:Private bookings and corporate programming stabilize midweek occupancy. Technology and financial services sectors in Singapore and Dubai purchase block reservations for product launches and team entertainment.
Established volume favors Beverage Service; emerging adoption favors Event Management.
Customer Type:
Generational and occupational demographics shape venue design, music programming, and pricing architecture across metropolitan markets.
- Millennials:Urban professionals aged 28-43 prioritize experiential consumption and premium spirits knowledge. London and New York operators target this cohort with craft-cocktail education and curated wine lists.
- Gen Z:Digital-native consumers demand Instagrammable environments and seamless mobile payment integration. Seoul and São Paulo venues invest in shareable moment engineering and QR-code settlement systems.
- Professionals:Corporate clientele seek after-work networking spaces with reliable WiFi and private seating. CBD locations in Tokyo and Sydney capture this demand through business-district proximity.
- Tourists:Transient visitors concentrate in destination nightlife districts with simplified menu structures and multilingual staff. Barcelona's Gothic Quarter and Bangkok's Sukhumvit corridor anchor this segment.
Professional cohorts sustain weekday revenue; tourist flows concentrate weekend capacity.
Atmosphere:
Physical environment design dictates acoustic treatment, ventilation load, and per-square-meter revenue realization.
- Dance Floor:High-capacity formats with professional sound systems and lighting rigs absorb substantial fixed costs. Miami and Ibiza operators deploy AI-driven demand forecasting to optimize bottle-service inventory hour-by-hour.
- Rooftop:Elevated venues exploit underutilized air rights with lower occupancy costs than street-level leases. São Paulo and Mexico City expansion favors this format for panoramic views and natural ventilation.
- Lounge:Seated conversation-focused spaces with lower decibel thresholds suit intimate gatherings and date occasions. Fire-safety certification timelines in Germany and France extend opening schedules for these formats.
- Sports Bar:Broadcast-centric environments with multiple screens and pub-food menus capture game-day traffic. British operators leverage integrated table-management systems to handle surge capacity during football fixtures.
Dance Floor configurations dominate premium pricing; Rooftop formats gain share fastest in high-rent districts.
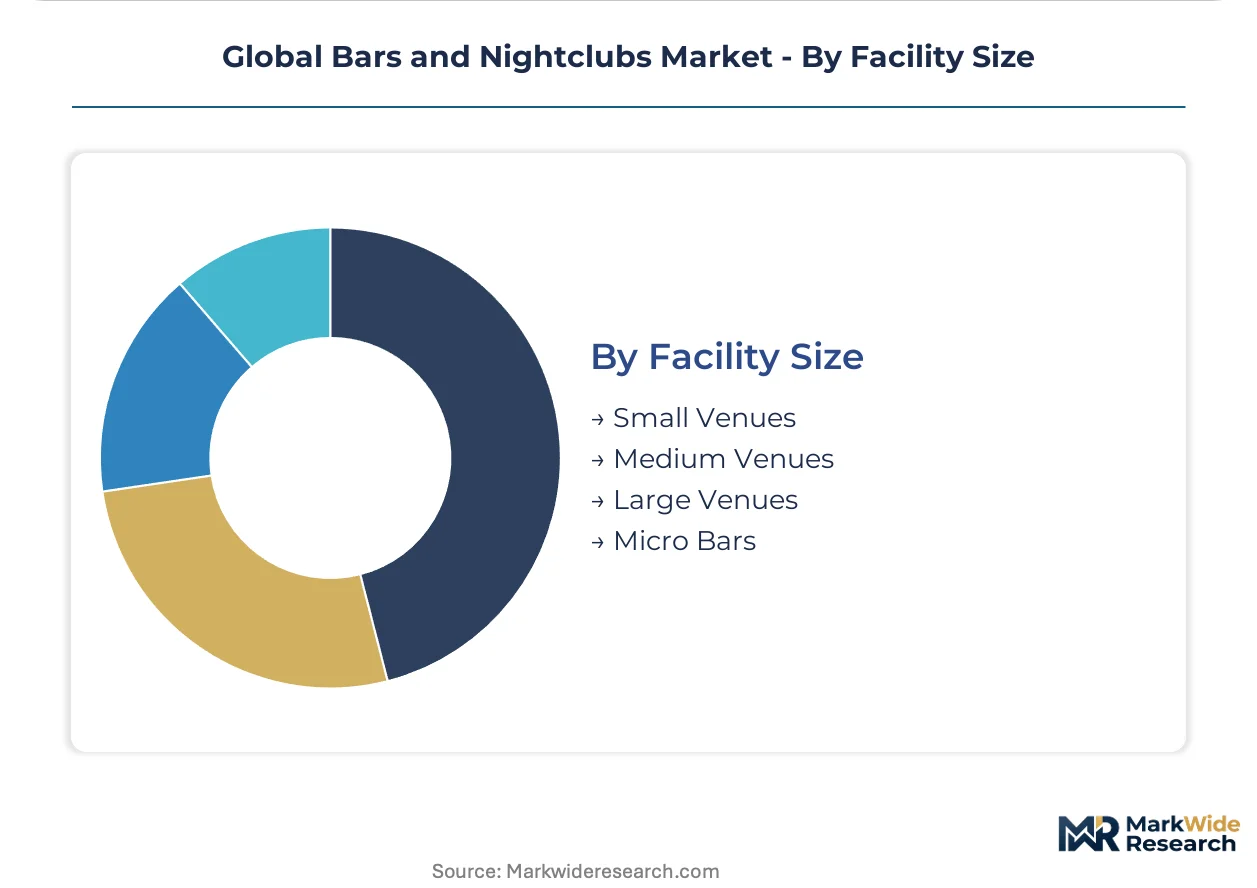
Facility Size:
Scale determines staff-to-guest ratios, corporate event viability, and regulatory complexity thresholds.
- Large Venues:Multi-room establishments with capacity exceeding 500 guests absorb fixed costs through diversified programming and private event contracts. Occupancy limits tie directly to fire-safety codes enforced by municipal authorities.
- Micro Bars:Intimate formats under 50 seats minimize labor overhead in urban real-estate scarcity conditions. Central business district rents in London, New York, and Tokyo consume 25-35% of revenue for these operators.
- Medium Venues:Mid-scale operations balance table service with dance-floor capacity. These configurations suit neighborhood anchors in secondary cities with lower licensing friction.
- Small Venues:Limited-capacity formats emphasize curated experiences and regular clientele relationships. Independent operators in competitive labor markets face pressure from certified mixology talent scarcity.
Large Venues capture corporate contract value; Micro Bars proliferate in rent-constrained districts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for premium spirits packaging concentrates sourcing risk in China and Mexico, while venue investment flows toward Mediterranean and Southeast Asian clusters with favorable licensing frameworks and tourism velocity.
United States
Corporate event contracts from technology and financial services sectors stabilize midweek revenue in New York and Miami. FDA food-safety protocols and EPA commercial ventilation standards govern operating permits across jurisdictions. Miami and Ibiza nightclub operators deploy AI-driven demand forecasting to optimize bottle-service inventory hour-by-hour.
Spain
Barcelona and Madrid nightlife clusters anchor Mediterranean venue investment through concentrated young professional demand and extended-hours licensing. EU F-Gas Regulation phasedown schedules accelerate equipment replacement cycles for refrigeration-dependent beverage service. Barcelona's Gothic Quarter generates dense tourist traffic requiring multilingual staff and simplified menu structures.
United Kingdom
Stonegate Group and JD Wetherspoon plc leverage estate scale to deploy integrated table-management systems across British pub networks. Local alcohol-licensing boards enforce occupancy limits tied to fire-safety codes. London central business district rents consume 25-35% of revenue for micro-bar formats with limited seating capacity.
Germany
Berlin dance-floor venues absorb heavy sound-dampening infrastructure costs to satisfy municipal noise ordinances near residential zones. Fire-safety certification timelines from local authorities extend venue-opening schedules by 4-8 months. Berlin and Hamburg operators face compressed replacement windows for non-compliant ice machines under EU F-Gas Regulation mandates.
Singapore
Technology and financial services sectors purchase block bookings for product launches and team entertainment, stabilizing midweek revenue. The city-state's strict public order frameworks shape venue design and operating hour constraints. Marina Bay and Clarke Quay clusters concentrate premium rooftop and outdoor format investments with panoramic views and natural ventilation advantages.
Global Bars and Nightclubs Market Vendor Landscape
On the supply side, the industry is fragmented across independent operators, regional estate-holders, and multinational hospitality groups with divergent capital access and technology deployment capabilities. Three strategic archetypes dominate: scale-driven estate consolidators controlling in-house supply chains, experience-focused premium hospitality specialists leveraging proprietary guest-data analytics, and cost-optimized neighborhood anchors sustaining volume through standardized formats. Competitive moves concentrate on M&A-driven estate expansion and digital infrastructure integration for reservation and payment platforms.
Within the estate consolidator tier, Stonegate Group and JD Wetherspoon plc exemplify scale-driven operators with extensive British pub networks. Hakkasan Group occupies a position among premium hospitality specialists emphasizing VIP experiences and data-driven service personalization. These three entities represent contrasting strategic postures across cost leadership, differentiation, and experience-focused positioning within licensed premises hospitality.
| Leading Market Players |
|---|
| Stonegate Group |
| Hakkasan Group |
| Mitchells and Butlers plc |
| Applebee's Restaurants LLC |
| Dave & Buster's Entertainment Inc. |
| JD Wetherspoon plc |
| Fuller's Group |
| Revolution Bars Group plc |
| Greene King plc |
| Others |
Supply Flow & Price Mechanics
Guadalajara's glass bottle manufacturing clusters feed premium spirits packaging demand across North American venues, concentrating input cost leverage in Mexican production corridors and amplifying pricing volatility when freight rates spike. This geographic tethering shapes margin structures for beverage service operators who lack backward integration into packaging supply.
Pricing Analysis
Corporate event buyers anchor contract-based pricing structures across large venue formats. Three-tier pricing structure across premium bottle service, standard table minimums, and economy cover charges differentiates by atmosphere type and event timing. Pricing pressure stems from certified mixology talent scarcity in competitive labor markets like New York and London. Independent micro-bar operators exhibit highest price sensitivity due to central business district rent absorption, while estate-scale pub networks sustain lowest sensitivity through in-house procurement control.
Supply Chain Analysis
Glass bottle feedstock draws from concentrated manufacturing bases in Mexico and China, with secondary capacity in Italy and France. Premium spirits packaging, refrigeration equipment compliant with EU F-Gas Regulation, and acoustic dampening materials constitute critical input categories. Tariff exposure on imported packaging from China creates structural vulnerability for US-based operators. Distribution runs through national beverage distributors with direct-to-venue delivery contracts, though micro-bars increasingly source through consolidated procurement cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation phasedown constitutes a regulatory inflection forcing capital redeployment into compliant refrigeration infrastructure, compressing returns for operators with legacy equipment exposure while creating aftermarket service revenue pools for prepared suppliers.
For Market Incumbents: Harden estate-scale competitive positioning through captive supply chain control over food and beverage procurement, mirroring JD Wetherspoon plc's cost architecture. Accelerate GDPR-compliant guest analytics deployment to defend against emerging reservation-platform intermediaries fragmenting customer data ownership. Prioritize fire-safety certification pipeline management to compress venue-opening timelines in German and French jurisdictions.
For New Entrants and Emerging Players: Build out rooftop and outdoor formats in São Paulo, Mexico City, and Bangkok where underutilized urban air rights lower per-square-meter occupancy costs versus street-level leases. Target corporate event management contracts from technology and financial services sectors in Singapore and Dubai, where block booking demand stabilizes midweek revenue. Pursue AI-driven demand forecasting partnerships with high-volume nightclub operators as a differentiated service-layer offering.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because estate-scale operators with integrated table-management systems and in-house supply chains command sustainable cost advantages over fragmented independent competitors. Acquisition targets should demonstrate proprietary guest-data analytics capabilities or dominant positions in Mediterranean nightlife clusters with favorable extended-hours licensing. Monitor EU F-Gas Regulation enforcement intensity as a signal for equipment replacement cycle acceleration and aftermarket service revenue inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| GDPR-Compliant Guest Analytics Deployment | Enables personalized service recovery without violating European privacy frameworks under CNIL and national authority oversight. |
| EU F-Gas Compliant Equipment Replacement | Captures aftermarket service revenue pools as Spanish and Italian operators face compressed replacement windows for refrigeration hardware. |
| Rooftop Format Expansion | Exploits underutilized urban air rights in high-rent districts with natural ventilation advantages and lower occupancy costs. |
| Corporate Event Contract Acquisition | Stabilizes midweek revenue through block bookings from technology and financial services sectors in Singapore and Dubai clusters. |
| Integrated Table-Management System Deployment | Reduces transaction friction and improves tax-audit transparency for municipal licensing boards across British pub networks. |
Methodological Framework
Initial hypotheses were tested against primary input from venue operations directors, beverage procurement managers, municipal licensing officials, and nightlife technology vendors and refined through secondary validation against SEC filings of listed hospitality groups, EU regulatory implementation notices, and national trade association membership data. Bottom-up venue capacity modeling triangulated with top-down metropolitan market sizing across Barcelona, Madrid, London, New York, and Miami clusters.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include service type, customer demographic cohort, atmosphere configuration, and facility size tier. CAGRs were derived from fitted growth curves applied to venue investment flows and equipment replacement cycle data. Forecast inputs incorporated EU F-Gas Regulation phasedown schedules and mobile payment platform adoption velocity.
The forecast holds incumbent behavior within observed patterns; aggressive consolidation moves by private equity-backed estate aggregators would shift outcomes beyond modeled ranges. Cross-checking against national alcohol licensing board permit issuance data and commercial real estate transaction volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Sparkling Red Wine Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
High-End Chinese Spirits Market
Alcoholic Beverages
Wine Cellar Market
Alcoholic Beverages
Global Premium Gin Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
Rotels Market
Alcoholic Beverages
Russia Tequila Market
Alcoholic Beverages
Middle East and Africa Alcoholic Beverage Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Pressurized Wine Filter System Market
Alcoholic Beverages
Malt Whiskey Market