
 White Wine Market | 2026-2036
White Wine Market Size, Share, and Industry Trends Forecast 2026-2036
White Wine Market Intelligence
On-trade hospitality is decoupling from traditional red-dominated wine lists as younger consumers favor lighter, lower-tannin beverages. E&J Gallo Winery leverages its massive California vineyard network to sustain volume leadership in mid-market Chardonnay. Jackson Family Wines anchors its portfolio in premium Sonoma and Napa terroir expressions, while Treasury Wine Estates competes aggressively through Penfolds-branded luxury white releases across Asia-Pacific duty-free channels.
White wine comprises fermented grape juice excluding skin contact during maceration, typically achieving alcohol content between 11.5% and 14% ABV with acidity levels preserved through temperature-controlled stainless steel or neutral oak aging. Its primary commercial purpose spans direct consumption, food pairing, and mixology applications in hospitality settings. Chardonnay dominates value pools in the premium tier across North American and Australian markets, while Sauvignon Blanc from New Zealand's Marlborough region commands outsized margin per hectoliter. Skin fermentation methods, though still marginal, are attracting cellar investment as natural wine positioning gains shelf space in independent retail channels.
EU Green Deal agricultural standards and REACH chemical compliance frameworks shape vineyard input sourcing and export labeling requirements for European producers. The Alcohol and Tobacco Tax and Trade Bureau (TTB) in the United States enforces appellation integrity and sulfite disclosure rules that constrain formulation flexibility for domestic bottlers. Stakeholders must monitor evolving organic certification thresholds and carbon footprint disclosure mandates as procurement criteria tighten across Northern European import markets.
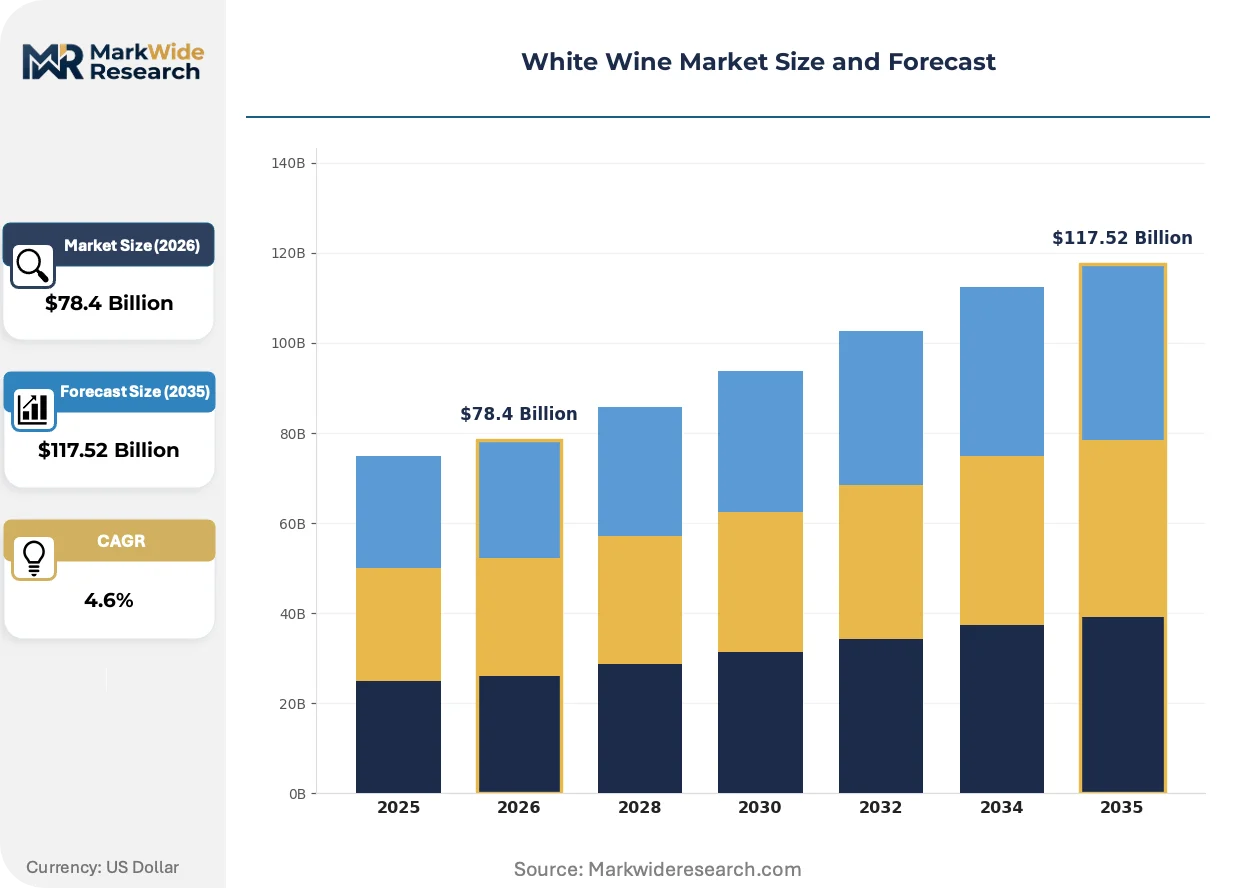
Market Dynamics
EU Green Deal farming standards are redirecting cellar investment toward organic viticulture certification, forcing producers to reconfigure vineyard input sourcing and sulfite management protocols across European supply chains.
Growth Catalysts
- EU Green Deal agricultural standards:Mandatory organic certification thresholds under EU farming regulations are accelerating vineyard conversion rates across France, Italy, and Spain.
- Cocktail culture expansion:On-trade hospitality channels in the United States and Germany are broadening white wine placement beyond traditional red-dominated wine lists.
- Low-intervention winemaking:Skin fermentation methods and natural wine positioning are attracting cellar investment from independent retail channels in urban clusters.
Market Restraints
- Input cost volatility:Stainless steel tank and temperature-control equipment prices fluctuate with energy markets, compressing margin for mid-tier producers.
- Supply concentration risk:Premium Chardonnay grape supply concentrates in California's Central Coast and Sonoma County, exposing buyers to regional climate disruption.
- Regulatory friction:TTB appellation integrity rules and sulfite disclosure requirements in the United States constrain formulation flexibility for domestic bottlers.
Strategic Opportunities
- Underpenetrated duty-free channels:Asia-Pacific airport retail networks present expansion vectors for luxury white wine releases targeting Chinese and Japanese travelers.
- Carbon footprint disclosure mandates:Northern European import markets are tightening procurement criteria around vineyard emissions accounting, rewarding early compliance investments.
- Neutral oak aging convergence:Producers combining temperature-controlled stainless steel with selective oak integration are capturing premium tier price points in Germany and the United States.
Industry Challenges
- Certification timeline compression:EU organic viticulture certification requires multi-year conversion periods that strain working capital for small-scale vineyard operations.
- Talent scarcity in enology:Specialized expertise in low-intervention fermentation techniques remains concentrated in France and Italy, limiting cellar team scaling elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Wine Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $117.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Sauvignon Blanc, Chardonnay, Riesling, Pinot Grigio Production Method: Traditional Method, Carbonic Maceration, Cold Fermentation, Skin Fermentation Price Tier: Premium, Mid-range, Budget, Luxury Packaging Type: Bottle, Tetra Pak, Keg, Canned |
| Companies Covered | Delicato Family Wines, Jackson Family Wines, E&J Gallo Winery, Ste. Michelle Wine Estates, Treasury Wine Estates, The Wine Group, Deutsch Family Wine & Spirits, Bronco Wine Company, Trinchero Family Wine & Spirits, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Wine Market Strategic Shifts & Innovations
Winemaking technology and distribution models are diverging sharply between precision-controlled industrial scale and minimal-intervention artisanal production, with regulatory frameworks accelerating this bifurcation.
Precision fermentation monitoring systems using real-time acidity and temperature sensors are enabling micro-adjustments during crush and aging. Large-scale California and Australian producers are adopting these platforms fastest, integrating them with existing climate-control infrastructure. The technology is expanding into mid-tier facilities previously dependent on manual sampling protocols.
REACH chemical compliance frameworks and EU Green Deal agricultural standards are tightening vineyard input restrictions across European production zones. French and Italian cooperatives are reformulating pest management protocols and sulfite thresholds to maintain export eligibility. Premium tier producers in Burgundy and Piedmont face the steepest reformulation costs.
Direct-to-consumer subscription models are displacing traditional three-tier distribution for boutique labels in the United States and United Kingdom. Urban millennials in London, New York, and San Francisco are driving volume through curated monthly deliveries. This channel rotation is most visible in the premium Sauvignon Blanc segment sourced from New Zealand's Marlborough region.
White Wine Market Segmentation
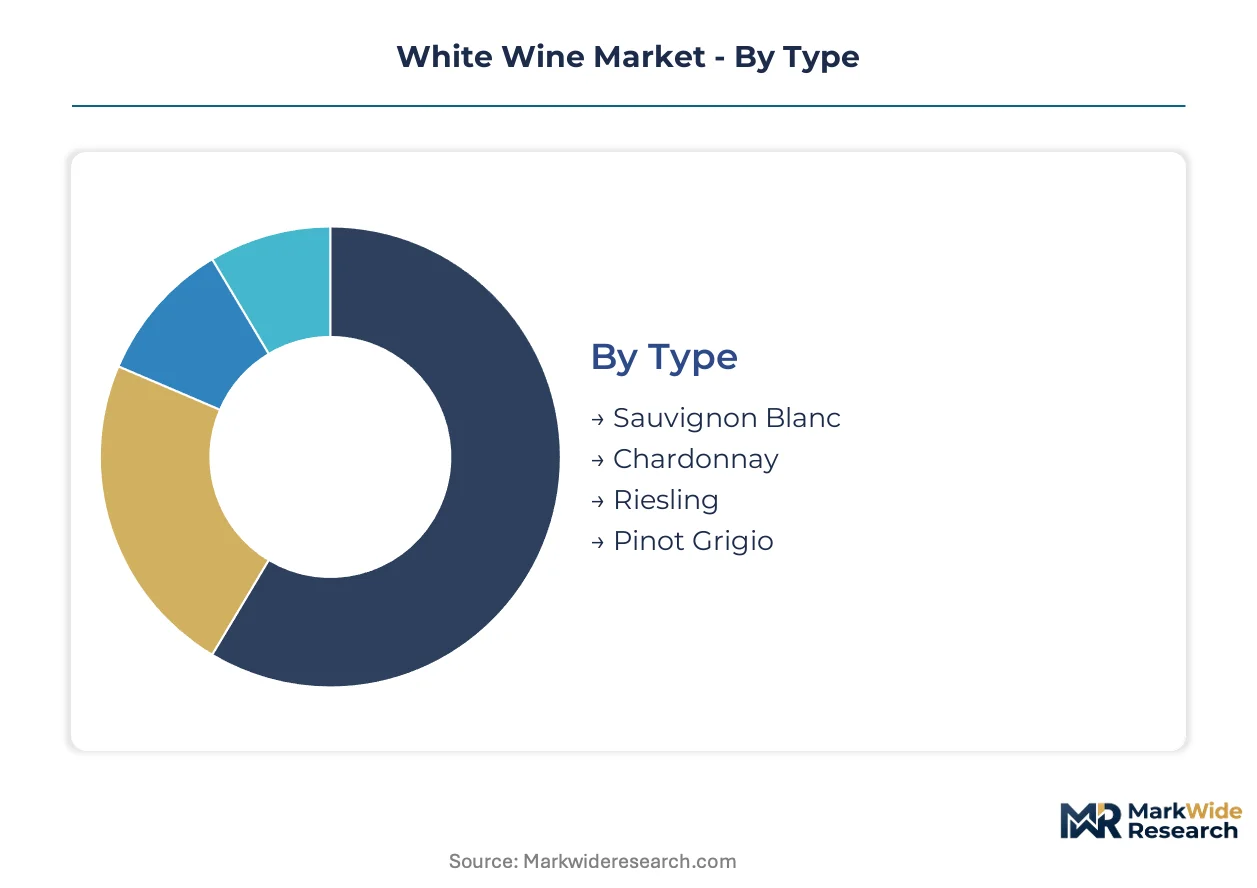
White wine segmentation reflects divergent cellar philosophies and channel economics. Production method and grape variety determine margin architecture, while packaging innovation unlocks new consumption occasions.
Type:
Grape variety selection governs terroir expression and price ceiling potential.
- Chardonnay:Fermented and aged in temperature-controlled stainless steel or neutral oak, achieving 11.5-14% ABV with malolactic conversion options. Demand concentrates in California's Sonoma County and Napa Valley for premium expressions, driven by on-trade cocktail menu expansion in the United States.
- Sauvignon Blanc:High-acid grape variety preserving crisp aromatics through cold fermentation protocols. New Zealand's Marlborough region commands outsized margin per hectoliter, with Chinese and Japanese travelers driving duty-free channel velocity across Asia-Pacific airports.
- Riesling:German-origin variety with pronounced terroir sensitivity and residual sugar versatility.
- Pinot Grigio:Italian-dominant variety produced at volume for mid-tier food pairing applications.
Chardonnay leads on scale; Sauvignon Blanc leads on momentum.
Production Method:
Winemaking technique determines input cost structure and regulatory compliance burden.
- Traditional Method:Temperature-controlled stainless steel or neutral oak aging with standardized sulfite management. Large-scale California and Australian producers deploy precision fermentation monitoring systems for micro-adjustments during crush.
- Skin Fermentation:Extended grape skin contact producing amber or orange wine expressions with elevated tannin structure. Urban independent retail channels in London, New York, and San Francisco are expanding shelf space allocation for natural wine positioning.
- Cold Fermentation:Sub-15°C temperature protocols preserving volatile aromatic compounds.
- Carbonic Maceration:Whole-grape fermentation technique limiting extraction for lighter body profiles.
Traditional Method anchors volume throughput; Skin Fermentation is climbing the fastest.
Price Tier:
Price positioning stratifies across certification grade, volume scale, and performance tier.
- Premium:Sonoma and Napa terroir expressions with appellation integrity verification. Germany and the United States concentrate demand for neutral oak aging convergence.
- Luxury:Limited-release bottlings targeting Asia-Pacific duty-free channels with carbon footprint disclosure compliance.
- Mid-range:Volume-tier positioning for broad retail distribution.
- Budget:Mass-market placement with compressed margin profiles.
Premium captures margin concentration; Luxury is gaining share fastest.
Packaging Type:
Format innovation reshapes distribution economics and consumption occasion access.
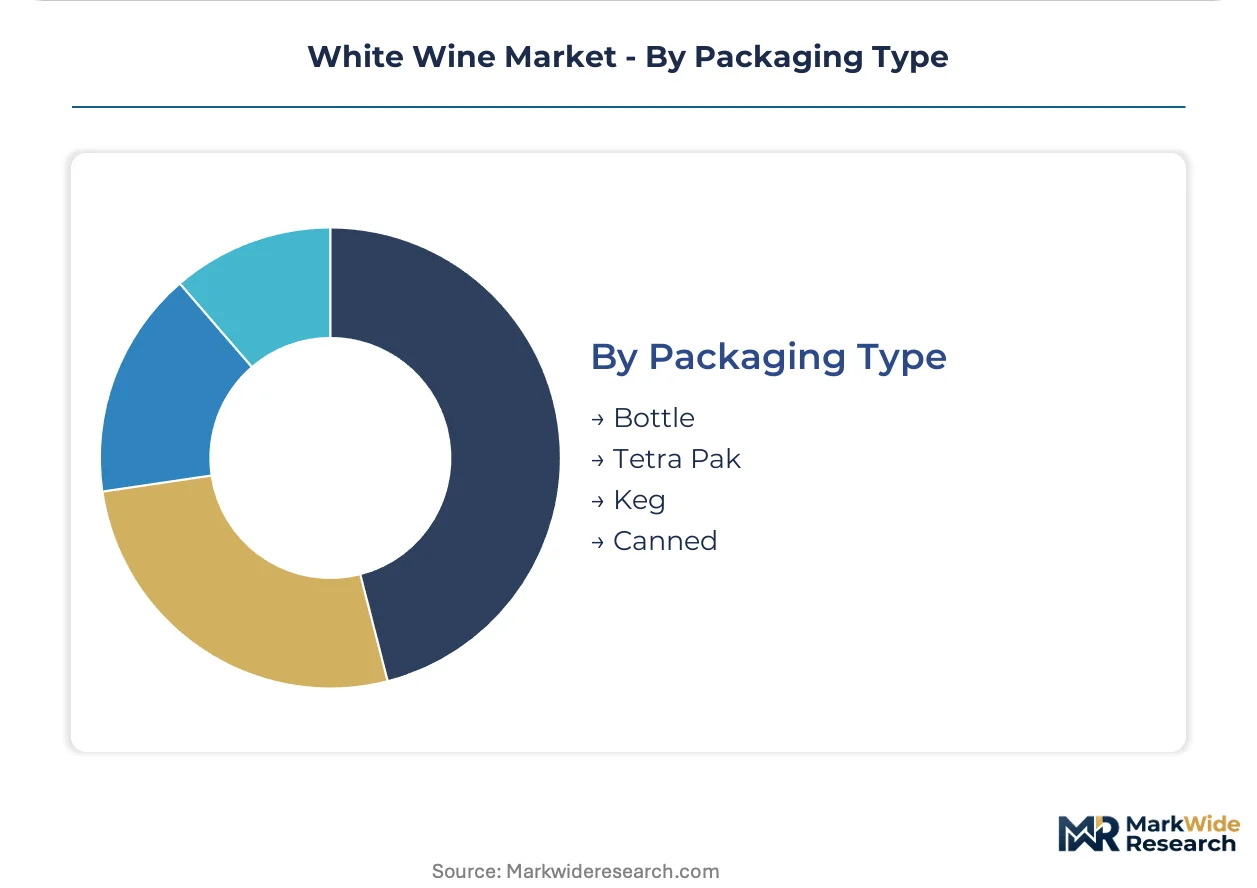
- Bottle:Standard 750ml glass format dominating on-trade hospitality and retail channels. Glass supply chain concentration in Europe shapes procurement patterns for export-oriented producers.
- Canned:Single-serve aluminum format expanding outdoor and casual consumption occasions. United States and United Kingdom urban millennials are driving volume through direct-to-consumer subscription models.
- Tetra Pak:Aseptic carton format for volume retail in price-sensitive markets.
- Keg:Draught format for hospitality on-premise efficiency.
Bottle retains channel dominance; Canned shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sonoma County anchors premium white wine production, with California's Central Coast and Napa Valley forming the dominant North American cluster. Germany's Mosel and Rheingau regions concentrate Riesling expertise, while New Zealand's Marlborough district commands global Sauvignon Blanc margins.
United States
On-trade cocktail menu expansion drives Chardonnay velocity in New York and San Francisco hospitality clusters. TTB appellation integrity rules constrain sulfite disclosure flexibility for domestic bottlers. Sonoma County producers are converging temperature-controlled stainless steel with selective neutral oak integration to capture premium tier price points.
Germany
Residual sugar versatility in Riesling expressions attracts export demand from Northern European import markets. EU Green Deal farming standards mandate organic viticulture certification timelines that strain working capital for small-scale Mosel operations. Rheingau cellars are investing in precision fermentation monitoring systems for micro-adjustments during crush.
New Zealand
Chinese and Japanese travelers drive duty-free channel velocity for Marlborough Sauvignon Blanc across Asia-Pacific airports. The country's national agricultural regulator enforces vineyard input restrictions that align with REACH chemical compliance frameworks for European export eligibility. Wellington-based distributors are expanding direct-to-consumer subscription models for urban millennial segments.
France
Skin fermentation methods for natural wine positioning gain shelf space in Paris and Lyon independent retail channels. EU Green Deal agricultural standards force Burgundy cooperatives to reformulate pest management protocols and sulfite thresholds. Champagne producers are redirecting cellar investment toward low-intervention winemaking techniques.
Australia
Penfolds-branded luxury white releases target Asia-Pacific duty-free expansion vectors. The country's national wine authority enforces carbon footprint disclosure protocols that reward early compliance investments for Northern European procurement criteria. Barossa Valley precision fermentation platforms enable micro-adjustments during crush for large-scale producers.
White Wine Market Key Industry Players
Portfolio diversification dominates the current landscape as producers split resources between precision-controlled industrial scale and minimal-intervention artisanal production. The vendor base concentrates around three strategic archetypes: California-based volume leaders with massive vineyard networks, premium terroir specialists anchored in Sonoma and Napa, and Asia-Pacific luxury exporters leveraging duty-free channel velocity. M&A activity and capacity expansion in organic viticulture certification represent the dominant competitive moves.
Among California-based producers, E&J Gallo Winery and Jackson Family Wines exemplify divergent scale-positioning archetypes, while Treasury Wine Estates occupies the Asia-Pacific luxury export tier. These three entities represent the spectrum from volume-tier Chardonnay throughput to premium terroir expression to duty-free branded luxury releases.
| Leading Market Players |
|---|
| Delicato Family Wines |
| Jackson Family Wines |
| E&J Gallo Winery |
| Ste. Michelle Wine Estates |
| Treasury Wine Estates |
| The Wine Group |
| Deutsch Family Wine & Spirits |
| Bronco Wine Company |
| Trinchero Family Wine & Spirits |
| Others |
Cost & Logistics Intelligence
Stainless steel tank procurement costs cascade from energy-intensive manufacturing hubs through California and Australian cellar operations into premium-tier bottle pricing, with temperature-control equipment volatility compressing margins for mid-market Chardonnay producers unable to pass through input spikes.
Pricing Analysis
Distributor margin layering in three-tier US markets separates on-trade hospitality markups from direct-to-consumer subscription discounts, with price differentiation anchored in appellation integrity verification and organic certification grade. Pricing pressure stems from EU Green Deal compliance investments that small-scale Mosel and Rheingau operations struggle to amortize. Budget-tier buyers in mass retail channels exhibit highest price sensitivity, while luxury duty-free purchasers in Asia-Pacific airports show lowest elasticity.
Supply Chain Analysis
Enology talent scarcity in named manufacturing geographies—France, Italy, and emerging California clusters—constrains cellar team scaling for low-intervention fermentation techniques. Supply concentrates in California's Central Coast and Sonoma County for premium Chardonnay, New Zealand's Marlborough district for Sauvignon Blanc, and Germany's Mosel for Riesling. Raw material dependencies include temperature-control equipment, neutral oak barrels, and stainless steel fermentation vessels. Single-source vulnerability runs through concentrated glass bottle manufacturing in Europe. Distribution runs through three-tier wholesale networks in the United States and direct-to-subscriber models in urban UK and US clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The white wine market reads as a late-cycle quality story, justified by demand-shift toward premium terroir expressions with verified carbon footprint disclosure and organic certification credentials across Northern European import markets.
For Market Incumbents: Deploy precision fermentation monitoring systems to defend yield consistency against climate disruption threats in Sonoma and Napa County supply zones. Anchor capacity addition in certified organic vineyard blocks to preempt EU Green Deal procurement lockout. Capture distributor margin compression through direct-to-consumer subscription channel control in London, New York, and San Francisco urban clusters. For New Entrants and Emerging Players: The premium-to-mid-range price-point gap offers white-space entry for skin fermentation specialists targeting independent retail allocation in Paris, Lyon, and Berlin natural wine scenes. Penetrate Asia-Pacific duty-free velocity through Marlborough Sauvignon Blanc alternatives with Japanese traveler marketing alignment. Pursue go-to-market partnership with curated subscription platforms rather than three-tier wholesale buildout. For Investors and Strategic Acquirers: Consolidation pressure builds where organic certification timeline compression strains working capital for small-scale Mosel, Rheingau, and Burgundy cooperatives. Long-term viability favors targets with captive vineyard supply and early EU Green Deal compliance investment. Watch carbon footprint disclosure mandate adoption rates across Northern European import markets as inflection signal for procurement criteria tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Viticulture Certification Investment | EU Green Deal compliance secures export eligibility for French and Italian cooperatives into Northern European procurement channels. |
| Precision Fermentation Technology Deployment | Real-time acidity sensors enable micro-adjustments that protect yield consistency in California and Australian large-scale cellars. |
| Direct-to-Consumer Subscription Launch | Curated monthly deliveries bypass three-tier margin layering for urban millennial segments in London and New York. |
| Asia-Pacific Duty-Free Channel Expansion | Airport retail networks capture Chinese and Japanese traveler velocity for Marlborough Sauvignon Blanc and Penfolds-branded luxury releases. |
| Carbon Footprint Disclosure Program | Early compliance investments reward producers with preferred supplier status under tightening Northern European procurement criteria. |
Research Approach
Bottom-up on-trade hospitality and retail channel modeling reconciled against top-down vineyard acreage and crush volume tracking forms the analytical core. Primary interviews with cellar masters, enology directors, distributor procurement leads, and independent retail buyers in Paris, London, and San Francisco combined with secondary validation from EU Green Deal regulatory filings, TTB appellation integrity records, and customs export data. Triangulation across stakeholder inputs and trade databases anchors volume and value estimates.
Input-output matrices map grape variety supply through production method tiers into price tier and packaging format demand across the projection horizon. Segmentation dimensions include grape variety, production technique, certification grade, and channel format. CAGRs derive from vintage-to-vintage shipment velocity analysis and acreage conversion trajectory modeling. Forecast inputs incorporate EU organic certification timeline data and Asia-Pacific traveler arrival patterns.
Caveats apply where climate disruption in California's Central Coast, EU regulatory threshold revisions, or carbon disclosure mandate acceleration could materially shift the outlook. Forecasts reflect assumptions around organic conversion rates and duty-free channel recovery velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Premium Wine Cooler Market
Alcoholic Beverages
United States Tequila Market
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
Wine Cellar Market
Alcoholic Beverages
North America Soju Market
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
Spirit-Based RTD Mixes Market
Alcoholic Beverages
Ready to Drink Cocktails Market
Alcoholic Beverages
Asia-Pacific Tequila Market
Alcoholic Beverages
Beer Filter System Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Chardonnay Market
Alcoholic Beverages
Beer Brewing Machine Market
Alcoholic Beverages
Europe Alcoholic Beverage Market
Alcoholic Beverages
Chocolate Beer Market
Alcoholic Beverages
Instant Wine Chillers and Refreshers Market