
 Lager Market | 2026-2036
Lager Market Size, Share, and Industry Trends Forecast 2026-2036
Lager Market Intelligence
Premium lager tier is collapsing the mass-market price floor as consumers trade up from economy labels. Anheuser-Busch InBev leverages its vertical integration into barley sourcing and can manufacturing to protect margin pools across Latin America. Heineken N.V. anchors its position through zero-alcohol lager R&D intensity in European markets. Carlsberg Group differentiates via its water stewardship certifications and localized brewing footprints in Asian growth corridors.
Lager denotes a bottom-fermented beer produced at 7-13°C using Saccharomyces pastorianus yeast, yielding a clean, crisp profile with 4-6% ABV and extended cold maturation of 4-12 weeks for flavor stability. Pilsner dominates volume globally due to its neutral palate and scalable production economics, while craft Helles variants capture expanding margin pools in urban on-trade channels across North America and Western Europe. Can packaging is displacing glass fastest in off-trade and e-commerce segments, driven by weight logistics and recycling loop efficiency.
FDA labeling rules and TTB alcohol content disclosures shape product formulation and interstate distribution compliance for US brewers, while the EU Green Deal packaging waste framework and REACH chemical standards govern material substitution across European production lines. China's SAMR enforces GB standards on alcoholic beverage labeling and additive thresholds for domestic and imported lagers alike. Stakeholders must monitor how diverging national deposit-return schemes and carbon border adjustments reshape packaging cost structures and export market access.
Market Dynamics
The EU Green Deal packaging waste directives are forcing brewers to reformulate materials and logistics, compressing legacy glass supply chains while accelerating aluminum can adoption across European and Latin American distribution networks.
Growth Catalysts
- EU Green Deal packaging mandates:Deposit-return schemes in Germany and the Netherlands are driving can format conversion, reducing per-unit logistics costs for brewers serving supermarket chains.
- Zero-alcohol lager R&D intensity:European health-conscious consumers are pulling alcohol-free variants into mainstream bar and restaurant menus, expanding addressable occasions beyond traditional beer consumption.
- Brazil urban off-trade concentration:São Paulo and Rio de Janeiro supermarket chains are consolidating procurement, favoring canned formats with superior shelf-life and recycling loop efficiency.
Market Restraints
- Barley input cost volatility:Climate-driven harvest variability in Australia and Argentina is compressing margin predictability for brewers without captive grain sourcing.
- Glass supply concentration:European container glass production clusters in Germany and Italy face energy cost spikes, creating bottle availability bottlenecks during peak summer demand windows.
- Extended cold maturation requirements:The 4-12 week lagering cycle constrains inventory velocity and working capital efficiency versus ale production economics.
Strategic Opportunities
- Asian growth corridor localization:Vietnam and Thailand present underpenetrated premium lager white space where water stewardship certifications differentiate imported and locally-brewed portfolios.
- E-commerce direct-to-consumer channels:Specialty retailers in North America are building subscription models for craft Helles variants, bypassing traditional three-tier distribution markups.
- Carbon border adjustment readiness:Early compliance with embedded emissions accounting positions EU-based brewers for preferential access to UK and Swiss markets post-2026.
Industry Challenges
- Master brewer talent scarcity:Traditional lager fermentation expertise is concentrating among aging European specialists, constraining quality consistency at new Asian and Latin American production facilities.
- Multi-format packaging line capex:Simultaneous glass, can, and keg production requires flexible filling equipment investments that strain mid-capitalization brewery balance sheets.
- REACH chemical compliance timelines:ECHA substance restrictions on coatings and inks are forcing reformulation cycles that delay new product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lager Market |
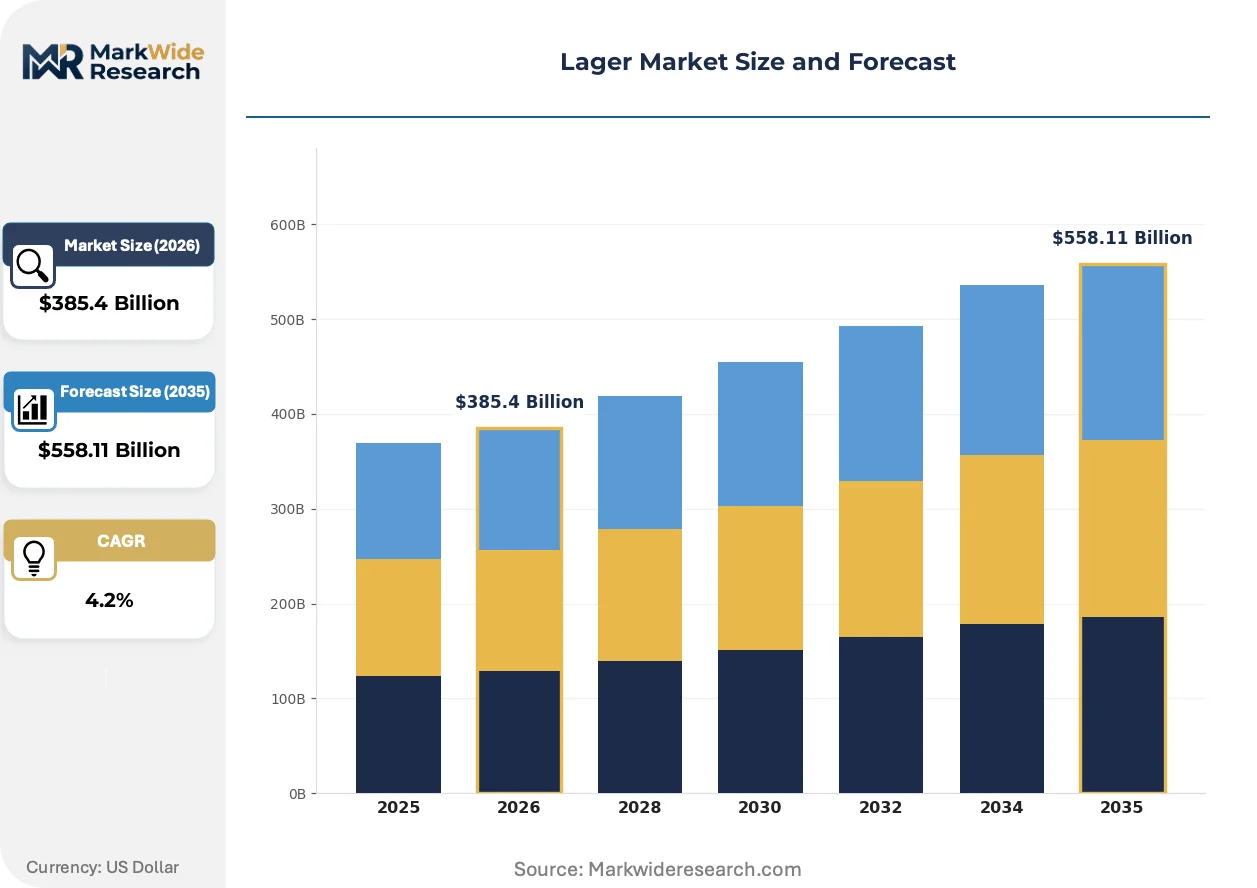
| Market Size in 2026 | $385.4 Billion |
| Market Size in 2035 | $558.11 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pilsner, Helles, Bock, Märzen Packaging Type: Bottle, Can, Keg, Draft Sales Channel: On-trade, Off-trade, E-commerce, Wholesaler End User: Retail Consumers, Bars, Restaurants, Events |
| Companies Covered | Anheuser-Busch InBev, Heineken N.V., Carlsberg Group, Molson Coors Beverage Company, China Resources Snow Breweries, Tsingtao Brewery Company Limited, Asahi Breweries, Kirin Brewery Company Limited, Diageo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lager Market Strategic Shifts & Innovations
Active packaging material substitution and fermentation process digitization are compressing traditional production timelines while regulatory carbon accounting is embedding emissions transparency into brand positioning.
Aluminum can packaging is displacing glass bottles in off-trade and e-commerce segments. German supermarket chains and Brazilian hypermarkets are consolidating procurement around lightweight recyclable formats. This shift is compressing logistics cost structures and enabling direct-to-consumer shipping economics previously blocked by breakage rates.
EU Green Deal packaging waste directives are mandating extended producer responsibility across European production lines. Brewers face material substitution deadlines for non-recyclable label adhesives and composite closures. German and Dutch facilities are responding with closed-loop can recycling partnerships and deposit-return scheme integration.
Urban on-trade buyers are rotating procurement toward craft Helles and Pilsner variants with localized brewing footprints. North American bars and restaurants are displacing multinational economy labels with regional brewery portfolios. This preference shift is most visible in Denver, Portland, and Brooklyn where taproom density supports just-in-time keg delivery models.
Lager Market Segmentation
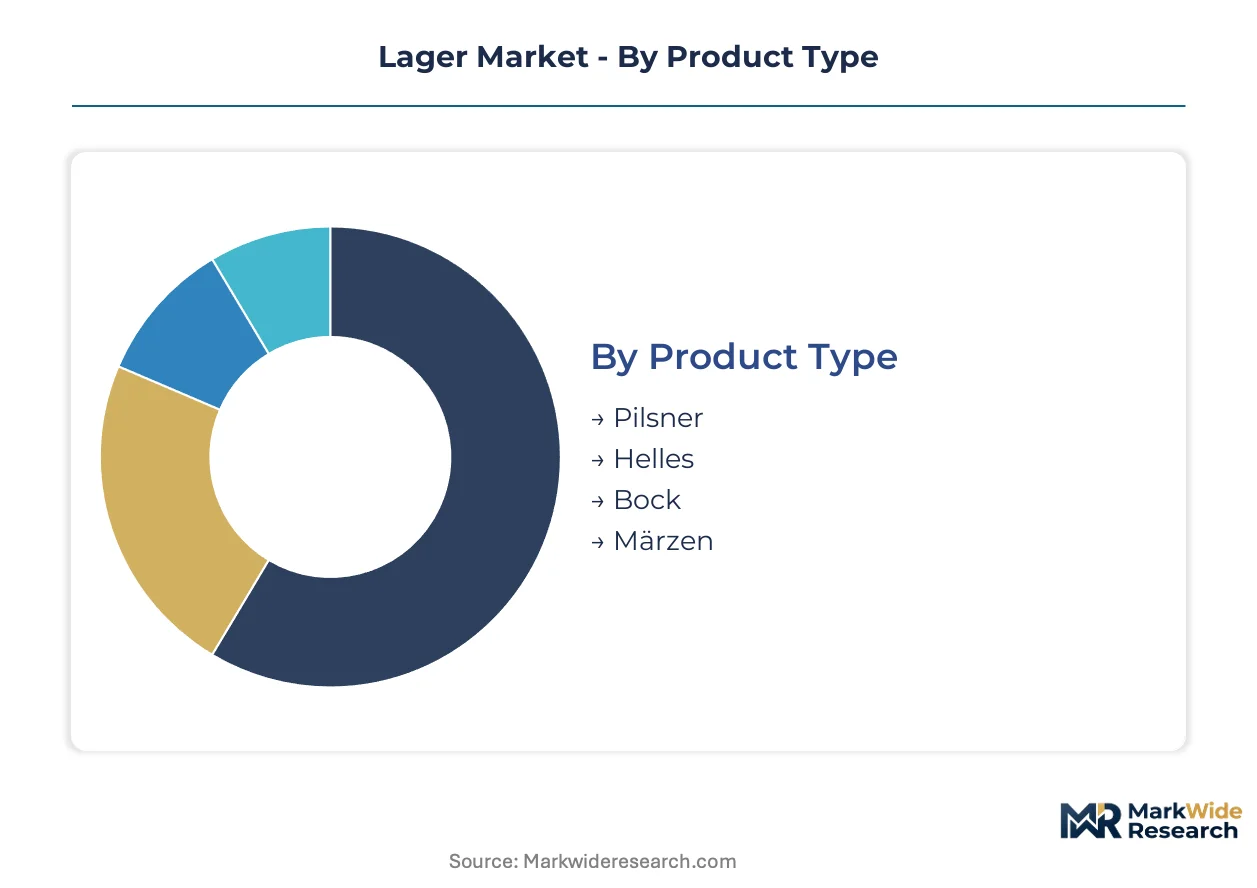
Segmentation in the lager market reveals how margin pools concentrate around format innovation and channel control. Brewers align production capacity with packaging flexibility and distribution reach to capture value across diverging consumption occasions.
Product Type:
Pilsner commands the deepest margin pools through scalable production economics and universal palate acceptance, while craft variants extract premium pricing in urban on-trade channels.
- Pilsner:Bottom-fermented at 7-13°C with Saccharomyces pastorianus yeast, delivering 4-6% ABV and neutral flavor profile suited to mass-market scale. Brazilian supermarket chains and German beverage retailers concentrate procurement around this format for inventory velocity and cross-brand substitution flexibility.
- Helles:Munich-style pale lager with softer malt sweetness and 4.7-5.4% ABV, requiring extended cold maturation of 4-12 weeks for clarity. Denver, Portland, and Brooklyn bars are rotating taps toward regional craft Helles portfolios, displacing multinational economy labels through just-in-time keg delivery models.
- Bock:Strong lager tradition at 6.3-7.2% ABV with pronounced malt backbone, seasonally concentrated in German-speaking markets.
- Märzen:Amber-hued Oktoberfest style with toasted malt character, tied to autumn event consumption in Bavaria and Austrian brewing regions.
Pilsner holds installed capacity. Helles is rotating up the share rankings.
Packaging Type:
Format selection determines logistics cost structures and recycling loop participation, with lightweight alternatives gaining shelf-space negotiations.
- Can:Aluminum format displacing glass fastest in off-trade and e-commerce segments, driven by weight logistics and recycling loop efficiency. São Paulo and Rio de Janeiro hypermarkets consolidate procurement around cans for superior shelf-life and direct-to-consumer shipping economics.
- Bottle:Glass container facing availability bottlenecks from European production concentration in Germany and Italy, where energy cost spikes constrain peak summer supply.
- Keg:Stainless steel returnable format anchoring on-trade volume in urban taproom corridors with high outlet density.
- Draft:Direct-draw systems in bars and restaurants requiring specialized dispensing infrastructure and line maintenance protocols.
Can holds installed capacity. Draft is rotating up the share rankings.
Sales Channel:
Channel control separates brewers with direct retail relationships from those dependent on intermediary markups.
- On-trade:Bars, restaurants, and licensed premises where tap placement and rotation agreements determine volume allocation. German and Dutch deposit-return scheme integration is compressing traditional three-tier distribution economics.
- Off-trade:Supermarket and hypermarket chains consolidating procurement power around canned formats with extended shelf stability.
- E-commerce:Direct-to-consumer subscription models for craft Helles variants in North America, bypassing wholesale markups through specialty retailer platforms.
- Wholesaler:Traditional three-tier intermediaries maintaining regulatory compliance and route-to-market access in fragmented state-level jurisdictions.
Off-trade holds installed capacity. E-commerce is rotating up the share rankings.
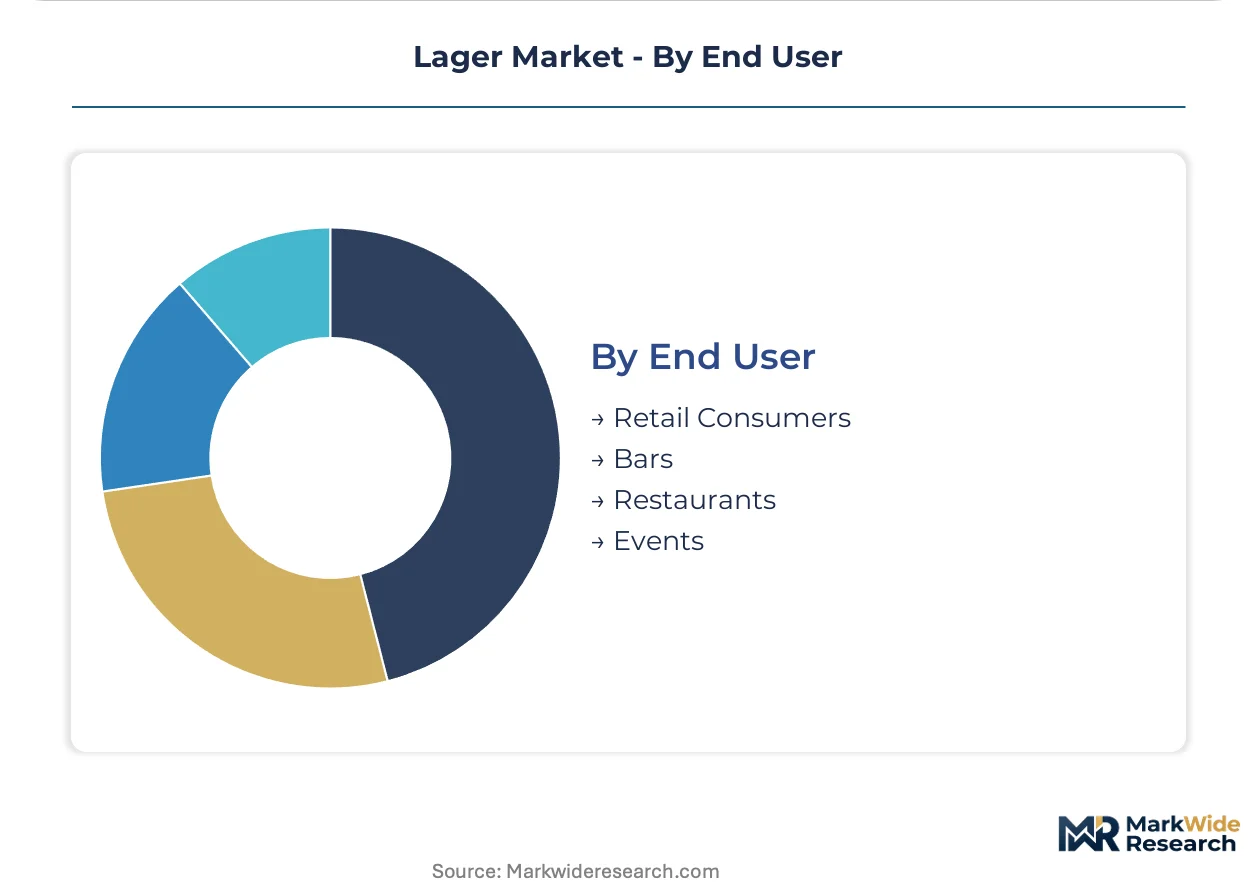
End User:
End-user concentration shapes product formulation, packaging mix, and service level requirements across diverging consumption contexts.
- Retail Consumers:Individual purchasers selecting from off-trade and e-commerce assortments based on price tier, format convenience, and brand recognition.
- Bars:On-trade outlets rotating tap portfolios toward craft Helles and localized brewing footprints in Denver, Portland, and Brooklyn corridors.
- Restaurants:Food-service establishments pairing lager selections with menu positioning, where zero-alcohol variants expand addressable occasions beyond traditional beer consumption.
- Events:Stadium, festival, and concert venues requiring high-volume can and draft logistics with temporary infrastructure deployment.
Retail Consumers hold installed capacity. Restaurants are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian supermarket chains demand economy-tier pricing that compresses margins, while German on-trade buyers absorb premium craft Helles markups with minimal volume elasticity.
Germany
Bavarian brewing traditions anchor craft Helles demand in Munich and Berlin taproom corridors. The EU Green Deal packaging waste directives force deposit-return scheme compliance across German production lines. Stuttgart and Hamburg facilities are converting glass lines to aluminum can formats to meet 2025 material substitution deadlines.
Brazil
São Paulo and Rio de Janeiro hypermarkets are consolidating procurement around canned lagers with extended shelf stability. ANVISA enforces labeling standards on alcoholic beverage alcohol content and additive thresholds. Southern Brazil's Rio Grande do Sul state hosts expanding malting capacity to reduce import dependency for barley inputs.
United States
Denver, Portland, and Brooklyn bars rotate taps toward regional craft Helles portfolios displacing multinational economy labels. FDA labeling rules and TTB alcohol content disclosures shape interstate distribution compliance. Pacific Northwest brewing clusters are building subscription e-commerce models bypassing traditional three-tier wholesale markups.
China
Urban tier-one cities concentrate premium lager demand as middle-class consumers trade up from mass-market labels. SAMR enforces GB standards on alcoholic beverage labeling and additive thresholds for domestic and imported products. Yangtze River Delta brewing facilities are localizing production to capture margin pools previously served by imports.
Vietnam
Ho Chi Minh City and Hanoi on-trade channels present underpenetrated premium lager white space with expanding taproom density. The country's national food safety regulator monitors additive thresholds and labeling compliance for domestic and imported beers. Mekong Delta water stress is driving brewer investment in stewardship certifications that differentiate portfolios.
Lager Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the lager market structure. Mass-market scale operators concentrate barley sourcing and can manufacturing through backward integration, while craft specialists compete on fermentation expertise and localized brewing footprints. Two strategic archetypes dominate: vertically integrated multinational brewers controlling upstream supply chains, and regional craft operators leveraging just-in-time keg delivery models. Competitive moves center on portfolio diversification into zero-alcohol variants and geographic expansion through Asian growth corridor localization.
Within the multinational tier, Anheuser-Busch InBev, Heineken N.V., and Carlsberg Group occupy positions representing scale-driven archetypes with captive grain sourcing and aluminum can production integration. These entities exemplify the vertically integrated model that protects margin pools across Latin American and European distribution networks. Their positioning reflects the structural advantage of controlling input costs through upstream supply chain ownership rather than market procurement.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Heineken N.V. |
| Carlsberg Group |
| Molson Coors Beverage Company |
| China Resources Snow Breweries |
| Tsingtao Brewery Company Limited |
| Asahi Breweries |
| Kirin Brewery Company Limited |
| Diageo |
| Others |
Cost & Logistics Intelligence
Installed brewing capacity in Germany and Brazil generates scale economies that compress per-unit production costs while simultaneously concentrating supply-side bargaining power among maltsters and aluminum suppliers. This dual concentration creates asymmetric price floors where mass-market Pilsner margins tighten faster than craft Helles premiums expand.
Pricing Analysis
The EU Green Deal packaging waste directives dictate the pricing tier structure across European production lines, mandating material substitution investments that propagate through premium-mid-economy pricing differentiation. Quality grade and water stewardship certification level separate craft Helles commanding taproom markups from economy Pilsner facing Brazilian supermarket procurement consolidation. Cost compression in economy tiers is intensifying because São Paulo hypermarkets are consolidating volume around canned formats with extended shelf stability. Retail consumers selecting from off-trade assortments exhibit highest price sensitivity, while Brooklyn and Portland bars absorbing regional craft portfolios show minimal volume elasticity to markup increases.
Supply Chain Analysis
Strait of Malacca transit underwrites barley shipment routes from Australia and Argentina to Asian brewing facilities, creating logistics chokepoint exposure for brewers without captive grain sourcing. Supply concentrates in Germany, Brazil, and China for malting capacity, aluminum can manufacturing, and brewing equipment fabrication respectively. Raw material dependencies rest on Australian barley harvests, German glass container production, and Chinese aluminum smelter output. Single-source vulnerability runs through European container glass clusters in Germany and Italy facing energy cost spikes. Distribution runs through three-tier wholesale intermediaries in fragmented US state-level jurisdictions and direct-to-consumer e-commerce subscription models in Pacific Northwest brewing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
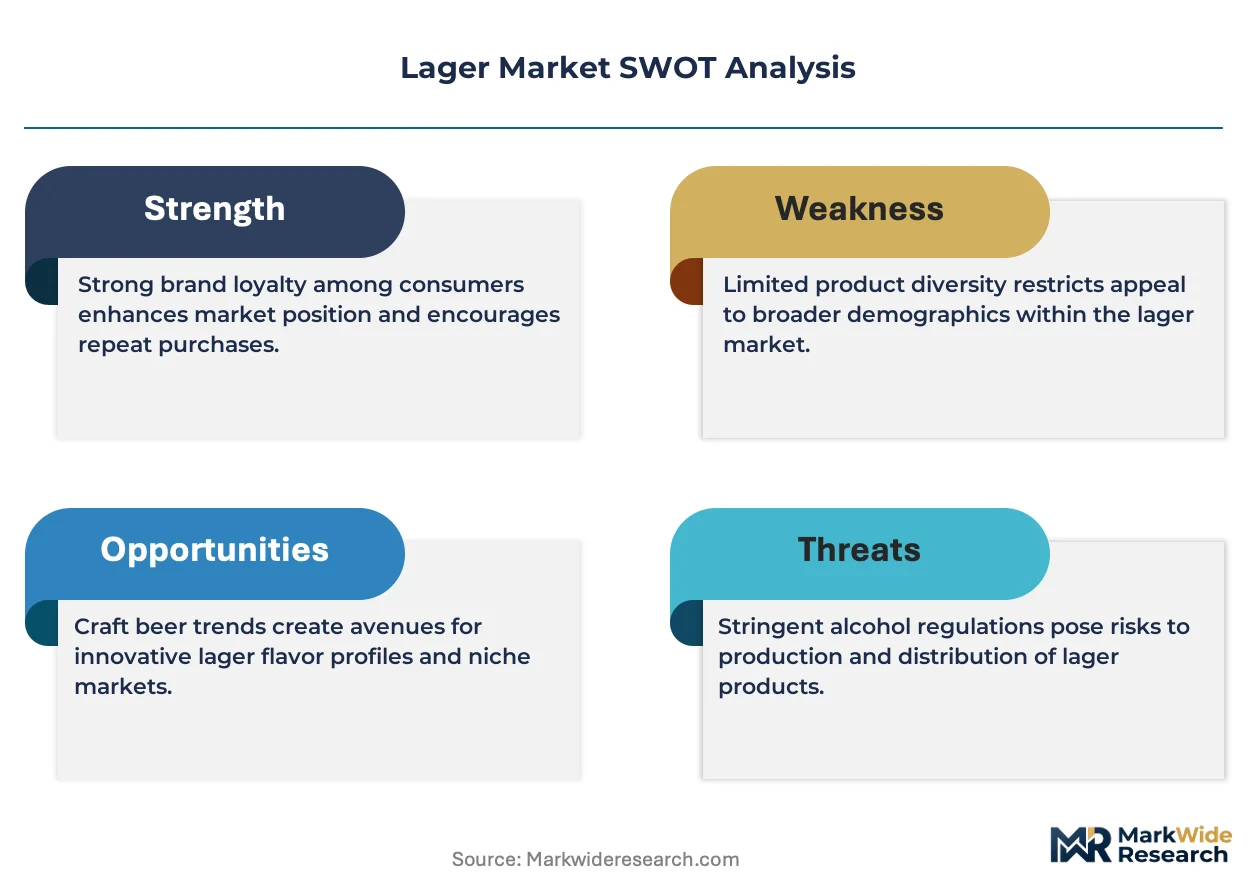
The lager market functions as a defensive-moat story anchored in regulatory entrenchment: TTB labeling compliance and EU Green Deal material substitution deadlines create fixed-cost barriers that entrench incumbents against craft upstarts lacking compliance infrastructure.
For Market Incumbents: Secure backward integration into barley sourcing and can manufacturing to protect margin pools across Latin American distribution networks against climate-driven harvest variability. Anchor capacity addition in Vietnam and Thailand growth corridors where water stewardship certifications differentiate portfolios and localized brewing footprints reduce import dependency exposure. For New Entrants and Emerging Players: Differentiate on fermentation expertise scarcity by recruiting aging European master brewers to anchor quality consistency at new Asian production facilities. Target underpenetrated premium lager white space in Ho Chi Minh City and Hanoi on-trade channels through just-in-time keg delivery models bypassing traditional three-tier wholesale markups. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among craft specialists with subscription e-commerce channels and taproom direct-to-consumer relationships. Long-term viability over the next decade hinges on packaging format flexibility and carbon border adjustment readiness. Acquisition target archetype: regional craft operators with localized brewing footprints and water stewardship certifications. The signal to watch as inflection indicator is deposit-return scheme expansion beyond Germany and Netherlands into additional EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Alcohol Lager R&D Intensity | Heineken N.V. anchors European positioning through alcohol-free variant development expanding addressable consumption occasions. |
| Asian Growth Corridor Localization | Vietnam and Thailand facilities capture margin pools previously served by imports while mitigating Mekong Delta water stress exposure. |
| E-Commerce Direct-to-Consumer Launch | Pacific Northwest brewing clusters bypass three-tier distribution markups through specialty retailer subscription platforms. |
| Aluminum Can Format Conversion | German and Dutch facilities meet EU Green Deal material substitution deadlines through closed-loop recycling partnerships. |
| Water Stewardship Certification Investment | Carlsberg Group differentiates portfolios in Asian growth corridors where Mekong Delta stress elevates resource transparency value. |
Research Approach
The analysis maps Pilsner, Helles, Bock, and Märzen sub-sectors, each validated through master brewers, procurement leads at supermarket chains, distribution channel partners, and regulatory affairs directors. Primary interviews with these stakeholders combined with secondary validation from FDA labeling filings, EU Green Deal directive texts, ANVISA regulatory databases, and SAMR GB standards documentation. Bottom-up volume modeling and top-down value triangulation cross-checked against customs trade data and brewery capacity disclosures.
Consistency checks validated outputs against external benchmarks including aluminum can manufacturing capacity reports and barley harvest estimates from Australian and Argentine agricultural agencies. The analytical framework segments by product type, packaging format, sales channel, and end-user across the projection horizon. CAGRs derived from installed capacity utilization trajectories and format conversion velocity assumptions. Forecast inputs include deposit-return scheme adoption timelines and carbon border adjustment mechanism implementation patterns.
Forecasts assume regulatory continuity in FDA, TTB, EU Green Deal, REACH, and SAMR regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as climate-driven barley harvest variability and energy cost spikes in European glass manufacturing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Wine Bags Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
North America Mezcal Market
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Sake and Plum Wine Market
Alcoholic Beverages
Stemware Market
Alcoholic Beverages
Coffee Beer Market
Alcoholic Beverages
Scotch Whisky Market
Alcoholic Beverages
Puncheon Barrel Market
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
Beer Dispensing Machine Market