
 Citrus Oil Market | 2026-2036
Citrus Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Oil Market Analysis
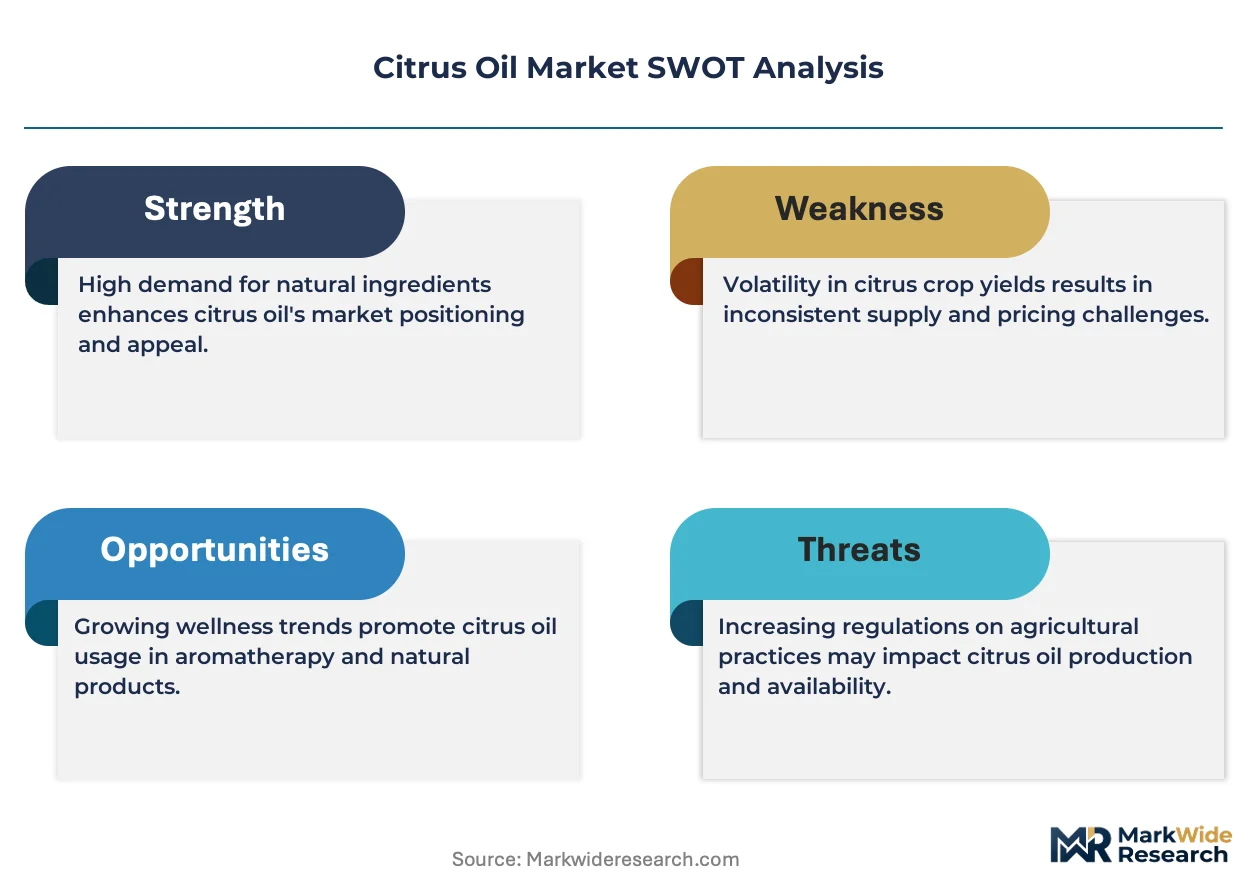
Buyer concentration in the citrus oil market is broadening as mid-sized personal care and specialty food manufacturers diversify supply sources beyond traditional flavor houses. Symrise AG leverages integrated botanical supply chains across Mediterranean growing regions to secure consistent raw material flows. Givaudan SA sustains leadership in cold-pressed orange oil applications through dedicated agronomy partnerships with Brazilian cooperatives. Lionel Hitchen Essential Oils Ltd. anchors its position in European pharmaceutical-grade citrus derivatives via distillation expertise honed over decades.
Citrus oil comprises volatile aromatic compounds extracted from citrus fruit peels, primarily limonene, pinene, and citral, yielding concentrated essences through mechanical cold pressing or steam distillation for flavor, fragrance, and antimicrobial applications. Orange oil dominates volume flows due to its cost-efficient extraction from abundant processing byproducts, while grapefruit oil commands premium positioning in niche aromatherapy channels where therapeutic-grade certification limits supply elasticity. Solvent extraction occupies a shrinking share as clean-label preferences push brands toward cold-pressed and centrifugation methods that retain fuller terpene profiles.
The EPA regulates citrus oil as a minimum-risk pesticide under FIFRA exemptions, creating a dual-use pathway for household cleaning applications that conventional chemical actives cannot access. REACH compliance in Europe mandates full substance registration for limonene imports, raising documentation burdens for suppliers serving cosmetic and pharmaceutical end users. Stakeholders must monitor evolving fragrance allergen labeling rules under the EU Cosmetics Regulation, as expanded disclosure requirements could redirect formulation choices toward standardized terpene isolates.
Market Dynamics
Clean-label mandates across personal care and food formulations are compressing solvent extraction methods while elevating cold-pressed and centrifugation techniques that preserve fuller terpene profiles. This shift is redistributing value capture toward equipment suppliers and agronomy partners capable of certifying traceable supply chains.
Growth Catalysts
- EU Green Deal sustainable sourcing mandates:Procurement officers at European fragrance houses now require documented carbon footprints and regenerative agriculture certifications from Brazilian and Mediterranean suppliers.
- Household cleaning dual-use pathway:EPA FIFRA exemptions for citrus oil as a minimum-risk pesticide unlock formulations that conventional chemical actives cannot access, expanding addressable market for limonene-based disinfectants.
- Pharmaceutical-grade distillation demand:European pharmacopeia compliance for citrus derivatives in topical and oral applications drives investment in GMP-certified extraction facilities.
Market Restraints
- Brazilian orange oil supply concentration:Climate volatility in São Paulo state and cooperative consolidation limits buyer negotiating leverage and creates single-source vulnerability for global fragrance houses.
- Limonene price volatility:Feedstock costs fluctuate with orange juice processing volumes, squeezing margins for derivatives manufacturers lacking backward integration into fruit processing.
- REACH documentation burdens:Full substance registration requirements for limonene imports into Europe raise compliance costs and exclude smaller traders from cosmetic and pharmaceutical supply chains.
Strategic Opportunities
- Underpenetrated Indian aromatherapy channel:Ayurveda-inspired wellness brands in Maharashtra and Karnataka represent uncaptured demand for therapeutic-grade grapefruit and bergamot oils with organic certification.
- Convergence of cold-pressing with inline spectroscopy:Real-time terpene profiling during extraction enables batch-specific quality premiums and reduces downstream rejection rates at flavor houses.
- EU Cosmetics Regulation allergen labeling expansion:Mandated disclosure of fragrance sensitizers redirects formulation toward standardized terpene isolates with documented purity thresholds.
Industry Challenges
- GMP-certified distillation talent scarcity:European pharmaceutical-grade facilities face recruitment gaps for operators qualified in FDA and EMA validation protocols.
- Fragrance allergen testing timeline compression:Expanded EU disclosure requirements force reformulation cycles that outpace traditional 18-month product development schedules.
- Cold-press equipment capex intensity:Centrifugation and inline quality systems require capital deployment that mid-sized processors cannot finance without cooperative pooling arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Oil Market |
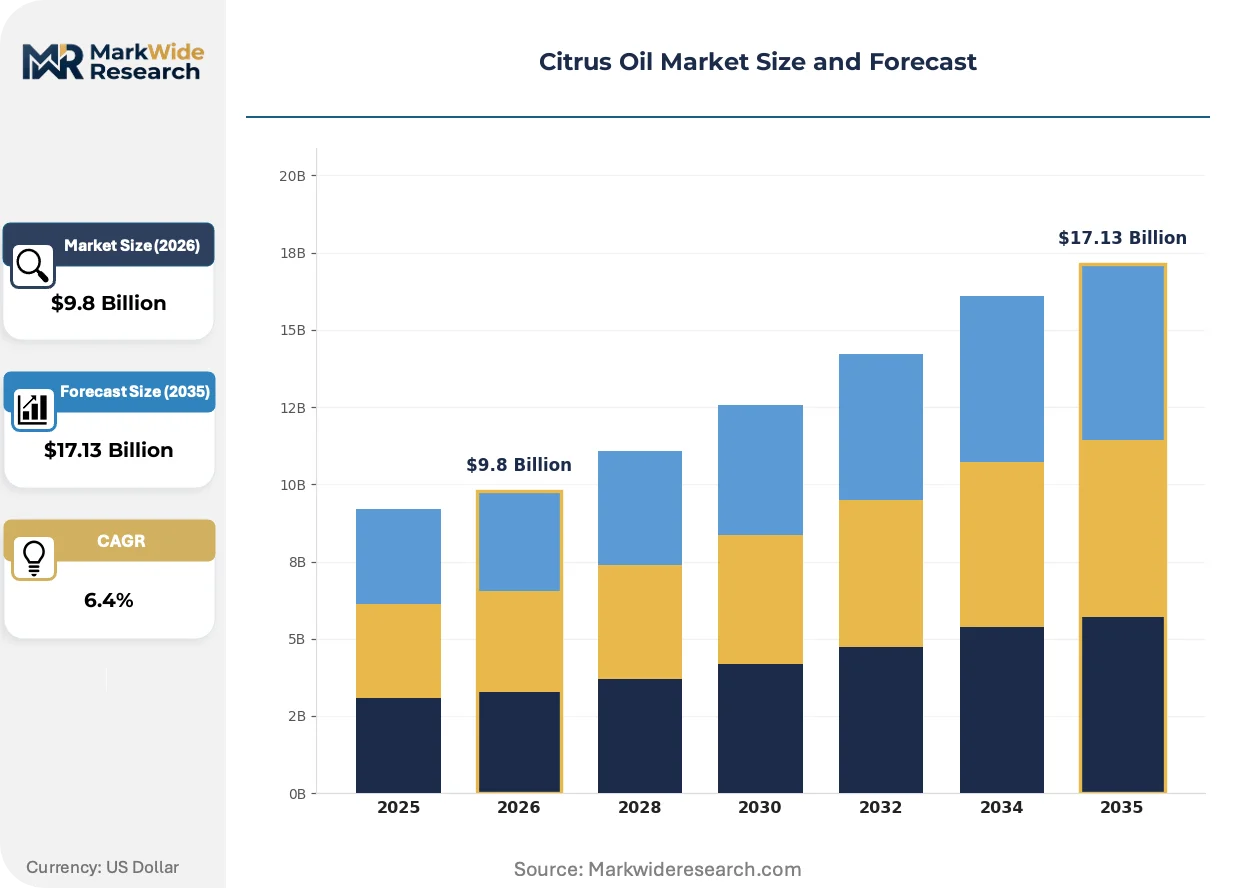
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orange Oil, Lemon Oil, Lime Oil, Grapefruit Oil Application: Food Flavoring, Cosmetics, Aromatherapy, Cleaning Products Extraction Method: Cold Pressing, Steam Distillation, Solvent Extraction, Centrifugation End User: Food & Beverage, Personal Care, Household Products, Pharmaceuticals |
| Companies Covered | Lionel Hitchen Essential Oils Ltd., doTERRA International LLC, Symrise AG, Citromax Flavors Inc., Bontoux S.A.S., Young Living Essential Oils LC, Mountain Rose Herbs, Givaudan SA, Citrus and Allied Essences Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Oil Market Emerging Trajectories
Extraction technology is fragmenting into modular, quality-verified units that displace centralized solvent-based processing. Regulatory disclosure mandates are rewriting formulation specifications. Buyer procurement patterns are compressing supplier qualification timelines.
Inline near-infrared spectroscopy is modularizing quality assurance by enabling real-time terpene fingerprinting during cold-pressing operations. Personal care formulators in France and Germany are adopting these systems to reduce batch rejection rates and secure clean-label certifications. The technology is compressing value capture toward equipment-integrated suppliers while marginalizing traders lacking analytical capabilities.
REACH substance registration deadlines for limonene and pinene derivatives are forcing European cosmetic manufacturers to consolidate supplier bases toward fully documented sources. The regulation is elevating compliance costs that exclude smaller Mediterranean traders and redirect volume toward Brazilian cooperatives with established dossiers. Fragrance houses are responding by embedding regulatory affairs teams directly within agronomy partnership structures.
Direct contracting between personal care brands and Brazilian citrus cooperatives is displacing traditional flavor house intermediaries in orange oil procurement. Mid-sized manufacturers in North America and Western Europe are establishing multi-year offtake agreements with named growing regions to secure traceability for ESG reporting. This pattern is most visible in certified organic segments where cooperative premiums justify bypassing conventional distribution tiers.
Citrus Oil Market Segmentation
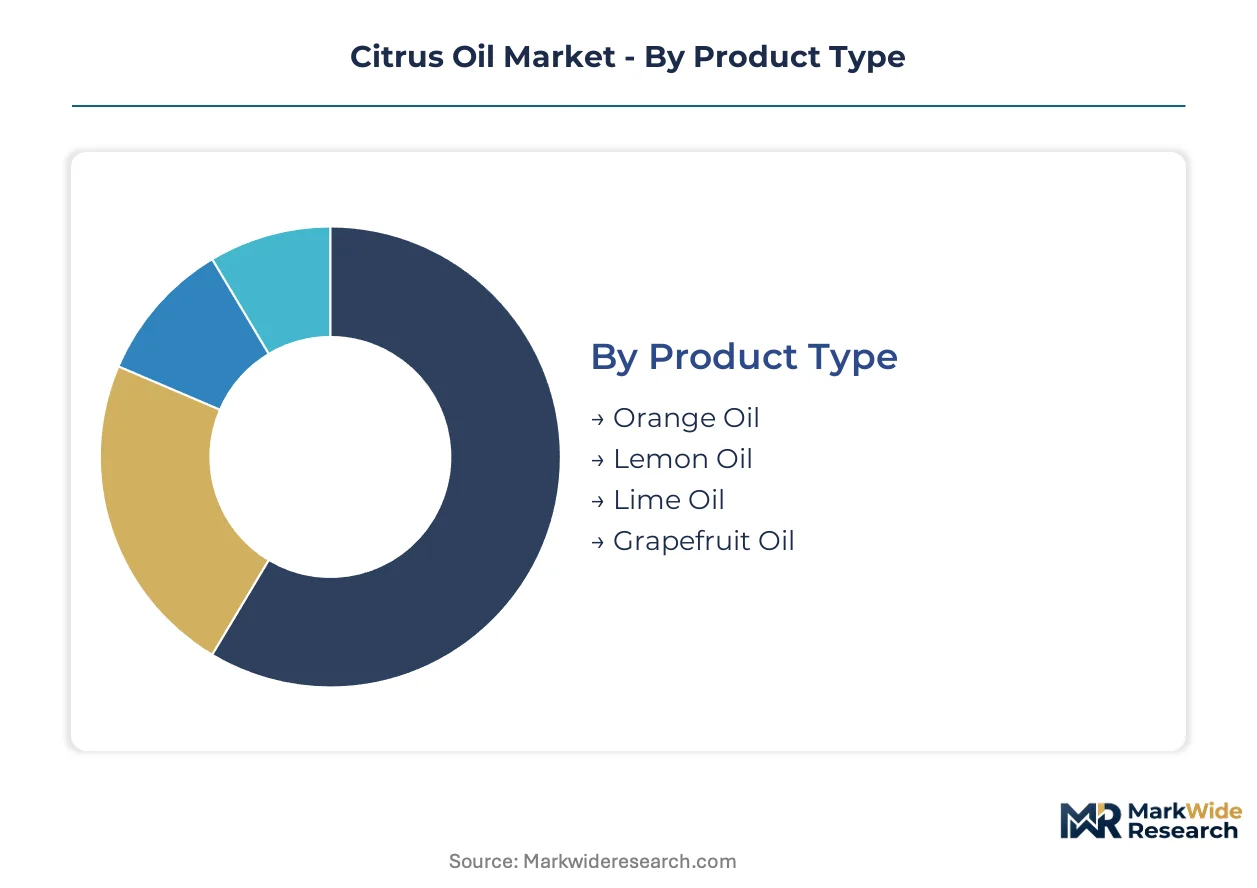
Citrus oil market segmentation reveals how extraction technology, application chemistry, and end-user compliance requirements create distinct value tiers. Buyers navigate trade-offs between terpene fidelity, regulatory documentation, and unit economics across product categories.
Product Type:
Chemical composition and feedstock abundance differentiate volume positioning across citrus oil varieties.
- Orange Oil:Cold-pressed orange oil contains 90-95% limonene with minor pinene and myrcene fractions, making it the dominant volume driver. Brazilian São Paulo cooperatives supply global fragrance houses seeking cost-efficient base notes for mass-market personal care formulations.
- Lemon Oil:Higher citral content (3-5%) delivers sharper aromatic profiles prized in premium cleaning products. Italian Calabrian and Sicilian producers capture value through EU-protected geographical indication status and documented carbon footprints for Green Deal compliance.
- Lime Oil:Distinctive terpene signature with higher gamma-terpinene supports niche flavor applications in Mexican and Southeast Asian food manufacturing.
- Grapefruit Oil:Therapeutic-grade certification requirements limit supply elasticity; South African and Florida growers serve aromatherapy channels with organic credentials.
Orange oil leads on scale; grapefruit oil leads on momentum.
Application:
Formulation chemistry and disclosure mandates segment demand by end-use specification intensity.
- Food Flavoring:FDA GRAS status and FEMA-approved usage levels govern incorporation into beverages and confectionery. Brazilian orange oil dominates through backward integration into juice processing waste streams.
- Cosmetics:EU Cosmetics Regulation allergen labeling drives reformulation toward standardized terpene isolates with documented purity thresholds. French and German formulators now require batch-specific chromatographic certificates.
- Aromatherapy:Therapeutic-grade certification from named growing regions commands 40-60% premiums over food-grade equivalents. Indian Ayurveda brands in Maharashtra represent uncaptured demand for certified organic bergamot and grapefruit.
- Cleaning Products:EPA FIFRA minimum-risk pesticide exemption unlocks limonene-based disinfectants that conventional chemical actives cannot access. North American private-label manufacturers are direct-contracting Brazilian cooperatives for traceable supply.
Food flavoring anchors volume flows; aromatherapy generates steepest expansion trajectory.
Extraction Method:
Capital intensity and terpene retention rates determine competitive positioning across processing technologies.
- Cold Pressing:Mechanical rupture of oil glands preserves volatile terpene profiles without thermal degradation. Equipment-integrated suppliers in Mediterranean regions capture value through inline spectroscopy systems that enable batch-specific quality premiums.
- Steam Distillation:Thermal extraction produces pharmaceutical-grade derivatives meeting European pharmacopeia compliance for topical and oral applications. GMP-certified facilities face talent scarcity for FDA and EMA validation protocols.
- Solvent Extraction:Hexane-based methods occupy shrinking share as clean-label preferences push brands toward mechanical alternatives; residual solvent limits restrict cosmetic and pharmaceutical eligibility.
- Centrifugation:High-speed separation yields fuller terpene retention with lower thermal footprint than distillation. Mid-sized processors struggle with capex intensity without cooperative pooling arrangements.
Cold pressing dominates current capacity; centrifugation is climbing the fastest as equipment costs decline.
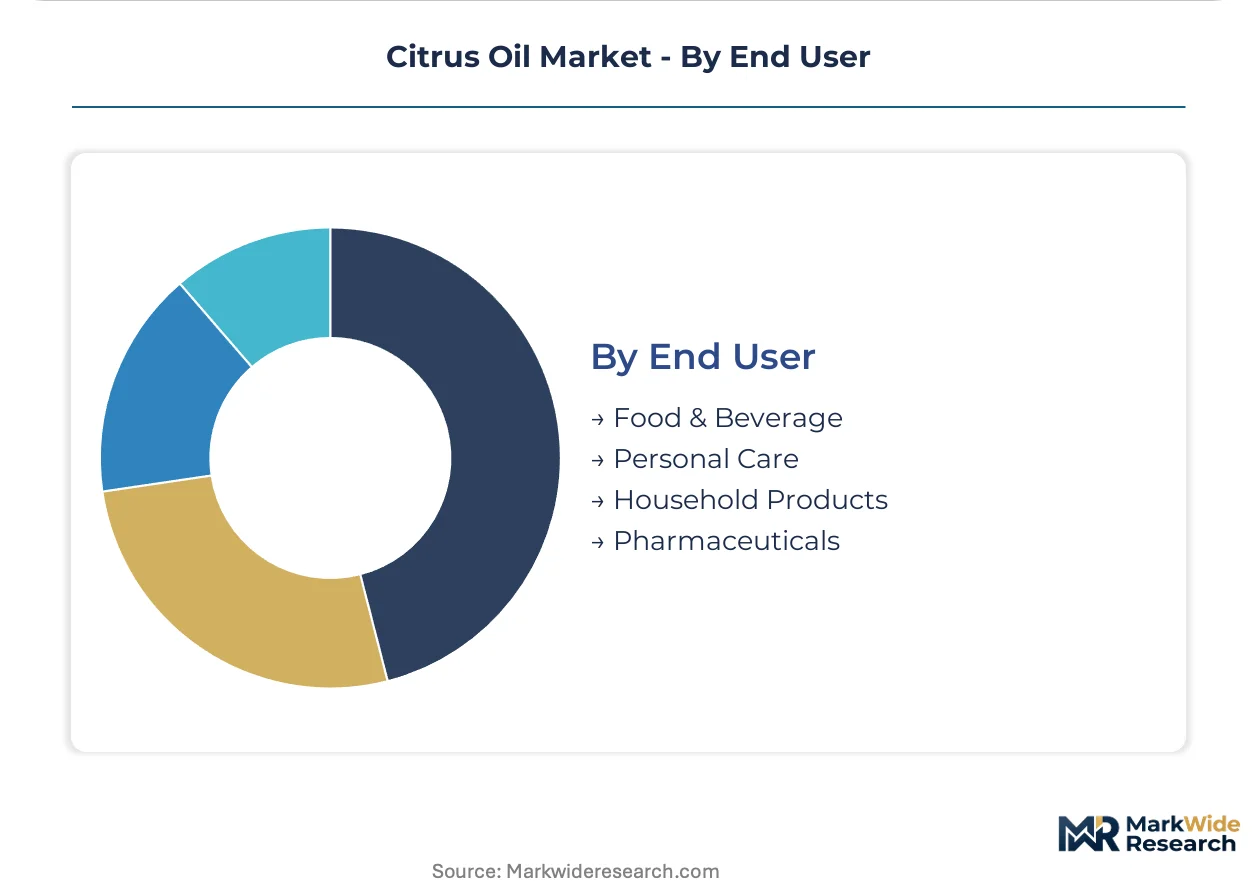
End User:
Procurement sophistication and compliance documentation requirements stratify buyer segments.
- Food & Beverage:Flavor houses require consistent limonene concentrations for beverage emulsion stability. Brazilian cooperative consolidation limits negotiating leverage for mid-sized manufacturers.
- Personal Care:ESG reporting mandates drive direct contracting with named growing regions. North American and Western European brands establish multi-year offtake agreements bypassing traditional distribution tiers.
- Household Products:EPA registration pathways favor minimum-risk pesticide formulations. Limonene-based disinfectants expand addressable market beyond conventional chemical actives.
- Pharmaceuticals:European pharmacopeia and USP compliance demands GMP-certified extraction with full substance registration under REACH. Documentation burdens exclude smaller Mediterranean traders from supply chains.
Food & beverage commands volume concentration; pharmaceuticals generates highest margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled distillation operators and agronomy specialists concentrate in Mediterranean and Brazilian growing belts, anchoring extraction capacity for fragrance and pharmaceutical applications.
Brazil
São Paulo state cooperatives supply cold-pressed orange oil to global fragrance houses seeking traceable supply for ESG reporting. ANVISA, the national health regulator, governs pharmaceutical-grade extraction facility licensing. Campinas and Ribeirão Preto anchor processing clusters where direct contracting between personal care brands and growers displaces traditional intermediaries.
United States
Florida grapefruit growers and California lemon processors serve therapeutic-grade aromatherapy channels with organic certification premiums. EPA FIFRA exemptions enable limonene-based disinfectant formulations that conventional chemical actives cannot access. The Tampa Bay and Ventura County clusters concentrate cold-pressing capacity for household cleaning product manufacturers.
Italy
Calabrian and Sicilian producers capture value through EU-protected geographical indication status for lemon oil with documented carbon footprints. ECHA REACH substance registration mandates for limonene imports raise compliance costs that redirect volume toward established dossier holders. Reggio Calabria and Syracuse maintain distillation expertise for pharmaceutical-grade citrus derivatives.
India
Maharashtra and Karnataka Ayurveda-inspired wellness brands represent uncaptured demand for certified organic bergamot and grapefruit oils. FSSAI governs food-grade flavoring applications while state agricultural departments promote organic certification schemes. Mumbai-Pune corridor traders face documentation gaps that exclude smaller operators from European cosmetic supply chains.
Germany
Flavor houses in Hamburg and Frankfurt require batch-specific chromatographic certificates for EU Cosmetics Regulation allergen labeling compliance. EMA validation protocols for GMP-certified extraction facilities face talent scarcity for pharmaceutical-grade distillation operations. The Cologne-Düsseldorf industrial belt concentrates formulation R&D for standardized terpene isolates.
Citrus Oil Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across extraction technology tiers. The vendor base stratifies between equipment-integrated suppliers capturing value through inline quality systems and traders lacking analytical capabilities. Three archetypes dominate: integrated botanical supply chain operators, cold-pressing equipment specialists, and pharmaceutical-grade distillation houses. Competitive moves center on backward integration into fruit processing and multi-year offtake agreements with named growing regions.
Within the integrated supply chain tier, Symrise AG and Givaudan SA exemplify players leveraging Mediterranean and Brazilian agronomy partnerships to secure consistent raw material flows. Lionel Hitchen Essential Oils Ltd. occupies a position among European pharmaceutical-grade specialists, anchoring decades of distillation expertise for compliance-intensive applications. These three represent the structural split between diversified fragrance houses and focused extraction houses serving pharmacopeia markets.
| Leading Market Players |
|---|
| Lionel Hitchen Essential Oils Ltd. |
| doTERRA International LLC |
| Symrise AG |
| Citromax Flavors Inc. |
| Bontoux S.A.S. |
| Young Living Essential Oils LC |
| Mountain Rose Herbs |
| Givaudan SA |
| Citrus and Allied Essences Ltd. |
| Others |
Supply Flow & Price Mechanics
Fragrance house procurement officers in Hamburg and Paris anchor the dominant contract-based long-term offtake pricing model, leveraging multi-year agreements with São Paulo cooperatives to lock in limonene supply for ESG reporting compliance.
Pricing Analysis
Bundled agronomy partnerships with inline spectroscopy certification command premiums over unbundled spot-market trading. Three-tier pricing structure across therapeutic-grade, food-grade, and industrial-grade certifications separates premium grapefruit oil from standard orange oil from economy solvent-extracted derivatives. Cost compression in food-grade orange oil is intensifying because Brazilian cooperative consolidation limits buyer negotiating leverage. Mid-sized personal care manufacturers exhibit highest price sensitivity, while pharmaceutical formulators accept steep premiums for GMP-certified documentation.
Supply Chain Analysis
EU Green Deal domestic-content mandates for documented carbon footprints are reshaping sourcing toward Mediterranean producers with EU-protected geographical indication status. Supply concentrates in Brazil, Italy, and the United States, with São Paulo cooperatives, Calabrian distillers, and Florida grapefruit growers anchoring global flows. The chain draws from orange juice processing waste streams, cold-press equipment modules, and GMP-certified distillation talent pools. Single-source vulnerability in Brazilian orange oil creates structural exposure to climate volatility in São Paulo state. Distribution runs through fragrance house intermediaries, though direct contracting between personal care brands and cooperatives is accelerating.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The citrus oil market functions as a stable compounder, with EU Cosmetics Regulation allergen labeling mandates driving steady reformulation demand across personal care and pharmaceutical channels.
For Market Incumbents: Acquire GMP-certified distillation facilities in European pharmacopeia markets to capture pharmaceutical-grade margin premiums. Secure backward integration into Brazilian cooperative structures before direct contracting displaces traditional fragrance house intermediaries. Invest in inline near-infrared spectroscopy systems to defend against equipment-integrated suppliers capturing batch-specific quality premiums. For New Entrants and Emerging Players: Ayurveda-inspired wellness distributors in Maharashtra and Karnataka represent the most penetrable channel for therapeutic-grade organic certification. Target uncaptured demand for certified organic bergamot and grapefruit oils with documented purity thresholds. Establish cooperative pooling arrangements to overcome centrifugation equipment capex intensity. For Investors and Strategic Acquirers: Personal care conglomerates seeking ESG-compliant supply chains are the most active acquirer in this space. Focus on five-to-ten-year viability windows for Mediterranean and Brazilian extraction assets with established REACH dossiers. Watch for EU Cosmetics Regulation fragrance allergen expansion timelines as the signal for accelerated terpene isolate standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Structures | Direct contracting with São Paulo growers secures traceable supply for ESG reporting mandates. |
| Inline Spectroscopy Deployment | Real-time terpene profiling enables batch-specific quality premiums at French and German flavor houses. |
| GMP Certification Investment | FDA and EMA validation protocols unlock pharmaceutical-grade margin capture in European facilities. |
| Organic Certification Expansion | FSSAI-compliant schemes in Maharashtra open Ayurveda channel access for therapeutic-grade oils. |
| Long-term Offtake Agreements | Multi-year contracts with named growing regions bypass traditional distribution tiers for North American brands. |
Methodological Framework
Bottom-up personal care and pharmaceutical formulation modeling reconciled against top-down citrus cooperative production tracking forms the analytical core. Primary interviews with fragrance house procurement officers, GMP facility validation specialists, Brazilian cooperative agronomists, and EU regulatory affairs consultants combined with secondary validation from ECHA REACH registration databases, ANVISA facility licensing records, and EU-protected geographical indication registries. Customs trade data for limonene and pinene derivatives, FAO citrus production statistics, and fragrance house SEC filings provided supply-side triangulation.
Historical trendline analysis of cold-pressed orange oil volume flows and therapeutic-grade grapefruit oil premium trajectories informed projection frameworks. Segmentation dimensions modeled include citrus variety, extraction method, application chemistry, and end-user compliance tier. CAGRs were derived from regression analysis of cooperative output data and personal care brand procurement disclosures across the projection horizon. Forecast inputs incorporated EU Green Deal implementation timelines and EPA FIFRA exemption utilization rates for household cleaning applications.
Revisions become necessary when Brazilian climate volatility disrupts São Paulo state harvests, when EU Cosmetics Regulation allergen labeling expansion accelerates beyond modeled timelines, or when REACH substance registration deadlines shift. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Natural Berry Flavor Market
Flavorings and Food Additives
Edible Food Paints Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
United States Food Flavor Market
Flavorings and Food Additives
Asia-Pacific Flavor and Fragrance Market
Flavorings and Food Additives
North America Vanilla and Vanillin Market
Flavorings and Food Additives
Flavor Emulsions Market
Flavorings and Food Additives
Smoked Dextrose Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Vanilla Bean Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
Canola Lecithin Market
Flavorings and Food Additives
Japan Food Colorants Market
Flavorings and Food Additives
Cocoa Extract Market