
 Decanter Market | 2026-2036
Decanter Market Size, Share, and Industry Trends Forecast 2026-2036
Decanter Market Analysis
Lead-free crystal is repositioning decanter economics across the premium tier, displacing traditional leaded formulations as health-conscious buyers recalibrate purchase criteria. Alfa Laval leverages its industrial separation expertise to inform precision-manufacturing techniques that cross-pollinate into high-end consumer glassware. Pieralisi Maip SpA anchors its position through specialized Italian craft heritage, while GEA Group Aktiengesellschaft competes on engineering-driven consistency in blown-glass tolerances.
A decanter is a vessel engineered for controlled aeration and sediment separation of wine and spirits, typically featuring a wide base surface area of 750–1500 milliliters to maximize oxygen exposure while minimizing oxidation time. Glass and crystal materials command the dominant margin pools, with lead-free crystal variants capturing accelerating share as safety certification becomes a procurement filter. Wine decanters lead volume across home use and restaurant channels, while gift sets concentrate seasonal revenue spikes and command premium pricing through limited-edition artistic designs.
EPA guidelines on lead content in consumer glassware, coupled with REACH substance restrictions in Europe and FDA food-contact material standards, collectively elevate compliance costs for manufacturers while creating market access barriers for uncertified imports. BIS certification requirements in India and evolving GB standards in China add further layer complexity for exporters targeting multiple jurisdictions. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation mandates and certification renewal cycles that will reshape supplier qualification protocols.
Market Dynamics
Lead-free crystal formulation mandates are compressing supplier margins while creating certification premiums that reward heritage glassblowers with established testing infrastructure. EPA lead-content thresholds and REACH substance restrictions have eliminated cost-competitive shortcuts, forcing reformulation investments that favor scaled artisans over import-dependent distributors.
Growth Catalysts
- REACH substance restrictions:European lead-content limits accelerate premium-tier demand for certified lead-free crystal, redirecting hospitality procurement toward compliant heritage suppliers in Bohemia and Waterford.
- Artisan glassblowing clusters:Concentrated craft heritage in Murano, Waterford, and Bohemia enables premium positioning through authenticity narratives that command price premiums in gift and hospitality channels.
- FDA food-contact material standards:Tightened US safety protocols filter uncertified imports, expanding market access for domestic and European manufacturers with established testing documentation.
Market Restraints
- Raw material cost volatility:High-purity silica sand and rare-earth clarifiers face supply uncertainty from concentrated mining operations in China and Brazil, compressing margin predictability for mid-tier producers.
- Heritage craft labor scarcity:Master glassblower pipelines in Murano and Waterford face generational attrition, constraining volume scalability for premium artisan brands despite demand expansion.
- Substitution by aeration devices:Electric wine aerators and instant-decanting gadgets capture convenience-oriented home users, particularly in North American and East Asian markets with tech-forward consumption patterns.
Strategic Opportunities
- Underpenetrated Indian hospitality:Luxury hotel construction in Mumbai, Bangalore, and Goa creates first-mover positioning for lead-free crystal decanters as BIS certification requirements mature and import compliance infrastructure develops.
- Direct-to-consumer craft platforms:Digital-native channels bypass traditional wholesale markups, enabling Murano and Bohemian artisans to capture margin previously allocated to distributor networks.
- Wine tourism integration:Vineyard tasting-room retail and estate hospitality programs in Napa, Bordeaux, and Mendoza create captive demand for branded decanter merchandise with provenance storytelling.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous EPA, REACH, FDA, and BIS compliance testing extends product launch cycles by 8-14 months, straining working capital for seasonal gift-market timing.
- Legacy mold precision deficits:Hand-blown heritage techniques struggle to achieve dimensional consistency required by automated restaurant dishwashing systems, limiting chain-hospitality penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decanter Market |
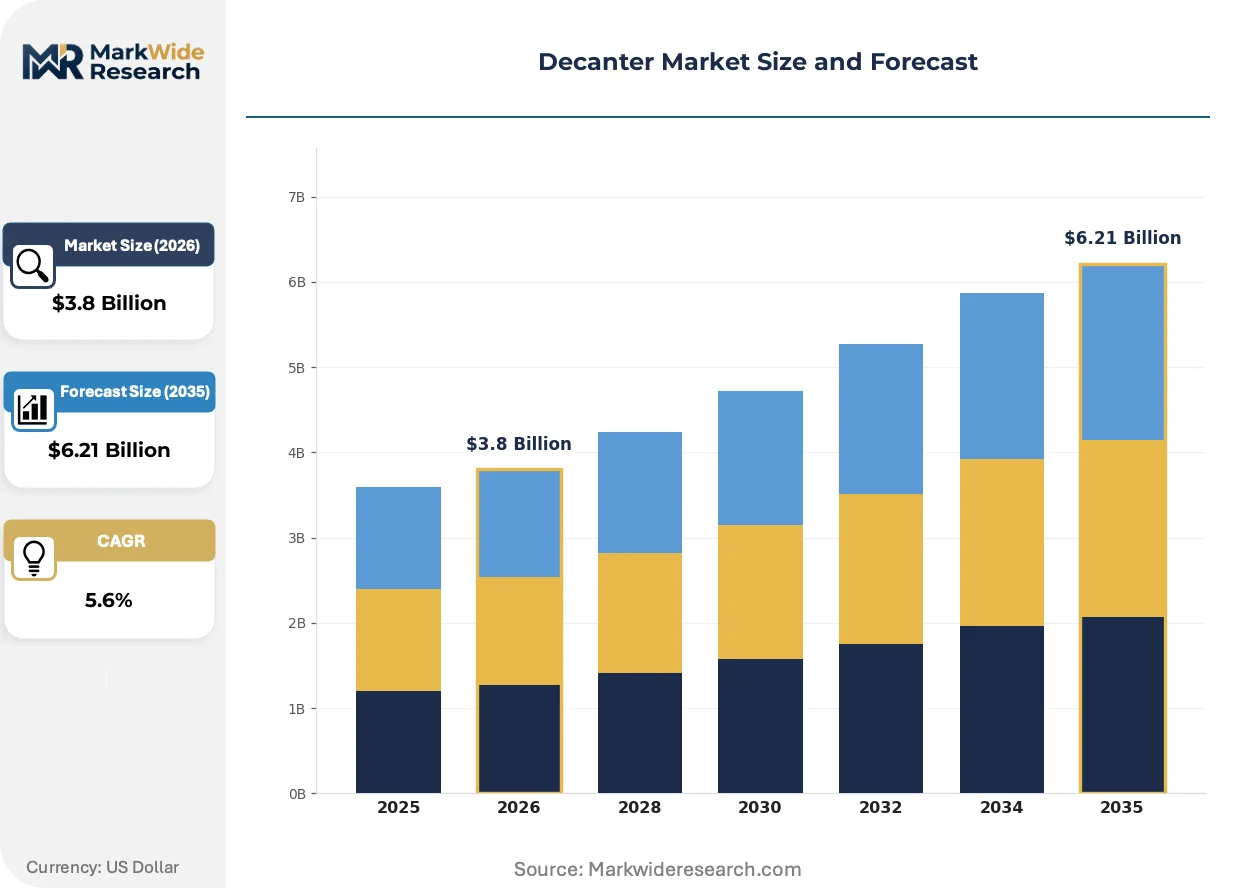
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Wine Decanters, Whisky Decanters, Carafes, Decorative Decanters Material: Glass, Crystal, Plastic, Stainless Steel Design: Classic, Modern, Vintage, Artistic Usage: Home Use, Restaurants, Wine Tasting Events, Gift Sets |
| Companies Covered | ANDRITZ, IHI Corporation, GEA Group Aktiengesellschaft, FLSmidth, Mitsubishi Kakoki Kaisha, Alfa Laval, Pieralisi Maip SpA, Centrisys, Flottweg SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decanter Market Emerging Trajectories
Digital fabrication and regulatory transparency tools are compressing traditional craft-to-market timelines while elevating material traceability as a purchase determinant. These shifts reward suppliers who integrate precision measurement with heritage narrative.
Laser-based internal stress detection systems enable non-destructive quality verification of hand-blown crystal wall thickness and structural integrity. Boutique hospitality procurement teams in Copenhagen and Melbourne now require batch-level certification documentation. This metrology convergence is rewriting supplier qualification protocols, compressing the competitive advantage window for heritage brands without digitized quality infrastructure.
REACH Annex XVII lead-content restrictions and EPA TSCA Section 8 reporting mandates have eliminated grandfathered formulations for imported crystal. European manufacturers face reformulation costs exceeding €200,000 per product line for comprehensive testing documentation. Gift-set producers targeting transatlantic distribution now prioritize unified lead-free compositions to avoid dual-SKU complexity and customs detention risk.
Certification-driven preference shifts now dominate hospitality procurement, with sustainability officers in London and Singapore mandating cradle-to-grave material documentation. Third-party verified lead-free claims displace traditional brand loyalty in RFP scoring. Chain restaurant buyers in Dubai and Sydney increasingly specify ISO 9001-aligned suppliers with blockchain-traceable batch records, marginalizing opaque artisan intermediaries.
Decanter Market Segmentation
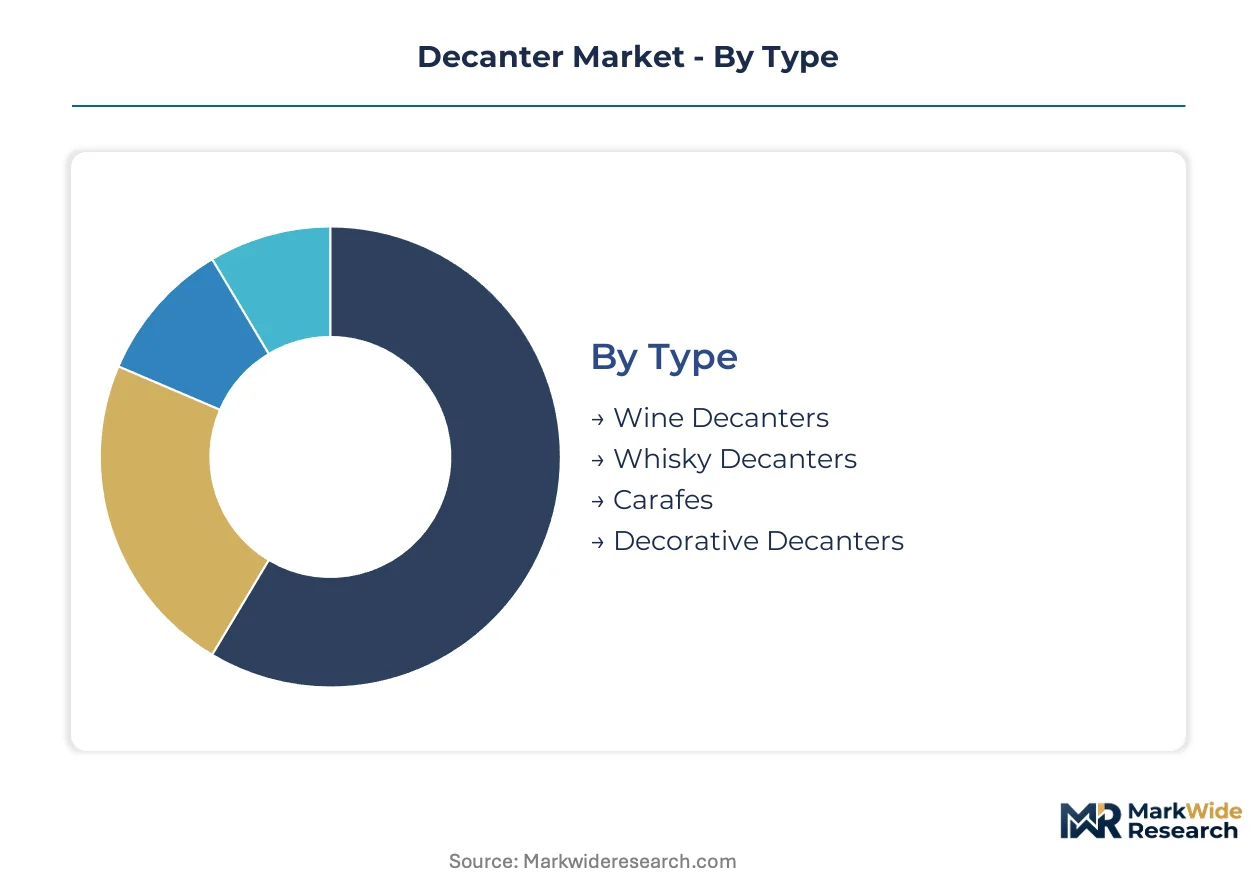
Decanter procurement patterns diver sharply across material grades and end-use contexts, with hospitality buyers prioritizing certification-compliant crystal while home consumers trade off aeration performance against storage footprint. Understanding these segment boundaries enables suppliers to align production capacity with the upgrade cycles and replacement velocities that characterize each demand pool.
Type:
Wine decanters command replacement cycles tied to breakage rates and hospitality inventory refresh schedules, while spirit-focused formats follow gift-giving calendars and collector acquisition patterns.
- Wine Decanters:Engineered with wide-base geometries of 750–1500 milliliter capacity to maximize oxygen exposure surface area for red wine aeration. Demand concentrates in restaurant channels across France, Italy, and Spain where sommelier-led service mandates vessel replacement every 18–24 months due to etching and thermal stress accumulation.
- Whisky Decanters:Feature narrower neck profiles and heavier base construction to minimize evaporation of high-proof spirits. Collector demand in Scotland, Japan, and Kentucky drives limited-edition releases with distillery co-branding, though volume expansion lags wine formats due to longer replacement cycles.
- Carafes:Multi-beverage utility vessels with simplified silhouettes for water, juice, and casual wine service. Mid-tier hospitality in Germany and Austria favors stackable, dishwasher-safe formats for banquet operations.
- Decorative Decanters:Prioritize aesthetic statement over functional aeration, often sealed with ground-glass stoppers for display purposes. Murano and Bohemian artisans dominate commissioned pieces for luxury residential interiors in Switzerland and Monaco.
Volume placements concentrate in Wine Decanters; the faster expansion belongs to Whisky Decanters.
Material:
Material selection directly determines regulatory compliance pathways and margin architecture, with lead-free crystal commanding certification premiums that glass and alternative substrates cannot replicate.
- Glass:Soda-lime and borosilicate formulations dominate mass-market production through automated pressing and blowing lines. Cost-tier positioning in Brazil and Mexico favors durability over optical clarity for everyday home use.
- Crystal:Lead-free variants now displace traditional leaded formulations as EPA thresholds and REACH Annex XVII restrictions eliminate non-compliant imports. Heritage producers in Waterford and Bohemia capture hospitality procurement through unified transatlantic certification documentation.
- Plastic:Polycarbonate and Tritan copolymer formats serve outdoor hospitality and poolside service where breakage liability prohibits glass. Australian and South African safari lodges specify BPA-free certification for guest safety protocols.
- Stainless Steel:Double-walled insulated constructions target temperature retention for chilled white wines and spirits. Japanese design houses lead aesthetic innovation, though market penetration remains constrained by weight and opacity limitations.
Glass captures the largest unit placements; crystal gains share fastest on certification-driven hospitality procurement.
Design:
Design taxonomy reflects generational purchasing preferences and gift-market occasionality, with aesthetic positioning determining channel access and price realization.
- Classic:Traditional silhouettes—duck, swan, and ship's decanter profiles—anchor heritage brand portfolios. Established collectors in England and the Netherlands favor these forms for estate continuity and provenance signaling.
- Modern:Minimalist geometries with angular cuts and asymmetric bases attract design-forward hospitality in Copenhagen and Melbourne. Scandinavian procurement officers specify these for new-build luxury properties seeking differentiated tableside presentation.
- Vintage:Reproduction and authentic period pieces serve the secondary market and auction channel. Authentication documentation requirements in France and Italy limit scalable supply to verified estate provenance.
- Artistic:Limited-edition collaborations with contemporary glass artists command premium pricing through gallery and museum retail. Venice Biennale exposure drives collector demand for Murano atelier production with certificate of authenticity.
Modern designs expand most quickly in hospitality specification; Classic forms retain the deepest installed base.
Usage:
Usage context determines performance specifications, replacement frequency, and margin structure, with commercial applications demanding durability certifications absent from consumer channels.
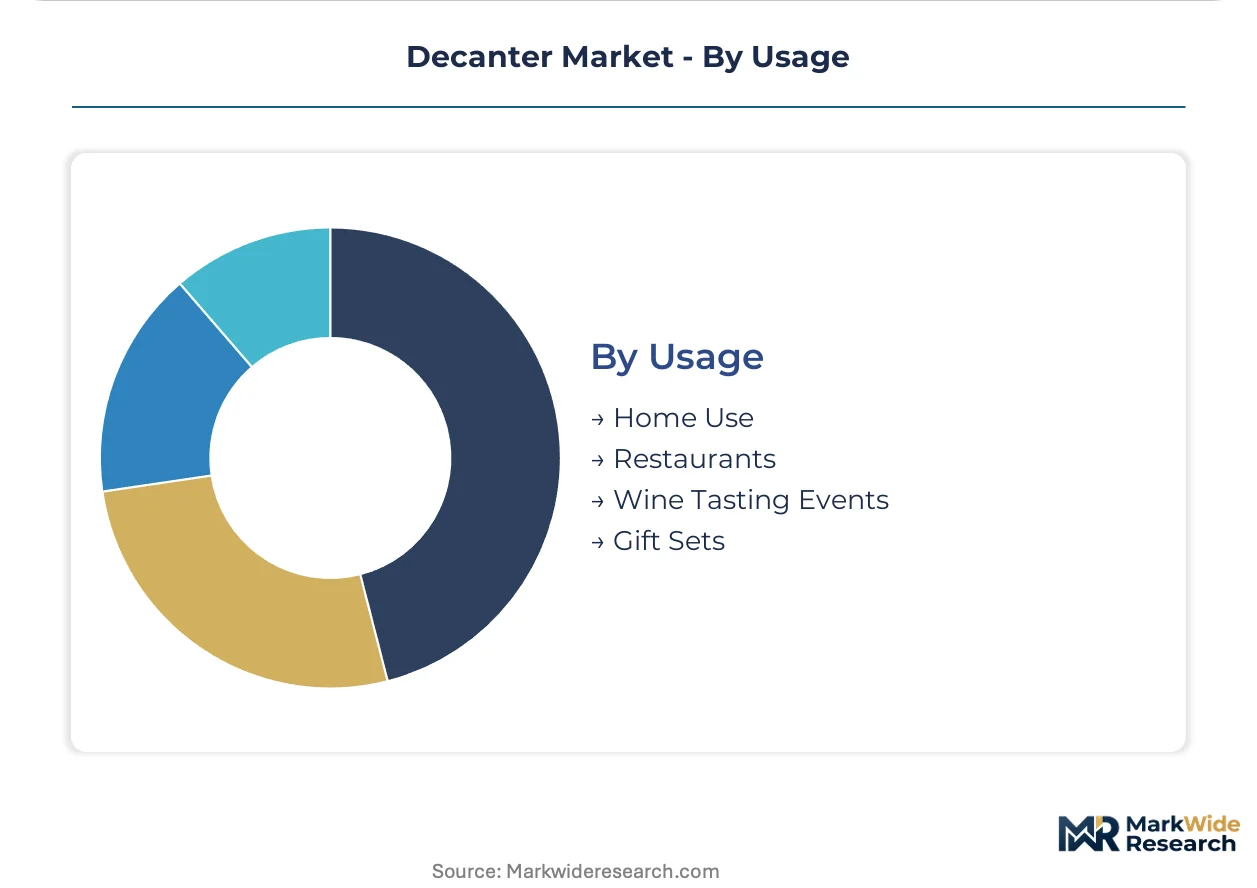
- Home Use:Individual and family consumption drives volume through retail and e-commerce, with purchase timing tied to household formation and entertaining occasions. North American and East Asian buyers increasingly research aeration efficacy metrics before selection.
- Restaurants:Chain and independent hospitality procurement mandates ISO 9001-aligned suppliers with batch-traceable quality documentation. Automated dishwashing compatibility tests in Dubai and Sydney eliminate hand-blown heritage pieces lacking dimensional tolerance.
- Wine Tasting Events:Vineyard estate programs and mobile sommelier services require portable, rapid-decanting formats. Napa, Bordeaux, and Mendoza tasting rooms create captive retail demand for branded merchandise with estate provenance.
- Gift Sets:Seasonal revenue concentration around year-end and wedding calendars commands premium packaging and limited-edition artistic collaborations. Gift-box producers in Bohemia and Waterford prioritize unified lead-free compositions to avoid dual-SKU complexity for transatlantic distribution.
Home Use generates the highest unit volume; Gift Sets achieve the steepest price realization per vessel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian glassmaking heritage clusters in Murano benefit from Veneto region tax incentives for artisan craft preservation. Czech Bohemia and Irish Waterford anchor European lead-free crystal production. Japanese precision manufacturing and Indian hospitality construction create complementary demand poles outside traditional European supply bases.
United States
Napa Valley vineyard tasting rooms and Manhattan fine-dining procurement drive lead-free crystal specification. FDA food-contact material standards filter uncertified imports, expanding market access for domestic manufacturers with established testing documentation. Pacific Northwest design studios in Portland and Seattle pioneer minimalist decanter geometries for hospitality specification.
Italy
Murano atelier production commands gallery retail premiums through Venice Biennale exposure. ECHA REACH Annex XVII lead-content restrictions eliminate grandfathered formulations, forcing reformulation investments that favor scaled heritage suppliers over import-dependent distributors. Tuscan wine tourism estates in Chianti and Montalcino create captive branded merchandise demand.
Czech Republic
Bohemian glassblowing clusters in Nový Bor and Kamenický Šenov supply heritage-certified lead-free crystal to transatlantic hospitality chains. EU Green Deal sustainability reporting requirements elevate cradle-to-grave material documentation as an RFP scoring factor. Prague-based exporters prioritize unified compositions to avoid dual-SKU complexity for US-EU distribution.
Japan
Tokyo design houses and Osaka hospitality procurement drive precision-manufactured crystal specification. METI industrial standards align with FDA-equivalent safety protocols, enabling seamless export qualification. Kyoto craft ateliers preserve hand-blown techniques for limited-edition collector releases with certificate-of-authenticity documentation.
India
Luxury hotel construction in Mumbai, Bangalore, and Goa creates first-mover positioning for certified lead-free crystal. BIS certification requirements mature as import compliance infrastructure develops, extending product launch cycles for seasonal gift-market timing. Maharashtra-based distributors build testing documentation capabilities to serve hospitality procurement mandates.
Decanter Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage craft ateliers commanding premium-tier pricing while industrial fabricators serve volume hospitality procurement. The supplier base organizes around three archetypes: precision-engineering multinationals leveraging separation technology cross-over, regional craft heritage houses with established certification infrastructure, and scale-driven manufacturers optimizing automated production for mid-tier glass formats. Competitive moves concentrate on geographic expansion into underpenetrated hospitality markets and portfolio diversification toward lead-free crystal formulations that satisfy multi-jurisdiction compliance requirements.
Among precision-engineering specialists, Alfa Laval exemplifies technology transfer from industrial separation equipment into high-end consumer glassware manufacturing protocols. GEA Group Aktiengesellschaft occupies a position within the engineering-driven consistency tier, while Pieralisi Maip SpA anchors Italian craft heritage positioning through specialized regional production methods. These three entities represent distinct competitive vectors—technology cross-pollination, manufacturing precision, and artisan authenticity—that structure rivalry across certification-sensitive hospitality procurement channels.
| Leading Market Players |
|---|
| ANDRITZ |
| IHI Corporation |
| GEA Group Aktiengesellschaft |
| FLSmidth |
| Mitsubishi Kakoki Kaisha |
| Alfa Laval |
| Pieralisi Maip SpA |
| Centrisys |
| Flottweg SE |
| Others |
Supply Flow & Price Mechanics
High-purity silica sand and rare-earth clarifiers flow from concentrated mining operations in China and Brazil through three distinct pricing tiers before reaching hospitality procurement teams in Dubai and Sydney. Master glassblower labor scarcity in Murano and Waterford compresses volume scalability for premium artisan brands, forcing cost absorption into gift-set premiums while mid-tier producers compete on automated pressing efficiency.
Pricing Analysis
Lead-time premiums reward heritage suppliers with certified inventory positioned for immediate hospitality deployment, while spot-market glass formats trade at discounts due to breakage liability and dimensional inconsistency risks. Three-tier pricing structure across certified lead-free crystal, standard glass, and polycarbonate outdoor formats separates procurement budgets by end-use context. Pricing pressure stems from REACH and EPA reformulation mandates that add €200,000 per product line in testing documentation costs. Chain restaurant buyers exhibit highest price sensitivity due to automated dishwashing compatibility requirements, while collector markets absorb premiums for limited-edition Murano atelier releases.
Supply Chain Analysis
Reverse-logistics flows for damaged crystal decanters remain underdeveloped, with most hospitality breakage handled through landfill disposal rather than refurbishment or material recovery programs. Production concentrates in the Czech Republic, Italy, and Ireland, with Bohemian and Waterford heritage clusters anchoring lead-free crystal supply. Raw material dependencies center on Chinese silica sand, Brazilian rare-earth clarifiers, and German precision molding equipment. Single-source vulnerability runs through concentrated mining operations for high-purity inputs. Distribution runs through specialized glassware wholesalers and direct-to-consumer craft platforms bypassing traditional markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master glassblower generational attrition constrains volume expansion for premium heritage brands, propping pricing power for scaled artisans with established training pipelines. Supply scarcity favors incumbents with captive craft labor and certification infrastructure.
For Market Incumbents: Cement dominance by acquiring distressed Bohemian ateliers with intact ECHA documentation and master glassblower rosters. Expand automated precision-manufacturing capacity in the Czech Republic to serve chain-hospitality procurement mandating ISO 9001-aligned dimensional tolerances. Defend against electric wine aerator substitution by integrating laser-based internal stress detection as a batch-certification premium service. For New Entrants and Emerging Players: BIS certification maturation in India opens a window for first-mover positioning in Mumbai and Bangalore luxury hotel construction. Target underpenetrated vineyard tasting-room retail in Mendoza and Napa with estate-branded merchandise programs. Pursue direct-to-consumer craft platform launches bypassing wholesale distributor markups to capture margin previously allocated to intermediary networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier glass fabricators in Portugal and Spain with dormant lead-free reformulation capabilities and established FDA testing relationships. Long-term viability hinges on certification infrastructure rather than brand heritage alone. Monitor generational transfer rates in Murano and Waterford master glassblower pipelines as inflection indicators for premium-tier supply constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Crystal Reformulation | REACH and EPA mandates force €200,000 product-line investments that eliminate import-dependent distributors. |
| Direct-to-Consumer Platform Launch | Murano and Bohemian artisans capture margin previously allocated to wholesale networks through digital-native channels. |
| Automated Precision Manufacturing Scale-Up | GEA Group and Alfa Laval engineering protocols enable dimensional consistency for chain-hospitality dishwashing compatibility. |
| Vineyard Estate Branded Merchandise | Napa, Bordeaux, and Mendoza tasting rooms create captive retail demand with provenance storytelling premiums. |
| Blockchain-Traceable Batch Certification | Sustainability officers in London and Singapore mandate cradle-to-grave documentation displacing traditional brand loyalty in RFP scoring. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospitality procurement officers, heritage glassblower atelier managers, and FDA compliance consultants validated demand patterns and certification timelines. Secondary sources included ECHA REACH Annex XVII documentation, EPA TSCA Section 8 reporting mandates, BIS certification requirements, and EU Green Deal sustainability reporting frameworks. Bottom-up volume modeling across material grades and design categories triangulated against top-down hospitality construction spend data.
Segmentation-level granularity modeled material type, design taxonomy, and usage context across the projection horizon. Wine decanter replacement cycles, whisky decanter collector acquisition patterns, and gift-set seasonal concentration were dimensioned separately. CAGRs derived from fitted growth curves incorporating regulatory compliance cost trajectories and artisan labor supply constraints. Forecast inputs included luxury hotel construction pipelines in Mumbai and Bangalore, Murano master glassblower retirement rates, and electric wine aerator penetration in North American and East Asian markets.
The model assumes a particular technology adoption path for laser-based internal stress detection systems; alternative pathways for non-destructive quality verification would alter the outlook for heritage brand competitive positioning. Forecasts reflect assumptions regarding REACH and EPA regulatory stability, silica sand supply continuity from Chinese mining operations, and generational transfer rates in European craft ateliers. Practitioners should monitor BIS certification infrastructure development in India and master glassblower pipeline attrition in Waterford for early signals of supply constraint intensification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
Pub Cellar Equipment Market
Alcoholic Beverages
Beer Dispenser Market
Alcoholic Beverages
North America Craft Beer Market
Alcoholic Beverages
Mezcal Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Winetainer Market
Alcoholic Beverages
Hard Tea Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
South Africa Tequila Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Wine Barrel Market
Alcoholic Beverages
Global TCD Alcohol DM Market