
 Global Food-Grade Alcohol Market | 2026-2036
Global Food-Grade Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food-Grade Alcohol Market Foresight
Beverage producers are reorganizing procurement priorities around high-purity ethanol grades, pulling demand away from legacy industrial buyers. Cargill leverages its integrated grain-to-ethanol network across North American corn belts to secure feedstock cost advantages. Archer Daniels Midland anchors its position through continuous fermentation technology investments that tighten specification control. Roquette Freres differentiates via pea-starch derived alcohol streams serving European clean-label beverage brands.
Food-grade alcohol denotes ethanol and allied alcohols meeting pharmacopeial and food safety purity thresholds, typically exceeding 96% concentration with controlled methanol, aldehyde, and heavy metal limits below 10 ppm; manufacturers achieve this through multi-stage rectification, molecular sieve dehydration, and activated carbon filtration to render the substance suitable for human consumption, pharmaceutical excipient duty, and cosmetic solvent applications. Ethanol dominates product type revenue due to its universality across beverage, pharmaceutical, and extraction end uses, while propanol and butanol segments capture narrower but higher-margin niches in flavor encapsulation and natural extract processing. Application-level margin pools concentrate in pharmaceuticals and cosmetics, where USP and FCC certification requirements create specification premiums that bakery and confectionery volumes rarely command.
The FDA, EPA, and EFSA frameworks govern contaminant limits, labeling protocols, and environmental discharge from fermentation facilities, with REACH registration requirements in Europe adding substance dossier burdens that favor larger producers with regulatory affairs capacity. Brazil's ANVISA and China's SAMR enforce parallel purity standards that shape export market access for multinational suppliers. Stakeholders must monitor how evolving biofuel mandates in major grain-producing jurisdictions redirect fermentation capacity between fuel and food-grade channels.
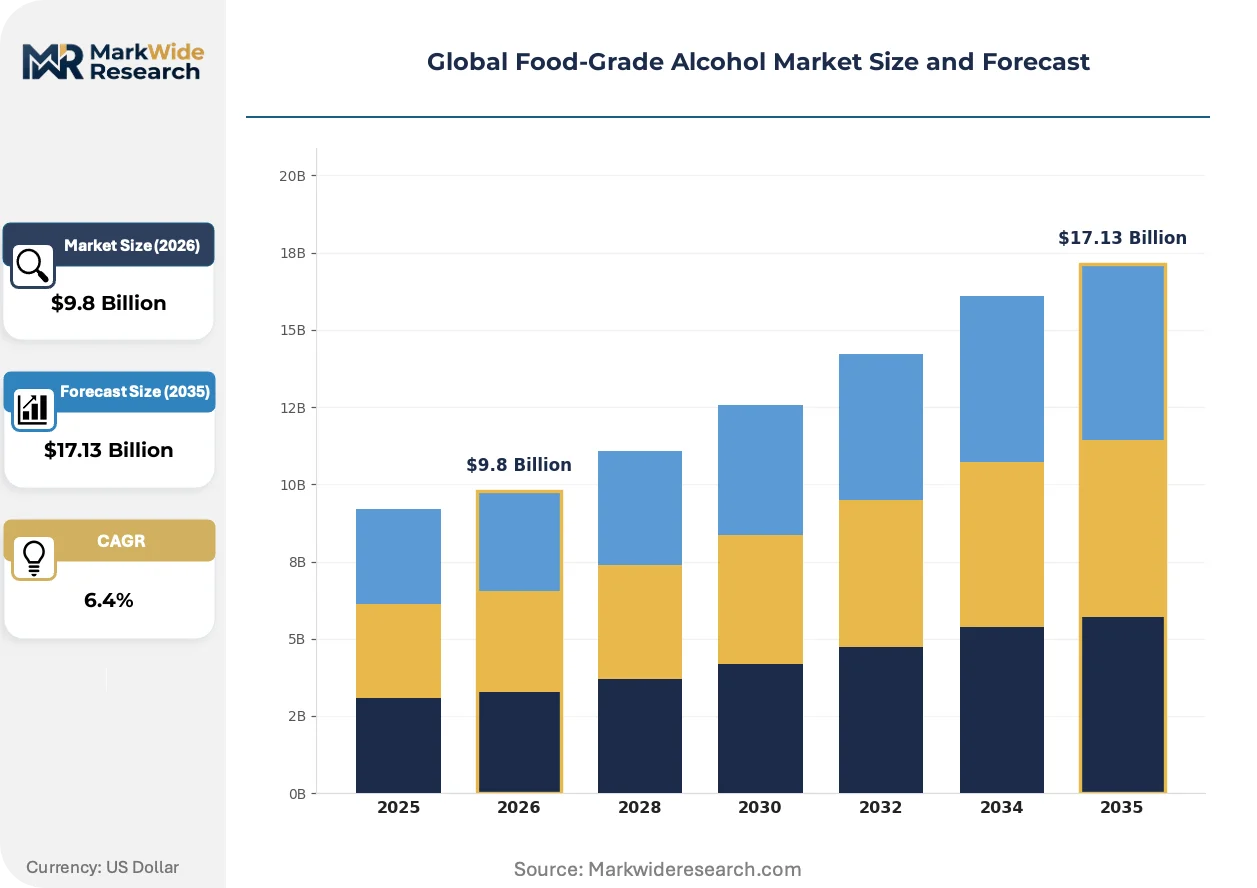
Market Dynamics
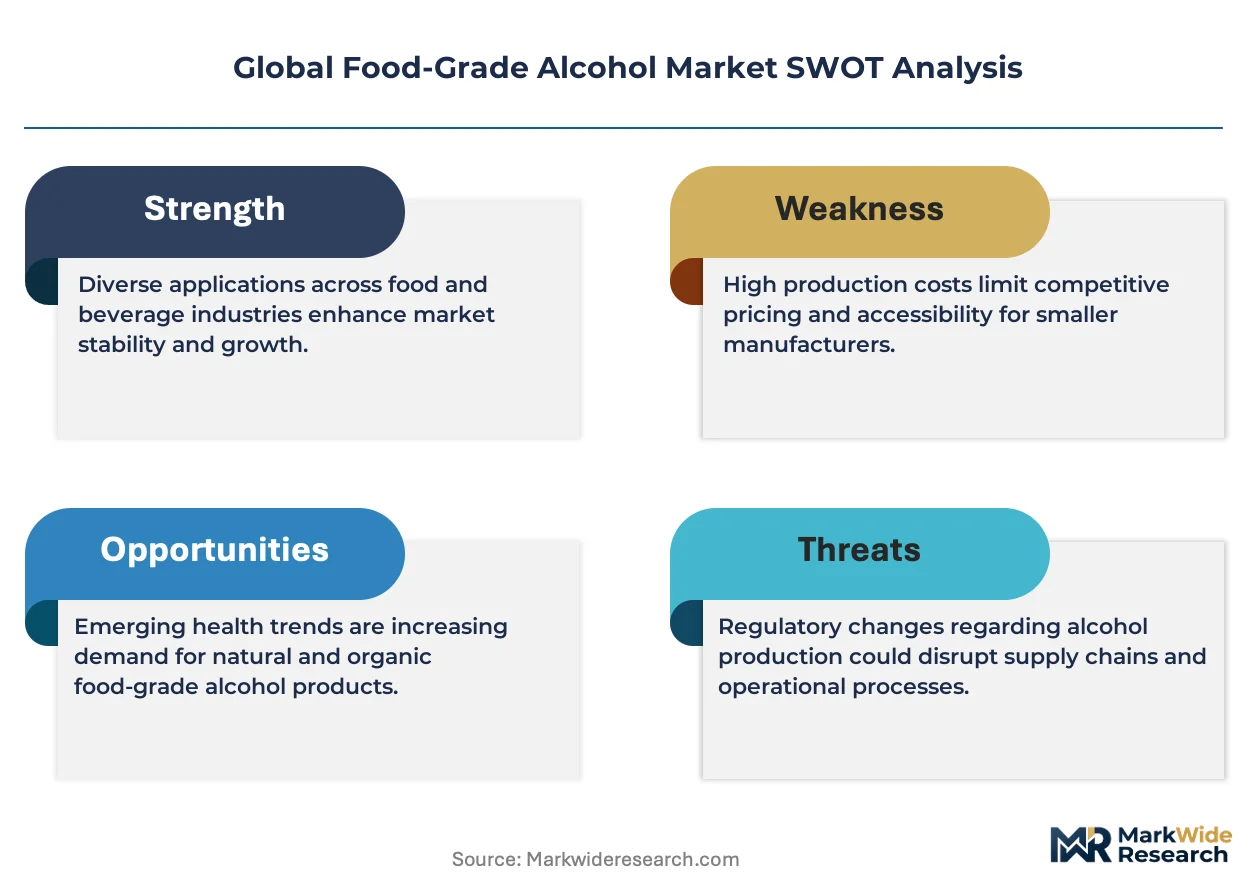
Biofuel policy intersections in grain-producing jurisdictions are redirecting fermentation capacity between fuel and food-grade channels, tightening supply availability for beverage and pharmaceutical buyers while elevating feedstock competition.
Growth Catalysts
- REACH compliance mandates:EFSA and ECHA purity thresholds are forcing legacy industrial ethanol streams toward higher-margin food-grade rectification, expanding certified supply pools for European beverage manufacturers.
- Ready-to-drink formulation expansion:Beverage producers are reformulating cocktail portfolios around neutral grain spirits, pulling volume from traditional distilled categories into higher-throughput canning lines.
- China's SAMR traceability requirements:Import certification protocols are consolidating supplier relationships around multinationals with dossier-ready quality systems, accelerating market share concentration.
Market Restraints
- Corn price volatility:Drought cycles across the US Midwest and Argentine Pampas are compressing crush margins for fermentation-dependent producers without captive grain origination.
- Technical limitation in molecular sieve regeneration:Energy intensity of dehydration cycles caps capacity expansion economics for mid-scale rectifiers lacking combined heat and power integration.
- Brazilian ANVISA export certification friction:Batch-level testing protocols for residual pesticide metabolites are extending customs clearance timelines for sugarcane-derived ethanol shipments.
Strategic Opportunities
- India's FSSAI clean-label acceleration:Natural extract and flavor houses are qualifying pea-starch and cellulosic alcohol streams to serve reformulating confectionery and beverage brands.
- Pharmaceutical excipient grade premiums:USP certification for parenteral and oral dosage applications commands specification multiples that food-grade volumes rarely achieve.
- Carbon capture integration at fermentation sites:EU Green Deal emissions accounting is creating offtake markets for beverage-grade CO2 coproducts, improving unit economics for compliant facilities.
Industry Challenges
- Rectification operator skill scarcity:Multi-stage column control and chromatographic separation expertise is concentrating among aging workforces in European and North American production clusters.
- Cross-contamination protocol complexity:Kosher, halal, and organic certification audits require dedicated tankage and line segregation that fragments batch scheduling efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food-Grade Alcohol Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethanol, Isopropanol, Methanol, Butanol, Propanol Application: Bakery, Confectionery, Beverage, Pharmaceuticals, Cosmetics Packaging Type: Drums, Intermediate Bulk Containers, Bottles, Totes, Carboys End User: Food Manufacturers, Beverage Producers, Personal Care Firms, Pharmaceutical Labs, Chemical Synthesizers |
| Companies Covered | Cargill, Archer Daniels Midland, Roquette Freres, MGP Ingredients, Wilmar International, Grain Processing Corporation, Manildra Group, Cristalco, Fonterra Co-operative Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food-Grade Alcohol Market Shifts & Advancements
Continuous fermentation monitoring and membrane separation advances are compressing specification variance while enabling smaller-scale distributed production closer to end-use clusters.
Membrane pervaporation for final dehydration is supplanting traditional molecular sieve pressure-swing adsorption in new capacity installations. Premium spirits distillers in Scotland and Kentucky are adopting ceramic membrane systems to preserve volatile congeners during proofing. The technology is enabling craft-scale producers to achieve pharmaceutical-grade purity without multi-million-dollar rectification investments.
EU Green Deal carbon border adjustment mechanisms are reshaping import economics for grain-origin ethanol. ETS-linked emissions accounting now differentiates Brazilian sugarcane and US corn streams in European procurement tenders. Beverage multinationals are reformulating sourcing strategies around verified low-carbon intensity supply chains to preempt 2026 tariff phase-ins.
Specification-driven procurement is consolidating buyer-seller relationships around multi-year offtake agreements with embedded quality audits. Pharmaceutical and cosmetics manufacturers are displacing spot-market purchasing with dedicated supply contracts featuring quarterly certification renewals. This pattern is most pronounced in German and Swiss chemical processing corridors where REACH dossier continuity carries regulatory risk weight.
Global Food-Grade Alcohol Market Segmentation
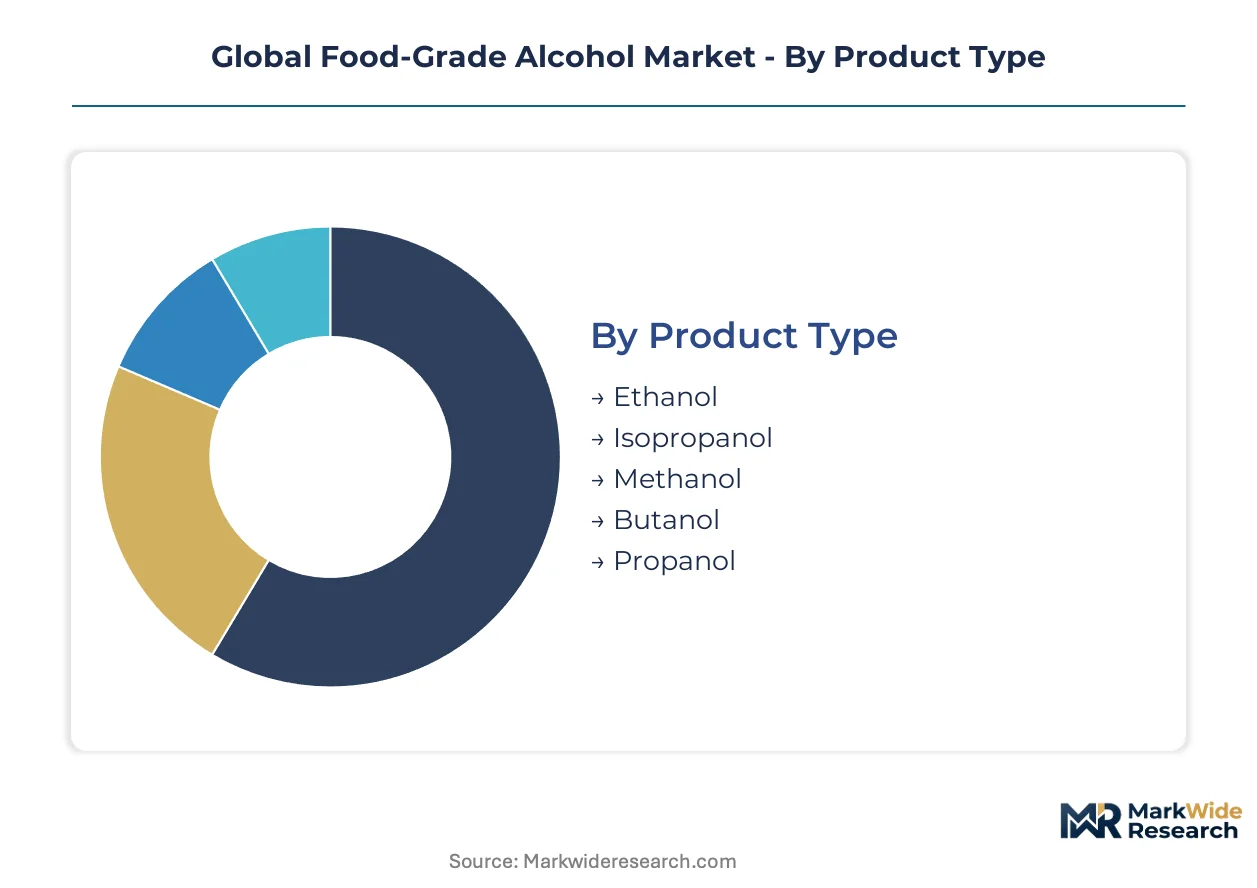
Food-grade alcohol buyers select grades and formats through specification-driven procurement that varies sharply by end-use compliance burden and supply chain proximity. Segmentation reveals how pharmaceutical and beverage channels pull divergent purity premiums while packaging economics reshape distribution reach.
Product Type:
Domestic fermentation capacity in grain-belt regions supplies ethanol and butanol primarily to national beverage and food manufacturers, while isopropanol and propanol move through specialized export channels serving pharmaceutical and cosmetics formulators in regulated jurisdictions.
- Ethanol:Multi-stage rectification achieves concentrations exceeding 96% with methanol and aldehyde limits below 10 ppm, rendering it suitable for human consumption. Demand concentrates in United States beverage canning lines and Brazilian sugarcane-derived spirits production, where biofuel policy intersections tighten feedstock competition. REACH-compliant European imports favor verified low-carbon intensity supply chains.
- Butanol:Higher molecular weight delivers superior flavor encapsulation properties for natural extract processing. Japanese and German flavor houses are qualifying butanol streams for clean-label confectionery reformulations, though volume remains constrained by fermentation yield economics relative to ethanol.
- Isopropanol:Antiseptic-grade specifications serve pharmaceutical excipient and cosmetic solvent applications under USP and FCC certification.
- Methanol:Strictly controlled trace limits restrict food-grade methanol to specialized extraction processes with heavy regulatory documentation.
- Propanol:Narrow niche in parenteral dosage formulations commands specification multiples that food-grade volumes rarely achieve.
Ethanol commands the established base. The steepest expansion runs through butanol as clean-label extract demand climbs.
Application:
Margin stratification separates pharmaceutical and cosmetics certification premiums from commodity bakery and confectionery volumes, with beverage applications occupying a mid-tier defined by brand positioning rather than specification alone.
- Pharmaceuticals:USP certification for parenteral and oral dosage applications mandates batch-level documentation and quarterly renewal audits. Swiss and German chemical processing corridors are consolidating procurement around multi-year offtake agreements with embedded quality systems, displacing spot-market purchasing.
- Beverage:Neutral grain spirits feed ready-to-drink canning expansion while premium spirits maintain pot still and column distillation differentiation. Scotland and Kentucky distillers are adopting ceramic membrane systems to preserve volatile congeners during proofing.
- Cosmetics:FCC-grade solvents for skincare formulation require heavy metal limits below 10 ppm with activated carbon filtration documentation.
- Bakery:Vanilla and almond extract carriers operate at thinner margins with less stringent certification overhead.
- Confectionery:Flavor dilution applications prioritize cost efficiency over specification premiums in mass-market segments.
Pharmaceuticals capture the highest margin pool. Beverage applications are expanding most quickly through ready-to-drink reformulation.
Packaging Type:
Volume scale and handling automation requirements segment packaging selection, with bulk formats dominating ingredient supply to manufacturers while unitized packaging serves laboratory and craft-scale end users.
- Intermediate Bulk Containers:1000-liter totes with aseptic liners minimize transfer contamination for pharmaceutical and beverage manufacturers with automated dosing systems. European facilities are qualifying IBC formats for REACH-registered substance handling with embedded traceability codes.
- Drums:200-liter steel and HDPE drums retain dominance in chemical synthesizer and personal care firm procurement where batch segregation and kosher/halal certification require dedicated tankage.
- Totes:Collapsible intermediate formats reduce return logistics costs for high-frequency ingredient replenishment.
- Bottles:Glass and fluorinated polymer bottles serve analytical laboratory and small-batch cosmetics formulators.
- Carboys:Traditional glass carboys persist in legacy pharmaceutical compounding operations with established validation protocols.
Intermediate bulk containers are gaining share fastest in automated manufacturing corridors. Drums retain the volume base in certification-intensive segments.
End User:
Procurement sophistication varies by regulatory exposure, with pharmaceutical labs and personal care firms operating specification-driven systems while food manufacturers prioritize feedstock cost stability.
- Pharmaceutical Labs:Parenteral and oral dosage manufacturers enforce USP certification with quarterly dossier renewals and on-site supplier audits. Swissmedic and FDA inspection readiness concentrates purchasing among multinationals with regulatory affairs capacity.
- Beverage Producers:Premium spirits and ready-to-drink formulators are reorganizing procurement around high-purity ethanol grades, pulling demand from legacy industrial buyers toward integrated grain-to-ethanol networks.
- Personal Care Firms:Clean-label positioning drives qualification of pea-starch and cellulosic alcohol streams for reformulating skincare and fragrance products.
- Food Manufacturers:Extract and flavor dilution applications prioritize supply security over specification premiums.
- Chemical Synthesizers:Intermediate chemical production utilizes food-grade alcohol as reaction solvent where residual purity affects downstream product registration.
Pharmaceutical labs anchor the specification premium tier. Beverage producers are climbing the fastest as ready-to-drink expansion redirects volume flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian sugarcane-derived ethanol flows primarily to European beverage manufacturers seeking low-carbon intensity supply chains under EU Green Deal carbon border adjustments. United States corn-belt fermentation capacity serves both domestic ready-to-drink canning expansion and pharmaceutical excipient demand.
United States
Midwest grain processors supply neutral grain spirits to expanding ready-to-drink canning lines while pharmaceutical manufacturers in New Jersey and North Carolina pull USP-grade volumes. FDA purity thresholds and EPA environmental discharge protocols govern fermentation facility operations. Iowa and Illinois corn-belt clusters concentrate multi-stage rectification capacity with integrated carbon capture coproduct recovery.
Brazil
Sugarcane mills in São Paulo state redirect hydrous ethanol streams between fuel and beverage-grade channels as ANVISA export certification requirements tighten batch-level pesticide metabolite testing. The country's national pharmaceutical regulator enforces parallel purity standards shaping access for multinational suppliers. Paulínia and Piracicaba industrial corridors anchor fermentation capacity serving European procurement tenders.
Germany
REACH-registered substance dossiers and ECHA purity mandates consolidate supplier relationships around multinationals with regulatory affairs capacity in the Rhine-Ruhr chemical processing corridor. ETS-linked emissions accounting differentiates feedstock origins in procurement decisions. Hamburg and Rotterdam-Antwerp port clusters handle verified low-carbon intensity ethanol imports for beverage reformulation.
China
SAMR import certification protocols with embedded traceability requirements accelerate market share concentration among dossier-ready suppliers serving pharmaceutical and cosmetics manufacturers in Jiangsu and Zhejiang provinces. The country's national standards body enforces contaminant limits parallel to USP and FCC frameworks. Yangtze River Delta fermentation sites scale capacity amid biofuel policy intersections with food-grade output.
India
FSSAI clean-label acceleration drives qualification of alternative starch-derived alcohol streams for reformulating confectionery and beverage brands in Maharashtra and Gujarat. The country's food safety regulator tightens purity documentation for natural extract processing. Mumbai-Pune and Ahmedabad-Vadodara industrial belts concentrate flavor house procurement upgrading specification requirements.
Global Food-Grade Alcohol Market Competitive Landscape
Player mix skews toward integrated agribusiness conglomerates with captive grain origination networks and mid-scale rectifiers serving regional certification-intensive segments. Market structure concentrates around three strategic archetypes: grain-to-ethanol integrators controlling upstream feedstock costs, continuous fermentation technology specialists tightening specification variance, and alternative starch-derived alcohol innovators serving clean-label demand pools. Dominant competitive moves include multi-year offtake agreements with embedded quality audits and membrane pervaporation technology licensing for distributed craft-scale production.
Among North American agribusiness integrators, Cargill and Archer Daniels Midland represent the grain-to-ethanol archetype with Midwest corn-belt network density, while Roquette Freres exemplifies European alternative starch specialization serving REACH-compliant beverage reformulation. These three occupy positions spanning feedstock cost control, continuous fermentation scale, and pea-starch differentiation vectors respectively.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Roquette Freres |
| MGP Ingredients |
| Wilmar International |
| Grain Processing Corporation |
| Manildra Group |
| Cristalco |
| Fonterra Co-operative Group |
| Others |
Supply & Pricing Matrix
Mid-scale rectifier capacity-utilization gaps between molecular sieve and membrane pervaporation installations create divergent cost floors across the ethanol value chain. These technology-driven scale economies concentrate pricing power among integrated grain-to-ethanol networks in the US Midwest and São Paulo state, while elevating entry barriers for distributed craft-scale competitors lacking combined heat and power integration.
Pricing Analysis
Membrane pervaporation dehydration technology commands 15-20% specification premiums over legacy molecular sieve pressure-swing adsorption systems in pharmaceutical-grade procurement. Three-tier pricing structure across USP-certified, FCC-grade, and industrial-rectified ethanol levels segments buyer pools by certification burden and batch documentation requirements. Pricing pressure stems from corn price volatility across the US Midwest and Argentine Pampas compressing crush margins for non-integrated producers. Chemical synthesizers and mass-market confectionery manufacturers exhibit highest price sensitivity, while parenteral pharmaceutical labs absorb specification multiples without volume elasticity.
Supply Chain Analysis
Port congestion at Rotterdam-Antwerp and Hamburg clusters extends customs clearance timelines for Brazilian sugarcane-derived ethanol shipments facing ANVISA batch-level pesticide metabolite testing. Geographic supply concentration centers on the United States, Brazil, and China as these countries scale fermentation capacity amid biofuel policy intersections. Raw material dependencies draw from corn belts in Iowa and Illinois, São Paulo sugarcane estates, and Yangtze River Delta grain processing corridors. Single-source vulnerability runs through EU Green Deal carbon border adjustment mechanisms differentiating feedstock origins in European procurement tenders. Distribution feeds from bulk intermediate bulk container formats to automated beverage canning lines and pharmaceutical manufacturing sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food-grade alcohol market is cycling through a capacity rationalization phase as biofuel policy redirects fermentation output between fuel and beverage-grade channels. Corn price volatility and REACH compliance investments are compressing margins for non-integrated players while rewarding scale economies.
For Market Incumbents: Consolidate procurement relationships around multi-year offtake agreements with embedded quarterly certification renewals to lock in pharmaceutical and cosmetics volume. Deepen backward integration into captive grain origination networks across North American corn belts to insulate crush margins from drought cycles. Prioritize membrane pervaporation technology licensing to mid-scale rectifiers seeking distributed production capabilities without multi-million-dollar capital commitments.
For New Entrants and Emerging Players: Anchor in India's FSSAI clean-label acceleration by qualifying pea-starch and cellulosic alcohol streams for reformulating confectionery and beverage brands in Maharashtra and Gujarat. Target pharmaceutical excipient grade premiums in Swiss and German chemical processing corridors where USP certification commands specification multiples. Pursue carbon capture integration partnerships at fermentation sites to improve unit economics through EU Green Deal emissions accounting offtake markets.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors continuous fermentation specialists with regulatory affairs capacity and dossier-ready quality systems. Long-term viability over the next decade hinges on differentiation through alternative starch-derived alcohol innovation and REACH-registered substance handling infrastructure. Acquisition targets should demonstrate embedded traceability codes and multi-jurisdiction certification continuity. The signal to watch is EU Green Deal carbon border adjustment tariff phase-ins reshaping import economics for grain-origin ethanol.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Pervaporation Technology Licensing | Ceramic membrane systems enable craft-scale producers to achieve pharmaceutical-grade purity without multi-million-dollar rectification investments. |
| Multi-Year Offtake Agreement Expansion | Pharmaceutical manufacturers in Swiss and German corridors are displacing spot-market purchasing with dedicated supply contracts featuring embedded quality audits. |
| Carbon Capture Integration at Fermentation Sites | EU Green Deal emissions accounting creates offtake markets for beverage-grade CO2 coproducts, improving unit economics for compliant facilities. |
| Alternative Starch-Derived Alcohol Qualification | Pea-starch and cellulosic streams serve European clean-label beverage brands and Indian FSSAI reformulating confectionery manufacturers. |
| REACH-Registered Substance Dossier Investment | ECHA purity mandates consolidate supplier relationships around multinationals with regulatory affairs capacity in the Rhine-Ruhr chemical processing corridor. |
Research Methodology
Cross-validation between primary interviews with fermentation plant managers, beverage procurement leads, pharmaceutical regulatory affairs directors, and distribution channel partners anchors the qualitative findings. Secondary validation draws from FDA filings, EFSA contaminant limit databases, ANVISA export certification protocols, and customs/trade data for ethanol flows through Rotterdam-Antwerp and Hamburg port clusters. Bottom-up capacity modeling across molecular sieve and membrane pervaporation installations triangulates against top-down demand aggregation from beverage canning line expansions and pharmaceutical excipient procurement patterns.
Sensitivity analysis around corn price volatility scenarios and biofuel policy intersection effects informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, packaging format, and regional production hub clustering. CAGRs derive from installed capacity trajectories, technology adoption curves for membrane pervaporation systems, and specification premium capture rates in pharmaceutical versus beverage channels. Industry-specific forecast inputs incorporate EU Green Deal carbon border adjustment implementation timelines and SAMR traceability requirement phase-ins.
Material uncertainties — drought cycles across the US Midwest and Argentine Pampas, REACH dossier renewal friction, and Brazilian ANVISA batch-level testing protocol extensions — sit outside the modeled envelope. Forecasts reflect assumptions regarding fermentation capacity allocation between fuel and food-grade channels, membrane pervaporation cost reduction curves, and carbon capture coproduct market development. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Asia-Pacific Kegs Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
Commercial Beer Tap System Market
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
Global Distillation System Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
Alcohol Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Absinthe Market
Alcoholic Beverages
UK Tequila Market
Alcoholic Beverages
Europe Alcohol E-Commerce Market
Alcoholic Beverages
India Alcohol Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market