
 Stemware Market | 2026-2036
Stemware Market Size, Share, and Industry Trends Forecast 2026-2036
Stemware Market Analytics
EU REACH chemical compliance is consolidating cost-of-entry calculus for European stemware producers, forcing reformulation of traditional lead-crystal recipes. Baccarat leverages its heritage positioning to sustain pricing power in ultra-premium hospitality channels. Zwiesel Kristallglas AG anchors German engineering credibility through patented Tritan crystal technology that resists chipping in commercial dishwashers. Libbey competes aggressively on volume scale across North American casual-dining chains with standardized bowl shapes optimized for automated polishing lines.
Stemware denotes footed drinking vessels engineered with elongated stems to isolate hand warmth from bowl contents, typically fabricated from soda-lime glass, lead-free crystal, or borosilicate compositions fired at 1,400–1,600°C before precision molding or hand-blowing. Red wine glasses with oversized bowls dominate commercial procurement volumes due to sommelier-driven service protocols in full-service restaurants. Crystal material commands the deepest margin pools despite slower volume growth, as Bavarian producers extract value from tourism-linked authenticity narratives and limited-batch handcrafting. Acrylic segments attract outdoor hospitality operators seeking shatter resistance for poolside and rooftop venues where glass breakage liability constrains traditional alternatives.
CE marking governs mechanical safety and thermal shock resistance for stemware distributed across European Union member states, while FDA indirect food additive regulations in the United States limit lead and cadmium migration from decorative surface coatings into beverages. Germany's Federal Institute for Risk Assessment periodically revises leachable heavy metal thresholds, compelling exporters like Stölzle Lausitz to maintain dual certification portfolios. Stakeholders must monitor whether California's Proposition 65 enforcement expansion into tableware categories triggers broader state-level disclosure mandates that reshape labeling and material sourcing decisions.
Market Dynamics
The EU's revised Packaging and Packaging Waste Regulation is forcing lead-crystal reformulation across European manufacturing clusters, compressing margin structures for traditional producers while opening technical pathways for engineered glass substitutes.
Growth Catalysts
- Experiential dining expansion:Upscale restaurants in Germany and France are multiplying tasting-menu formats that require dedicated stemware collections per wine service protocol.
- REACH chemical compliance:The ECHA framework is consolidating cost-of-entry calculus, eliminating marginal producers and concentrating volume among certified manufacturers.
- Tritan crystal engineering:Patented borosilicate-titanium formulations now resist commercial dishwasher thermal shock, unlocking institutional procurement channels previously closed to crystal.
Market Restraints
- Raw material concentration:High-purity silica sand deposits cluster in specific Bavarian and Thuringian districts, creating geographic supply vulnerability.
- Energy cost volatility:Natural gas-fired melting furnaces operating at 1,400–1,600°C face input cost instability across German industrial zones.
- Acrylic substitution threat:Shatter-resistant polymer vessels capture outdoor hospitality segments where glass breakage liability constrains traditional procurement.
Strategic Opportunities
- Tourism-linked authenticity narratives:Bavarian glassmaking clusters extract premium pricing from heritage-positioned limited-batch handcrafting for luxury hospitality.
- California Proposition 65 expansion:Anticipated enforcement into tableware categories creates first-mover advantage for compliant labeling systems.
- Automated polishing integration:Machine-blown collections optimized for robotic finishing lines reduce unit labor content for volume casual-dining contracts.
Industry Challenges
- Master glassblower scarcity:Hand-finishing expertise concentrates among aging practitioners in Bohemian and Bavarian craft lineages with limited apprenticeship pipelines.
- Dual certification complexity:Exporters must maintain parallel FDA and BfR compliance portfolios with divergent leachable heavy metal thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stemware Market |
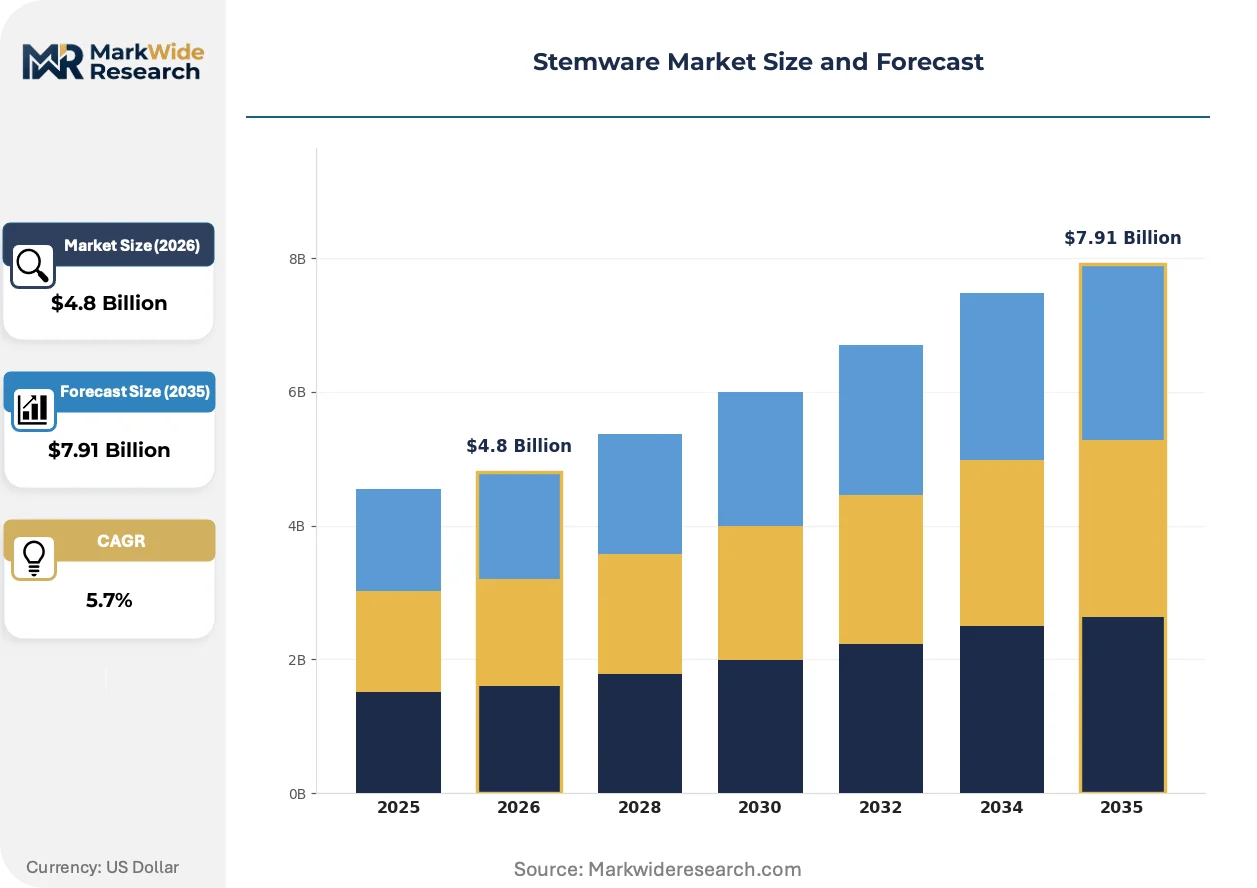
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Wine Glasses, White Wine Glasses, Champagne Flutes, Cocktail Glasses Material: Crystal, Glass, Acrylic, Stainless Steel Design: Traditional, Modern, Vintage, Elegant Customer Type: Restaurants, Households, Event Planners, Hotels |
| Companies Covered | Baccarat, Libbey, Tiroler Glashütte GmbH, Zwiesel Kristallglas AG, Bormioli Luigi S.p.A., Waterford, Cristal d'Arques Paris, Stölzle Lausitz, Bayerische Glaswerke GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stemware Market Evolving Landscape
Active reformulation of crystal chemistry and service-format specialization are compressing traditional category boundaries, with material science and regulatory compliance converging to redefine competitive positioning.
Laser-based internal engraving technology is electrifying personalization services for hospitality procurement. Premium hotel chains in Dubai and Singapore now specify monogrammed bowl bases for private-dining rooms. This capability is compressing minimum-order quantities and enabling just-in-time customization previously reserved for hand-blown commissions.
REACH Annex XVII restrictions on lead migration are forcing compositional pivots across EU manufacturing. Traditional lead-crystal recipes face phased elimination, accelerating adoption of barium-zinc alternatives. German producers are responding with engineered transparency matching refractive indices of legacy formulations.
Sommelier-driven service protocols now dictate bowl geometry standardization across full-service restaurant chains. Red wine glasses with 650ml+ bowl capacities dominate commercial specification sheets. This preference consolidation is visible across independent restaurant groups in Melbourne, Copenhagen, and Mexico City seeking credential alignment with Court of Master Sommeliers service standards.
Stemware Market Segmentation
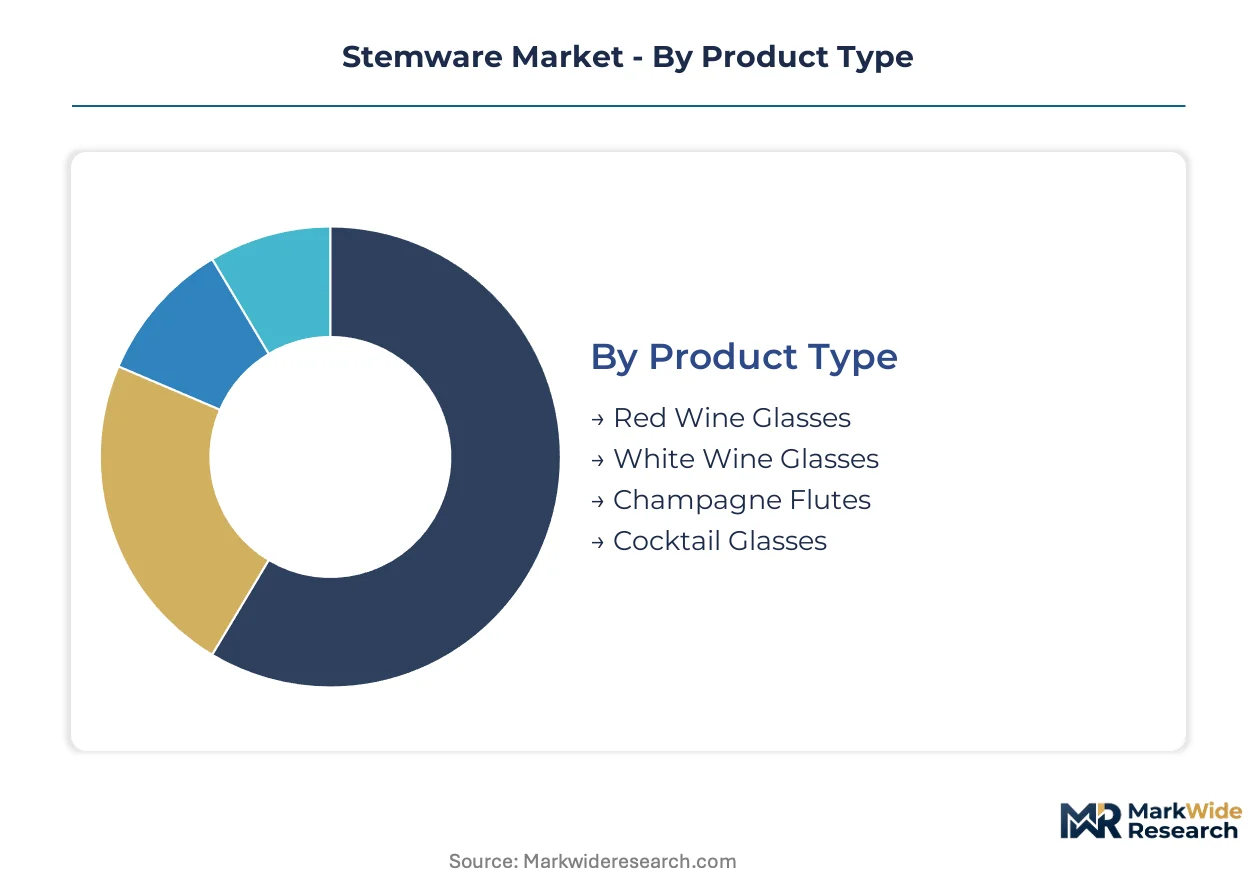
Stemware procurement decisions hinge on divergent compliance burdens across hospitality versus household channels. Certification requirements from FDA, REACH, and CE marking reshape competitive viability within each segment cluster.
Product Type:
CE marking governs mechanical safety for all stemware categories distributed across EU member states, while FDA indirect food additive regulations constrain lead migration in US-bound shipments.
- Red Wine Glasses:Oversized bowls with 650ml+ capacities dominate commercial procurement due to sommelier-driven service protocols in full-service restaurants. Bavarian producers supply machine-blown collections optimized for automated polishing lines to North American casual-dining chains.
- White Wine Glasses:Narrower bowl profiles concentrate aromatics for chilled service temperatures. Demand concentrates in French and Italian hospitality markets where tasting-menu formats require dedicated glassware per varietal protocol.
- Champagne Flutes:Elongated silhouettes preserve effervescence in celebratory service contexts. Acrylic substitutes capture outdoor hospitality segments in Dubai and Singapore rooftop venues.
- Cocktail Glasses:Stemmed martini and coupe variants serve mixology-focused establishments. Vintage design revivals drive procurement from heritage-positioned German handcrafting clusters.
Leading the category by volume: Red Wine Glasses. Growing fastest: Champagne Flutes.
Material:
REACH Annex XVII restrictions on lead migration force compositional pivots across EU manufacturing, eliminating marginal producers from crystal segments.
- Crystal:Barium-zinc engineered formulations now match refractive indices of legacy lead-crystal recipes. Bavarian tourism-linked authenticity narratives extract premium pricing for limited-batch handcrafting in luxury hospitality channels.
- Glass:Soda-lime compositions fired at 1,400–1,600°C serve standardized bowl shapes across high-volume casual-dining contracts. Libbey anchors North American procurement through scale-optimized machine production.
- Acrylic:Shatter-resistant polymer vessels eliminate breakage liability for poolside and rooftop operators. Outdoor hospitality segments in coastal US states and Mediterranean resorts drive adoption.
- Stainless Steel:Thermal retention properties suit insulated wine service in extreme climates. Expedition and adventure hospitality operators in alpine and desert geographies specify double-walled constructions.
Crystal commands the deepest margin pools despite slower volume expansion. Acrylic segments are climbing the fastest as liability-conscious operators diversify material portfolios.
Design:
Laser-based internal engraving capabilities compress minimum-order quantities and enable just-in-time customization previously reserved for hand-blown commissions.
- Traditional:Classical silhouettes align with Court of Master Sommeliers credential standards across Melbourne and Copenhagen independent restaurant groups.
- Modern:Minimalist geometries target design-forward hospitality concepts in Singapore and Dubai premium hotel chains.
- Vintage:Coupe and Nick-and-Nora revivals serve craft cocktail establishments seeking Prohibition-era aesthetic differentiation.
- Elegant:Hand-finished details from Thuringian glassmaking clusters supply ultra-premium hospitality procurement with monogrammed bowl bases.
Modern design leads procurement volume from new-build hospitality developments. Vintage styling shows the steepest expansion trajectory as mixology culture proliferates.
Customer Type:
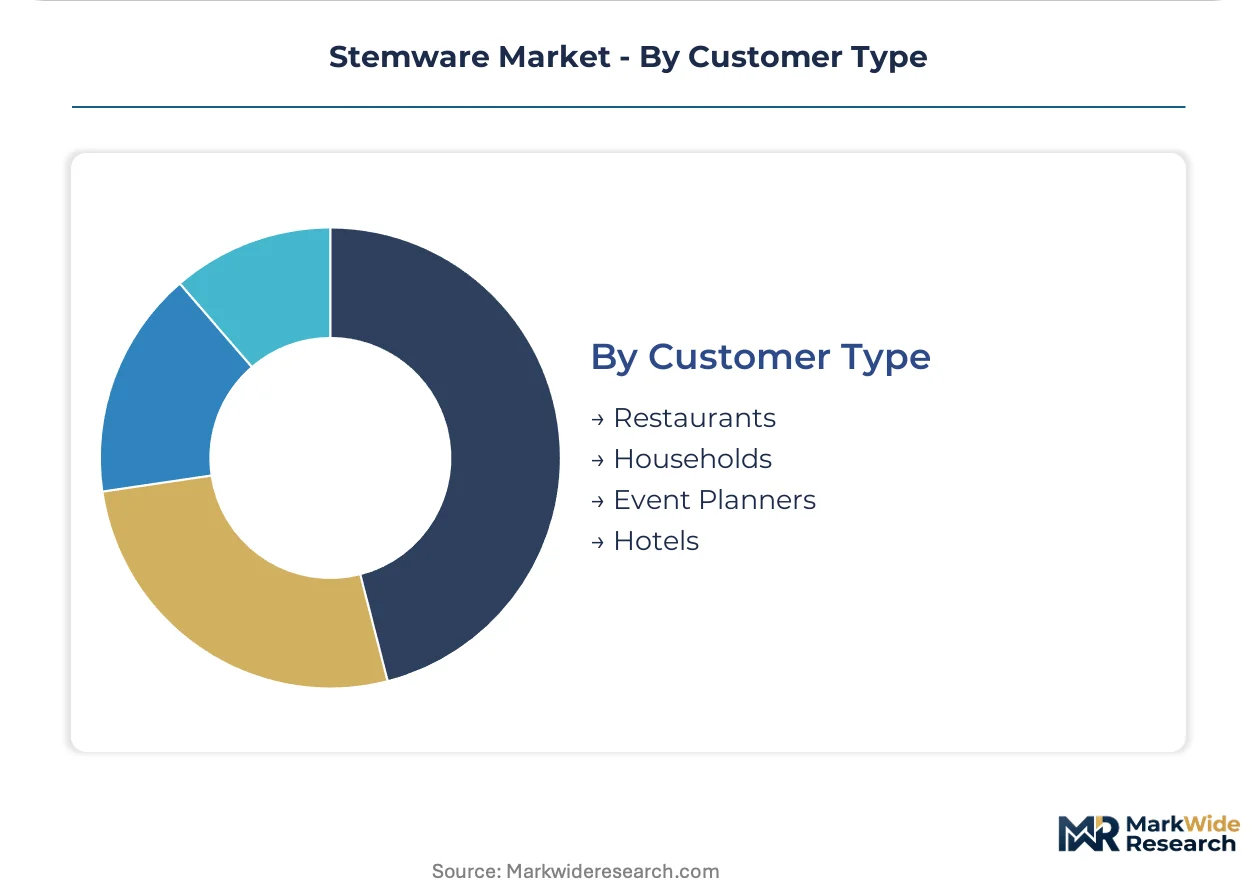
Dual certification complexity separates institutional buyers maintaining parallel FDA and BfR compliance portfolios from price-sensitive household segments.
- Restaurants:Full-service chains specify Tritan crystal engineering for commercial dishwasher thermal shock resistance. Zwiesel Kristallglas AG anchors German engineering credibility in this channel.
- Households:E-commerce-direct procurement favors standardized machine-blown collections with reduced unit labor content. German and French consumers prioritize heritage-positioned Bavarian authenticity.
- Event Planners:Rental-oriented procurement demands chip-resistant durability across high-turnover service cycles. Acrylic and engineered glass substitutes penetrate this segment.
- Hotels:Private-dining room specifications increasingly require laser-engraved personalization at compressed lead times. Premium chains in Dubai and Singapore drive this capability adoption.
Restaurants dominate absolute procurement volume. Hotels are gaining share fastest as experiential dining formats multiply across luxury hospitality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bavaria and Thuringia concentrate glassmaking heritage assets, while REACH compliance costs are redrawing competitive boundaries across European manufacturing clusters. Tax incentives for craft preservation in these zones sustain hand-finishing capabilities against automated Asian competition.
Germany
Experiential dining formats in Munich and Berlin drive crystal stemware procurement from heritage-positioned hospitality chains. The Federal Institute for Risk Assessment periodically revises leachable heavy metal thresholds, compelling dual certification maintenance. Bavarian glassmaking clusters supply machine-blown collections optimized for automated polishing lines.
United States
Casual-dining chains across the Midwest and Southeast specify standardized bowl shapes for high-volume service protocols. FDA indirect food additive regulations limit lead and cadmium migration from decorative surface coatings into beverages. Toledo, Ohio anchors North American machine-blown production through scale-optimized manufacturing infrastructure.
France
Tasting-menu proliferation in Paris and Lyon requires dedicated stemware collections per varietal service protocol. ECHA REACH Annex XVII restrictions on lead migration force compositional pivots across EU manufacturing. Cristallerie traditions in Baccarat and Saint-Louis sustain ultra-premium positioning through limited-batch handcrafting.
Italy
Mixology-focused establishments in Milan and Rome drive vintage coupe and Nick-and-Nora revivals for Prohibition-era aesthetic differentiation. CE marking governs mechanical safety and thermal shock resistance for EU-distributed tableware. Murano and Tuscany glassworking districts supply heritage-positioned collections to European luxury hospitality.
China
Premium hotel developments in Shanghai and Shenzhen specify laser-engraved personalization for private-dining room differentiation. The country's national standards body enforces food-contact material safety requirements for imported tableware. Yangtze River Delta manufacturing zones produce machine-blown collections for cost-sensitive hospitality procurement.
Stemware Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. The vendor base organizes around three strategic archetypes: heritage-positioned crystal houses commanding ultra-premium hospitality channels, scale-driven machine-blown producers serving high-volume casual-dining contracts, and engineered-material specialists commercializing dishwasher-resistant formulations. Competitive moves concentrate on automated polishing integration and dual certification portfolio maintenance.
Within the heritage-positioned tier, Baccarat and Waterford exemplify authenticity-driven positioning through French and Irish craft lineages respectively. Zwiesel Kristallglas AG anchors German engineering credibility through patented crystal technology. These three represent distinct geographic anchoring strategies—French luxury narrative, Irish craft heritage, and German precision engineering—each occupying defensible positions against commoditization pressure.
| Leading Market Players |
|---|
| Baccarat |
| Libbey |
| Tiroler Glashütte GmbH |
| Zwiesel Kristallglas AG |
| Bormioli Luigi S.p.A. |
| Waterford |
| Cristal d'Arques Paris |
| Stölzle Lausitz |
| Bayerische Glaswerke GmbH |
| Others |
Value Network & Pricing Analysis
Automated polishing line integration across Bavarian manufacturing clusters compresses unit labor content while concentrating procurement leverage among volume buyers. This capital-intensive transition simultaneously elevates cost barriers for marginal producers and tightens price discipline across standardized machine-blown segments.
Pricing Analysis
Short lead-time premiums command substantial markups in hospitality procurement, while spot inventory liquidations from overcapacity periods trigger discounting cascades. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with REACH-compliant crystal extracting brand premiums over unverified imports. Cost compression in economy tiers intensifies because Asian machine-blown imports erode margin floors. Casual-dining chains exhibit acute price sensitivity, whereas ultra-premium hotel operators prioritize lead-time reliability over unit cost.
Supply Chain Analysis
CE marking and FDA dual certification requirements gate supplier eligibility for cross-border distribution, eliminating uncertified competitors from institutional channels. High-purity silica sand deposits draw from Bavarian and Thuringian districts, with boron and titanium oxide additives sourcing from Chinese and Turkish chemical processors. Single-source vulnerability concentrates in specialized furnace electrode suppliers for 1,400°C melting operations. Distribution runs through hospitality-focused distributors in Germany and France, with direct OEM relationships penetrating North American casual-dining chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII compliance costs are consolidating this market into a consolidation play, forcing reformulation investments that marginal producers cannot absorb.
For Market Incumbents: Cement engineering credibility through patented Tritan crystal certification investments that lock out commodity competitors. Anchor procurement relationships with hospitality chains through guaranteed commercial dishwasher thermal shock performance. Acrylic substitution threats from outdoor venue operators demand preemptive shatter-resistant glass formulations. For New Entrants and Emerging Players: Enter via laser-engraved personalization services where compressed minimum-order quantities enable just-in-time customization for premium hotel private-dining rooms. Target event planner rental segments with chip-resistant durability specifications underserved by heritage handcrafters. Pursue direct e-commerce household channels emphasizing Bavarian authenticity narratives. For Investors and Strategic Acquirers: Exit pathways concentrate in heritage-positioned crystal houses with defensible tourism-linked authenticity narratives and limited-batch handcrafting capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than volume scale. Watch for California Proposition 65 enforcement expansion into tableware as inflection indicator for compliance-premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation Program | Barium-zinc engineered transparency preserves refractive performance while eliminating lead-crystal regulatory liability across EU distribution. |
| Automated Polishing Line Integration | Robotic finishing reduces unit labor content for North American casual-dining contracts competing with Asian imports. |
| Laser Engraving Capability Deployment | Internal monogramming technology captures premium hotel procurement in Dubai and Singapore with compressed lead times. |
| Tritan Crystal Patent Licensing | Commercial dishwasher thermal shock resistance unlocks institutional procurement channels previously closed to traditional crystal. |
| Tourism-Linked Heritage Positioning | Bavarian glassmaking authenticity narratives extract pricing power from luxury hospitality seeking craft lineage differentiation. |
Research Methodology
Trade association filings, customs export records, and hospitality procurement databases formed the secondary backbone for volume and trade flow calibration. Primary interviews with glassmaking plant managers, hospitality procurement directors, and distribution channel partners validated production cost structures and pricing dynamics. Bottom-up and top-down triangulation reconciled facility-level capacity data with national production statistics.
Bottom-up modeling anchored forecasts in machine-blown versus hand-finished production splits, cross-referenced with material composition trends and end-use segment growth differentials. Segmentation dimensions included product type, material grade, design category, and customer channel across the analysis window. CAGRs derived from regression-weighted historical shipment patterns adjusted for regulatory phase-in schedules and energy cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA enforcement intensity variations and natural gas price volatility in German industrial zones. Forecasts reflect assumptions about REACH transition timelines and hospitality capital expenditure cycles. A model refresh is warranted upon material change in EU Packaging and Packaging Waste Regulation implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Spirit-Based RTD Mixes Market
Alcoholic Beverages
Beer Line Cooling System Market
Alcoholic Beverages
Beer Bottling Kit Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Home Brew Boiler Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
Built-In Wine Coolers Market
Alcoholic Beverages
Europe Alcohol E-Commerce Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Microbrewery Supplies Market
Alcoholic Beverages
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market
Alcoholic Beverages
Europe Beer Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Craft Wine Market