
 Liqueurs Market | 2026-2036
Liqueurs Market Size, Share, and Industry Trends Forecast 2026-2036
Liqueurs Market Outlook
Multi-source botanical procurement is hardening as a competitive necessity for premium liqueur producers. Diageo leverages its vertical integration into vanilla and citrus supply chains to secure consistent flavor profiles across its portfolio. Pernod Ricard anchors its anise and herb sourcing through long-term agricultural partnerships in the Mediterranean basin. Rémy Cointreau differentiates through controlled orange peel cultivation in Caribbean and Corsican orchards.
Liqueurs are sweetened, flavored spirit beverages typically produced through maceration, distillation, or compounding of fruits, herbs, spices, or cream bases with neutral spirits at 15–40% ABV, serving primarily as cocktail modifiers, digestifs, or dessert accompaniments in on-premise and retail channels. Fruit Liqueurs dominate volume due to their versatility in mixology and lower production complexity, while Cream Liqueurs command margin premiums through proprietary emulsion technologies and limited shelf-stable formulations. Herbal Liqueurs occupy a mature but defensible niche tied to regional drinking rituals and established brand legacies.
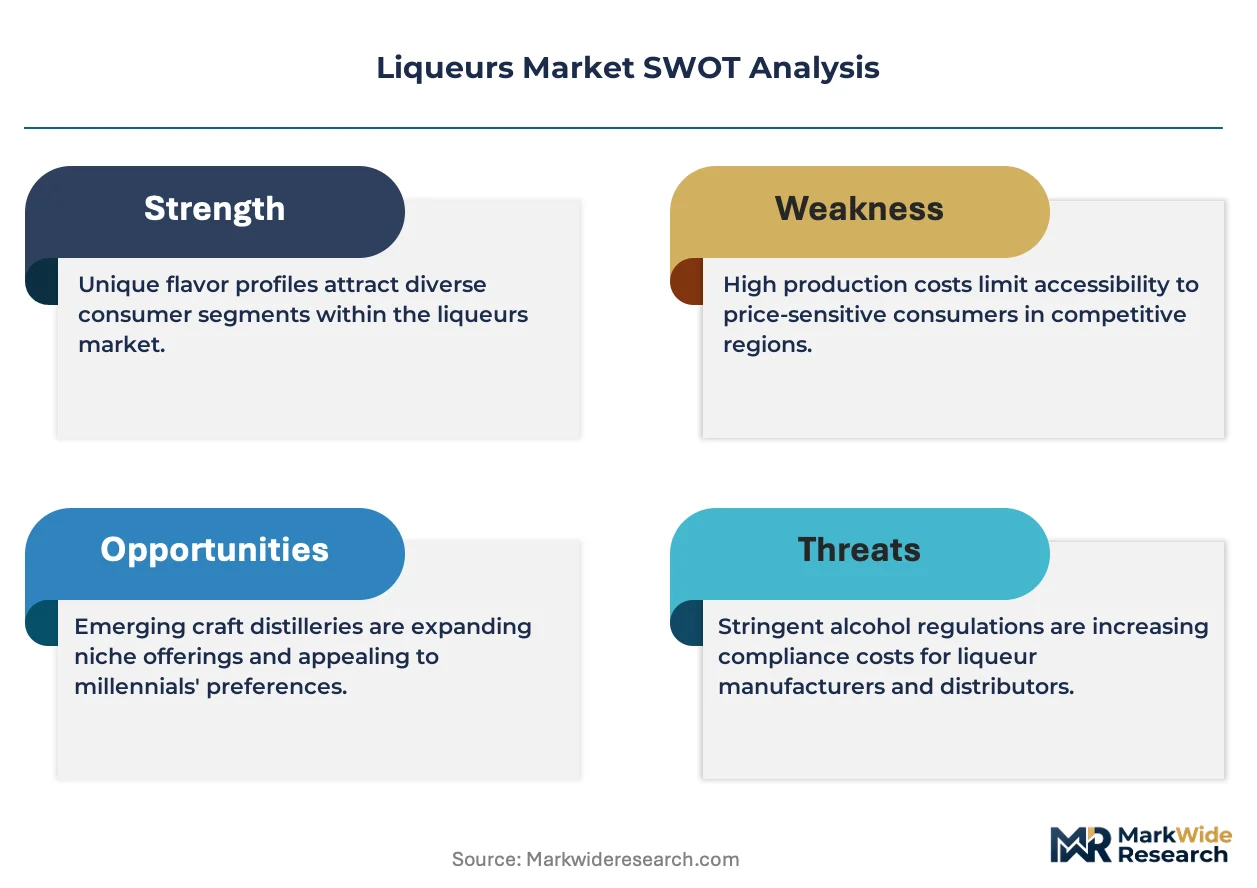
FDA labeling requirements and TTB certificate-of-label approvals govern US market entry, while EFSA additive regulations and EU Spirits Regulation define ingredient permissibility across European markets. These frameworks elevate compliance costs for new entrants but protect incumbent positions through accumulated regulatory expertise. Stakeholders must monitor evolving low-ABV tax classifications and sugar-content disclosure mandates that could reshape formulation strategies and portfolio architectures.
Market Dynamics
Premium cocktail culture is compressing traditional liqueur consumption windows while simultaneously expanding per-occasion spend, forcing producers to reposition heritage brands for mixology-forward occasions without alienating established digestif rituals.
Growth Catalysts
- EU Spirits Regulation harmonization:Standardized origin labeling across member states reduces cross-border friction for heritage brands seeking shelf space in German, Italian, and French retail channels.
- Botanical traceability protocols:Mediterranean agricultural partnerships now document herb provenance from field to bottle, satisfying EFSA additive disclosure requirements while commanding retail price premiums.
- On-premise mixology expansion:Premium cocktail bars in London, New York, and Tokyo are constructing dedicated liqueur programs that rotate seasonal amaro and fruit expressions.
Market Restraints
- Vanilla supply concentration:Madagascar and Indonesian vanilla bean harvest volatility directly destabilizes production costs for cream liqueur emulsion formulations.
- TTB certificate-of-label backlog:FDA labeling requirement complexity extends US market entry timelines by 8-14 months for European heritage producers unfamiliar with TTB format specifications.
- Low-ABV wine and spritz substitution:Aperol-style bitter aperitifs and canned wine spritzers capture casual social occasions previously served by orange and coffee liqueurs.
Strategic Opportunities
- Indian duty-free channel expansion:Mumbai and Delhi airport retail operators are allocating premium spirits floor space to European herbal liqueurs targeting returning diaspora and business travelers.
- Carbon-neutral distillation mandates:EU Green Deal compliance incentives reward producers retrofitting copper pot stills with biomass or geothermal energy systems.
- Non-alcoholic liqueur analogues:Distillate-free botanical concentrates using glycerin and natural flavor extraction are penetrating sober-curious hospitality programs in Copenhagen and Melbourne.
Industry Challenges
- Master blender succession gaps:Retirement waves among European distilleries with proprietary maceration protocols threaten consistency in herbal bitter formulations.
- Multi-jurisdiction sugar disclosure:Divergent FDA added-sugar labeling, EU nutritional declaration requirements, and emerging market front-of-pack warning systems force parallel packaging SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liqueurs Market |
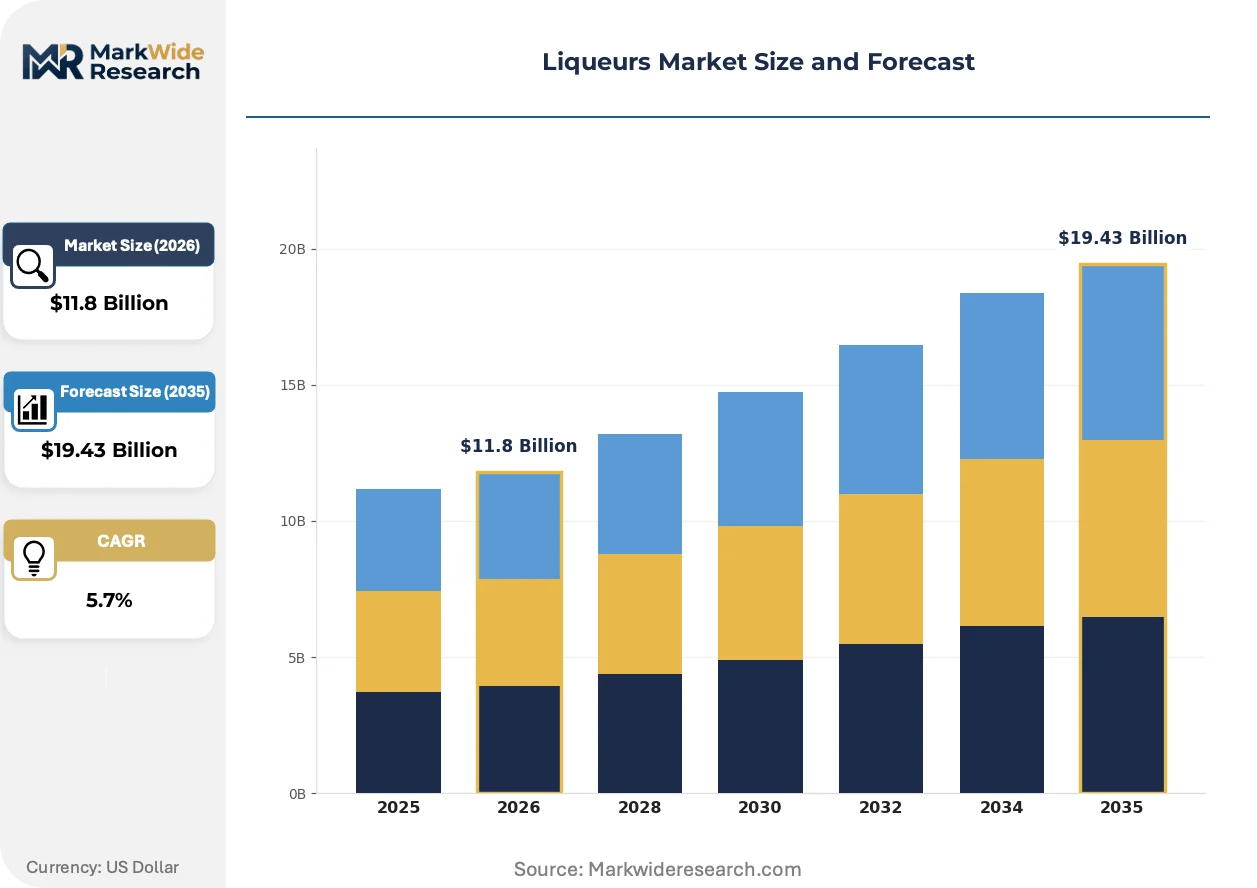
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.43 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Liqueurs, Cream Liqueurs, Herbal Liqueurs, Coffee Liqueurs Alcohol Content: Low ABV, Medium ABV, High ABV, Ultra High ABV Flavor Profile: Sweet, Bitter, Spicy, Citrus Packaging Type: Glass Bottles, Plastic Bottles, Tetra Packs, Cans |
| Companies Covered | Diageo, Pernod Ricard, Bacardi, Campari Group, Brown-Forman, Rémy Cointreau, Beam Suntory, Constellation Brands, Lucas Bols, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liqueurs Market Strategic Shifts
Rotary vacuum distillation and ultrasonic extraction are compressing traditional maceration timelines while preserving volatile aromatic compounds, enabling seasonal limited releases that previously required year-long production cycles.
Rotary vacuum distillation operates at reduced temperatures to extract delicate floral and citrus notes without thermal degradation. Craft producers in Provence and Piedmont are adopting this equipment to release small-batch elderflower and bergamot expressions within weeks of harvest. The technology is rewriting the seasonal release calendar, collapsing the gap between raw material availability and bottled product.
EFSA additive regulations are tightening permissible colorant and sweetener categories across EU member states, forcing reformulation of legacy cream liqueurs reliant on artificial stabilizers. Manufacturers are migrating toward carrageenan and lecithin emulsion systems. German and Irish producers face the steepest compliance curves given their established cream liqueur export volumes.
Direct-to-trade sampling programs are displacing traditional distributor-led education for on-premise accounts. Brand ambassadors now curate bespoke tasting flights for individual bar programs rather than regional wholesale events. This pattern is most visible in London's Soho and Shoreditch districts, where independent mixology venues negotiate exclusive cask selections and collaborative limited editions.
Liqueurs Market Segmentation
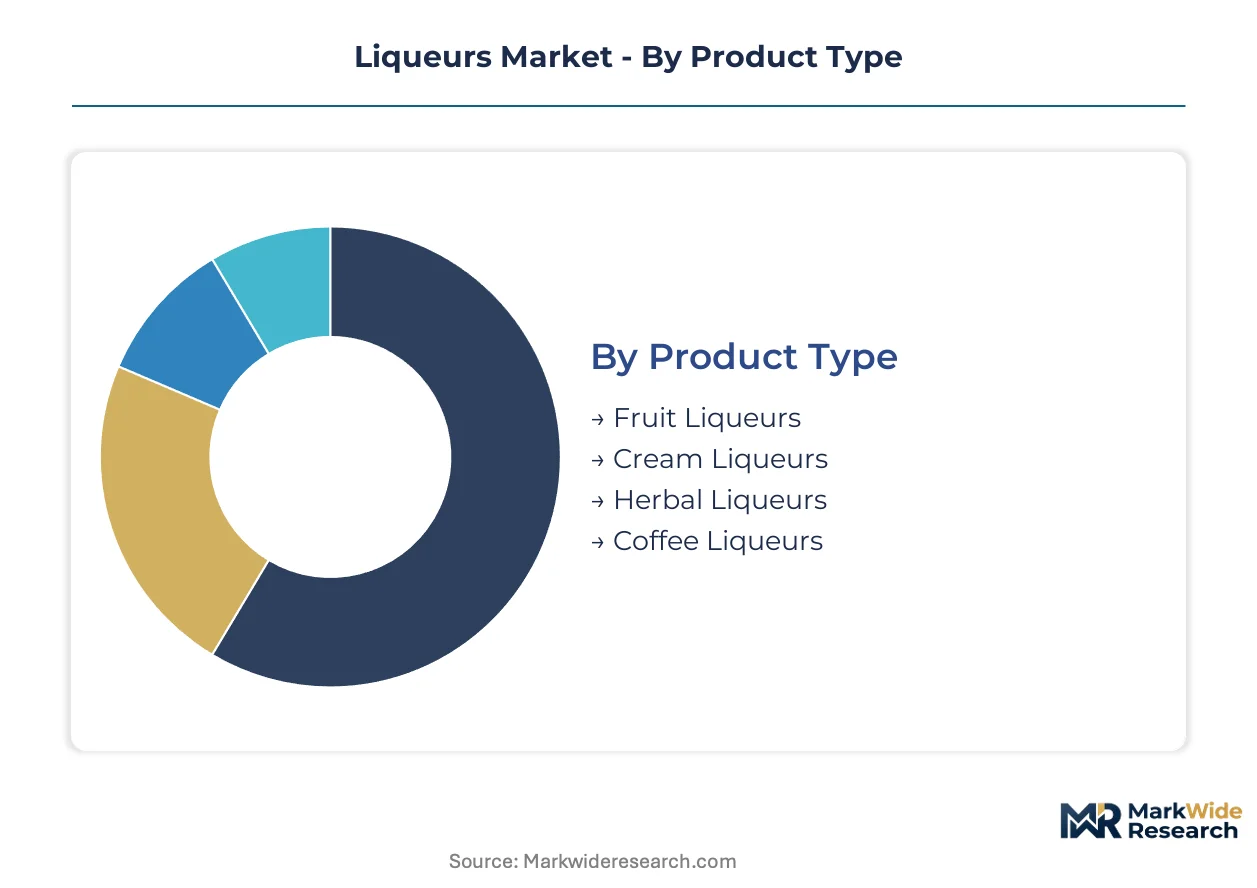
Liqueur producers calibrate formulation, positioning, and channel strategy against four intersecting dimensions. Product type determines margin structure and production complexity. Alcohol content governs tax classification and occasion targeting. Flavor profile shapes mixology compatibility. Packaging type dictates shelf-life economics and on-premise presentation.
Product Type:
Production technology separates commodity modifiers from proprietary emulsion systems and heritage maceration protocols.
- Fruit Liqueurs:Macerated or compounded fruit infusions at 15-30% ABV deliver consistent flavor delivery for cocktail programs. Demand concentrates in German and Italian retail channels where orange and berry expressions anchor home bar repertoires, though margin compression from private-label alternatives limits premium pricing headroom.
- Cream Liqueurs:Proprietary emulsion technologies stabilize dairy-fat suspensions in alcohol matrices, creating shelf-stable formulations with 12-18 month viability. Irish and German producers command price premiums through in-house production of carrageenan and lecithin stabilizer systems, insulating against EFSA additive regulation volatility.
- Herbal Liqueurs:Bitter botanical macerations rooted in Mediterranean drinking rituals.
- Coffee Liqueurs:Roasted bean extraction products targeting dessert and cocktail applications.
Mature deployment sits with Herbal Liqueurs. Newer deployment is concentrated in Cream Liqueurs.
Alcohol Content:
Tax brackets and occasion targeting split formulation strategies across ABV tiers.
- Low ABV:Products at 15-20% ABV occupy spritz and long-drink occasions. German consumers drive volume through traditional half-bitter aperitifs, though Aperol-style substitutes erode share in casual social settings.
- Medium ABV:The 21-30% ABV band dominates standard liqueur consumption.
- High ABV:Concentrated expressions at 31-40% ABV serve digestif and cocktail-modifier functions.
- Ultra High ABV:Limited-production spirits above 40% ABV target collector and craft cocktail segments.
Volume concentrates in Medium ABV. Premium expansion is climbing the fastest in Low ABV.
Flavor Profile:
Palate segmentation maps directly to mixology program construction and seasonal rotation calendars.
- Sweet:Vanilla, caramel, and chocolate-dominant profiles serve dessert accompaniment and entry-level cocktail occasions. German cream liqueur consumption anchors this segment, though sugar-content disclosure mandates across EU member states force reformulation toward reduced-calorie variants.
- Bitter:Gentian, wormwood, and citrus-peel bitterness defines amaro and digestif categories. Italian and German on-premise accounts rotate seasonal bitter expressions, with London cocktail bars constructing dedicated bitter liqueur flights.
- Spicy:Cinnamon, clove, and pepper-forward profiles target winter seasonal releases.
- Citrus:Orange, lemon, and bergamot expressions leverage Corsican and Caribbean peel sourcing.
Bitter profiles dominate on-premise mixology deployment. Sweet profiles retain the largest retail footprint.
Packaging Type:
Material selection balances presentation requirements, logistics economics, and sustainability positioning.
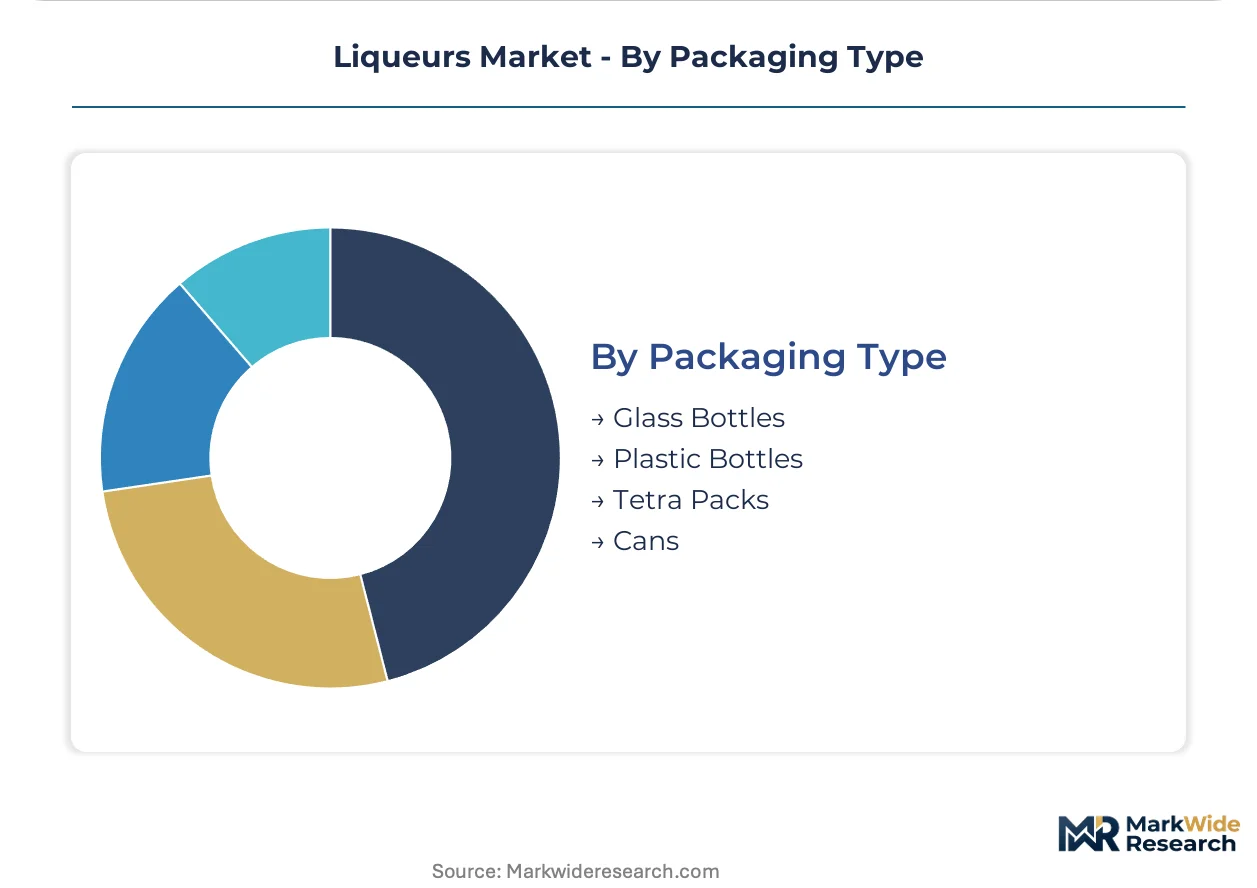
- Glass Bottles:Premium positioning and UV protection for light-sensitive botanical formulations. German and Irish heritage brands maintain embossed and screen-printed glass as standard, with weight reduction initiatives responding to EU Green Deal carbon accounting requirements.
- Plastic Bottles:Polyethylene terephthalate formats reduce shipping weight for value-tier retail.
- Tetra Packs:Aseptic cartons for ready-to-serve cocktail bases and cream liqueur minis.
- Cans:Single-serve formats for outdoor and festival occasions.
Glass dominates heritage brand portfolios. Cans represent the steepest expansion trajectory in outdoor consumption channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heritage consumption patterns concentrate liqueur demand in mature European markets, while craft distilling and premium cocktail culture are expanding the addressable base in North American and Asian metropolitan centers. Regulatory harmonization across the EU Spirits Regulation framework is reducing cross-border friction for established producers. Emerging duty-free channels in India and Southeast Asia are creating new volume outlets for premium European brands.
Germany
Traditional herbal liqueur consumption remains culturally embedded in Bavarian and Rhineland drinking rituals, with Jägermeister and Underberg maintaining household penetration across generations. EFSA additive regulations and EU Spirits Regulation labeling directives govern origin and ingredient disclosure requirements for all domestic producers. Berlin's craft distilling cluster in Neukölln and Kreuzberg is generating small-batch amaro and fruit liqueur expressions targeting cocktail bar programs.
United States
Premium cocktail bars in New York, Los Angeles, and Chicago are constructing dedicated liqueur programs that rotate seasonal amaro and bitter expressions. FDA labeling requirements and TTB certificate-of-label approvals extend market entry timelines for European heritage brands unfamiliar with format specifications. Kentucky's bourbon heritage corridor is diversifying into coffee and cream liqueur production using existing distillation infrastructure.
Italy
Amaro and digestif traditions anchor domestic consumption in Milan, Turin, and Rome, with Campari and Aperol serving as aperitivo category staples. EU Spirits Regulation harmonization standardizes origin labeling across member states, protecting geographic indications for bitter liqueurs from Piedmont and Lombardy. The Franciacorta wine region is expanding into fruit liqueur production using surplus grape must and local botanicals.
France
Corsican and Caribbean orange peel cultivation supports Rémy Cointreau's controlled supply chain for triple-sec formulations. EFSA additive regulations are tightening permissible colorant categories, forcing reformulation of legacy cream liqueurs reliant on artificial stabilizers. The Provence-Alpes-Côte d'Azur region is adopting rotary vacuum distillation equipment for small-batch elderflower and bergamot seasonal releases.
India
Mumbai and Delhi airport retail operators are allocating premium spirits floor space to European herbal liqueurs targeting returning diaspora and business travelers. FSSAI labeling requirements and state-level excise variations create complex compliance landscapes for imported spirits. Bangalore's emerging craft beverage scene is experimenting with indigenous spice and botanical liqueurs using cardamom, saffron, and sandalwood.
Liqueurs Market Competitive Environment
Portfolio diversification dominates the current landscape as heritage houses reposition legacy brands for mixology-forward occasions without alienating established digestif rituals. The market structure consolidates around multinational spirits conglomerates with accumulated regulatory expertise and captive botanical supply chains. Three strategic archetypes prevail: vertically integrated majors controlling vanilla and citrus cultivation, Mediterranean partnership-based herb sourcers, and craft distillers leveraging rotary vacuum distillation for seasonal releases. M&A activity and direct-to-trade sampling programs represent the dominant competitive vectors.
Within the vertically integrated tier, Diageo and Pernod Ricard exemplify contrasting supply chain philosophies. Diageo leverages backward integration into vanilla and citrus supply chains to secure consistent flavor profiles across its liqueur portfolio. Pernod Ricard anchors anise and herb sourcing through long-term agricultural partnerships in the Mediterranean basin. Rémy Cointreau occupies a specialist position through controlled orange peel cultivation in Caribbean and Corsican orchards, differentiating its triple-sec expressions through geographic provenance control.
| Leading Market Players |
|---|
| Diageo |
| Pernod Ricard |
| Bacardi |
| Campari Group |
| Brown-Forman |
| Rémy Cointreau |
| Beam Suntory |
| Constellation Brands |
| Lucas Bols |
| Others |
Value Chain & Pricing Dynamics
Master blender expertise concentrated in Bavaria and the Rhineland widens labor-cost differentials between heritage German producers and new market entrants, compressing margin spreads at the economy tier while amplifying premium capture for houses with proprietary maceration protocols.
Pricing Analysis
Service bundling separates heritage houses from commodity competitors, with technical education and mixology training included for on-premise accounts versus unbundled transactional pricing for retail. Three-tier pricing structure across premium, standard, and economy levels stratifies by botanical traceability certification and vintage-dated releases. Price differentiation hinges on controlled-origin citrus peel and captive vanilla cultivation. Cost compression in cream liqueur emulsions is intensifying because EFSA additive regulations force carrageenan system migrations. Value-tier buyers exhibit highest price sensitivity; collector-edition purchasers show minimal elasticity.
Supply Chain Analysis
Return flows for spent botanical matter and copper still refurbishment create circular material loops, particularly in German and Irish distilling corridors. Madagascar, Indonesia, and Tahiti anchor vanilla bean supply for cream liqueur formulations. Orange peel sourcing draws from Corsican and Caribbean orchards controlled by major houses. Herb procurement rests on Mediterranean agricultural partnerships spanning Provence, Piedmont, and Andalusia. Single-source vulnerability in Madagascar vanilla harvests threatens cost stability. Distribution runs through bonded warehouse networks and duty-free channel operators in Mumbai and Delhi airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA additive regulations and EU Spirits Regulation harmonization are accelerating consolidation by elevating compliance burdens that marginalize craft distillers lacking regulatory expertise or captive supply chains.
For Market Incumbents: Deploy botanical traceability certification as a defensive moat, investing in field-to-bottle documentation systems that satisfy EFSA disclosure requirements while commanding retail premiums. Deepen backward integration into citrus and vanilla cultivation to insulate against Madagascar harvest volatility and Indonesian supply disruptions. Control on-premise channel access through direct-to-trade sampling programs that displace distributor-led education in London and New York cocktail bars. For New Entrants and Emerging Players: EU Green Deal carbon-neutral distillation incentives in Germany open a window for biomass and geothermal retrofits that qualify for compliance rewards unavailable to legacy copper pot still operators. Target Bangalore's emerging craft beverage scene with indigenous spice liqueurs using cardamom and saffron that bypass European supply chain bottlenecks. Pursue collaborative limited editions with independent mixology venues in Copenhagen and Melbourne as the primary go-to-market pathway. For Investors and Strategic Acquirers: Re-rating potential sits with Mediterranean partnership-based herb sourcers given EFSA additive regulation tightening that privileges established agricultural documentation systems. Five-to-ten year viability favors houses with rotary vacuum distillation capabilities enabling compressed seasonal release calendars. Watch for master blender succession announcements at Bavarian and Rhineland distilleries as the critical inflection signal for consistency risk in proprietary bitter formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Traceability Certification | EFSA additive disclosure compliance secures shelf access across German and Italian retail channels. |
| Rotary Vacuum Distillation Adoption | Provence and Piedmont craft producers compress elderflower release timelines from harvest to bottle. |
| Carbon-Neutral Still Retrofit | EU Green Deal biomass and geothermal incentives reward German distilleries with compliance credits. |
| Direct-to-Trade Sampling Program | London Soho and Shoreditch bars negotiate exclusive cask selections bypassing wholesale distributors. |
| Indigenous Spice Liqueur Development | Bangalore craft producers differentiate through cardamom and sandalwood formulations for domestic palates. |
Study Parameters
Independent corroboration across master blenders at Bavarian and Rhineland distilleries, procurement leads at Mediterranean herb cooperatives, and regulatory affairs specialists at EFSA member state agencies underwrites the qualitative findings. Primary interviews with on-premise program directors at London and New York cocktail bars, category buyers at German and Italian retail chains, and brand ambassadors for heritage houses combined with secondary validation from EU Spirits Regulation filings, EFSA additive guidance documents, and customs trade data for vanilla and citrus peel imports. Bottom-up volume triangulation against top-down value estimates tested segmentation assumptions across product type, alcohol content tier, and flavor profile dimensions.
Rate-of-change decomposition separated volume drivers from price-mix effects across the analysis window. The forecast framework modeled product type segmentation by production technology complexity, alcohol content tier by tax classification and occasion targeting, flavor profile by mixology program compatibility, and packaging type by shelf-life economics and sustainability positioning. CAGRs were derived from trend extrapolation moderated by regulatory inflection points and supply chain concentration risks. Rotary vacuum distillation adoption curves and EFSA reformulation timelines served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for ultrasonic extraction and non-alcoholic glycerin-based analogues would alter the outlook for traditional maceration demand. Forecasts reflect assumptions regarding EU Spirits Regulation enforcement consistency, Madagascar vanilla harvest stability, and master blender succession pipeline depth. Material deviation in EFSA additive category restrictions, TTB certificate-of-label approval timelines, or carbon-neutral distillation mandate acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
Cigar Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Wine Filling Machine Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Europe Alcohol E-Commerce Market
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
Ready to Serve Cocktails Market
Alcoholic Beverages
Global Beer Market
Alcoholic Beverages
Home Brew Boiler Market
Alcoholic Beverages
Whey Based Vodka Market
Alcoholic Beverages
Distillers Malt Market
Alcoholic Beverages
Cabernet Sauvignon Market
Alcoholic Beverages
Vodka Market
Alcoholic Beverages
Home Beer Brewing Machine Market
Alcoholic Beverages
Puncheon Barrel Market