
 Rice Wine Market | 2026-2036
Rice Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Wine Market Analysis
Japan's liquor tax reclassification is pivoting small-scale rice wine producers toward premium positioning to offset higher per-liter duties. Ozeki Sake Co., Ltd. leverages vertical integration from rice cultivation to bottling to protect margin structures. Kuaijishan Shaoxing Rice Wine Company anchors its competitive stance through geographic dominance in eastern China's heritage production zone. Takara Holdings Inc. differentiates via diversified fermentation technology spanning multiple Asian rice wine traditions.
Rice wine denotes an alcoholic beverage produced through saccharification of starches in polished rice grains by koji mold (Aspergillus oryzae), followed by parallel fermentation yielding 14–20% alcohol by volume, with flavor profiles spanning dry to sweet depending on rice polishing ratio and yeast strain. Premium Rice Wine commands the dominant value share as consumers trade upward toward junmai daiginjo and aged Shaoxing classifications with documented provenance. Sparkling Rice Wine represents the fastest-expanding product type, driven by younger demographics in urban consumption clusters seeking lower-alcohol, effervescent formats. Specialty Liquor Stores retain the highest margin capture among distribution channels due to staff-guided purchasing and temperature-controlled storage infrastructure.
Japan's National Tax Agency governs sake labeling standards and geographic indication protections, while China's SAMR enforces food safety codes for fermented cereal beverages under GB national standards. The EU's F-Gas Regulation and REACH framework affect imported rice wine packaging materials and cold-chain logistics compliance for European distribution. Stakeholders must monitor evolving alcohol duty structures and carbon-footprint disclosure requirements as these frameworks increasingly determine market access eligibility and retail shelf placement economics.
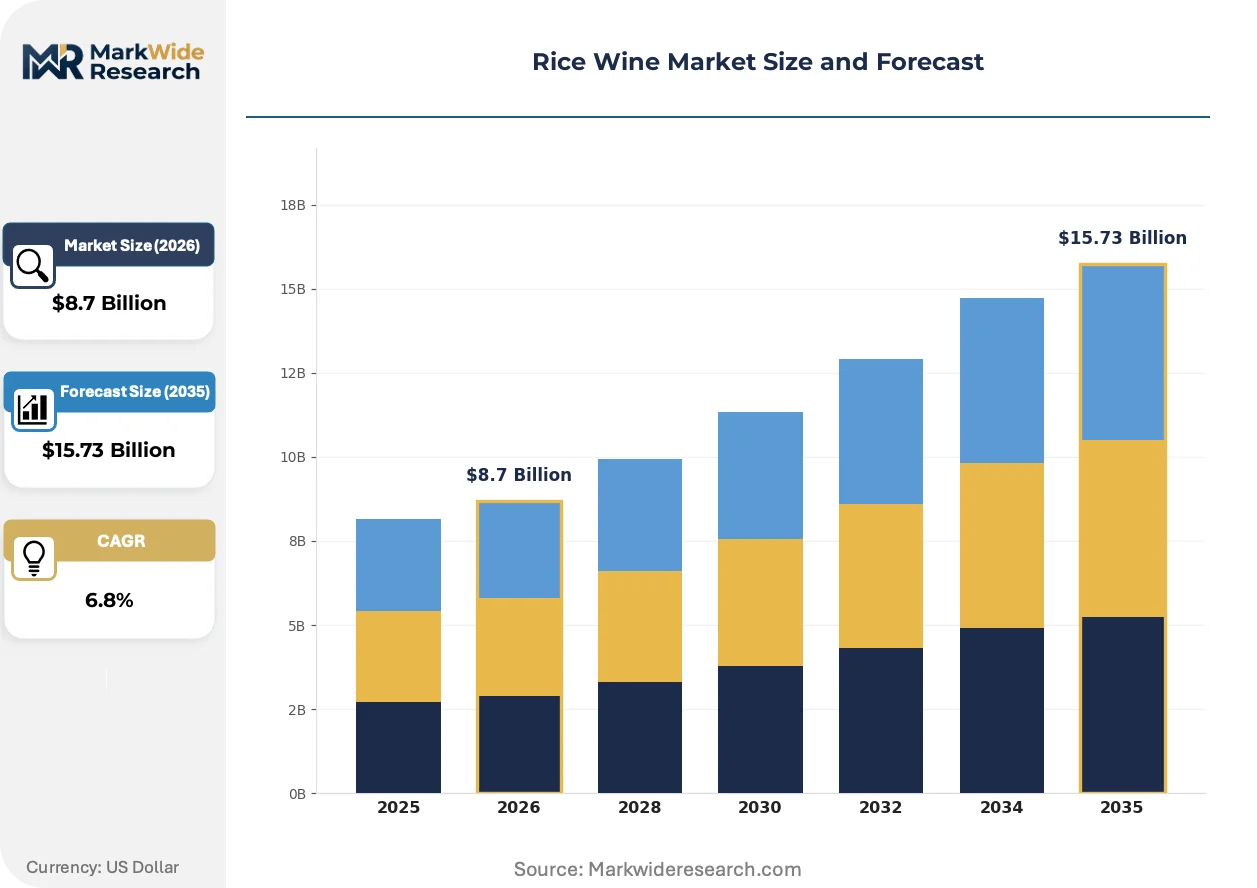
Market Dynamics
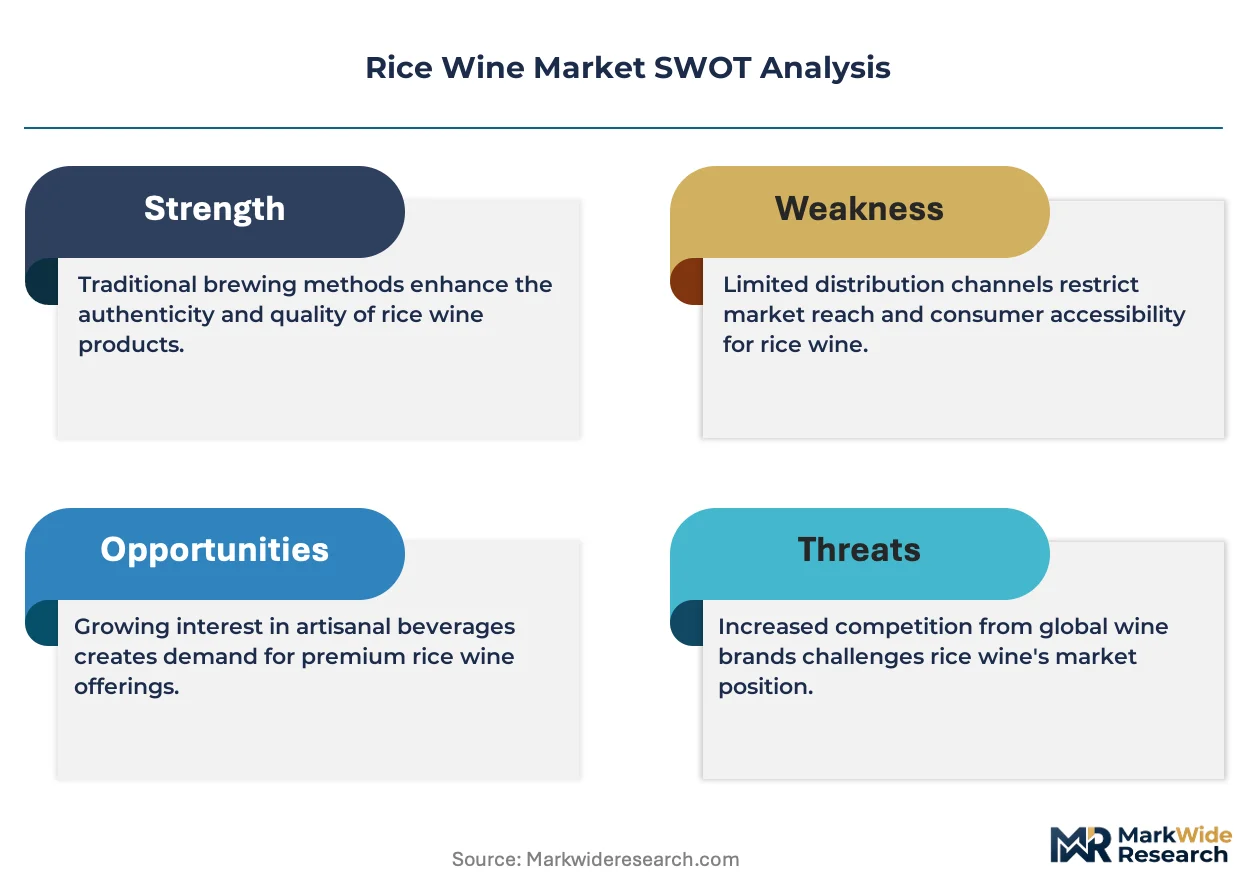
Japan's liquor tax reclassification is compressing margins for small-scale brewers while simultaneously accelerating premiumization across the fermented rice beverage category. Brewers are responding by restructuring product portfolios toward higher-margin classifications to absorb elevated per-liter duties.
Growth Catalysts
- Heritage Production Zoning:Geographic indication protections in Zhejiang province concentrate premium Shaoxing-style output, creating scarcity-driven pricing power for aged classifications.
- Sparkling Format Innovation:Lower-alcohol effervescent rice wines attract urban millennial and Gen-Z cohorts seeking sessionable alternatives to traditional still expressions.
- Restaurant Channel Expansion:East Asian tasting-menu establishments are integrating structured rice wine pairings, elevating category visibility beyond ethnic cuisine contexts.
Market Restraints
- Input Cost Volatility:Polished rice grain prices fluctuate with climate-induced harvest variability, compressing margin predictability for koji-based fermentation operations.
- Supply Concentration Risk:Premium koji mold strains and specialized yeast cultures depend on concentrated domestic suppliers in Japan and China, creating single-source vulnerability.
- Substitution Threat:Craft beer and low-intervention natural wines capture similar occasion-based consumption moments among younger demographics in metropolitan clusters.
Strategic Opportunities
- Underpenetrated Western Markets:Specialty liquor stores in North America and Western Europe lack staff-trained rice wine merchandising, representing white-space distribution expansion.
- Technology Convergence:Precision fermentation analytics combined with traditional koji propagation methods enable consistent quality scaling without heritage craft dilution.
- EU Cold-Chain Infrastructure:The F-Gas Regulation's phase-down of hydrofluorocarbon refrigerants creates openings for compliant temperature-controlled logistics providers serving premium import channels.
Industry Challenges
- Master Brewer Talent Scarcity:Traditional toji certification pathways require decade-long apprenticeships, constraining production capacity expansion for heritage-method producers.
- Compliance Timeline Compression:China's SAMR enforcement of updated GB national standards for fermented cereal beverages demands reformulation and relabeling investments with compressed implementation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rice Wine Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Premium Rice Wine, Sparkling Rice Wine, Unfiltered Rice Wine, Flavored Rice Wine Distribution Channel: Online Retail, Specialty Liquor Stores, Supermarkets, Bars End User: Households, Restaurants, Caterers, Importers Packaging Type: Bottles, Casks, Tetra Packs, Kegs |
| Companies Covered | Ozeki Sake Co., Ltd., Kuaijishan Shaoxing Rice Wine Company, Takara Holdings Inc., Kikkoman Corporation, Zhejiang Guyuelongshan Shaoxing Wine Co., Ltd., Asahishuzo Co., Ltd., Hakutsuru Sake Brewing Co., Ltd., Hakkaisan Brewery, Gekkeikan Sake Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Wine Market Emerging Trajectories
Active fermentation science and consumption occasion engineering are reshaping competitive positioning across the rice wine category. Producers are deploying biotechnology and format innovation to capture shifting demographic preferences.
Controlled-temperature koji propagation systems are expanding into commercial-scale operations previously dependent on seasonal ambient conditions. Medium-capacity breweries in Japan's Niigata and Hyogo prefectures are adopting these systems to stabilize output consistency year-round. The technology is expanding into premium junmai daiginjo production, compressing quality variance that previously differentiated small-batch from industrial-scale offerings.
The EU's F-Gas Regulation is mandating refrigerant transitions across cold-chain logistics serving temperature-sensitive rice wine imports. Packaging material suppliers must reformulate seals and closures to meet REACH chemical compliance thresholds. European specialty retailers are responding by consolidating sourcing through compliant logistics providers, filtering non-compliant producers from shelf access.
Urban consumption clusters are fragmenting purchase occasions across multiple channels rather than consolidating through traditional hospitality venues. Younger buyers in Shanghai, Tokyo, and Seoul are acquiring single-serve formats through convenience retail and direct-to-subscription models, displacing restaurant-centric discovery patterns. This behavioral rotation is most visible in sparkling rice wine uptake, where trial-sized packaging dominates e-commerce velocity metrics.
Rice Wine Market Segmentation
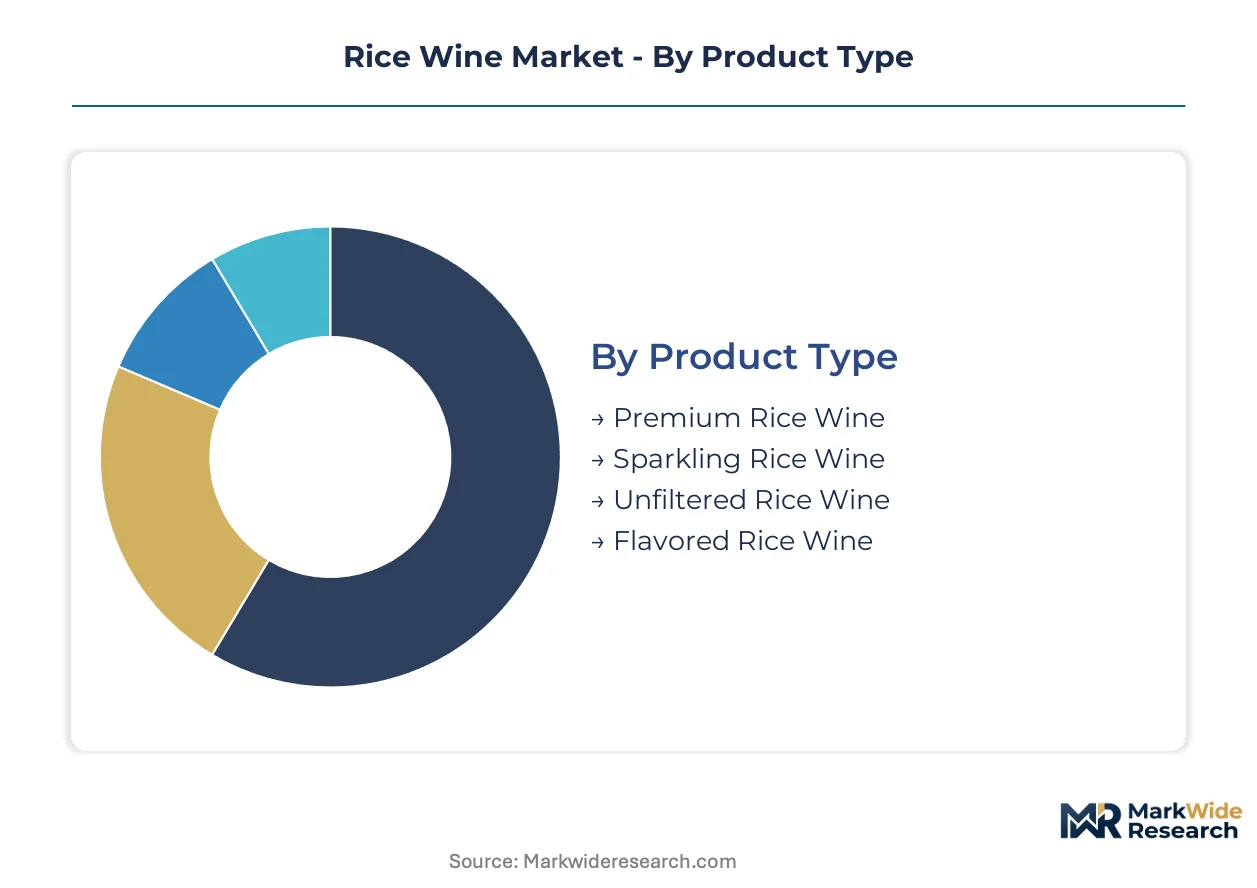
Rice wine segmentation reflects divergent consumption occasions and margin architectures across product formats and channel structures. Producers must calibrate portfolio depth against the operational requirements of each segment, from temperature-controlled logistics for premium expressions to high-velocity packaging for convenience retail.
Product Type:
Premium expressions operate as standalone category anchors with dedicated production protocols, while flavored and sparkling variants embed within broader beverage portfolios as occasion-extenders.
- Premium Rice Wine:Junmai daiginjo and aged Shaoxing classifications with documented rice polishing ratios and geographic indication status command the dominant value share. Demand concentrates in Zhejiang province heritage zones and Tokyo-Osaka metropolitan corridors, where documented provenance justifies scarcity-driven pricing tiers.
- Sparkling Rice Wine:Secondary fermentation in bottle or tank yields 5–8% ABV effervescent formats with lower residual sugar than traditional expressions. Urban millennial cohorts in Shanghai, Seoul, and Singapore drive uptake through convenience retail and direct-to-consumer subscription channels, displacing restaurant-centric discovery patterns.
- Unfiltered Rice Wine:Nigori-style cloudy expressions retain rice solids for creamy mouthfeel and elevated amino acid content.
- Flavored Rice Wine:Yuzu, plum, and lychee infusions target casual consumption occasions outside traditional pairing contexts.
Premium Rice Wine leads volumes today; Sparkling Rice Wine is gaining share fastest.
Distribution Channel:
Channel economics stratify sharply between staff-guided discovery environments and self-service velocity formats, with margin capture inversely correlated to throughput speed.
- Specialty Liquor Stores:Temperature-controlled storage infrastructure and trained sommelier staff support premium junmai daiginjo and aged Shaoxing merchandising. North American and Western European markets show underpenetrated white-space expansion potential where knowledgeable guidance remains scarce.
- Online Retail:Direct-to-subscription models and single-serve trial formats dominate e-commerce velocity metrics for sparkling and flavored variants. Japan's National Tax Agency labeling standards and China's SAMR cross-border e-commerce rules create compliance complexity for international fulfillment.
- Supermarkets:Mass-market junmai and cooking-grade Shaoxing compete on shelf placement and promotional frequency.
- Bars:On-premise cocktail programs integrate rice wine as base spirit for craft mixology applications.
Specialty Liquor Stores capture the highest margins per liter; Online Retail shows the steepest expansion trajectory.
End User:
Volume concentration differs from value concentration across household, foodservice, and trade intermediary segments with distinct procurement rhythms.
- Restaurants:East Asian tasting-menu establishments in Kyoto, Seoul, and Taipei are expanding structured rice wine pairings beyond ethnic cuisine contexts. Staff training investments and inventory holding costs limit penetration to mid-to-upper tier operations.
- Households:Home consumption spans ceremonial gift-giving, cooking applications, and casual drinking occasions with highly variable price elasticity across demographics.
- Caterers:Event-based procurement favors volume formats and consistent supply security over provenance documentation.
- Importers:EU F-Gas Regulation compliance and REACH packaging standards filter non-compliant producers from European shelf access, consolidating sourcing through certified logistics providers.
Restaurants lead value capture per occasion; Households dominate absolute volume throughput.
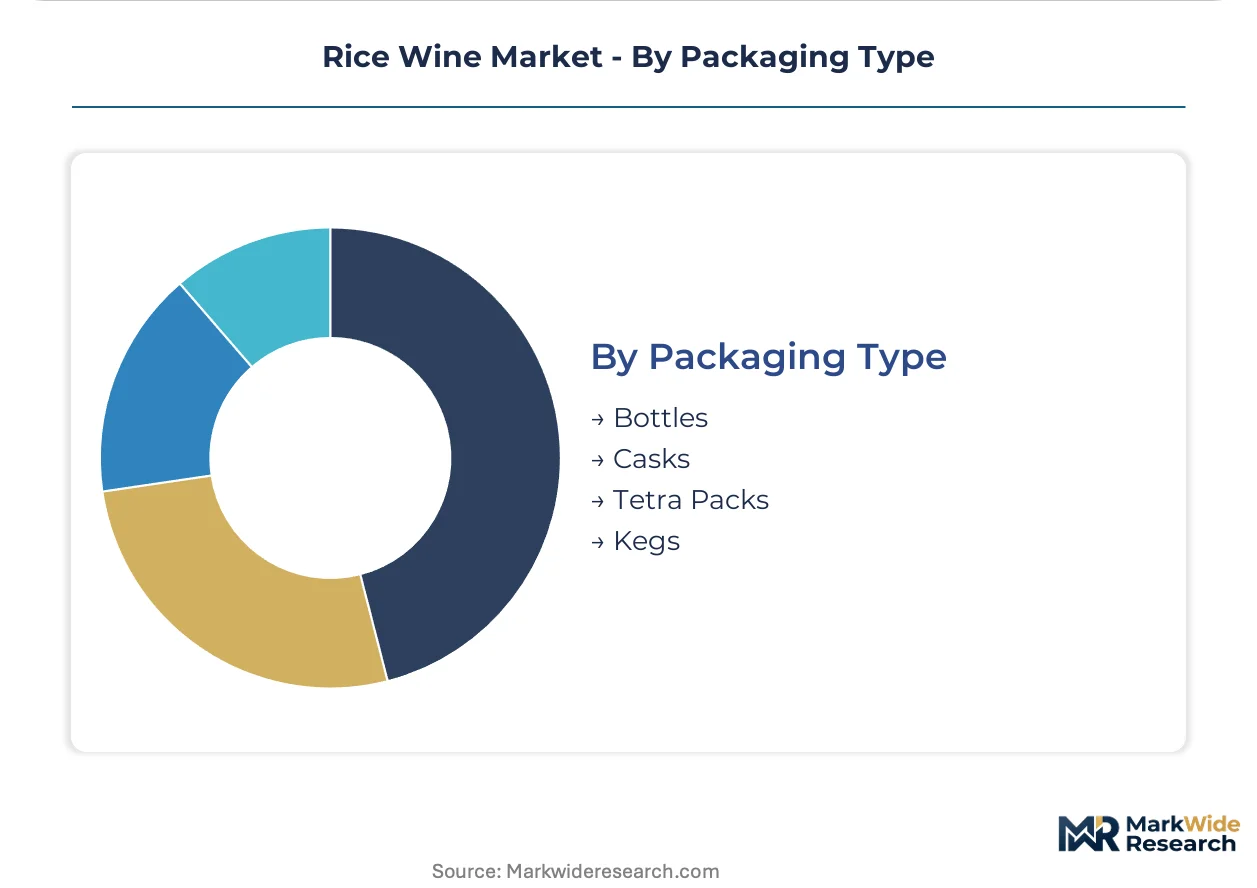
Packaging Type:
Format selection tracks consumption occasion fragmentation, with single-serve and large-format options diverging toward convenience retail versus on-premise dispensing systems.
- Bottles:Standard 720ml and 1.8L glass formats remain the reference standard for premium junmai daiginjo and aged Shaoxing expressions. REACH chemical compliance thresholds for seals and closures are reformulating supplier specifications for European export markets.
- Kegs:Stainless steel and disposable KeyKeg formats serve sparkling rice wine draft programs in Tokyo, Seoul, and Sydney bars. Cold-chain integrity requirements and cleaning protocol standardization limit adoption to established beverage distribution networks.
- Casks:Oak and ceramic vessels support extended aging programs for heritage-method producers.
- Tetra Packs:Aseptic carton formats target cooking-grade volume applications with minimal storage infrastructure.
Bottles command the dominant share; Kegs are climbing the fastest among format innovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rice wine production traces its commercial lineage to China's Shaoxing region and Japan's Kansai corridor, where koji-based fermentation methods scaled during the Tang and Edo periods respectively. These heritage zones remain the geographic anchors for premium classification systems and documented provenance protocols that govern contemporary trade.
China
Shaoxing-style heritage production in Zhejiang province concentrates aged rice wine output with documented geographic indication status. SAMR enforces updated GB national standards for fermented cereal beverages, demanding reformulation investments from legacy producers. The Yangtze River Delta cluster around Shaoxing city anchors scarcity-driven pricing for vintage classifications with certified provenance documentation.
Japan
Tokyo-Osaka metropolitan corridors drive junmai daiginjo consumption through restaurant channel expansion and ceremonial gift-giving occasions. The National Tax Agency governs sake labeling standards and geographic indication protections, with revised liquor tax frameworks compressing margins for small-scale brewers. Niigata and Hyogo prefectures concentrate controlled-temperature koji propagation adoption among medium-capacity breweries seeking year-round output consistency.
South Korea
Urban millennial cohorts in Seoul drive sparkling rice wine uptake through convenience retail and direct-to-subscription channels. MFDS regulates alcohol labeling and food safety codes for traditional fermented beverages, creating compliance thresholds for import positioning. The Seoul Capital Area serves as the primary consumption cluster for lower-alcohol effervescent formats displacing restaurant-centric discovery patterns.
United States
Specialty liquor stores in California and New York Metro represent underpenetrated white-space expansion for staff-guided premium rice wine merchandising. FDA and state-level alcohol beverage control boards govern import labeling and distribution licensing, with temperature-controlled logistics requirements filtering non-compliant producers. The Pacific Northwest and Greater Boston clusters show emerging draft program adoption for kegged sparkling formats in craft beverage bars.
Germany
Specialty retailers in Berlin and Munich consolidate sourcing through REACH-compliant logistics providers serving temperature-sensitive import channels. The EU F-Gas Regulation mandates refrigerant transitions across cold-chain infrastructure, with ECHA chemical compliance thresholds reformulating packaging seals and closures. Bavaria and North Rhine-Westphalia concentrate compliant distribution networks that filter non-compliant producers from shelf access.
Rice Wine Market Vendor Landscape
The competitive structure tilts toward heritage-method specialists with documented geographic indication protections and integrated supply chains. Small-scale brewers cluster around traditional certification pathways, while mid-cap operators adopt precision fermentation analytics to stabilize quality scaling. Three archetypes dominate: vertical integrators controlling rice cultivation through bottling, heritage-zone specialists leveraging geographic scarcity, and diversified fermentation technology platforms spanning multiple Asian traditions. Consolidation pressures favor backward integration into upstream rice supply and strategic partnerships with compliant European logistics providers.
Among Japanese heritage-method specialists, Ozeki Sake Co., Ltd. and Asahishuzo Co., Ltd. occupy positions exemplifying the vertical integrator archetype with captive supply chain control. Kuaijishan Shaoxing Rice Wine Company anchors the geographic concentration model through dominance in eastern China's heritage production zone. Takara Holdings Inc. represents the diversified fermentation platform approach, spanning multiple rice wine traditions through technology convergence rather than single-origin specialization.
| Leading Market Players |
|---|
| Ozeki Sake Co., Ltd. |
| Kuaijishan Shaoxing Rice Wine Company |
| Takara Holdings Inc. |
| Kikkoman Corporation |
| Zhejiang Guyuelongshan Shaoxing Wine Co., Ltd. |
| Asahishuzo Co., Ltd. |
| Hakutsuru Sake Brewing Co., Ltd. |
| Hakkaisan Brewery |
| Gekkeikan Sake Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive rice cultivation through bottling anchors supply positions for Ozeki Sake Co., Ltd. and Asahishuzo Co., Ltd., insulating margin structures against polished rice grain volatility while enabling scarcity-driven pricing tiers for junmai daiginjo expressions. This integration choice concentrates pricing power with heritage-zone specialists who control documented provenance from koji propagation to finished goods.
Pricing Analysis
Bundled temperature-controlled storage and staff-guided discovery commands premium capture at specialty liquor stores, while unbundled single-serve trial formats compete on velocity through convenience retail and direct-to-subscription channels. Three-tier pricing structure across premium junmai daiginjo, standard junmai, and economy cooking-grade expressions reflects rice polishing ratios and geographic indication status as primary differentiation drivers. Pricing pressure stems from Japan's liquor tax reclassification compressing margins for small-scale brewers. Household cooking applications show highest price sensitivity; ceremonial gift-giving occasions demonstrate lowest.
Supply Chain Analysis
Certification gating through Japan's National Tax Agency labeling standards and China's SAMR GB national standards filters non-compliant producers from premium channel access. Geographic supply concentrates in Japan, China's Zhejiang province, and South Korea's Seoul Capital Area. Raw material dependencies include polished rice grains, koji mold strains from Aspergillus oryzae cultures, and specialized yeast cultures. Single-source vulnerability around premium koji suppliers in Niigata and Hyogo prefectures creates structural risk. Distribution runs through specialty liquor stores with temperature-controlled infrastructure in premium tiers, shifting toward direct-to-consumer fulfillment for sparkling and flavored variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rice wine has entered a late-cycle quality phase where consumer trading toward junmai daiginjo and aged Shaoxing classifications with documented provenance rewards heritage-method specialists over volume-scale operators.
For Market Incumbents: To counter substitution pressure from craft beer and low-intervention natural wines, secure backward integration into upstream rice supply in Niigata and Zhejiang heritage zones while investing in controlled-temperature koji propagation systems that stabilize year-round output consistency without diluting craft credentials.
For New Entrants and Emerging Players: Begin with white-space expansion in North American and Western European specialty liquor stores where staff-trained rice wine merchandising remains scarce, targeting sparkling format innovation for urban millennial cohorts through convenience retail and subscription channels rather than competing for restaurant placement.
For Investors and Strategic Acquirers: Roll-up economics work for diversified fermentation technology platforms because fragmented heritage-method specialists lack capital to comply with EU F-Gas Regulation cold-chain mandates and REACH packaging standards independently. Five-to-ten year viability favors acquirers of mid-cap operators with captive koji propagation capabilities. Watch for inflection when Japan's National Tax Agency signals further tax framework revisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Zone Capacity Expansion | Controlled-temperature koji systems in Niigata stabilize junmai daiginjo quality variance year-round. |
| EU Compliance Certification | F-Gas Regulation and REACH alignment unlocks specialty retail shelf access in Berlin and Munich. |
| Sparkling Format Line Extension | 5-8% ABV effervescent variants capture Seoul and Shanghai millennial trial through convenience channels. |
| Direct-to-Subscription Launch | Single-serve packaging displaces restaurant-centric discovery for urban household consumption clusters. |
| Geographic Indication Protection | Zhejiang province scarcity documentation anchors scarcity-driven pricing for aged Shaoxing classifications. |
Methodological Framework
Multiple input streams — fermentation science literature, trade customs records, and regulatory filing databases — were reconciled against primary interviews with toji master brewers, specialty liquor store sommeliers, koji propagation equipment suppliers, and import compliance officers at EU logistics providers. Secondary validation drew from Japan's National Tax Agency labeling standards documentation, China's SAMR GB national standards, EU F-Gas Regulation implementation guidance, and trade flow data. Bottom-up production capacity modeling and top-down consumption clustering triangulated volume and value estimates.
Data-stream reconciliation across product type, distribution channel, end user, and packaging format dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory blending. Forecast inputs included rice polishing ratio adoption curves, sparkling format velocity metrics in convenience retail, and restaurant channel pairing expansion rates in East Asian metropolitan corridors.
Several conditions sit outside the modeled scope, including climate-induced harvest variability affecting polished rice grain input costs, abrupt regulatory shifts in alcohol duty structures, and technological disruption from precision fermentation analytics adoption timelines. Forecasts reflect documented assumptions about koji strain propagation stability and cold-chain infrastructure investment continuity. A model refresh is warranted upon material change in Japan's liquor tax framework or China's SAMR enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Ready to Drink Cocktails Market
Alcoholic Beverages
Asia Pacific Beer Market
Alcoholic Beverages
Home Beer Brewing Machine Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Craft Beer Market
Alcoholic Beverages
E-Commerce Liquor Market
Alcoholic Beverages
Brewers Spent Grain Market
Alcoholic Beverages
Decanter Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Pinot Meunier Market
Alcoholic Beverages
American Oak Barrels Market
Alcoholic Beverages
White Spirits Market
Alcoholic Beverages
Dark Spirits Market