
 Asia-Pacific Spirits Market | 2026-2036
Asia-Pacific Spirits Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Spirits Market Outlook
China's dual carbon goals are repositioning capital allocation across the Asia-Pacific spirits value chain. Kweichow Moutai Co., Ltd. leverages its Guizhou production base to sustain baijiu's cultural premium while modernizing energy-intensive fermentation. Diageo PLC anchors its regional footprint through Scotch and Chinese white spirit portfolios distributed across multiple price tiers. Suntory Holdings Limited differentiates via Japanese whisky craftsmanship that commands scarcity premiums in Tokyo, Seoul, and Singapore.
Asia-Pacific spirits encompass distilled alcoholic beverages typically exceeding twenty percent alcohol by volume, produced through fermentation followed by heat-driven separation and often barrel maturation for flavor development. These products serve ceremonial, social, and premium gifting functions across diverse cultural contexts. Whiskey and vodka occupy the largest volume positions, while gin captures accelerated growth as mixology culture expands in Bangkok, Sydney, and Shanghai bar scenes. Luxury price tier expressions concentrate margin pools, though mid-range packaging in glass bottles sustains the broadest household penetration across supermarket and liquor store channels.
China's SAMR enforces national food safety standards on distillate labeling and additive disclosure, while Japan's National Tax Agency governs whisky authenticity criteria that restrict geographic indication claims. India's FSSAI and state excise boards impose layered compliance burdens on imported spirit entry, shaping product registration timelines and tariff-influenced pricing. Stakeholders must monitor how evolving emissions enforcement and labeling harmonization across Chinese, Japanese, and Indian jurisdictions will reshape production location decisions and cross-border portfolio allocation.
Market Dynamics
China's dual carbon goals are forcing distillery operators across the Asia-Pacific region to reconfigure energy-intensive fermentation and aging infrastructure, redirecting capital toward emission retrofits and cleaner thermal systems.
Growth Catalysts
- Experiential hospitality formats:Premium cocktail bars in Shanghai, Tokyo, and Bangkok are driving demand for aged whiskey and craft gin expressions. Venues now curate spirit-forward menus that command sustained consumer outlay.
- SAMR labeling harmonization:China's national food safety standards on distillate disclosure are reducing cross-provincial trade friction. Producers benefit from unified compliance frameworks across provincial excise jurisdictions.
- Scarcity-driven Japanese whisky:Limited-release expressions from established distilleries are absorbing collector demand across Seoul, Singapore, and Hong Kong auction circuits.
Market Restraints
- Barley and grain input volatility:Climate stress on Australian and Canadian grain belts is compressing malt supply predictability for Scotch and Japanese whisky producers.
- Import tariff layering:India's FSSAI registration requirements combined with state excise board levies create protracted entry timelines for foreign spirit portfolios.
- Emissions retrofit capex:China's MEE enforcement of distillery emission standards is imposing capital burdens on aging facility operators without immediate revenue offset.
Strategic Opportunities
- Vietnam's underpenetrated premium tier:Ho Chi Minh City and Hanoi hospitality corridors show nascent demand for super-premium baijiu and aged whisky expressions.
- Direct-to-retailer digital channels:Licensed e-commerce platforms in China and South Korea are bypassing traditional distributor markups for verified buyers.
- Carbon-neutral certification alignment:Producers achieving ISO 14001-compliant distillery operations can access preferential placement in China's state procurement and gifting channels.
Industry Challenges
- Master blender talent scarcity:The specialized sensory expertise required for consistent aged spirit production is concentrating among a shrinking cohort of Japanese and Scottish-trained professionals.
- Cross-border formulation compliance:Divergent additive permissibility between China's GB standards and Japan's National Tax Agency whisky criteria forces portfolio fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Spirits Market |
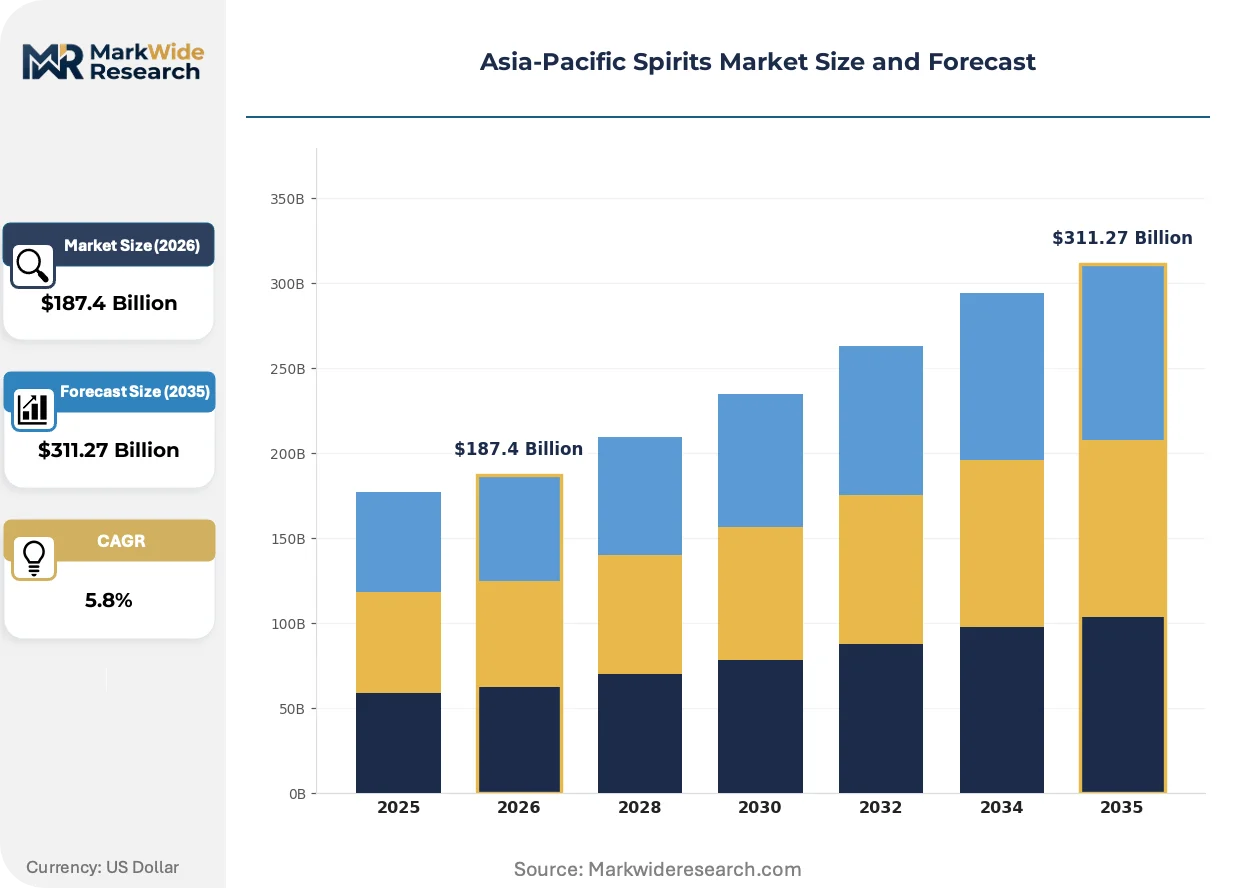
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whiskey, Vodka, Rum, Gin Packaging Type: Glass Bottles, Plastic Bottles, Tins, Kegs Price Tier: Premium, Mid-Range, Economy, Luxury Distribution Channel: Supermarkets, Online Retailers, Liquor Stores, Duty-Free Shops |
| Companies Covered | Kweichow Moutai Co., Ltd., Bacardi Limited, Diageo PLC, Asahi Group Holdings Ltd, Thai Beverage PLC, Pernod Ricard SA, Wuliangye Yibin Co., Ltd., LVMH Moët Hennessy Louis Vuitton, Suntory Holdings Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Spirits Market Strategic Shifts
Digital traceability systems and thermal efficiency retrofits are converging with shifting ceremonial consumption patterns to reshape how Asia-Pacific spirits are produced, authenticated, and consumed across tier-one urban corridors.
Electrified thermal systems for barrel warehousing are absorbing fossil fuel dependency in distillery operations. Suntory and domestic Chinese producers are piloting heat pump and solar thermal arrays for consistent aging climate control. This transition is compressing Scope 2 emissions profiles while requiring substantial electrical infrastructure upgrades at heritage production sites.
Japan's National Tax Agency tightened whisky authenticity criteria in 2021, restricting geographic indication claims to domestic distillation and aging. The regulation forced multinational portfolios to reclassify blended expressions and accelerated investment in Japanese domestic maturation capacity. Premium single malt releases now dominate Tokyo and Osaka duty-free channels as a direct response.
Corporate gifting protocols are shifting from volume-based baijiu transactions toward certified provenance and limited-edition releases. State-owned enterprise procurement officers in Beijing and Shenzhen now prioritize documented aging credentials and emission-compliant production over price-per-volume metrics. This rotation is visible in Kweichow Moutai's allocation strategies toward verified carbon-neutral distillery lines.
Asia-Pacific Spirits Market Segmentation
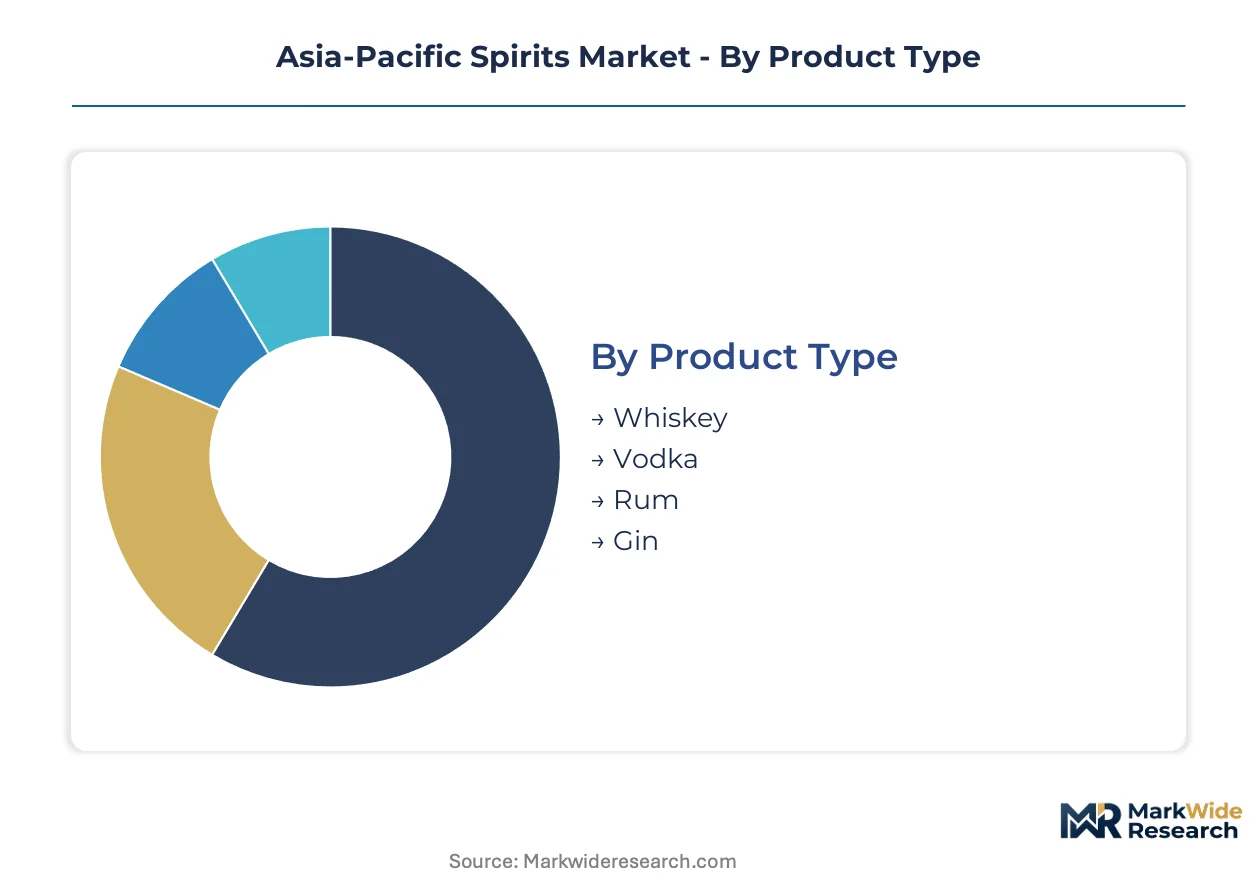
Segmentation in Asia-Pacific spirits reveals how ceremonial gifting, urban hospitality, and regulatory compliance fragment demand across distinct product specifications and channel configurations. Producers must calibrate portfolio breadth against the region's heterogeneous excise regimes and evolving carbon disclosure requirements.
Product Type:
Standardization dominates mass-market distillation, while aged expressions command customization through barrel programs and limited releases.
- Whiskey:Grain and malt distillates undergo extended oak maturation, with peated Scottish styles and Japanese single malts absorbing collector premiums. Demand concentrates in Tokyo, Seoul, and Singapore duty-free corridors where scarcity positioning drives sustained outlay.
- Vodka:Neutral spirit refined through multiple filtration stages serves as the base for flavored extensions and premium unflavored expressions. China's tier-one cities and India's metropolitan clusters sustain volume through cocktail-forward hospitality venues and celebratory consumption occasions.
- Rum:Molasses or sugarcane juice distillates range from white mixing grades to aged sipping expressions. Caribbean-origin bottlings face tariff layering across Indian state excise jurisdictions.
- Gin:Juniper-forward botanical spirits span London Dry and contemporary craft styles. Bangkok, Sydney, and Shanghai bar scenes are accelerating demand for small-batch expressions with regional botanical signatures.
Most installed capacity flows through Whiskey. Expansion is steepest in Gin.
Packaging Type:
Volume economics favor commodity formats, while premium tier differentiation requires material investment and closure engineering.
- Glass Bottles:Flint and amber glass containers with cork or synthetic closures dominate super-premium and luxury tiers. China's SAMR labeling standards mandate additive disclosure on primary packaging, forcing redesign cycles for imported portfolios.
- Plastic Bottles:PET and HDPE formats reduce freight cost for economy-tier vodka and rum in price-sensitive Indian and Southeast Asian markets. Environmental scrutiny under China's dual carbon goals is constraining new approvals for single-use plastic spirits packaging.
- Tins:Metal canisters serve ceremonial gifting functions for baijiu and limited-edition whisky releases. Procurement officers at Chinese state-owned enterprises prioritize documented carbon credentials for tin sourcing.
- Kegs:Stainless steel returnable containers supply on-premise dispensing systems for high-volume cocktail bars. Deployment concentrates in Tokyo and Melbourne hospitality corridors with established keg logistics infrastructure.
Glass Bottles absorb the majority of value. Kegs are climbing the fastest among format innovations.
Price Tier:
Margin architecture stratifies across four distinct expenditure thresholds, each with discrete channel access and regulatory exposure.
- Premium:Aged designations and verified provenance command placement in dedicated liquor stores and upscale supermarkets. Japan's National Tax Agency whisky authenticity criteria restrict geographic indication claims, compressing supply for genuine Japanese premium expressions.
- Mid-Range:Standard-aged whiskies and established gin brands sustain household penetration across supermarket and online channels. This tier faces the steepest competitive pressure from private-label extensions in Australian and South Korean retail.
- Economy:Unaged or minimally aged spirits in efficient packaging serve price-sensitive consumption in India's state-controlled liquor shops and Vietnam's traditional retail. FSSAI registration requirements prolong entry timelines for foreign economy-tier portfolios.
- Luxury:Limited releases, single-cask expressions, and heritage-designated baijiu dominate auction circuits and corporate gifting protocols. Kweichow Moutai's verified carbon-neutral distillery lines are securing preferential placement in Beijing and Shenzhen procurement channels.
Mid-Range captures the widest volume base. Luxury is gaining share fastest as gifting protocols rotate toward documented provenance.
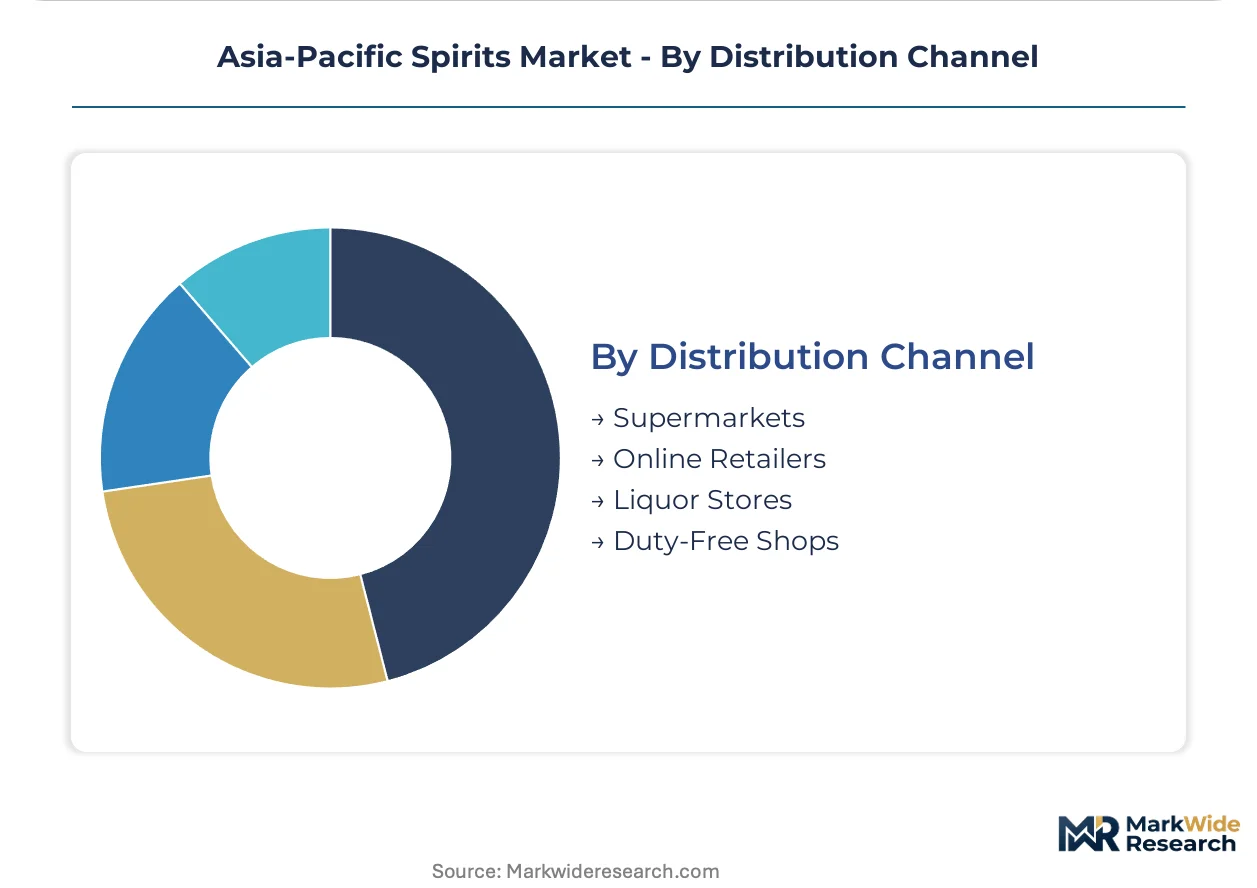
Distribution Channel:
Channel selection determines tax incidence, age verification burden, and brand control over pricing and placement.
- Supermarkets:Grocery and hypermarket chains with dedicated liquor sections sustain mid-range and economy volume across Australian, Japanese, and South Korean retail. Shelf-space fees and promotional calendars compress margin for imported brands.
- Online Retailers:Licensed e-commerce platforms in China and South Korea bypass traditional distributor markups through direct-to-consumer verification systems. SAMR and MFDS regulations mandate age-gating and delivery signature protocols that increase operational complexity.
- Liquor Stores:Specialty retailers with trained staff drive premium and luxury tier discovery through curated assortments. Independent stores in Singapore and Hong Kong maintain collector relationships for Japanese whisky limited releases.
- Duty-Free Shops:Airport and downtown travel retail channels absorb scarcity-driven demand for luxury expressions. Japan's domestic maturation investment post-2021 NTA criteria has concentrated single malt availability in Tokyo and Osaka duty-free corridors.
Supermarkets move the highest case volume. Online Retailers show the steepest expansion trajectory as verification technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baijiu fermentation traditions in China's Guizhou province established the foundational production architecture that now spans the Asia-Pacific spirits trade. Japanese whisky craftsmanship emerged from Yamazaki in 1923, creating a parallel heritage stream that commands scarcity premiums across Seoul, Singapore, and Hong Kong auction circuits today.
China
Tier-one cities Beijing, Shanghai, and Shenzhen absorb the majority of premium baijiu and aged whisky volume through corporate gifting protocols. SAMR labeling harmonization reduces cross-provincial trade friction for distillers operating under unified national food safety standards. Guizhou province hosts Kweichow Moutai's production base, where energy-intensive fermentation facilities face MEE emissions enforcement requiring thermal system retrofits.
Japan
Tokyo and Osaka duty-free corridors concentrate demand for single malt expressions following the 2021 National Tax Agency authenticity criteria restricting geographic indication claims. Limited-release allocations from established distilleries absorb collector premiums across domestic and export channels. Yamazaki and Hakushu maturation sites anchor domestic production capacity expansion responding to tightened regulatory definitions.
India
FSSAI registration requirements combined with state excise board levies create protracted entry timelines for foreign spirit portfolios seeking access to Delhi-Mumbai-Bangalore metropolitan clusters. Local whisky blends dominate volume through state-controlled liquor shops, while imported premium expressions face layered tariff incidence. Maharashtra and Karnataka hospitality corridors show nascent demand for super-premium gin and aged whisky.
South Korea
Seoul's Gangnam and Hongdae districts drive experiential cocktail culture demand for craft gin and Japanese whisky expressions. MFDS regulations mandate age-gating and delivery signature protocols for licensed e-commerce platforms bypassing traditional distributor markups. Domestic soju producers face margin pressure as consumer outlay rotates toward verified provenance imports.
Vietnam
Ho Chi Minh City and Hanoi hospitality corridors show underpenetrated demand for super-premium baijiu and aged whisky expressions. Traditional rice spirit consumption patterns create entry barriers for imported distillates lacking localized flavor profiling. Duty-free channels at Tan Son Nhat and Noi Bai airports absorb initial luxury tier exposure for traveling professionals.
Asia-Pacific Spirits Market Competitive Environment
Capital-heavy producers with heritage distillery assets compete with asset-light brand architects licensing third-party production capacity. The Asia-Pacific spirits structure concentrates around integrated fermentation-to-bottling operators, multinational portfolio conglomerates, and regional specialists commanding cultural authenticity premiums. Three archetypes dominate: heritage baijiu houses with state-linked distribution, Japanese craftsmanship distillers with scarcity positioning, and global spirits conglomerates with multi-price-tier coverage. Competitive moves center on domestic maturation capacity expansion and carbon-neutral certification alignment for state procurement access.
Within the heritage distillation tier, Kweichow Moutai Co., Ltd. and Wuliangye Yibin Co., Ltd. represent the integrated baijiu archetype with Guizhou and Sichuan production bases respectively. Suntory Holdings Limited occupies a position exemplifying Japanese craftsmanship scarcity positioning across domestic and export channels. Diageo PLC anchors the multinational portfolio conglomerate archetype with Scotch and Chinese white spirit distribution across multiple price tiers. These three patterns illustrate how geographic origin, production integration depth, and regulatory compliance posture stratify competitive positioning.
| Leading Market Players |
|---|
| Kweichow Moutai Co., Ltd. |
| Bacardi Limited |
| Diageo PLC |
| Asahi Group Holdings Ltd |
| Thai Beverage PLC |
| Pernod Ricard SA |
| Wuliangye Yibin Co., Ltd. |
| LVMH Moët Hennessy Louis Vuitton |
| Suntory Holdings Limited |
| Others |
Value Chain & Pricing Dynamics
Malted barley futures from the Australian Grain Exchange cascade through Asia-Pacific distillation economics, compressing margin pools at Scotch and Japanese whisky producers while amplifying pricing power for Guizhou baijiu houses with captive grain sourcing. This input-cost asymmetry stratifies final-product pricing tiers and redirects procurement strategies toward long-term malt supply agreements.
Pricing Analysis
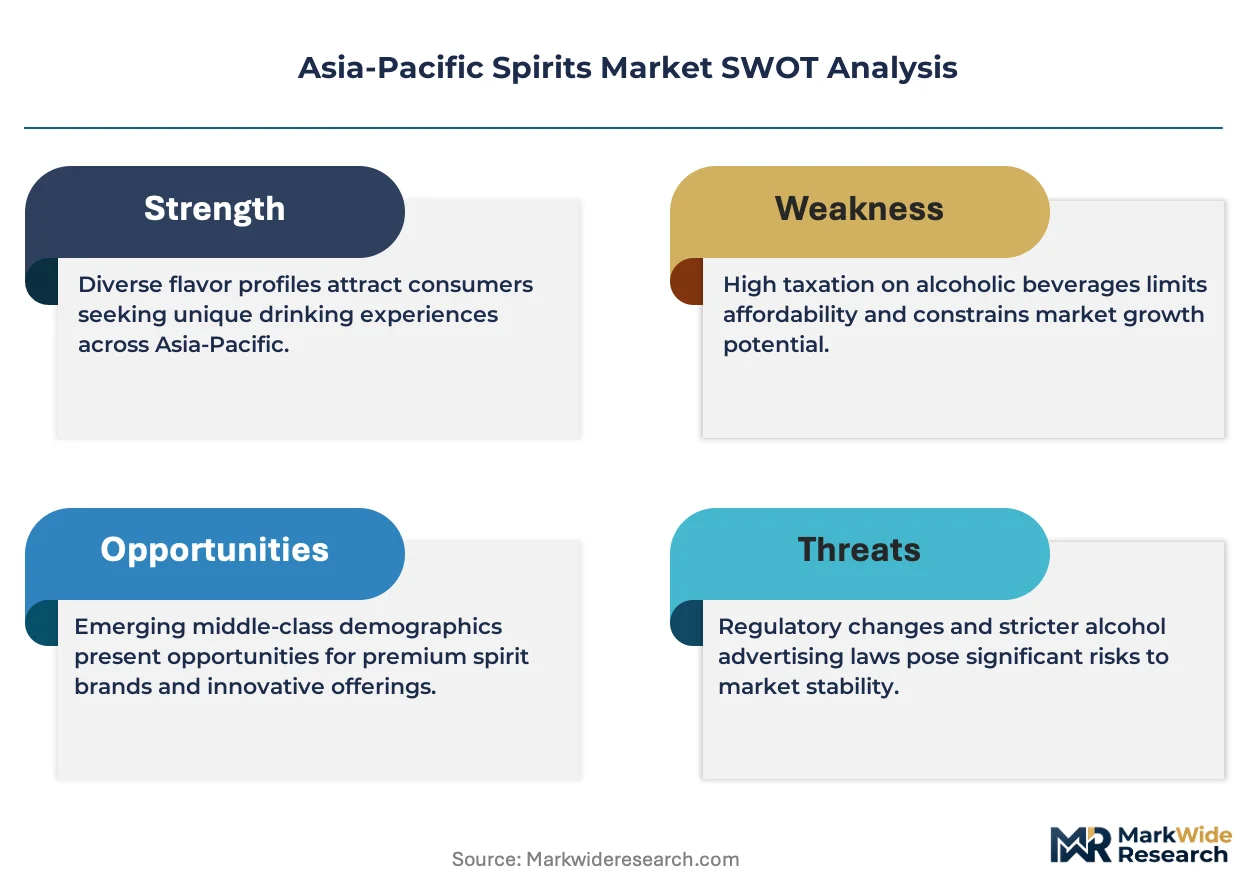
Three-tier pricing structure across premium, standard, and economy levels dominates Asia-Pacific spirits, with verified carbon credentials and documented aging periods commanding measurable premiums over commodity-grade expressions. Price differentiation hinges on emission-compliant production certification and scarcity-driven provenance documentation. Cost compression in mid-range whisky is intensifying because Australian grain belt climate stress has compressed malt supply predictability. Economy-tier buyers in India's state-controlled liquor shops exhibit highest price sensitivity, while luxury-tier collectors in Tokyo and Hong Kong auction circuits demonstrate lowest elasticity.
Supply Chain Analysis
Returnable stainless steel keg flows concentrate in Tokyo and Melbourne hospitality corridors, reducing packaging waste while requiring established reverse-logistics infrastructure for sanitizer-loop refurbishment. Primary distillation capacity concentrates in China, Japan, and Scotland, with Guizhou fermentation sites and Yamazaki maturation warehouses anchoring regional supply. Raw material flows draw from Australian malt barley, Canadian grain belts, and Scottish peat bogs. Single-source vulnerability concentrates in Japanese domestic maturation capacity following 2021 NTA authenticity criteria. Distribution runs through licensed e-commerce platforms in China and South Korea alongside traditional duty-free corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific spirits constitute a late-cycle quality story as corporate gifting protocols rotate toward documented provenance and limited-edition releases over volume-based transactions.
For Market Incumbents: Extend domestic maturation capacity in Japan and carbon-neutral certification coverage in Guizhou to defend against emerging craft-distiller entrants and tightening MEE emissions enforcement. Backward integration into captive grain sourcing secures supply predictability against Australian climate volatility. Channel control through licensed e-commerce verification systems preserves pricing power against distributor markup compression. For New Entrants and Emerging Players: Specialty liquor retailers in Vietnam's Ho Chi Minh City corridor offer lowest competitive density for super-premium baijiu and aged whisky penetration. Direct-to-retailer digital platforms bypass entrenched distributor networks while MFDS and SAMR compliance investments create regulatory moats. Localized flavor profiling for traditional rice spirit consumers unlocks Hanoi household penetration. For Investors and Strategic Acquirers: Asymmetric upside sits with heritage-distiller archetypes possessing verified carbon-neutral production lines and state-procurement channel access. Long-term viability favors integrated fermentation-to-bottling operators over asset-light brand licensors in a market rotating toward provenance documentation. Watch for MEE enforcement acceleration as inflection indicator for compliance-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Maturation Capacity Expansion | Post-2021 NTA criteria restrict geographic indication claims to Japan-distilled spirits, concentrating scarcity value. |
| Carbon-Neutral Certification Alignment | ISO 14001-compliant distillery operations unlock preferential placement in Beijing and Shenzhen state procurement channels. |
| Direct-to-Retailer Digital Channel Buildout | Licensed e-commerce platforms in China and South Korea bypass traditional distributor markups for verified buyer segments. |
| Heritage Distillery Asset Acquisition | Guizhou and Sichuan production bases with established baijiu fermentation architecture command cultural authenticity premiums. |
| Regional Botanical Gin Development | Craft expressions with localized flavor signatures capture mixology-driven demand in Bangkok, Sydney, and Shanghai bar scenes. |
Study Parameters
Coverage spans China, Japan, India, South Korea, and Vietnam, with primary inputs from each market's distillation executives, regulatory affairs specialists, hospitality procurement managers, and grain supply coordinators. Secondary validation draws from SAMR disclosure filings, Japan National Tax Agency whisky criteria documentation, FSSAI registration databases, and customs trade flow records. Bottom-up capacity assessments triangulate against top-down consumption estimates across the analysis window.
Granularity-level modeling disaggregates volume and value outputs across product type, price tier, packaging format, and distribution channel dimensions, with additional segmentation by regional regulatory cluster and carbon compliance status. CAGRs derive from trend extrapolation anchored in historical trajectory analysis and policy-impact scenario weighting. Forecast inputs incorporate MEE emissions enforcement timelines, NTA geographic indication criteria evolution, and corporate gifting protocol shifts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to climate stress on Australian grain belts and layered tariff restructuring across Indian state excise jurisdictions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Ready to Drink Cocktails Market
Alcoholic Beverages
Home Brew Boiler Market
Alcoholic Beverages
Global Hard Seltzers Market
Alcoholic Beverages
West Africa Alcoholic Beverages Market
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
Pinot Noir Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Global Bars and Nightclubs Market
Alcoholic Beverages
Wine Chocolate Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
Middle East and Africa Fermented Drinks Market
Alcoholic Beverages
Beer Stabilizers Market
Alcoholic Beverages
Italy Alcohol E-Commerce Market