
 Wound Skin Care Market | 2026-2036
Wound Skin Care Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Skin Care Market Analytics
Market Context
The capital-intensity divergence between integrated manufacturers and specialized innovators is reorganizing competitive dynamics in wound skin care. Smith+Nephew leverages its end-to-end surgical and advanced wound management portfolio to sustain premium positioning across hospital systems. Coloplast A/S anchors its presence in chronic care segments through deep channel relationships with long-term care facilities. Mölnlycke Health Care AB differentiates via silicone-based dressing technology and direct clinician engagement models.
Technical Definition and Structural Segments
Wound skin care encompasses medical products designed to protect, hydrate, debride, or biologically activate healing in compromised integumentary tissue, typically incorporating absorbent hydrocolloid or alginate matrices with moisture vapor transmission rates calibrated between 2,000 and 8,000 g/m²/24hr. These products serve to prevent infection, manage exudate, and accelerate re-epithelialization across acute and chronic injury presentations. Advanced dressings command margin pools through antimicrobial silver ion integration and sustained-release formulations, while biologics represent the fastest-expanding category as skin substitute grafts gain reconstructive and burn center adoption. Traditional dressings remain volume-dominant in emerging markets where cost sensitivity limits advanced product uptake.
Regulatory Framework and Outlook
FDA 510(k) clearance pathways and EMA Medical Device Regulation (MDR) classification systems govern market access for wound care products, with biologics facing additional Center for Biologics Evaluation and Review (CBER) or EMA Committee for Advanced Therapies scrutiny. ISO 13485 quality management certification and country-specific pharmacovigilance reporting shape supplier qualification requirements across hospital procurement networks. Stakeholders must monitor evolving reimbursement codes for cellular and tissue-based products while calibrating R&D portfolios against tightening clinical evidence thresholds.
Market Dynamics
FDA and EMA tightening of clinical evidence requirements for biologic skin substitutes is compressing development timelines and forcing manufacturers to restructure trial protocols before market authorization.
Growth Catalysts
- Silver ion antimicrobial integration:Hospital systems in Germany prioritize advanced dressings with sustained-release silver formulations to reduce surgical site infections and shorten length-of-stay metrics.
- Japan's aging demographic density:Long-term care facilities across Tokyo and Osaka prefectures drive recurring procurement volumes for hydrocolloid and alginate dressing categories.
- ISO 13485 certification expansion:Emerging market manufacturers achieving quality management certification unlock access to hospital procurement networks previously restricted to established suppliers.
Market Restraints
- Alginate raw material concentration:Seaweed harvesting for alginate wound dressings concentrates in coastal regions of Scotland and Norway, exposing supply chains to marine ecosystem volatility.
- EMA MDR transition friction:Reclassification of certain advanced dressings under stricter medical device regulations extends conformity assessment timelines by 12-18 months for European market entry.
- Traditional gauze substitution persistence:Cost-sensitive healthcare systems in lower-income markets continue defaulting to cotton-based dressings despite inferior moisture management outcomes.
Strategic Opportunities
- Home care channel expansion:Direct-to-patient distribution models for chronic wound management bypass hospital markup structures and capture recurring revenue streams in the United States.
- Silicone adhesive convergence with electronics:Integration of biosensor capabilities into silicone-based dressings enables real-time exudate monitoring for diabetic foot ulcer patients.
- India's PLI scheme for medical devices:Production-linked incentive frameworks reduce effective manufacturing costs for domestic wound care producers targeting export markets.
Industry Challenges
- Biologic graft handling protocols:Specialized cold chain infrastructure and tissue banking coordination require capital deployment that mid-tier manufacturers struggle to finance.
- 510(k) predicate device drift:FDA narrowing of acceptable predicate comparisons for novel dressing materials forces de novo pathway submissions with extended review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Skin Care Market |
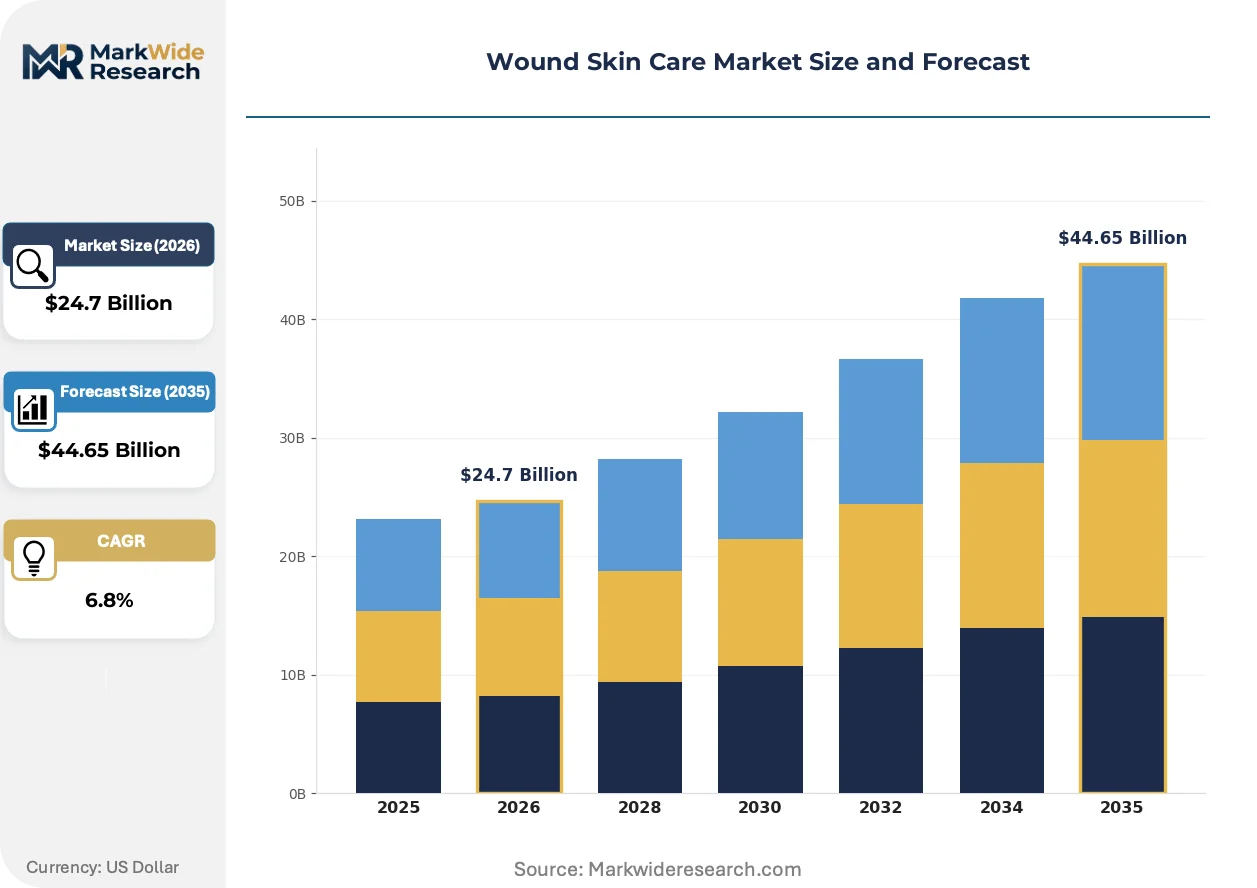
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Advanced Dressings, Traditional Dressings, Topical Agents, Biologics Application: Burns, Surgical Wounds, Chronic Wounds, Traumatic Wounds End User: Hospitals, Home Care, Clinics, Long-term Care Facilities Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Solventum, Smith+Nephew, 3M, Johnson & Johnson Services, Inc., ConvaTec Group PLC, Coloplast A/S, Mölnlycke Health Care AB, Cardinal Health, B. Braun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Skin Care Market Evolving Landscape
Wearable biosensor integration and bioactive material science are converging to transform passive dressings into therapeutic delivery platforms that monitor and respond to wound conditions in real time.
Electrospun nanofiber matrices engineered from polycaprolactone and collagen blends are miniaturizing scaffold architectures to sub-micron scales. Burn centers in the United States are adopting these structures for partial-thickness wound coverage. The technology is miniaturizing pore geometries to match native extracellular matrix dimensions, accelerating fibroblast migration and reducing graft rejection rates.
EMA Medical Device Regulation (MDR) Article 10 post-market surveillance requirements now mandate systematic clinical follow-up for Class III wound care devices. Manufacturers must establish periodic safety update reports and vigilance systems. High-risk biologic skin substitutes face the steepest compliance burden, with notified bodies demanding real-world evidence registries.
Hospital procurement consortia in Germany are consolidating vendor panels through single-source contracts for advanced wound management categories. Regional purchasing cooperatives replace individual facility negotiations. This concentration is most visible in North Rhine-Westphalia, where university hospital networks now contract directly with integrated manufacturers for five-year supply agreements.
Wound Skin Care Market Segmentation
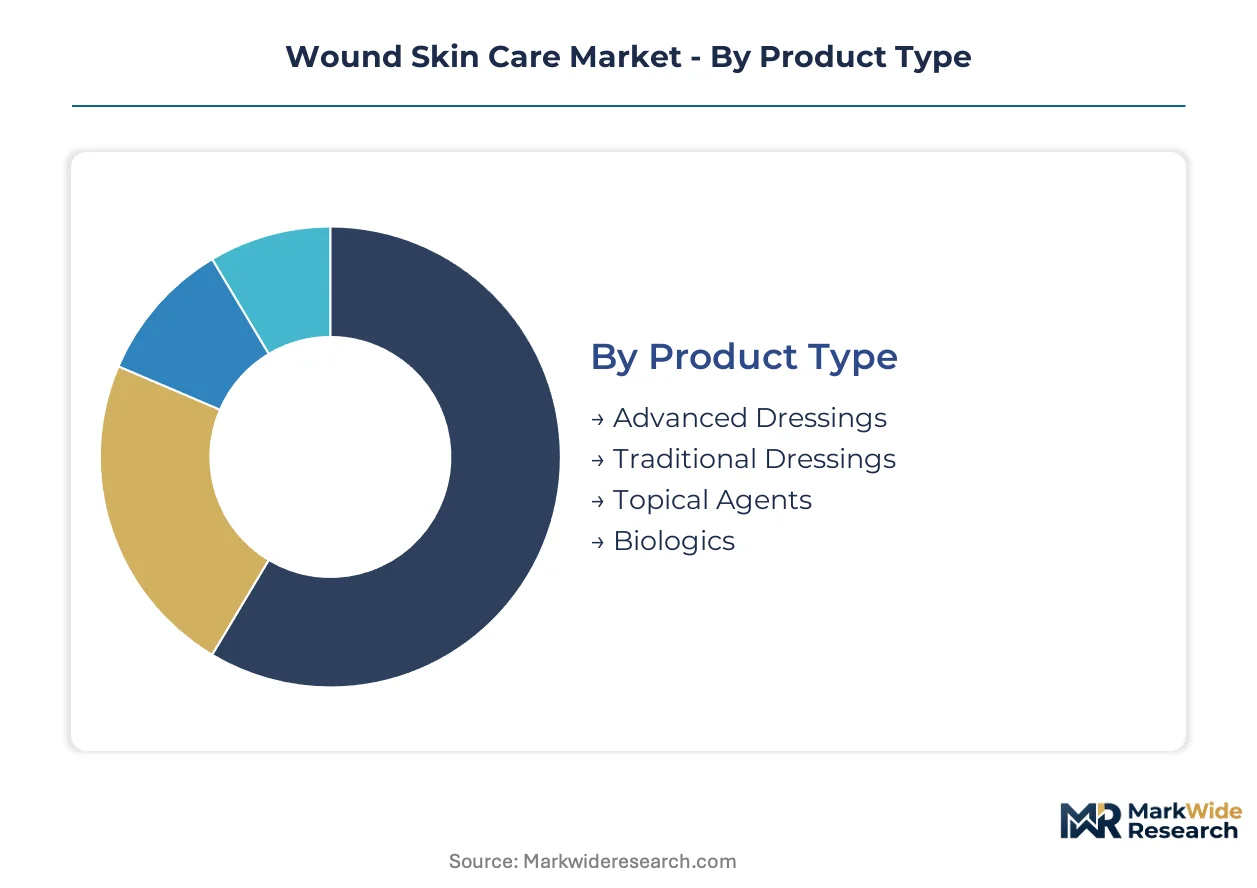
Wound skin care segmentation reflects divergent regulatory pathways and reimbursement frameworks across product categories. Manufacturers calibrate portfolio investments against distinct margin profiles and clinical evidence requirements.
Product Type:
FDA 510(k) clearance timelines vary dramatically across this category, with biologics facing CBER oversight while advanced dressings navigate predicate device pathways.
- Advanced Dressings:Hydrocolloid, alginate, and foam matrices with moisture vapor transmission rates between 2,000 and 8,000 g/m²/24hr dominate hospital procurement in Germany. Silver ion antimicrobial integration commands premium positioning as surgical site infection reduction becomes a reimbursable outcome metric.
- Biologics:Cellular and tissue-based skin substitutes require cold chain infrastructure and specialized tissue banking coordination. Burn centers in the United States drive adoption as reconstructive applications expand, though EMA MDR Article 10 post-market surveillance mandates now demand systematic clinical follow-up.
- Traditional Dressings:Cotton gauze and basic adhesive strips retain volume dominance in cost-sensitive emerging markets where reimbursement limits advanced product penetration.
- Topical Agents:Antimicrobial creams, hydrogels, and enzymatic debriders serve outpatient wound management protocols across Japanese long-term care networks.
Advanced Dressings handles the majority of throughput; Biologics is the fastest mover on share.
Application:
Clinical settings determine product specification requirements, with acute interventions prioritizing hemostasis and chronic presentations demanding moisture balance.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers drive recurring consumption of silicone-based and hydrofiber dressings. Home care channels in the United States capture expanding volumes as reimbursement shifts toward outpatient management.
- Surgical Wounds:Post-operative incision care requires antimicrobial prophylaxis and absorbency calibrated to exudate volume. German hospital procurement consortia consolidate vendor panels through single-source contracts for advanced categories.
- Burns:Partial and full-thickness thermal injuries utilize biologic grafts and biosynthetic matrices in specialized burn centers.
- Traumatic Wounds:Emergency department presentations favor rapid-application foam and film dressings for hemostasis and contamination barrier.
Chronic Wounds absorbs the greatest product volume; Surgical Wounds is expanding most quickly on procedural volume growth.
End User:
Procurement authority and reimbursement access create distinct channel economics across institutional settings.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements with manufacturers holding ISO 13485 certification. Operating room and wound care unit consumption drives bulk purchasing of advanced dressing categories.
- Home Care:Direct-to-patient distribution models bypass hospital markup structures. Diabetic foot ulcer management in the United States generates recurring revenue through subscription-based replenishment programs.
- Long-term Care Facilities:Pressure injury prevention protocols across Tokyo and Osaka prefectures sustain alginate and hydrocolloid demand in Japan's aging care infrastructure.
- Clinics:Outpatient wound centers handle debridement and dressing changes with lower inventory depth than acute care settings.
Hospitals commands the dominant procurement volume; Home Care is gaining share fastest on reimbursement migration.
Distribution Channel:
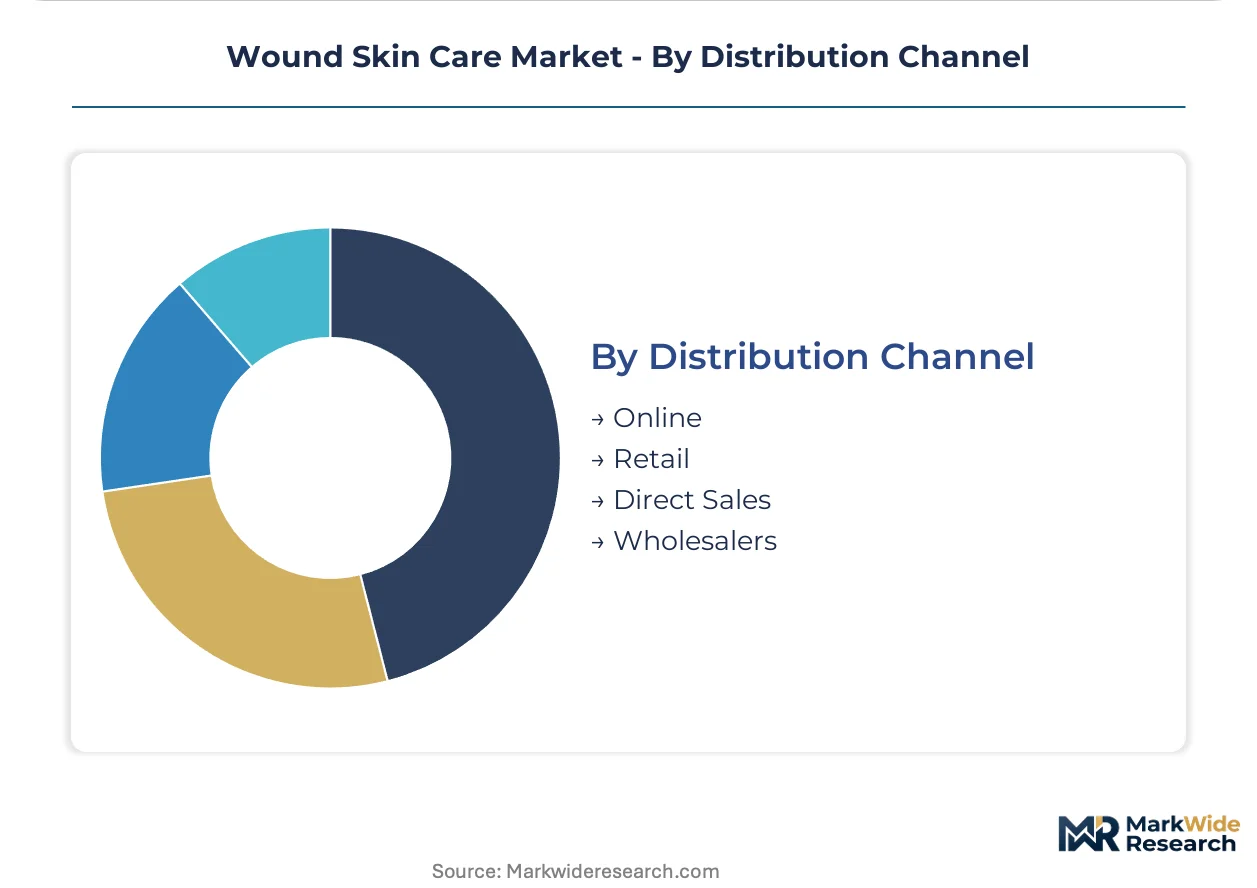
Channel selection reflects customer scale, urgency requirements, and regulatory documentation needs.
- Direct Sales:Manufacturer representatives engage hospital procurement committees and wound care specialists with clinical evidence portfolios. German university hospital networks in North Rhine-Westphalia contract directly with integrated manufacturers for advanced wound management categories.
- Wholesalers:Regional distributors aggregate demand from smaller clinics and long-term care facilities, managing inventory for products with stable demand profiles.
- Online:E-commerce platforms serve home care patients and small-practice clinicians with replenishment ordering convenience.
- Retail:Pharmacy and medical supply stores capture consumer-directed purchases of basic adhesive and gauze products.
Direct Sales manages the highest-value transactions; Online is climbing the fastest on home care channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate low price elasticity for advanced dressings with antimicrobial integration, while procurement officers in India and Brazil remain highly sensitive to unit costs and prioritize traditional gauze alternatives.
United States
Burn centers in Texas and Arizona drive biologic skin substitute consumption for reconstructive applications. FDA CBER oversight of cellular and tissue-based products requires manufacturers to maintain rigorous cold chain documentation. Hospital procurement consortia in the Northeast Corridor consolidate vendor panels through multi-year supply agreements with ISO 13485-certified suppliers.
Germany
University hospital networks in North Rhine-Westphalia negotiate single-source contracts for advanced wound management categories. EMA MDR Article 10 post-market surveillance mandates systematic clinical follow-up for Class III devices. Surgical site infection reduction protocols in Bavarian medical centers prioritize silver ion antimicrobial dressings with sustained-release formulations.
Japan
Long-term care facilities across Tokyo and Osaka prefectures sustain recurring demand for hydrocolloid and alginate dressing categories. METI industrial policy supports domestic medical device manufacturing through targeted subsidy programs. Aging demographic density in the Kanto region concentrates pressure injury prevention protocol implementation.
India
Cost-sensitive hospital systems in Maharashtra and Gujarat default to cotton-based traditional dressings despite inferior moisture management outcomes. CDSCO medical device registration requirements are tightening quality management system expectations for market authorization. The PLI scheme for medical devices reduces effective manufacturing costs for domestic producers targeting export markets from Tamil Nadu clusters.
Brazil
Public health procurement through SUS channels limits advanced dressing penetration in favor of basic adhesive and gauze products. ANVISA medical device registration pathways require in-country testing for novel wound care materials. São Paulo-based distributors aggregate demand from smaller clinics managing chronic wound outpatient protocols.
Wound Skin Care Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure with limited overlap between premium innovators and volume manufacturers. The vendor base clusters around three strategic archetypes: integrated surgical portfolio holders, specialized chronic care specialists, and emerging market cost optimizers. Dominant competitive moves include geographic expansion through distributor partnerships and portfolio diversification into adjacent wound management categories.
Among the integrated surgical portfolio holders, Smith+Nephew and 3M occupy positions exemplifying end-to-end wound and surgical care convergence. Coloplast A/S represents the specialized chronic care archetype with deep channel relationships in long-term care facilities. These three companies anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Solventum |
| Smith+Nephew |
| 3M |
| Johnson & Johnson Services, Inc. |
| ConvaTec Group PLC |
| Coloplast A/S |
| Mölnlycke Health Care AB |
| Cardinal Health |
| B. Braun |
| Others |
Value Network & Pricing Analysis
ISO 13485 certification gates both supply qualification and price differentiation simultaneously, separating certified manufacturers who command hospital procurement access from uncertified competitors relegated to commodity tenders. This quality management standard creates a bifurcated pricing landscape where certification status determines margin capture more than raw material costs.
Pricing Analysis
Recurring replenishment contracts for chronic wound management drive lifetime value in the home care channel. Three-tier pricing structure across premium, standard, and economy levels segments buyers by clinical setting complexity, with antimicrobial silver integration and silicone adhesive technology commanding tier-one positioning. Cost compression in the traditional gauze segment is intensifying because emerging market procurement officers prioritize unit economics over moisture management performance. Long-term care facilities in Japan demonstrate the lowest price sensitivity, while public health systems in Brazil exhibit acute responsiveness to per-unit differentials.
Supply Chain Analysis
Container availability constraints on the Scotland-Norway marine harvesting corridor elevate inbound logistics costs for alginate raw material sourcing. Seaweed harvesting concentrates in coastal Scotland and Norway, with polycaprolactone and collagen blends for electrospun matrices drawing from pharmaceutical-grade suppliers in Germany and the United States. Single-source vulnerability in marine ecosystem-dependent inputs exposes manufacturers to harvest volatility from North Atlantic temperature fluctuations. Distribution runs through hospital procurement consortia in Germany and direct-to-patient platforms in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of cold chain infrastructure and tissue banking coordination capabilities constrains mid-tier manufacturer participation in biologic skin substitutes, creating defendable positions for capital-deployed incumbents.
For Market Incumbents: Consolidate procurement relationships with German university hospital networks through multi-year single-source contracts before EMA MDR Article 10 surveillance mandates harden vendor qualification requirements. Deepen backward integration into alginate harvesting operations to secure supply against marine ecosystem volatility. Prioritize ISO 13485 certification maintenance as a barrier to emerging market cost optimizers seeking hospital network access. For New Entrants and Emerging Players: CDSCO fast-track registration for medical devices in India offers a lower-evidence pathway than FDA 510(k) or EMA MDR routes. Target home care channel expansion in the United States where reimbursement migration toward outpatient management creates white-space demand for direct-to-patient distribution models. Pursue silicone-based dressing innovation with biosensor integration as a differentiated entry angle against established hydrocolloid incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologic skin substitute manufacturing as cold chain infrastructure and real-world evidence registry maintenance become mandatory cost layers. Long-term viability favors integrated manufacturers with end-to-end surgical and wound management portfolios over pure-play dressing specialists. Watch EMA notified body capacity constraints as an inflection signal for European market entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks hospital procurement network access previously restricted to established suppliers in Germany and the United States. |
| Silicone Biosensor Integration | Enables real-time exudate monitoring for diabetic foot ulcer patients in home care settings. |
| Backward Integration into Alginate Harvesting | Secures supply chain resilience against North Atlantic marine ecosystem volatility affecting Scotland and Norway. |
| Direct-to-Patient Distribution Model | Bypasses hospital markup structures and captures recurring revenue streams in United States chronic wound management. |
| EMA MDR Article 10 Compliance Infrastructure | Mandates systematic clinical follow-up for Class III devices, creating regulatory moats against undercapitalized competitors. |
Research Methodology
Initial hypotheses were tested against primary input from wound care clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation. FDA 510(k) clearance databases, EMA MDR submission records, hospital procurement databases, and CMS Medicare reimbursement data provided structural anchors. Bottom-up demand modeling across product categories triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects in advanced dressings versus biologics versus traditional categories. Segmentation dimensions include product type, application setting, end-user institution, and distribution channel complexity, with regional regulatory clusters modeled separately. CAGRs were derived from fitted growth curves anchored to procedural volume trends and reimbursement migration patterns. Forecast inputs incorporate aging demographic density in Japan and hospital procurement consolidation in Germany.
Underlying assumptions cover stable FDA and EMA regulatory frameworks, with deviation risk concentrated in biologic skin substitute evidence requirement tightening and marine ecosystem volatility for alginate supply. Forecasts reflect these documented conditions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Europe Advanced Wound Care Market
Wound Care
Bioactive Wound Dressing Market
Wound Care
Bioactive Wound Management Market
Wound Care
Advanced Wound Management Market
Wound Care
Wound Care Centers Market
Wound Care
Global Burn Care Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Europe Wound Care Market
Wound Care
US Burn Care Centers Market
Wound Care
Wound Care Market
Wound Care
Chronic Wound Care Market
Wound Care
South Korea Wound Care Market
Wound Care
Wound Measurement Devices Market
Wound Care
Liquid Bandages Market
Wound Care
US Wound Care Centers Market
Wound Care
Global Diabetic Foot Ulcers Market