
 Asia Pacific Wound Care Market | 2026-2036
Asia Pacific Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Wound Care Market Insights
CE marking under the EU MDR is rotating as the de facto quality benchmark for Asia Pacific wound care exporters serving premium hospital segments. Mölnlycke Health Care leverages its Swedish manufacturing heritage to sustain premium positioning across Australian and Japanese tertiary centers. Smith & Nephew anchors its regional presence through specialized negative pressure wound therapy systems. ConvaTec Group differentiates via advanced ostomy and wound drainage portfolios tailored to aging patient demographics.
Asia Pacific wound care encompasses absorbent, antimicrobial, and moisture-retentive products engineered from hydrogel, foam, textile, and antimicrobial substrates to manage exudate, prevent infection, and accelerate tissue regeneration across acute surgical, chronic diabetic, and burn trauma cases. The dressings category dominates volume as hospitals standardize on silver-ion and foam composites for post-operative recovery, while the chronic wounds application segment captures expanding margin pools from diabetic foot ulcer protocols in China and India. Homecare end users represent the fastest-growing channel as post-discharge monitoring shifts toward nurse-led residential services in Australia and South Korea.
Japan's PMDA governs medical device registration timelines, Australia's TGA enforces biocompatibility testing for imported dressings, and India's CDSCO mandates local clinical validation for advanced wound therapy devices, collectively raising compliance costs for new entrants while protecting incumbent quality leaders. China's NMPA accelerated review pathways for innovative wound healing biologics are reshaping competitive access dynamics. Stakeholders must monitor how harmonization between ASEAN medical device directives and national regulators affects cross-border product registration strategies.
Market Dynamics
Japan's MEE environmental standards for medical waste disposal are pushing manufacturers toward biodegradable hydrogel formulations, fundamentally restructuring raw material sourcing and product development priorities across the region.
Growth Catalysts
- Silver-ion antimicrobial integration:Tertiary care networks in India and Australia are standardizing advanced foam composites with embedded silver ions for post-operative recovery protocols, accelerating hospital procurement cycles.
- Japan's MEE biodegradability mandates:Environmental compliance requirements for medical waste disposal are creating guaranteed demand pull for hydrogel manufacturers investing in enzymatically degradable polymer backbones.
- Homecare nursing expansion:Nurse-led residential wound monitoring services in Australia's metropolitan periphery and South Korea's aging suburbs are opening new channel volume for portable negative pressure systems.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane foam and superabsorbent polymer production depends on propylene oxide and acrylic acid derivatives, exposing margin structures to naphtha-cracker output fluctuations across Northeast Asian petrochemical complexes.
- Regulatory friction from India's CDSCO:Local clinical validation mandates for advanced wound therapy devices extend registration timelines by 18-24 months, freezing early-stage entrants from premium hospital segments.
- Technical limitation in chronic wound closure:Diabetic foot ulcer protocols in China and India remain constrained by inconsistent vascular assessment infrastructure, capping therapy efficacy rates regardless of dressing sophistication.
Strategic Opportunities
- Underpenetrated western India demand:Mumbai and Pune anchor private hospital chain expansion where advanced dressing penetration lags southern metros by 40 percentage points, creating whitespace for specialized distribution partnerships.
- NMPA accelerated biologics pathways:China's innovative wound healing biologics fast-track is compressing competitive access timelines for recombinant growth factor and stem cell-derived matrix entrants.
- Telemedicine-nursing convergence:Remote wound imaging combined with nurse dispatch platforms is emerging as a service layer in Australian and Japanese homecare markets, enabling subscription-based dressing replenishment models.
Industry Challenges
- Wound care specialist nursing shortage:Certified wound ostomy continence nurses remain concentrated in tier-1 hospital systems across China and India, limiting protocol standardization in community care settings.
- CE marking to EU MDR transition complexity:Asia Pacific exporters serving premium segments face documentation recertification burdens as notified bodies consolidate under stricter European oversight, compressing margin recovery timelines.
- Legacy ERP integration with traceability systems:Hospital procurement networks in Japan and South Korea require UDID-compliant serialization that conflicts with incumbent inventory management architectures, forcing middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Wound Care Market |
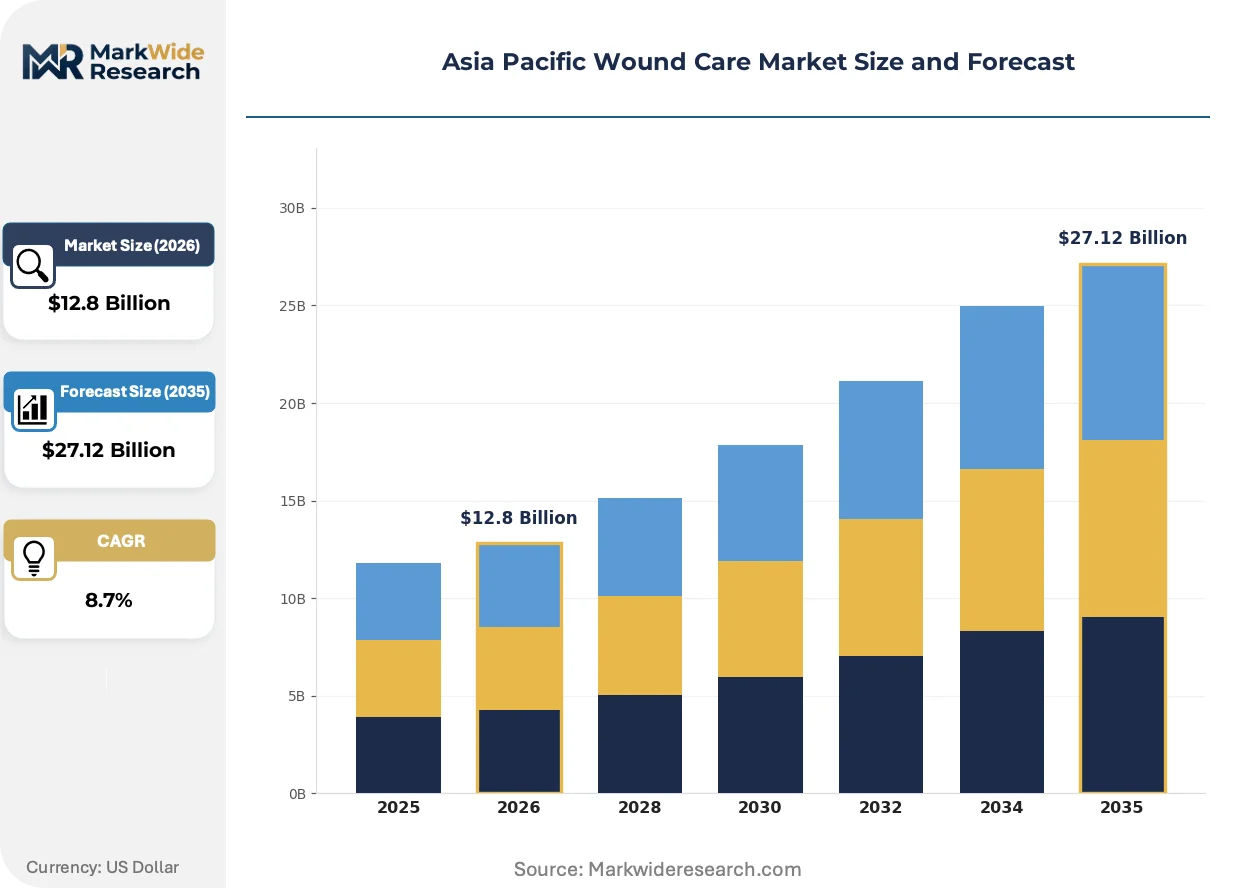
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Adhesives, Antiseptics, Therapies End User: Hospitals, Homecare, Clinics, Long-term Care Facilities Application: Surgical Wounds, Chronic Wounds, Burns, Ulcers Material: Hydrogel, Foam, Antimicrobial, Textile |
| Companies Covered | Mölnlycke Health Care, Baxter International, 3M, Medline Industries, B. Braun, Smith & Nephew, Coloplast Group, Cardinal Health, ConvaTec Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Wound Care Market Trends and Innovations
Digital wound assessment tools and bioactive material platforms are restructuring how clinicians evaluate healing progression and select therapeutic interventions across acute and chronic care pathways.
Smart dressing technology incorporating pH-sensitive dyes and wireless moisture sensors is bifurcating the traditional dressing category into passive absorbents and active monitoring platforms. Australian tertiary centers and Japanese long-term care facilities are piloting these systems for diabetic foot surveillance. The technology is bifurcating procurement committees into separate evaluation tracks for commodity dressings versus connected care infrastructure, reshaping vendor qualification criteria.
China's NMPA has established priority review channels for innovative wound healing biologics including recombinant human epidermal growth factor and decellularized extracellular matrix products. This regulatory architecture is compressing time-to-market for domestic developers while raising comparative evidence requirements for imported alternatives. Multinational manufacturers are responding by relocating clinical trial operations to Shanghai and Guangzhou to capture accelerated pathway access.
Hospital purchasing committees in South Korea and Australia are unbundling after-sales clinical training from device procurement contracts, treating education as a separately negotiated service line. This behavioral shift is fragmenting traditional bundled pricing models and exposing pure equipment vendors to specialist nursing consultancy competitors. The pattern is most visible in negative pressure wound therapy system tenders, where device margins compress while training and protocol development fees expand.
Asia Pacific Wound Care Market Segmentation
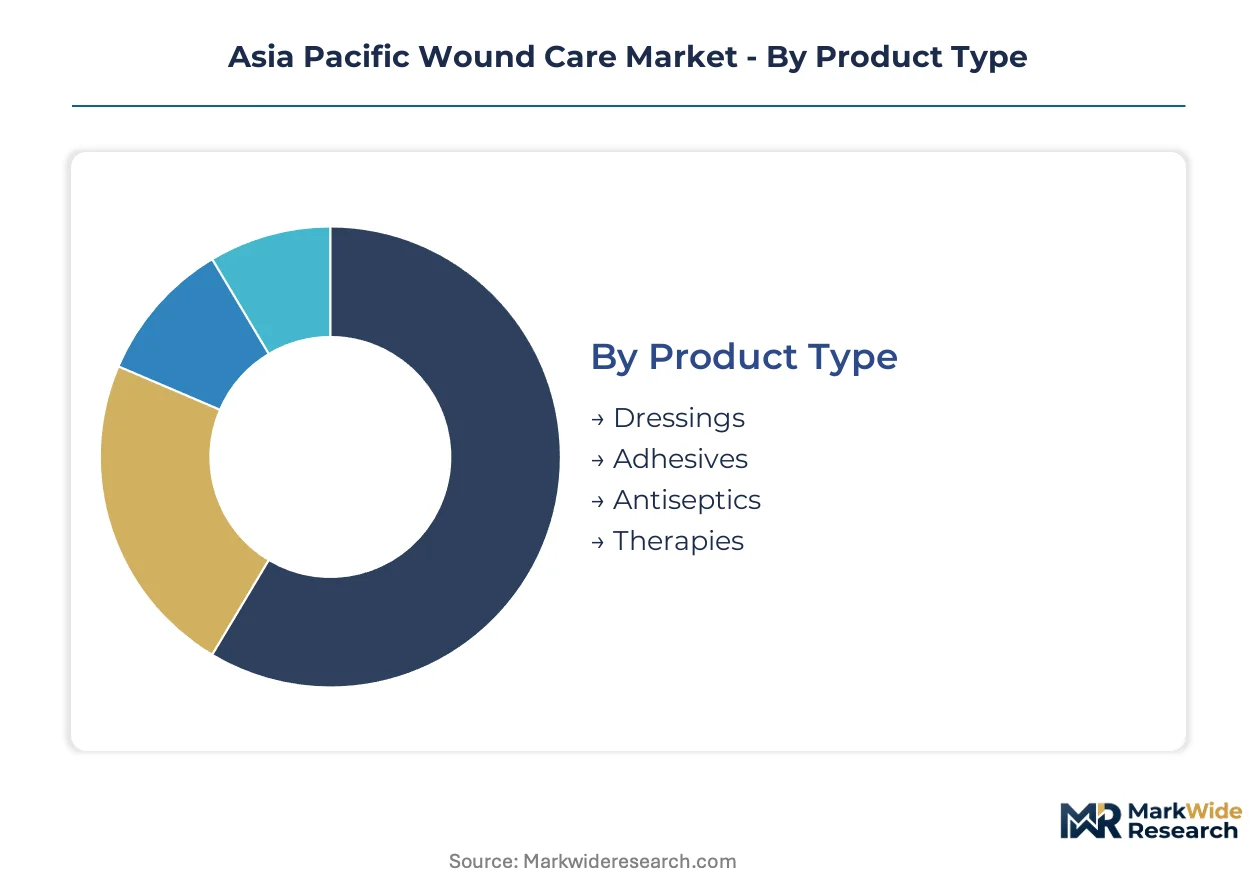
Segmentation in Asia Pacific wound care reveals how procurement priorities diverge between institutional buyers and emerging homecare channels. Material composition and application specificity determine reimbursement eligibility and clinical protocol adoption across Japan, India, and Australia's distinct regulatory environments.
Product Type:
Margin pools concentrate in advanced therapeutic interventions where hospital procurement committees pay premiums for clinical outcomes documentation.
- Dressings:Absorbent, antimicrobial, and moisture-retentive substrates manage exudate across acute surgical and chronic diabetic cases. Silver-ion foam composites dominate tertiary care standardization in India and Australia, with enzymatically degradable hydrogel variants gaining share under Japan's MEE environmental mandates.
- Therapies:Negative pressure wound therapy systems and specialized biologics command the highest per-procedure revenue. China's NMPA accelerated review pathways for recombinant growth factor products are compressing competitive access timelines for domestic developers.
- Adhesives:Medical-grade bonding agents secure dressing placement during patient mobility.
- Antiseptics:Topical antimicrobial solutions prevent infection in pre-operative skin preparation and wound cleansing protocols.
Dressings hold installed capacity. Therapies is rotating up the share rankings.
End User:
Channel economics split between volume-driven institutional contracts and expanding residential service models.
- Hospitals:Tertiary care networks anchor procurement volume through standardized formulary contracts. Mumbai and Pune private hospital chains are expanding advanced dressing penetration that lags southern Indian metros by substantial margins.
- Homecare:Nurse-led residential wound monitoring represents the steepest expansion trajectory across Australia's metropolitan periphery and South Korea's aging suburbs. Telemedicine-nursing convergence enables subscription-based dressing replenishment models.
- Clinics:Outpatient wound management centers handle post-discharge monitoring and dressing changes.
- Long-term Care Facilities:Japanese eldercare institutions pilot smart dressing technology with pH-sensitive dyes for diabetic foot surveillance.
Hospitals retain contract volume concentration. Homecare is climbing the fastest in year-over-year channel growth.
Application:
Clinical complexity and reimbursement intensity vary sharply between acute intervention and chronic management protocols.
- Chronic Wounds:Diabetic foot ulcer protocols in China and India capture expanding margin pools, though therapy efficacy remains constrained by inconsistent vascular assessment infrastructure in community settings.
- Surgical Wounds:Post-operative recovery standardization drives foam composite and silver-ion antimicrobial demand across tertiary care networks. Australian and Japanese hospital purchasing committees unbundle after-sales clinical training from device contracts.
- Burns:Trauma center specialization requires advanced moisture-retentive and antimicrobial substrate combinations.
- Ulcers:Pressure and venous ulcer management protocols vary by long-term care facility certification levels.
Surgical wounds maintains procedure volume leadership. Chronic wounds is gaining share fastest on demographic and diabetes prevalence trends.
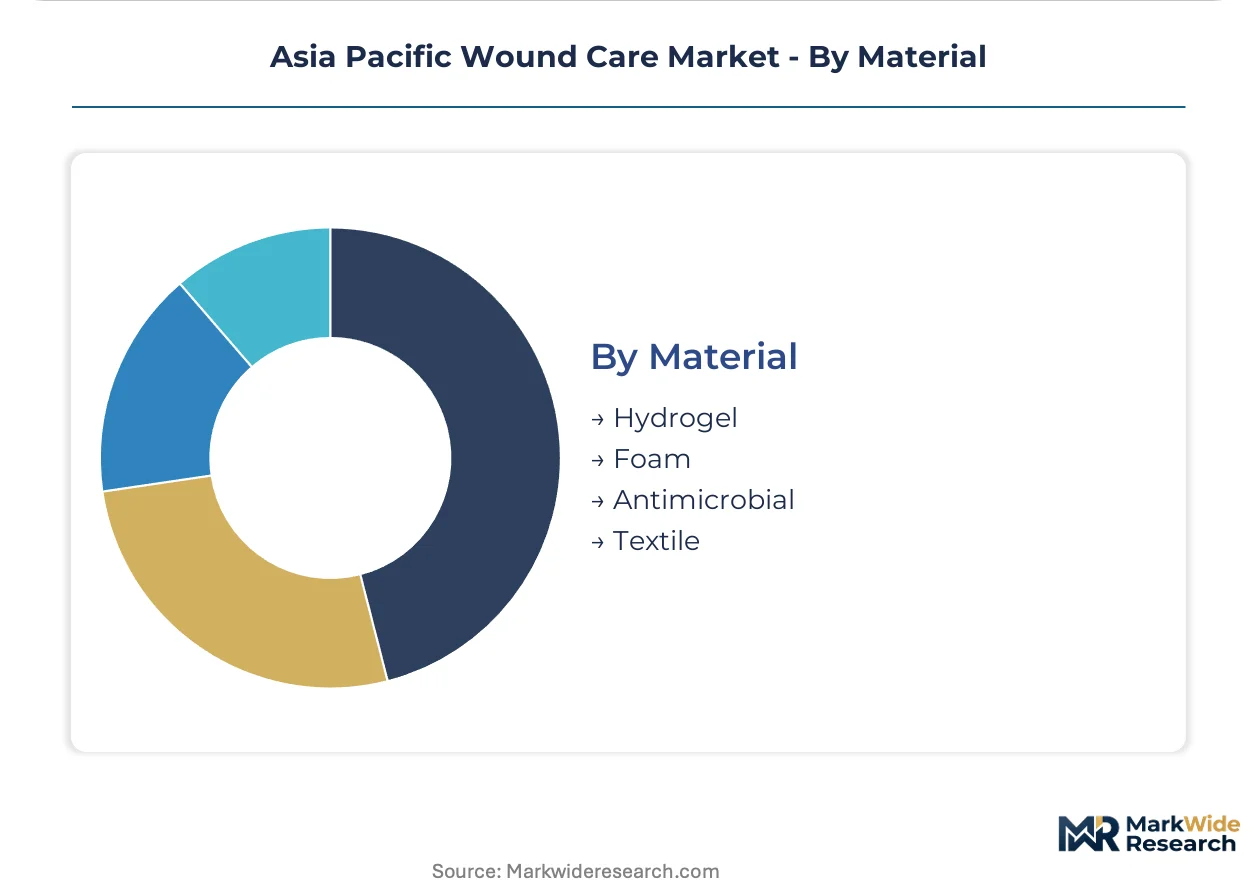
Material:
Raw material selection increasingly reflects environmental compliance costs alongside clinical performance specifications.
- Hydrogel:Enzymatically degradable polymer backbones are restructuring sourcing priorities as Japan's MEE biodegradability mandates create guaranteed demand pull. Water-retentive properties accelerate tissue regeneration in partial-thickness wounds.
- Foam:Polyurethane constructions with embedded silver ions dominate post-operative protocols. Petrochemical feedstock volatility in Northeast Asian naphtha-cracker output exposes margin structures to propylene oxide derivative pricing swings.
- Antimicrobial:Silver-ion and alternative biocide integration prevents infection across high-risk wound categories.
- Textile:Woven and non-woven substrates provide structural support for composite dressing constructions.
Foam holds manufacturing scale. Hydrogel is rotating up the share rankings on regulatory-driven formulation shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and homecare nursing networks concentrate purchasing power across five Asia Pacific markets. Each jurisdiction imposes distinct regulatory pathways that reshape competitive access and product formulation priorities.
China
Recombinant growth factor demand accelerates through Shanghai and Guangzhou clinical trial hubs. NMPA priority review channels compress registration timelines for domestic biologics developers. Yangtze River Delta medical device clusters attract multinational manufacturing relocation to capture accelerated pathway access.
Japan
Long-term care facilities pilot smart dressing systems with pH-sensitive monitoring capabilities. MEE biodegradability mandates for medical waste disposal force hydrogel manufacturers toward enzymatically degradable polymer backbones. Kanto region tertiary centers unbundle clinical training from device procurement contracts.
India
Private hospital chains in Mumbai and Pune expand advanced dressing penetration that trails southern metros. CDSCO local clinical validation requirements extend registration timelines for imported wound therapy devices. Western state nursing networks develop homecare monitoring protocols for post-discharge diabetic foot cases.
Australia
Metropolitan periphery nurse-led residential services drive portable negative pressure system demand. TGA biocompatibility testing requirements filter imported dressing qualifications. Victoria and New South Wales hospital purchasing committees treat clinical education as separately negotiated service lines.
South Korea
Aging suburban populations expand subscription-based dressing replenishment through telemedicine-nursing platforms. MFDS regulates medical device quality management systems for imported advanced wound care products. Seoul Capital Area procurement networks require UDID-compliant serialization integration.
Asia Pacific Wound Care Market Competitive Landscape
Player mix skews toward diversified medical device conglomerates with wound care as a vertical segment. Market structure concentrates around three to five quality-certified multinationals serving premium hospital tiers. Strategic archetypes include Swedish manufacturing heritage positioning, specialized negative pressure therapy focus, and advanced ostomy-drainage portfolio differentiation. Dominant competitive moves encompass clinical trial relocation to capture accelerated regulatory pathways and backward integration into biodegradable hydrogel raw material sourcing.
Within the heritage-manufacturing tier, Mölnlycke Health Care represents premium positioning sustained through tertiary center relationships. Smith & Nephew occupies a position exemplifying specialized therapy system anchoring across regional hospital networks. ConvaTec Group sits within the diversified portfolio archetype, with its corporate structure supporting aging demographic-focused product development.
| Leading Market Players |
|---|
| Mölnlycke Health Care |
| Baxter International |
| 3M |
| Medline Industries |
| B. Braun |
| Smith & Nephew |
| Coloplast Group |
| Cardinal Health |
| ConvaTec Group |
| Others |
Pricing and Supply Chain Analysis
Polyurethane foam manufacturing scale in Northeast Asian petrochemical complexes anchors cost structures across the Asia Pacific wound care supply base, concentrating margin leverage among integrated producers while compressing price floors for non-integrated dressing assemblers.
Pricing Analysis
Cost-plus contracts with naphtha-cracker indexation dominate raw material procurement for foam substrate producers. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked advanced dressings from hospital formulary generics and unbranded commodity alternatives. Pricing pressure stems from propylene oxide derivative volatility, forcing margin compression in mid-tier antimicrobial foam segments. Homecare nursing networks exhibit highest price sensitivity due to reimbursement caps, while Japanese tertiary centers prioritize clinical outcomes documentation over unit cost.
Supply Chain Analysis
Japan and South Korea anchor enzymatically degradable hydrogel polymer production under MEE biodegradability mandates. Raw material sourcing draws from acrylic acid derivatives, superabsorbent polymer granules, and medical-grade adhesive resins. Single-source vulnerability concentrates in specialty biocide supply for silver-ion integration. Distribution runs through hospital group purchasing organizations and specialized wound care distributors serving homecare networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific wound care market tracks a cyclical recovery pattern as hospital capital expenditure cycles normalize and post-pandemic surgical backlogs clear through tertiary care networks.
For Market Incumbents: Secure backward integration into biodegradable hydrogel raw material sourcing to capture Japan's MEE-driven formulation shifts. Deepen hospital formulary lock-in through bundled clinical training contracts that emerging pure-equipment vendors cannot match. Counter telemedicine-nursing platform entrants by embedding smart dressing connectivity into existing negative pressure therapy system architectures. For New Entrants and Emerging Players: Lead with underpenetrated western India demand whitespace where Mumbai and Pune private hospital chains trail southern metros in advanced dressing adoption. Target subscription-based replenishment models for Australian metropolitan periphery homecare networks. Anchor initial positioning through specialized distribution partnerships rather than direct hospital procurement committee engagement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart dressing technology developers with telemedicine platform integration. Five-to-ten year viability favors acquisition targets possessing NMPA accelerated pathway access for recombinant growth factor portfolios. Monitor CDSCO registration timeline compression as inflection signal for imported device competitive access dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Hydrogel Formulation Investment | Japan's MEE mandates create guaranteed demand pull for enzymatically degradable polymer backbones. |
| NMPA Accelerated Pathway Access | Domestic clinical trial relocation captures priority review channels for recombinant growth factor products. |
| Telemedicine-Nursing Platform Integration | Remote wound imaging combined with nurse dispatch enables subscription-based dressing replenishment models. |
| Western India Distribution Partnership | Mumbai and Pune private hospital chains expand advanced dressing penetration lagging southern metros. |
| CE Marking to EU MDR Documentation Recertification | Notified body consolidation under stricter European oversight raises compliance barriers for quality leaders. |
Research Methodology
Desk research of hospital procurement databases, GPO contracts, and regulatory filing precedents preceded structured interviews with hospital purchasing committee members, biomedical engineers, wound care specialist nurses, and distribution channel managers. Secondary validation incorporated TGA biocompatibility testing records, CDSCO registration timelines, and NMPA priority review pathway documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Variance decomposition across product type, end user channel, application severity, and material composition dimensions structured the quantitative framework. CAGRs derived from logistic adoption curves fitted to historical penetration data and forward-projected regulatory catalyst timelines. Forecast inputs incorporated diabetes prevalence trajectories, surgical procedure volume recovery patterns, and homecare nursing workforce expansion rates.
The analysis sits within stated boundaries; outcomes outside sustained hospital capital expenditure recovery or accelerated CDSCO review streamlining would require recalibration. Forecasts reflect documented assumptions regarding regulatory harmonization progress and petrochemical feedstock price stabilization. Recalibration cycles align with material shifts in NMPA biologics pathway access and MEE enforcement stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Care Biologics Market
Wound Care
Wound Closure Devices Market
Wound Care
Foam Dressing Market
Wound Care
Belgium and Netherlands Advanced Wound Care Market
Wound Care
Decubitus Ulcer Treatment Products Market
Wound Care
Global Silver Wound Dressing Market
Wound Care
Burn Care Centers Market
Wound Care
Bioactive Wound Management Market
Wound Care
Topical Wound Agents Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Pressure Bandages Market
Wound Care
Global Negative Pressure Wound Therapy (NPWT) Devices Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Europe Wound Care Market
Wound Care
Gauze Bandage Rolls Market
Wound Care
North America Advanced Wound Care Market