
 Asia-Pacific Antimicrobial Susceptibility Testing Market | 2026-2036
Asia-Pacific Antimicrobial Susceptibility Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Antimicrobial Susceptibility Testing Market Outlook
Hospital procurement consortia is rewriting distribution economics across the Asia-Pacific Antimicrobial Susceptibility Testing landscape. bioMérieux SA leverages its installed base of automated platforms to sustain recurring consumable revenue in tertiary hospitals. Becton, Dickinson and Company anchors its position through integrated specimen-to-result workflows that reduce laboratory turnaround times. Danaher Corporation competes by extending its life sciences instrumentation portfolio into antimicrobial resistance surveillance networks.
Antimicrobial susceptibility testing encompasses laboratory methods that determine bacterial or fungal sensitivity to specific antimicrobial agents, employing broth microdilution, disk diffusion, or automated optical detection to generate minimum inhibitory concentration values that guide therapeutic selection. Phenotypic testing dominates current volumes while genotypic testing captures accelerated growth as hospitals adopt rapid molecular resistance profiling for bloodstream infections. Automated systems command the largest product-type revenue pool, though consumables generate the steadiest margin profile through recurring replenishment cycles tied to installed instrument bases.
Japan's PMDA, China's NMPA, and India's CDSCO enforce divergent premarket approval pathways that fragment product registration timelines and complicate pan-regional launches for instrument manufacturers. Australia's TGA and South Korea's MFDS impose additional quality-management standards on in-vitro diagnostic devices, further segmenting compliance burdens. Stakeholders must monitor evolving harmonization talks between ASEAN medical device directives and national pharmacopeia updates to anticipate where regulatory convergence might unlock cross-border tender participation.
Market Dynamics
Hospital consolidation across China is virtualizing laboratory procurement through centralized tendering platforms that compress vendor margins while demanding integrated specimen-to-result workflows from antimicrobial susceptibility testing suppliers.
Growth Catalysts
- CDSCO diagnostic accuracy mandates:India's tightened AST standards force clinical laboratories to upgrade from manual disk diffusion to automated phenotypic systems, creating replacement demand across tertiary and district hospitals.
- Multidrug-resistant organism surveillance networks:National health agencies in Japan and South Korea mandate participation in centralized resistance databases, requiring compatible AST instrumentation with standardized data export protocols.
- Centralized laboratory investment:China's hospital group purchasing organizations aggregate demand for high-throughput automated platforms, reducing per-test costs through volume-based consumable contracts.
Market Restraints
- Instrument capital intensity:Automated AST systems require substantial upfront investment that district-level hospitals in Indonesia and Vietnam cannot absorb without concessional financing.
- Consumable import dependency:Specialized AST panels and reagents concentrate manufacturing in Western supply bases, exposing Asia-Pacific laboratories to currency fluctuation and shipping disruption.
- Genotypic-phenotypic correlation gaps:Rapid molecular resistance profiling detects genetic markers without confirming phenotypic expression, creating therapeutic guidance uncertainty for bloodstream infections.
Strategic Opportunities
- Philippines and Vietnam expansion:Underpenetrated hospital laboratory infrastructure in these markets offers first-mover positioning as public health budgets expand diagnostic capacity.
- Point-of-care AST integration:Convergence of microfluidic sample preparation with smartphone-based optical readout enables decentralized testing in rural clinics without permanent laboratory facilities.
- ASEAN medical device directive harmonization:Ongoing regulatory convergence discussions may unlock cross-border tender participation, reducing redundant registration costs for instrument manufacturers.
Industry Challenges
- Clinical microbiologist shortage:Specialized training programs in India and Indonesia cannot produce sufficient personnel to operate and interpret automated AST systems at required scale.
- Legacy LIS integration complexity:Hospital information systems in Japan and Australia use proprietary data architectures that resist seamless connectivity with new AST platforms, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Antimicrobial Susceptibility Testing Market |
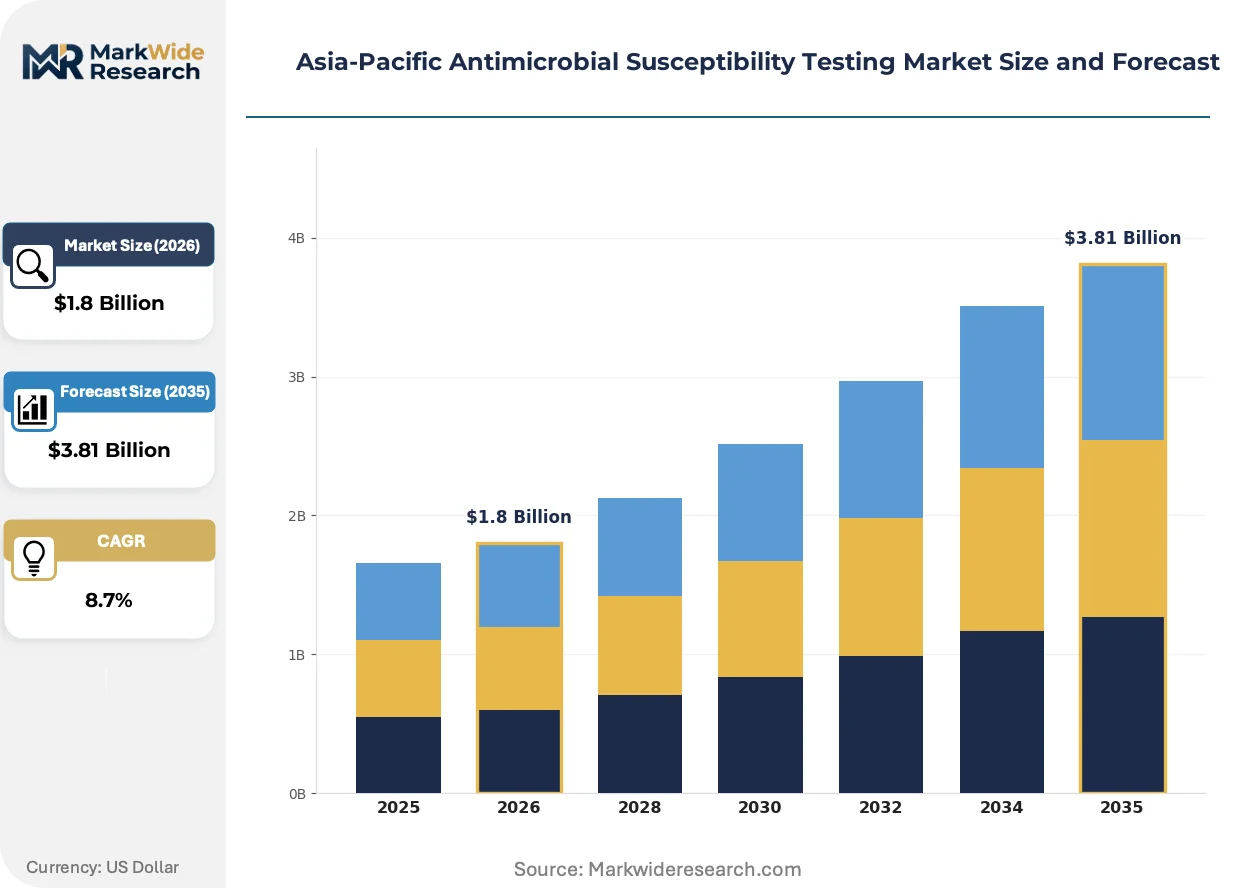
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Systems, Consumables, Software Technology: Phenotypic Testing, Genotypic Testing, Mass Spectrometry, Optical Imaging End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Public Health Organizations Delivery Mode: On-Site Testing, Off-Site Testing, Remote Monitoring, Cloud-Based Solutions |
| Companies Covered | bioMérieux SA, Becton, Dickinson and Company, Thermo Fisher Scientific Inc., Danaher Corporation, Bio-Rad Laboratories, Inc., Zhuhai DL Biotech Co., Ltd., Synbiosis, Bruker Corporation, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Antimicrobial Susceptibility Testing Market Strategic Shifts
Digital specimen tracking and artificial intelligence-assisted resistance pattern recognition are compressing laboratory turnaround times while reducing interpretation variability across Asia-Pacific clinical networks.
Cloud-based AST data management is virtualizing laboratory quality assurance by enabling real-time resistance surveillance across hospital networks. Tertiary hospitals in China and Japan deploy these platforms to coordinate antibiotic stewardship programs across satellite facilities. This architecture compresses the feedback loop between laboratory detection and clinical pharmacy intervention.
PMDA's tightened post-market surveillance requirements for in-vitro diagnostic devices now mandate adverse event reporting within compressed timelines. Japanese manufacturers must maintain domestic technical support infrastructure that smaller foreign competitors struggle to replicate. The regulation most affects mid-tier automated systems where service network density determines competitive viability.
Consolidated procurement through China's provincial health commissions now bundles AST instrumentation with multi-year consumable supply agreements. Traditional distribution channels face disintermediation as hospital groups negotiate directly with manufacturers for total-cost-of-ownership contracts. This restructuring concentrates purchasing power in the hands of procurement consortia spanning Beijing, Shanghai, and Guangdong hospital networks.
Asia-Pacific Antimicrobial Susceptibility Testing Market Segmentation
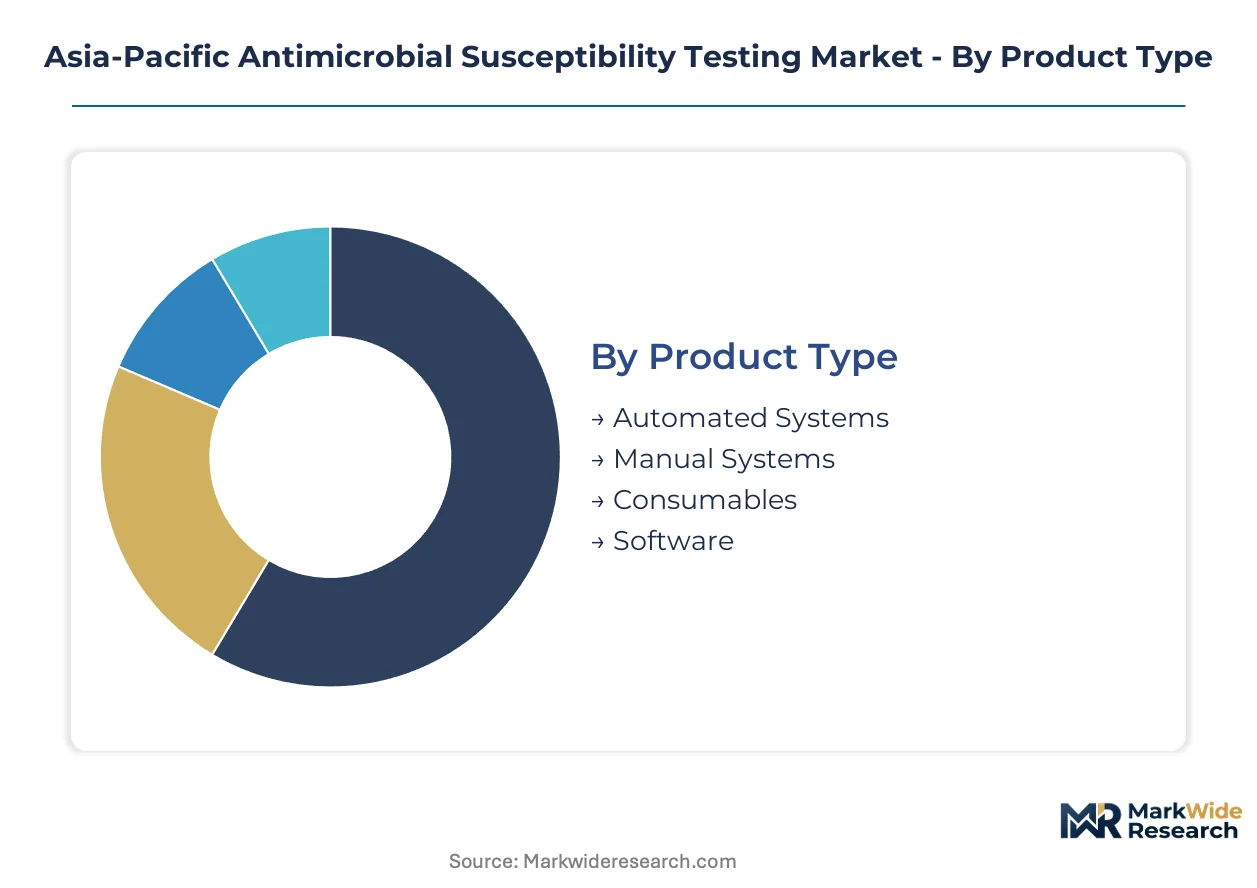
Antimicrobial susceptibility testing segments differ sharply in replacement velocity. Consumables turn monthly while automated systems lock hospitals into seven-year depreciation cycles. Understanding these temporal patterns shapes vendor revenue forecasting and working capital requirements across the Asia-Pacific laboratory supply chain.
Product Type:
Consumables rotate fastest through hospital procurement channels, while automated platforms anchor long-term vendor relationships through captive reagent contracts.
- Automated Systems:Integrated specimen-to-result platforms employ optical detection and robotic sample handling to generate minimum inhibitory concentrations. China's provincial hospital consortia concentrate procurement of these systems in Beijing, Shanghai, and Guangdong networks, bundling multi-year consumable supply agreements that compress distributor margins.
- Consumables:AST panels, reagent cartridges, and quality control organisms require monthly replenishment tied to installed instrument bases. India's CDSCO tightened diagnostic accuracy standards force laboratories to upgrade panel specifications, accelerating replacement cycles in tertiary and district hospitals.
- Manual Systems:Disk diffusion and broth microdilution kits serve resource-constrained facilities in Indonesia and Vietnam.
- Software:Laboratory information system modules manage resistance data export and surveillance network compliance.
Consumables dominate recurring revenue streams. Automated systems concentrate where capital budgets allow integrated workflow investment.
Technology:
Phenotypic methods retain volume leadership while genotypic approaches command premium positioning for rapid bloodstream infection diagnosis.
- Phenotypic Testing:Broth microdilution and disk diffusion generate minimum inhibitory concentration values through direct bacterial growth observation. Japan's PMDA mandates these methods for regulatory compliance in hospital accreditation, sustaining installed base protection across tertiary facilities.
- Genotypic Testing:PCR and nucleic acid amplification detect resistance gene markers within hours rather than days. South Korea's MFDS surveillance network requirements drive hospital adoption for carbapenem-resistant organism screening, though phenotypic correlation gaps create therapeutic guidance uncertainty.
- Mass Spectrometry:MALDI-TOF platforms accelerate species identification preceding susceptibility testing.
- Optical Imaging:Smartphone-based readout systems enable decentralized resistance profiling in rural clinic settings.
Phenotypic testing anchors regulatory compliance. Genotypic testing is where expansion concentrates for rapid turnaround applications.
End User:
Clinical laboratories generate the steadiest demand profile while public health organizations drive non-recurring surveillance instrumentation.
- Clinical Laboratories:Hospital-based and reference laboratories process routine diagnostic specimens requiring continuous AST capacity. China's hospital consolidation into group purchasing organizations aggregates demand for high-throughput automated platforms with standardized data protocols.
- Public Health Organizations:National resistance surveillance programs in Japan and South Korea mandate standardized AST instrumentation with centralized data export capabilities. Australia's TGA quality-management standards impose additional validation requirements on devices deployed in these networks.
- Research Institutions:Academic medical centers evaluate novel resistance mechanisms and therapeutic candidates.
- Pharmaceutical Companies:Drug developers employ AST for clinical trial endpoint microbiology and new agent profiling.
Clinical laboratories dominate installed base. Public health surveillance networks represent the fastest-growing trajectory for standardized platform deployment.
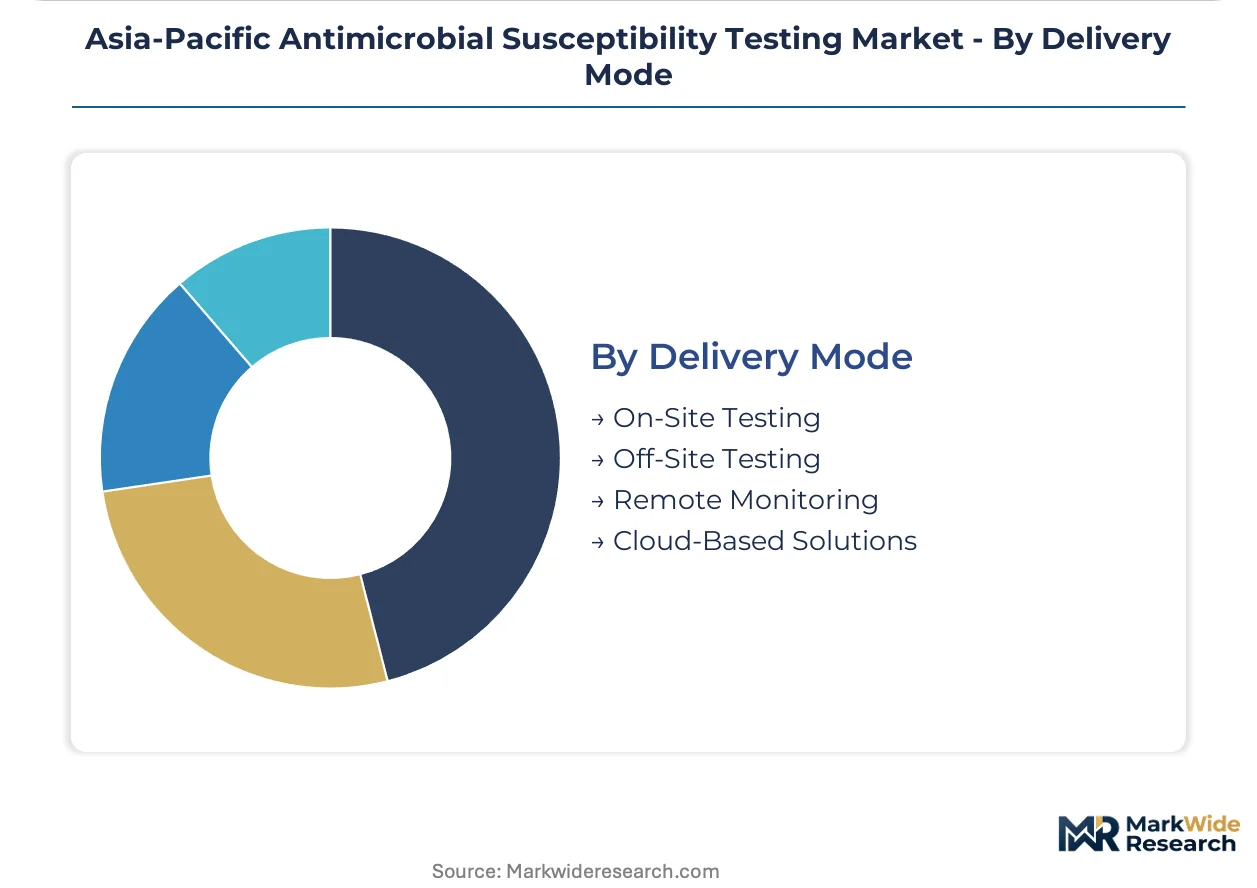
Delivery Mode:
On-site testing retains workflow integration advantages while cloud architectures compress quality assurance feedback loops across hospital networks.
- On-Site Testing:Permanent laboratory infrastructure processes specimens within hospital facilities, maintaining chain of custody and rapid turnaround for critical care applications. Japan's PMDA post-market surveillance requirements favor domestic service networks supporting these installed systems.
- Cloud-Based Solutions:Centralized data management platforms enable real-time resistance surveillance across satellite facilities. Tertiary hospitals in China deploy these architectures to coordinate antibiotic stewardship programs, compressing detection-to-intervention timelines.
- Off-Site Testing:Reference laboratories absorb overflow capacity from hospital-based facilities.
- Remote Monitoring:Telemedicine-linked AST supports rural clinic access without permanent laboratory investment.
On-site testing dominates installed base. Cloud-based solutions are where expansion concentrates for network coordination applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China's consolidated hospital consortia while Indonesia's fragmented laboratory base absorbs margin compression from import-dependent consumable sourcing. Japan and South Korea sustain premium positioning through regulatory-mandated quality tiers. India's diagnostic accuracy mandates reshape procurement across tiered hospital networks.
China
Provincial health commissions in Beijing, Shanghai, and Guangdong bundle automated AST platforms with multi-year consumable contracts through centralized tendering platforms. NMPA's tightened in-vitro diagnostic device standards accelerate replacement cycles in tertiary hospitals. Yangtze River Delta laboratory networks deploy cloud-based resistance surveillance architectures to coordinate antibiotic stewardship across satellite facilities.
Japan
PMDA post-market surveillance requirements compress adverse event reporting timelines and mandate domestic technical support infrastructure for automated systems. Tokyo-Osaka hospital clusters prioritize integrated specimen-to-result workflows that reduce laboratory turnaround times. Kanto region tertiary facilities anchor demand for phenotypic testing platforms that satisfy regulatory compliance mandates.
India
CDSCO diagnostic accuracy standards force district and tertiary hospitals to upgrade from manual disk diffusion to automated phenotypic systems. Maharashtra and Karnataka laboratory networks face clinical microbiologist shortages that constrain system utilization rates. Delhi-NCR hospital procurement aggregates demand for standardized AST instrumentation with compatible data export protocols.
South Korea
MFDS surveillance network participation mandates standardized AST instrumentation with centralized resistance database connectivity. Seoul Capital Area hospital groups invest in genotypic testing platforms for rapid carbapenem-resistant organism screening. Busan-Ulsan clinical laboratories balance phenotypic correlation requirements against molecular turnaround advantages for bloodstream infections.
Australia
TGA quality-management standards impose additional validation requirements on AST devices deployed in public health surveillance networks. New South Wales and Victoria hospital laboratories prioritize integrated workflows that compress detection-to-intervention timelines. Sydney-Melbourne tertiary centers deploy cloud-based architectures to coordinate resistance data across regional satellite facilities.
Asia-Pacific Antimicrobial Susceptibility Testing Market Competitive Environment
Integrated-system specialists and consumable-focused suppliers split the market through divergent capital-deployment strategies. bioMérieux SA leverages installed bases to sustain recurring revenue through captive reagent contracts. Becton, Dickinson and Company anchors positioning through specimen-to-result workflow integration. Danaher Corporation extends life sciences instrumentation into resistance surveillance networks. Tier-one players defend margin positions through multi-year hospital consortia agreements while mid-tier competitors compete on provincial tender participation.
Among the integrated-system archetype, bioMérieux SA and Becton, Dickinson and Company exemplify platform-centric positioning that locks hospitals into long-term consumable replenishment cycles. Danaher Corporation represents the diversification vector, extending analytical instrumentation expertise into antimicrobial resistance surveillance applications. Thermo Fisher Scientific Inc. occupies a position spanning reagent supply and analytical platforms. Zhuhai DL Biotech Co., Ltd. exemplifies regional specialist positioning within China's domestic procurement frameworks. Bruker Corporation and Bio-Rad Laboratories, Inc. anchor the precision-detection tier through mass spectrometry and optical imaging technologies.
| Leading Market Players |
|---|
| bioMérieux SA |
| Becton, Dickinson and Company |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Bio-Rad Laboratories, Inc. |
| Zhuhai DL Biotech Co., Ltd. |
| Synbiosis |
| Bruker Corporation |
| F. Hoffmann-La Roche Ltd |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in automated phenotypic system manufacturing across Western supply bases tightens vendor pricing power while forcing Asia-Pacific laboratories into long-term consumable contracts that lock in cost structures regardless of currency fluctuation.
Pricing Analysis
Configured-to-order pricing for integrated specimen-to-result platforms commands substantial premiums over standard automated systems. Contract-based long-term offtake dominates hospital procurement through China's provincial consortia, with price differentiation driven by NMPA certification tier and volume scale. Cost compression in mid-tier systems intensifies as district hospitals in Indonesia and Vietnam demand concessional financing. Public health surveillance networks exhibit lowest price sensitivity due to regulatory mandate compliance requirements.
Supply Chain Analysis
Contract manufacturing of AST panels and reagent cartridges concentrates in Germany, the United States, and Japan. Specialized optical detection components and quality control organisms draw from precision instrumentation hubs in Switzerland and the Netherlands. Single-source vulnerability runs through proprietary panel formulations that resist dual-sourcing. Distribution runs through manufacturer-direct hospital consortia agreements that disintermediate traditional laboratory supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where switching costs embedded in seven-year instrument depreciation cycles and captive consumable contracts protect incumbent positions against displacement.
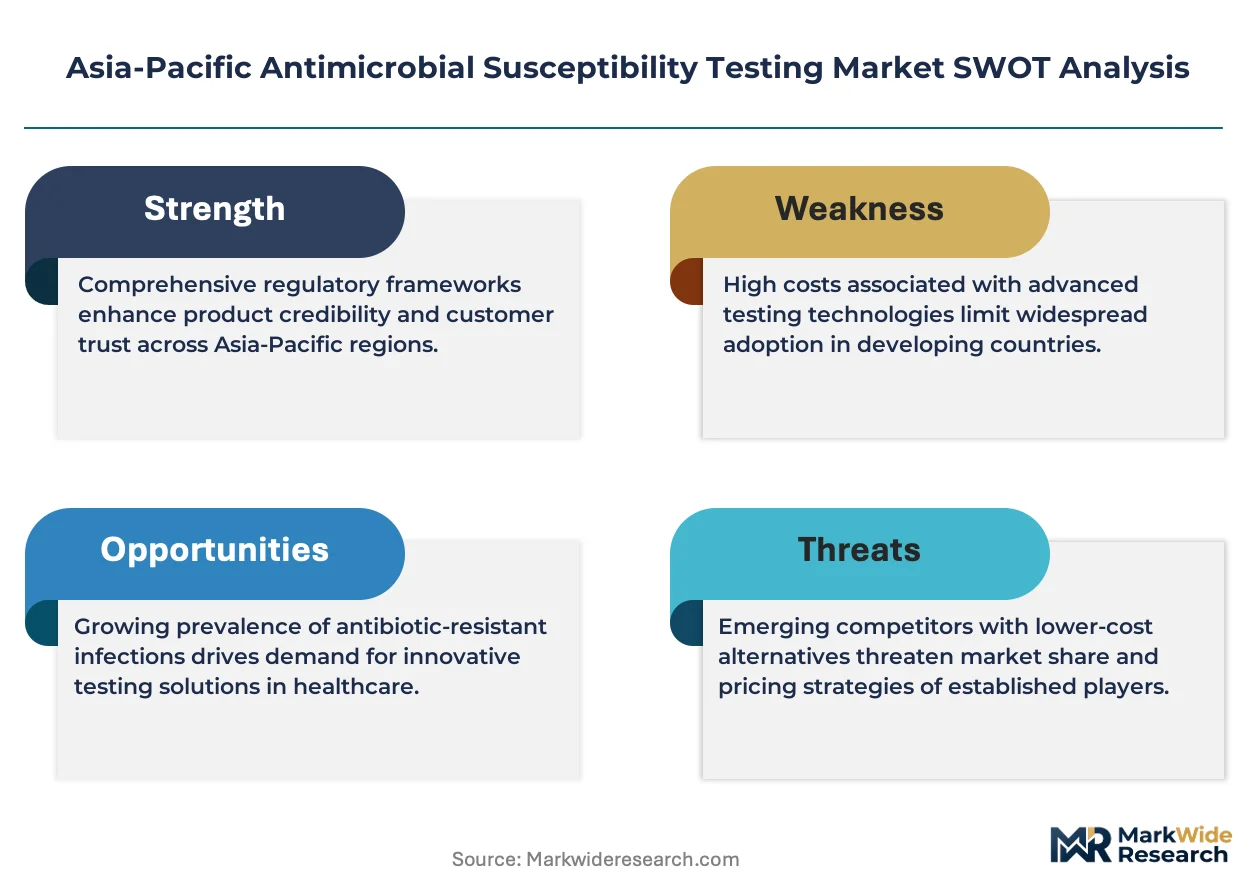
For Market Incumbents: Insulate installed base positions by deepening backward integration into reagent panel manufacturing and securing NMPA premarket approval for next-generation optical detection modules. Genotypic testing platforms threaten phenotypic volume retention as South Korean hospitals adopt rapid molecular screening. Channel control through direct procurement consortia relationships represents the critical defensive lever. For New Entrants and Emerging Players: Build out point-of-care AST capabilities for rural clinic deployment in Vietnam and the Philippines where permanent laboratory infrastructure remains underdeveloped. Smartphone-based optical readout systems offer the most penetrable white-space entry vector. Partnership with provincial health commissions for pilot tender participation provides the essential go-to-market pathway. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among consumable-focused suppliers with captive instrument installed bases. Long-term viability centers on regulatory entrenchment across multiple national pharmacopeia frameworks. Acquisition targets should display established CDSCO, PMDA, or NMPA registrations with domestic technical support infrastructure. Cloud-based resistance surveillance adoption rates signal inflection timing for platform replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Consumable Contract Securement | Locks hospital consortia into recurring revenue streams across Beijing, Shanghai, and Guangdong networks. |
| NMPA Premarket Approval Pathway | Accelerates platform replacement cycles in China's tertiary hospitals facing tightened diagnostic standards. |
| Point-of-Care Microfluidic Development | Enables decentralized testing access for rural clinics in Vietnam and Philippines without laboratory infrastructure. |
| Cloud-Based Surveillance Integration | Coordinates antibiotic stewardship programs across China's Yangtze River Delta hospital satellites. |
| Clinical Microbiologist Training Partnership | Addresses personnel shortages constraining system utilization in India's Maharashtra and Karnataka laboratory networks. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of CDSCO device registration databases, PMDA adverse event reporting systems, and NMPA in-vitro diagnostic approval records. Clinical microbiologists, hospital procurement committee members, biomedical engineers, and GPO contracts managers provided operational perspective. Bottom-up instrument installation tracking triangulates against top-down market sizing from customs import data and manufacturer revenue disclosures.
Forecast inputs span phenotypic versus genotypic technology mix, automated versus manual system penetration, and clinical laboratory versus public health end-use segmentation across the analysis window. CAGRs derive from logistic adoption curves fitted to regulatory mandate implementation timelines and hospital capital budget cycle patterns. Resistance surveillance network participation mandates and provincial tender platform consolidation serve as primary demand drivers in the quantitative framework.
Stress conditions across currency fluctuation, shipping disruption, and clinical microbiologist supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NMPA harmonization progress and ASEAN medical device directive convergence. Quarterly review of provincial tender award announcements and CDSCO diagnostic accuracy standard updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Adiponectin Testing Market
Testing Services
Global Newborn Screening Market
Testing Services
Infusion Toxicology Services Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
CRO Mass Spectroscopy Services Market
Testing Services
US & Europe Extractable and Leachable Testing Services Market
Testing Services
Nucleic Acid Amplification Testing Market
Testing Services
Passive Dosimetry Equipment and Service Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
Middle East and Africa IVD Regulatory Affairs Outsourcing Market
Testing Services
Home Care Testing Market
Testing Services
Osmometer Market
Testing Services
Global Biological Safety Testing Market
Testing Services
Addison Disease Testing Market
Testing Services
Sports Drug Testing Market
Testing Services
Germany Testing, Inspection and Certification Market