
 Anal Cancer Market | 2026-2036
Anal Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Anal Cancer Market Analysis
The treatment landscape for anal cancer is shifting between premium immunotherapy protocols and commodity chemotherapy regimens as reimbursement frameworks harden around biomarker-directed care. Merck & Co., Inc. leverages its checkpoint inhibitor portfolio to dominate first-line settings where PD-L1 expression guides payer decisions. Bristol-Myers Squibb Company competes through combination strategies that anchor its presence in recurrent disease management. F. Hoffmann-La Roche Ltd differentiates via diagnostic-therapeutic integration, controlling companion testing workflows that precede treatment selection.
Anal cancer comprises malignancies arising from the anal canal epithelium, predominantly squamous cell carcinoma linked to persistent human papillomavirus infection, with staging determined by tumor size, nodal involvement, and metastatic spread using TNM classification. Immunotherapy segments lead value creation as anti-PD-1 agents displace fluorouracil-based regimens in frontline care, while chemotherapy retains volume dominance in resource-constrained settings. End user concentration tilts toward hospitals where multidisciplinary tumor boards coordinate combined modality therapy, though home care administration routes are expanding for maintenance oral agents.
The FDA's breakthrough therapy designation and EMA's priority medicines scheme are reshaping development economics by truncating review timelines for agents demonstrating substantial improvement over existing standards. NCCN guidelines and ESMO clinical practice recommendations directly shape prescriber behavior and national reimbursement decisions across major markets. Stakeholders must monitor evolving biomarker definitions that determine trial eligibility and label expansion opportunities.
Market Dynamics
Checkpoint inhibitor therapy is compressing treatment timelines for anal cancer patients, forcing chemotherapy manufacturers to defend volume through pricing concessions while academic medical centers reconfigure infusion capacity toward immunotherapy administration.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's accelerated pathway truncates clinical development timelines for novel biologics, compressing the gap between phase II evidence and commercial availability.
- HPV Screening Intensification:Tightened cervical and anal cytology protocols in oncology clinics are expanding the addressable patient pool eligible for early intervention.
- Biomarker-Guided Reimbursement:PD-L1 companion diagnostic integration into payer prior-authorization workflows is steering treatment selection toward immunotherapy protocols.
Market Restraints
- Cold Chain Infrastructure:Anti-PD-1 biologics require specialized temperature-controlled distribution networks that concentrate supply control among integrated pharmacy-benefit managers.
- Fluorouracil Input Volatility:Generic chemotherapy API manufacturing concentration in Asian contract manufacturers creates periodic supply disruptions affecting combination regimen availability.
- Specialized Infusion Capacity:Academic medical centers face physical constraints in expanding chair time for extended immunotherapy monitoring protocols.
Strategic Opportunities
- Home Administration Routes:Oral maintenance agents following induction therapy enable channel expansion beyond hospital-based infusion centers into specialty pharmacy networks.
- Multidisciplinary Tumor Board Integration:Radiation oncology coordination with medical oncology creates service bundling opportunities for integrated delivery networks.
- Recurrent Disease Protocols:Second-line settings where chemotherapy resistance emerges represent untapped indication expansion for novel mechanism agents.
Industry Challenges
- Gynecologic Oncology Training Pipeline:Fellowship program output fails to match rising case volumes from HPV-related malignancy incidence, stretching specialist availability.
- Companion Diagnostic Synchronization:PD-L1 assay variability across platform vendors creates biomarker discordance complicating clinical trial enrollment and treatment selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anal Cancer Market |
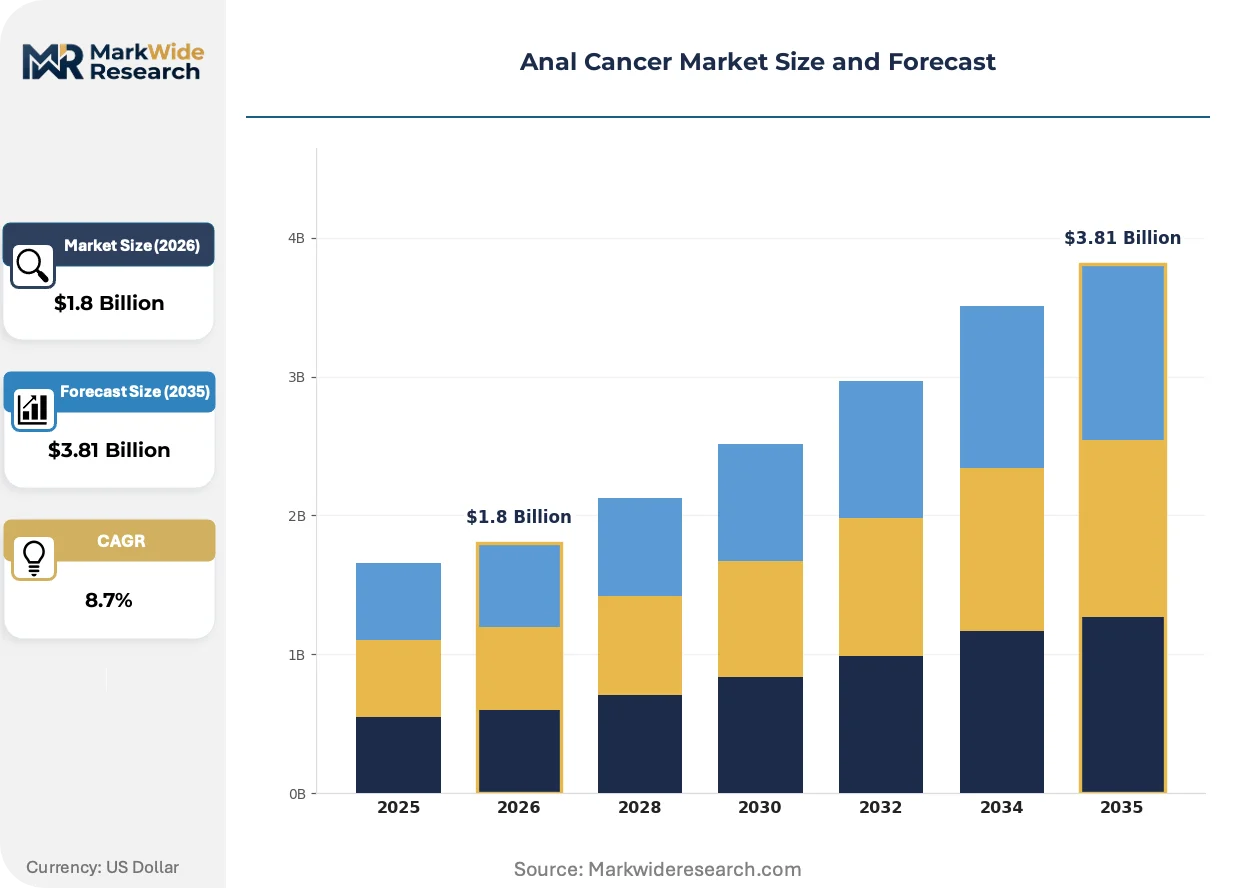
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy End User: Hospitals, Clinics, Research Laboratories, Home Care Treatment Stage: Localized, Advanced, Recurrent, Preventive Administration Route: Intravenous, Oral, Subcutaneous, Topical |
| Companies Covered | Merck & Co., Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, Pfizer Inc., Novartis AG, Sanofi, Amgen Inc., AstraZeneca plc, Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anal Cancer Market Emerging Trajectories
Clinical trial design is pivoting toward biomarker-enriched enrollment criteria, compressing the traditional broad-population approach while molecular profiling platforms proliferate in community oncology settings.
Neoadjuvant immunotherapy protocols are absorbing the preoperative treatment window previously occupied by chemoradiation, enabling pathologic complete response assessment that guides subsequent therapy de-escalation. Surgical oncologists at tertiary centers are adopting this sequencing rapidly, with multidisciplinary tumor boards rewriting standard-of-care pathways around response-adapted strategies. The structural consequence is absorption of radiation oncology capacity into medical oncology scheduling, compressing departmental revenue allocation.
The EMA's priority medicines scheme is truncating marketing authorization review timelines for agents demonstrating substantial improvement over fluorouracil-mitomycin standards, compressing the competitive window for incumbent therapies. European national reimbursement bodies are synchronizing health technology assessment timelines with EMA approval, accelerating patient access. Oncology clinics in Germany and France are restructuring pharmacy formularies around these compressed launch cycles.
Patient advocacy organizations are demanding earlier access to investigational therapies outside clinical trials, pressuring manufacturers to expand compassionate-use programs and early-access schemes. This behavioral shift is disrupting the traditional phase III enrollment funnel as eligible patients seek pre-approval access. The United States exhibits the strongest pressure, with FDA Project Facilitate accelerating single-patient IND processing.
Anal Cancer Market Segmentation
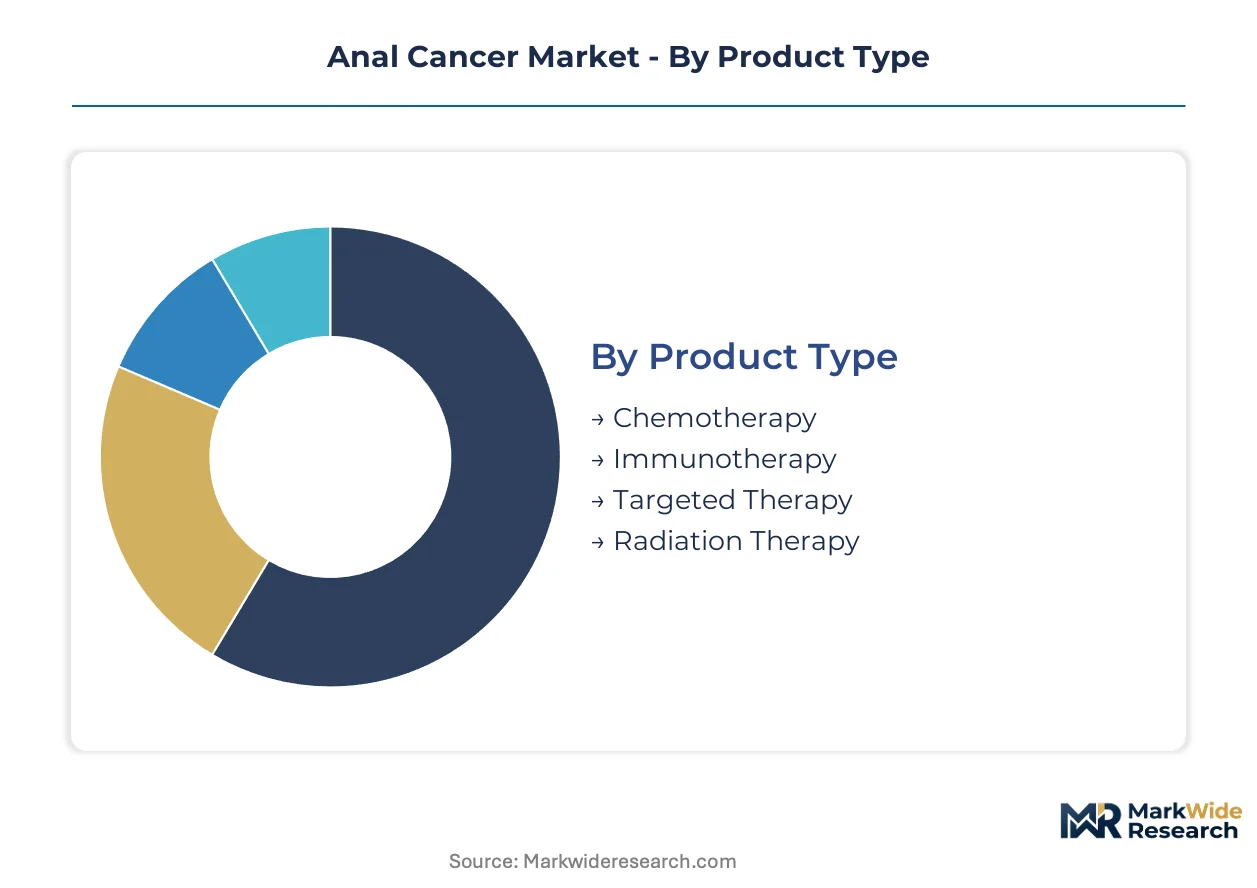
Treatment modality selection in anal cancer hinges on staging precision, biomarker status, and reimbursement alignment across integrated delivery networks. Segmentation reveals how immunotherapy displacement of chemotherapy concentrates value in checkpoint inhibitors while channel economics reshape administration site preferences.
Product Type:
Standalone biologics dominate premium reimbursement tiers while embedded combination regimens anchor volume throughput in community oncology.
- Immunotherapy:Anti-PD-1 antibodies function as standalone systemic agents requiring companion diagnostic qualification before payer authorization. Academic medical centers in the United States concentrate infusion capacity for these protocols as PD-L1 testing integration tightens.
- Chemotherapy:Fluorouracil-mitomycin combinations constitute embedded backbone regimens in chemoradiation protocols. Generic pricing pressure from Asian API manufacturers compresses margin while securing volume in resource-constrained settings.
- Targeted Therapy:EGFR and angiogenesis inhibitors occupy niche recurrent disease applications pending biomarker validation.
- Radiation Therapy:External beam and brachytherapy modalities integrate with systemic agents in combined modality standards.
Chemotherapy leads volumes today; immunotherapy is gaining share fastest.
End User:
Cost tier stratification separates capital-intensive inpatient capacity from ambulatory margin preservation.
- Hospitals:Multidisciplinary tumor boards coordinate combined modality therapy requiring radiation oncology infrastructure and surgical backup. Major United States academic centers anchor phase III enrollment and first-line adoption of breakthrough-designated agents.
- Clinics:Community oncology practices concentrate stable patient monitoring and maintenance therapy administration. United States-based networks expand infusion chair capacity as immunotherapy protocols compress treatment timelines.
- Research Laboratories:Centralized reference labs process PD-L1 companion diagnostics and HPV genotyping for trial eligibility.
- Home Care:Specialty pharmacy networks administer oral maintenance agents following hospital-based induction.
Hospitals lead volumes today; home care is expanding most quickly.
Treatment Stage:
Application urgency determines reimbursement velocity and regulatory pathway selection.
- Localized:Stage I-II disease management employs chemoradiation as curative intent standard. Neoadjuvant immunotherapy protocols are absorbing the preoperative window at tertiary United States centers.
- Advanced:Stage III-IV systemic therapy drives checkpoint inhibitor adoption where PD-L1 expression meets payer thresholds.
- Recurrent:Second-line settings after platinum resistance represent indication expansion targets for novel mechanism agents.
- Preventive:HPV vaccination and high-resolution anoscopy surveillance reduce progression to invasive disease.
Localized disease leads volumes today; recurrent settings show steepest expansion trajectory.
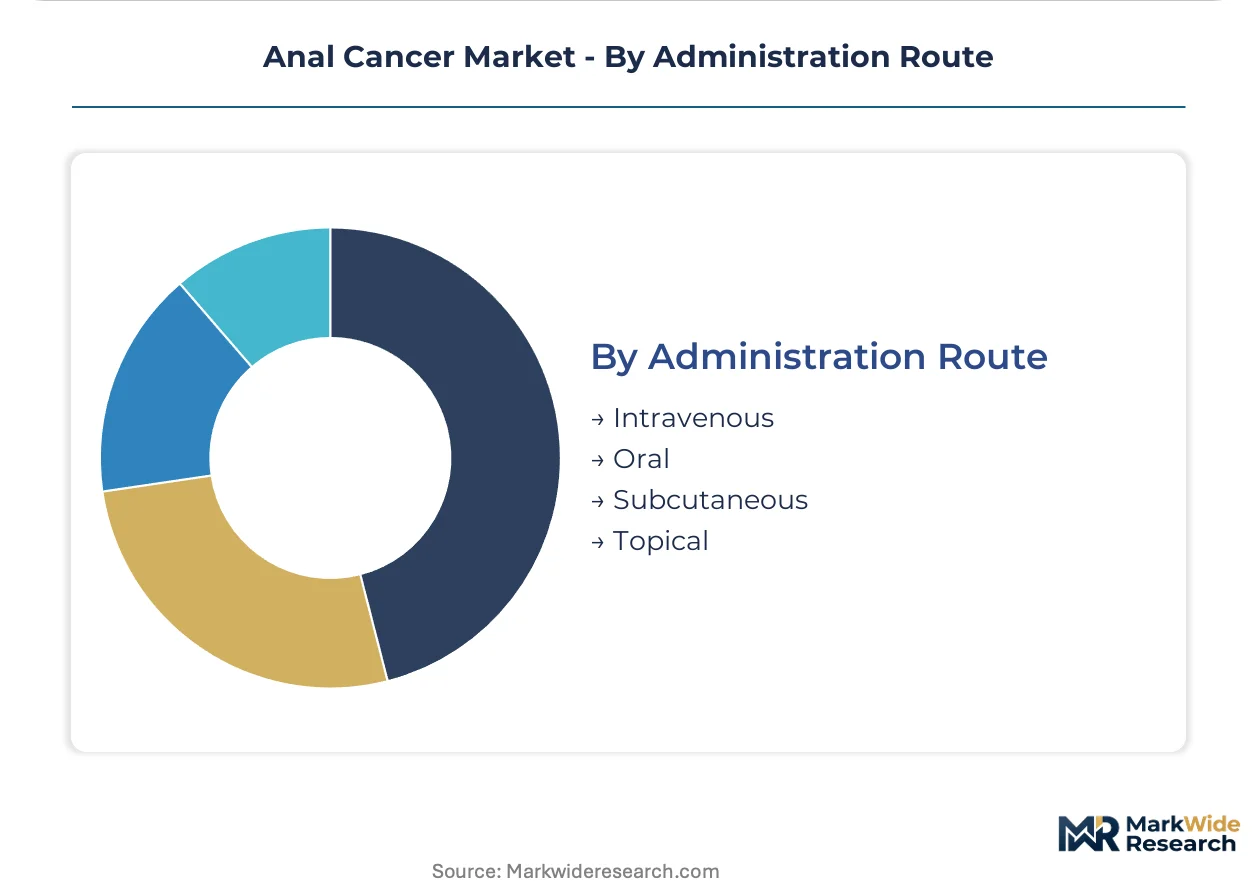
Administration Route:
Supply concentration in cold chain biologics versus commodity oral generics shapes distribution economics.
- Intravenous:Infusion-dependent biologics require temperature-controlled distribution and specialized nursing oversight. United States oncology clinics reconfigure physical capacity to accommodate extended immunotherapy monitoring protocols.
- Oral:Maintenance capecitabine and investigational agents enable channel shift toward specialty pharmacy dispensing.
- Subcutaneous:Limited current application in anal cancer with potential for future immunotherapy formulation.
- Topical:Investigational intralesional delivery for very early-stage or HIV-associated anal intraepithelial neoplasia.
Intravenous administration leads volumes today; oral routes are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates checkpoint inhibitor adoption while Germany accelerates EMA-synchronized reimbursement timelines, creating divergent access velocities across Atlantic markets.
United States
FDA breakthrough therapy designations compress commercialization timelines for anti-PD-1 agents. Academic medical centers in Boston, Houston, and New York anchor phase III enrollment pipelines. The NCCN guideline framework directly shapes commercial payer prior-authorization workflows.
Germany
EMA priority medicines scheme truncates marketing authorization reviews for novel biologics. National health technology assessment bodies synchronize reimbursement decisions with regulatory approval. University hospitals in Munich and Heidelberg restructure pharmacy formularies around compressed launch cycles.
France
ANSM coordinates early-access schemes for investigational therapies outside clinical trials. The HAS assessment framework evaluates incremental clinical benefit for reimbursement listing. Parisian oncology clinics expand immunotherapy infusion capacity amid rising HPV-related case volumes.
United Kingdom
NICE technology appraisals determine NHS England commissioning for systemic therapies. The Cancer Drugs Fund provides interim access pending full cost-effectiveness evaluation. London and Manchester academic centers lead adaptive trial design for neoadjuvant immunotherapy protocols.
Japan
PMDA sakigake designation accelerates review for breakthrough oncology agents. Regional cancer centers in Tokyo and Osaka integrate PD-L1 companion diagnostics into treatment pathways. The Ministry of Health, Labour and Welfare adjusts reimbursement pricing quarterly based on clinical utility assessments.
Anal Cancer Market Vendor Landscape
Top-tier vendors anchor first-line immunotherapy segments, while mid-tier specialists defend chemotherapy backbone positions through pricing concessions. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates controlling diagnostic-therapeutic workflows, biotech-focused innovators pursuing indication expansion, and generic manufacturers securing volume in resource-constrained settings. Dominant competitive moves include strategic partnerships with companion diagnostic platform vendors and geographic expansion into EMA-priority markets.
Within the integrated conglomerate tier, Merck & Co., Inc., Bristol-Myers Squibb Company, and F. Hoffmann-La Roche Ltd exemplify divergent strategic archetypes. Merck occupies a position anchored in frontline checkpoint inhibition where PD-L1 expression thresholds guide payer authorization. Bristol-Myers Squibb represents combination strategy specialization, anchoring presence in recurrent disease management through dual immunotherapy protocols. Roche exemplifies diagnostic-therapeutic integration, controlling companion testing workflows that precede treatment selection decisions across European and North American markets.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Novartis AG |
| Sanofi |
| Amgen Inc. |
| AstraZeneca plc |
| Johnson & Johnson Services, Inc. |
| Others |
Supply Flow & Price Mechanics
Fluorouracil API manufacturing concentration in Asian contract manufacturers flows through to chemotherapy backbone pricing tiers, while cold chain biologics for anti-PD-1 agents command premium reimbursement bands tied to companion diagnostic qualification.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for generic chemotherapy inputs, compressing margins on fluorouracil-mitomycin regimens. Three-tier pricing structure across premium checkpoint inhibitors, standard chemoradiation protocols, and economy generics separates academic medical center reimbursement from community oncology volume. Pricing pressure stems from biosimilar entry threats in immunotherapy and payer prior-authorization tightening around PD-L1 thresholds. Community oncology practices exhibit highest price sensitivity due to bundled reimbursement constraints, while academic centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
FDA and EMA certification requirements for companion diagnostic synchronization create gating bottlenecks that concentrate qualified supplier networks. Active pharmaceutical ingredient production draws from India, China, and Switzerland, with biologics manufacturing anchored in United States and German facilities. Cold chain distribution for anti-PD-1 agents rests on specialized pharmacy-benefit manager networks, while oral generics flow through standard wholesale channels. Single-source vulnerability in Asian API manufacturing creates periodic disruption risk for combination regimens. Distribution runs through integrated delivery networks for hospital-based infusion and specialty pharmacy networks for maintenance therapy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anal cancer market represents a late-cycle quality story where biomarker-directed care shifts demand toward PD-L1 qualified immunotherapy protocols with premium reimbursement durability.
For Market Incumbents: To counter biosimilar pressure in checkpoint inhibition, Merck and Bristol-Myers Squibb should deepen companion diagnostic platform control through exclusive assay partnerships while expanding infusion capacity at United States academic centers to capture first-line patient volume. Backward integration into PD-L1 testing workflows secures treatment selection influence ahead of payer authorization decisions.
For New Entrants and Emerging Players: Launch via specialty pharmacy networks for oral maintenance agents in the post-induction window, where hospital discharge creates channel disruption opportunity. Recurrent disease settings after platinum resistance offer the most penetrable white space, with neoadjuvant immunotherapy protocols at tertiary centers providing a second entry angle through radiation oncology coordination.
For Investors and Strategic Acquirers: Consolidation pressure builds where diagnostic-therapeutic integration capabilities fragment across mid-tier oncology-focused biotechs. Five-to-ten-year viability favors platforms with FDA breakthrough therapy designation momentum and EMA priority medicines scheme alignment. Acquisition targets should display companion diagnostic control or novel mechanism assets in second-line indication expansion. The signal to watch is NCCN guideline revision timing around neoadjuvant immunotherapy sequencing.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Platform Integration | FDA-qualified PD-L1 assays preceding anti-PD-1 authorization tighten payer control over treatment selection. |
| Neoadjuvant Immunotherapy Protocol Development | Pathologic complete response assessment at tertiary United States centers enables therapy de-escalation strategies. |
| Specialty Pharmacy Network Expansion | Oral maintenance agent distribution beyond hospital infusion centers captures post-induction patient volume. |
| EMA Priority Medicines Scheme Alignment | Compressed European marketing authorization timelines accelerate patient access ahead of national reimbursement. |
| Multidisciplinary Tumor Board Partnership | Radiation oncology coordination with medical oncology creates service bundling for integrated delivery networks. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with oncology drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov enrollment data, and hospital procurement databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market size estimates.
Historical reference periods spanning pre-immunotherapy standard-of-care through current checkpoint inhibitor displacement established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include treatment modality, administration route, disease stage, end-user setting, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating biomarker prevalence shifts, reimbursement policy changes, and clinical trial readout timelines as primary inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under companion diagnostic platform fragmentation or accelerated biosimilar entry conditions. Model outputs reflect documented assumptions around PD-L1 testing penetration and immunotherapy infusion capacity expansion. A model refresh is warranted upon material change in NCCN guideline sequencing or FDA breakthrough therapy designation revocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Global Autoimmune Disease Therapeutics Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Infantile Spasms Therapeutics Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Open Angle Glaucoma Market
Specialty Medicine
Cerebral Vein Thrombosis Treatment Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
Psoriatic Arthritis (Psa) Treatment Market
Specialty Medicine
Global Appendicitis Market