
 Global Herpes Market | 2026-2036
Global Herpes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Herpes Market Foresight
The shift from single-source API procurement to multi-source active pharmaceutical ingredient contracting is restructuring supply security across the herpes therapeutics value chain. GlaxoSmithKline plc leverages captive manufacturing of nucleoside analogs to sustain margin control on established antiviral brands. Pfizer Inc. competes through geographic diversification of its finished-dose supply network, while Gilead Sciences Inc. differentiates via proprietary prodrug platforms that extend patent life cycles.
Herpes comprises a family of double-stranded DNA viruses in the Herpesviridae family, with HSV-1 and HSV-2 representing the predominant human pathogens; acyclovir-class antivirals function through selective phosphorylation by viral thymidine kinase followed by DNA chain termination. The primary commercial purpose spans symptomatic lesion management, suppressive therapy to reduce transmission, and prophylaxis in immunocompromised populations. Oral tablets dominate volume consumption due to decades of clinical familiarity and generic price erosion, while injectable formulations command premium positioning in hospital settings for severe or disseminated infections. Diagnostic kits represent the fastest-expanding segment as molecular PCR platforms displace culture-based methods in clinical laboratories.
FDA review standards for antiviral efficacy endpoints, EMA requirements for pediatric investigation plans, and WHO prequalification protocols for developing-market access collectively shape product development priorities and registration sequencing across manufacturers. These frameworks elevate the cost and duration of clinical programs, filtering the competitive field toward entities with established regulatory infrastructure and cross-jurisdictional submission experience. Stakeholders must monitor the convergence of point-of-care diagnostic authorization pathways with telehealth prescribing regulations, as this interface determines which distribution channels capture patient-initiated care episodes.
Market Dynamics
Accelerated FDA approval pathways for antiviral therapies are compressing development timelines and intensifying competitive pressure on established nucleoside analog manufacturers.
Growth Catalysts
- Telehealth prescribing frameworks:US state-level telehealth regulations are expanding direct-to-consumer access channels for suppressive therapy prescriptions.
- Molecular PCR platform adoption:Clinical laboratories are displacing culture-based diagnostics with nucleic acid amplification technologies.
- Immunocompromised prophylaxis protocols:Hospital formularies are standardizing antiviral prophylaxis in transplant and oncology units.
Market Restraints
- Generic acyclovir price erosion:Decades of patent expiration have collapsed oral tablet margins to commodity levels.
- API supply concentration in China and India:Nucleoside precursor manufacturing clusters in Zhejiang and Gujarat create single-source vulnerability.
- EMA pediatric investigation requirements:Mandatory pediatric study plans extend registration timelines and inflate clinical program costs.
Strategic Opportunities
- WHO prequalification pathways:Developing-market access protocols in sub-Saharan Africa and Southeast Asia remain underpenetrated for branded antiviral entry.
- Prodrug platform extension:Valacyclovir and famciclovir analogs offer patent lifecycle management through improved bioavailability profiles.
- Point-of-care diagnostic integration:Rapid PCR devices are converging with pharmacy-based prescribing workflows in the United Kingdom and Germany.
Industry Challenges
- Cross-jurisdictional submission expertise:Simultaneous FDA, EMA, and PMDA filings require specialized regulatory affairs capabilities that mid-scale developers lack.
- Legacy antiviral resistance surveillance:Thymidine kinase mutant monitoring demands sustained post-market pharmacovigilance investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Herpes Market |
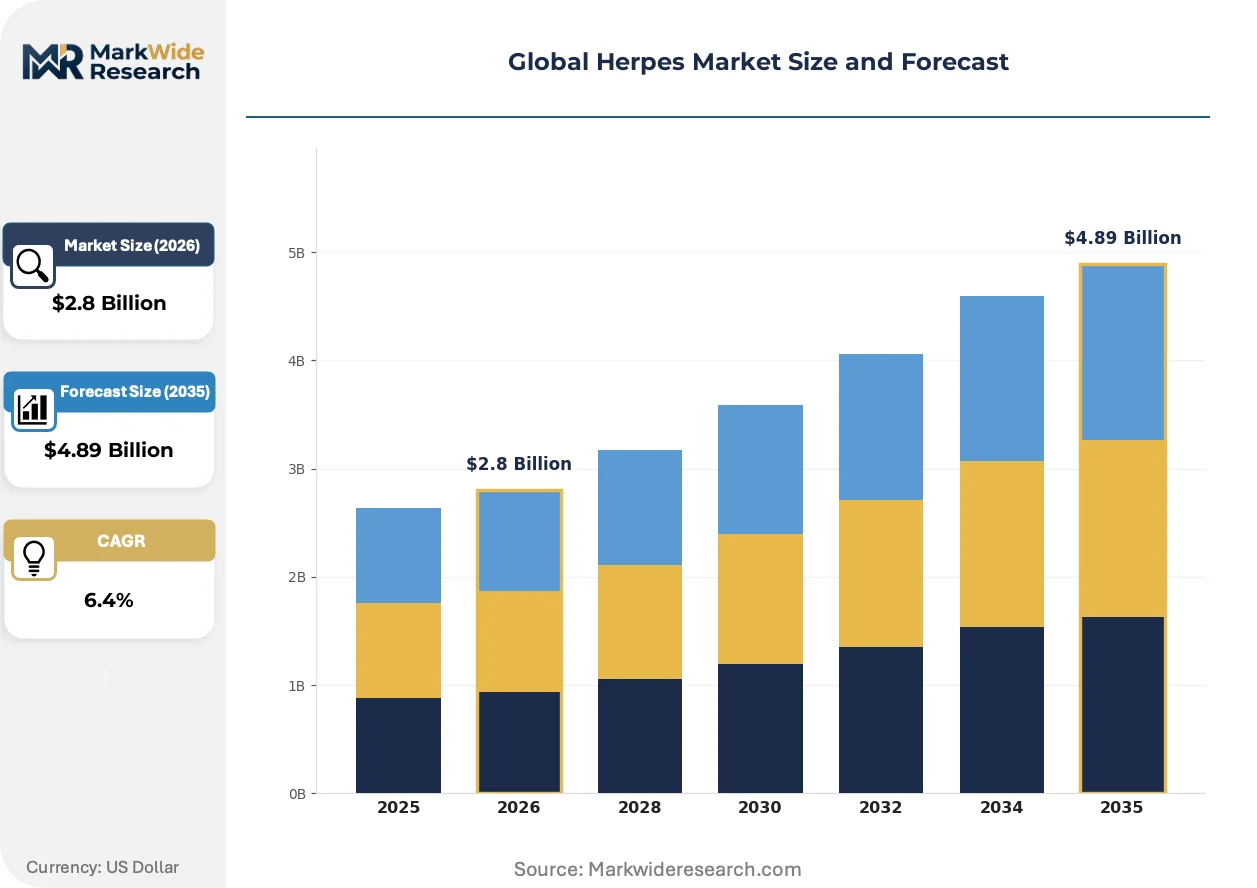
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiviral Creams, Oral Tablets, Injectable Formulations, Diagnostic Kits, Vaccines Therapy Area: Genital Herpes, Oral Herpes, Neonatal Herpes, Herpetic Whitlow, Herpes Encephalitis End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Research Institutes Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Government Healthcare Programs |
| Companies Covered | GlaxoSmithKline plc, Pfizer Inc., Novartis AG, Teva Pharmaceutical Industries Ltd., Viatris Inc., Merck & Co., Inc., Gilead Sciences Inc., Sanofi S.A., Fresenius SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Herpes Market Shifts & Advancements
Antiviral development is pivoting toward mechanism-diverse molecular entities as nucleoside analog saturation intensifies differentiation pressure on pipeline candidates.
CRISPR-based gene editing platforms are unifying latent viral reservoir targeting with host-directed immunomodulation. Academic research consortia in the United States and Switzerland are advancing preclinical candidates through IND-enabling studies. This convergence is unifying previously separate therapeutic modalities into single-administration curative approaches that threaten chronic suppressive therapy models.
The FDA's Project Orphan and Fast Track designations are compressing review timelines for novel antiviral mechanisms. Sponsors with breakthrough therapy status gain rolling review privileges that accelerate commercialization by twelve to eighteen months. Oncology and infectious disease divisions are prioritizing submissions that demonstrate transmission interruption endpoints.
Patients are initiating care episodes through direct-to-consumer platforms before presenting to traditional healthcare settings. Telehealth routing algorithms in the United States and Australia are capturing prescription volume that previously flowed through primary care networks. This channel migration is fragmenting prescriber concentration and forcing manufacturers to maintain parallel medical affairs infrastructures.
Global Herpes Market Segmentation
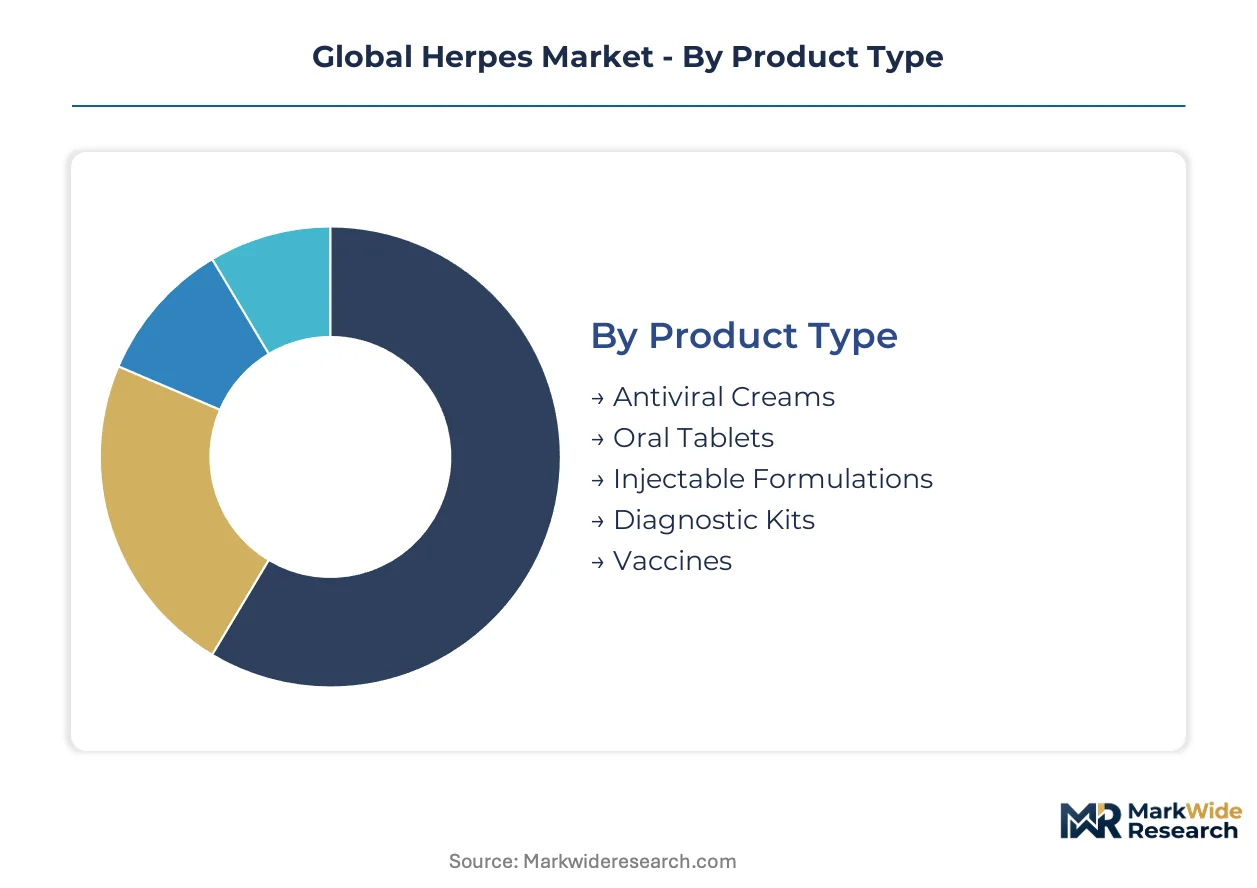
Product differentiation across the herpes therapeutics value chain reflects divergent patient acuity levels, regulatory pathways, and margin structures. Manufacturers must align formulation investments with channel-specific dispensing economics and diagnostic integration timelines.
Product Type:
Cost tier separates chronic suppressive therapy from acute intervention and preventive modalities.
- Antiviral Creams:Topical acyclovir and penciclovir formulations deliver localized lesion management with minimal systemic exposure. Demand concentrates in retail pharmacy channels across Germany and the United Kingdom where patients self-initiate treatment for recurrent oral herpes flares.
- Oral Tablets:Nucleoside analogs in tablet form dominate prescription volume through decades of clinical familiarity and generic price erosion. Volume concentrates in the United States where direct-to-consumer telehealth platforms route patients into suppressive therapy workflows.
- Injectable Formulations:Intravenous acyclovir serves hospitalized patients with disseminated or CNS infections.
- Diagnostic Kits:Molecular PCR platforms displace culture-based methods in clinical laboratories.
- Vaccines:Prophylactic candidates remain in clinical development with no approved products currently available.
Volume sits with oral tablets; growth tilts toward diagnostic kits.
Therapy Area:
Application severity determines whether treatment occurs in ambulatory, emergency, or intensive care settings.
- Genital Herpes:HSV-2 predominance drives suppressive therapy demand among immunocompetent adults. Patient-initiated care through telehealth platforms in Australia and the United States is expanding prescription capture outside traditional primary care networks.
- Oral Herpes:HSV-1 mediated cold sores generate episodic treatment demand with high recurrence rates. Demand clusters in pharmacy-accessible markets including Japan and South Korea where over-the-counter topical availability reduces prescription friction.
- Neonatal Herpes:Perinatal transmission protocols require intravenous antiviral prophylaxis in maternity wards.
- Herpetic Whitlow:Digital HSV infection among healthcare workers demands occupational exposure protocols.
- Herpes Encephalitis:CNS involvement necessitates emergency department intervention with IV formulations.
Oral herpes commands patient volume; genital herpes drives prescription value concentration.
End User:
Customer type dictates procurement sophistication, formulary control, and post-market surveillance obligations.
- Hospitals:Acute care institutions manage severe disseminated infections and immunocompromised prophylaxis protocols. Formulary standardization in transplant and oncology units across France and Italy is embedding antiviral prophylaxis into perioperative care pathways.
- Specialty Clinics:Dermatology and infectious disease practices handle recurrent outpatient management. Telehealth-integrated specialty networks in the United States are compressing time-to-prescription for suppressive therapy initiations.
- Diagnostic Laboratories:Molecular testing facilities process PCR-based HSV identification.
- Research Institutes:Academic medical centers conduct clinical trials for novel antiviral mechanisms and curative gene editing approaches.
Procurement scale sits with hospitals; prescription velocity tilts toward specialty clinics.
Distribution Channel:
Geography and reimbursement structure fragment patient access pathways across public and private financing models.
- Hospital Pharmacies:Captive dispensing for inpatient IV formulations and discharge medications. Concentrated demand in tertiary medical centers across Spain and Brazil where transplant volumes drive prophylactic antiviral consumption.
- Retail Pharmacies:Community-based dispensing for oral suppressive therapy and topical formulations. Independent and chain pharmacies in the United Kingdom and Canada serve as primary access points for recurrent lesion management.
- Online Pharmacies:Direct-to-consumer platforms enable prescription fulfillment following telehealth consultations.
- Government Healthcare Programs:Public procurement channels serve national health systems and developing-market access initiatives.
Transaction volume sits with retail pharmacies; channel expansion tilts toward online pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nucleoside precursor manufacturing clusters in Zhejiang province and Gujarat state anchor API supply security for finished-dose antiviral production worldwide. Patient access pathways diverge sharply between telehealth-enabled markets and public procurement systems. Regulatory frameworks in the United States, Germany, Japan, China, and Brazil collectively determine registration sequencing and commercial prioritization for manufacturers.
United States
Direct-to-consumer telehealth platforms route patients into suppressive therapy prescriptions at accelerating velocity. The FDA's accelerated approval pathways and Project Orphan designations compress development timelines for novel antiviral mechanisms. Research consortia in Boston and the San Francisco Bay Area advance CRISPR-based gene editing platforms through IND-enabling studies.
Germany
Retail pharmacy channels serve as primary access points for recurrent oral herpes lesion management with minimal prescription friction. The EMA's pediatric investigation plan requirements extend registration timelines for nucleoside analog developers. The Rhine-Ruhr metropolitan region concentrates molecular diagnostic laboratory capacity as PCR platforms displace culture-based methods.
Japan
Over-the-counter topical availability for HSV-1-mediated cold sores reduces prescription friction in pharmacy-accessible markets. The PMDA prioritizes submissions demonstrating transmission interruption endpoints for novel antiviral mechanisms. The Kansai region around Osaka anchors domestic pharmaceutical manufacturing infrastructure for nucleoside analog production.
China
API supply concentration in Zhejiang province creates single-source vulnerability for nucleoside precursor manufacturing. The NMPA's review standards for antiviral efficacy endpoints shape product development priorities for domestic developers. The Yangtze River Delta region clusters active pharmaceutical ingredient production for global generic antiviral supply.
Brazil
Tertiary medical centers in São Paulo drive prophylactic antiviral consumption in transplant and oncology units. ANVISA's registration requirements filter the competitive field toward entities with established cross-jurisdictional submission experience. The Southeast region concentrates hospital formulary standardization for immunocompromised patient protocols.
Global Herpes Market Competitive Landscape
Prodrug platform extension dominates the current landscape as manufacturers seek patent lifecycle management through improved bioavailability profiles. The vendor base stratifies across three tiers: multinational nucleoside analog specialists with captive API manufacturing, geographic diversifiers with distributed finished-dose networks, and generic tablet manufacturers competing on commodity margins. Strategic archetypes include backward-integrated incumbents, prodrug platform innovators, and molecular diagnostic integrators. Capacity expansion in multi-source API contracting and technology licensing for gene editing platforms represent the dominant competitive moves reshaping positioning.
Within the backward-integrated tier, GlaxoSmithKline plc and Pfizer Inc. exemplify divergent supply security strategies. Gilead Sciences Inc. occupies a distinct position through proprietary prodrug platforms that extend patent life cycles beyond traditional nucleoside analog expiration curves. These three entities collectively represent the competitive spectrum from captive manufacturing control to geographic diversification to molecular innovation.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Viatris Inc. |
| Merck & Co., Inc. |
| Gilead Sciences Inc. |
| Sanofi S.A. |
| Fresenius SE & Co. KGaA |
| Others |
Supply & Pricing Matrix
Specialty clinic procurement concentration in the United States and Germany anchors a three-tier pricing structure across premium, standard, and economy levels, with hospital formulary contracts commanding steepest discounts and retail pharmacy channels preserving broader margin flexibility for manufacturers.
Pricing Analysis
Warranty and service bundling remains unbundled across most antiviral categories, with oral tablet formulations sold purely on per-unit transactional terms while injectable products and diagnostic platforms increasingly incorporate training, calibration, and maintenance contracts. Price differentiation hinges on FDA approval tier and volume procurement scale, with branded nucleoside analogs capturing premium positioning against commodity generics. Cost compression in oral tablet segments is intensifying because of decades-long generic acyclovir availability. Hospital procurement committees demonstrate highest price sensitivity due to formulary standardization pressures, while direct-to-consumer telehealth patients show lowest sensitivity for suppressive therapy initiations.
Supply Chain Analysis
Local-content-rule angles are reshaping sourcing as India's PLI scheme and China's dual carbon goals incentivize domestic nucleoside precursor manufacturing over import-dependent models. API production draws from Zhejiang province, Gujarat state, and the Rhine-Ruhr region, with finished-dose formulation clustered in the United States, Japan, and Brazil. Key inputs include acyclovir base compounds, penciclovir intermediates, and molecular PCR reagents. Single-source vulnerability in Zhejiang manufacturing creates structural exposure to regulatory restriction or logistics disruption. Distribution runs through hospital pharmacies for IV formulations, retail chains for oral tablets, and online platforms for telehealth-integrated prescriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The herpes therapeutics sector sits in a technology-transition phase as CRISPR-based gene editing platforms displace chronic suppressive therapy models with curative approaches, threatening established nucleoside analog revenue streams.
For Market Incumbents: Cement backward integration into nucleoside precursor manufacturing to defend against API supply disruption from Zhejiang concentration. Prioritize prodrug platform patent extensions through improved bioavailability formulations to extend lifecycle control against generic erosion. Lock in hospital formulary standardization for immunocompromised prophylaxis protocols before gene editing candidates reach Phase III.
For New Entrants and Emerging Players: Telehealth platform partnerships offer the most penetrable channel for prescription volume capture outside traditional primary care networks. Target sub-Saharan Africa and Southeast Asia through WHO prequalification pathways where branded antiviral penetration remains limited. Pursue point-of-care diagnostic integration with rapid PCR devices to capture pharmacy-based prescribing workflows in the United Kingdom and Germany.
For Investors and Strategic Acquirers: The window for entry favors prodrug platform innovators with IND-enabling study completion and regulatory submission experience across FDA and EMA jurisdictions. Long-term viability hinges on curative mechanism diversification beyond nucleoside analog saturation. Watch for breakthrough therapy designation grants as the inflection signal accelerating commercialization timelines by twelve to eighteen months.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | IND-enabling studies for CRISPR-based latent reservoir targeting accelerate curative candidate pipelines through FDA Fast Track. |
| Regulatory Approval Pathway | Project Orphan designation compresses review timelines for novel antiviral mechanisms in oncology and infectious disease divisions. |
| Licensing Agreement | Technology licensing for gene editing platforms from academic consortia in Boston and San Francisco Bay Area transfers curative capabilities. |
| Manufacturing Scale-Up | Multi-source API contracting in Gujarat and Zhejiang reduces single-source vulnerability for nucleoside precursor supply security. |
| Pipeline Diversification | Prodrug platform extension through valacyclovir and famciclovir analogs extends patent lifecycles beyond traditional nucleoside expiration curves. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification databases provided structured validation points. Bottom-up prescription volume modeling and top-down therapeutic class sizing were reconciled through iterative triangulation.
Data-stream reconciliation across patient volume, pricing, and channel flow estimates shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include therapy area, product formulation, end-user institution type, and regional regulatory cluster. CAGRs were derived from historical trajectory analysis and forward-looking prescription routing assumptions. Forecast inputs incorporated telehealth platform penetration rates and molecular PCR platform adoption curves in clinical laboratories.
Caveats apply where FDA accelerated approval pathway revisions, EMA pediatric investigation requirement changes, or gene editing platform clinical failure could materially shift the outlook. Forecasts reflect assumptions around regulatory timeline stability and competitive entry sequencing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Malabsorption Syndrome Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Intestine (Small) Cancer Therapeutics Market
Specialty Medicine
Acrocallosal Syndrome Therapeutics Market
Specialty Medicine
Germ Cell Tumors Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Benign Positional Vertigo Market
Specialty Medicine
Cerebral Vein Thrombosis Treatment Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Epilepsy Treatment Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Ragweed Pollen Allergy Treatment Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market