
 Dyschromia Therapeutics Market | 2026-2036
Dyschromia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Dyschromia Therapeutics Market Foresight
REACH is hardening the cost-of-entry calculus for topical dyschromia products entering European markets, forcing extensive safety dossiers on active ingredients like arbutin and kojic acid. Pierre Fabre sustains its competitive position through heritage botanical extraction capabilities anchored in southwestern France. Bayer AG leverages its pharmaceutical manufacturing scale to supply dermatology channels with standardized depigmenting agents. Galderma S.A. differentiates through integrated clinic partnerships that combine prescription topicals with procedural device protocols.
Dyschromia therapeutics comprise pharmaceutical and device-based interventions targeting melanin pathway dysregulation, including tyrosinase inhibitors, melanin transfer blockers, and selective photothermolysis systems operating at 532 nm, 755 nm, or 1064 nm wavelengths to fragment epidermal and dermal pigment. These interventions serve the dual purpose of correcting cosmetic disfigurement and managing psychosocial burden in conditions ranging from melasma to vitiligo. Topical creams dominate current prescription volumes due to established reimbursement pathways and physician familiarity, while laser treatments capture disproportionate value per procedure in aesthetic-oriented settings. Phototherapy delivery modes are gaining structural momentum as home-use LED devices narrow the efficacy gap with clinical systems.
The FDA, EMA, and BIS collectively shape product standards through divergent tolerances for active ingredient concentrations and device energy thresholds, with India's recent Schedule H1 tightening restricting hydroquinone availability to prescription channels only. The EU's MDR reclassification of intense pulsed light devices has extended approval timelines and inflated clinical evidence requirements for manufacturers. Stakeholders must monitor regulatory divergence between the FDA's proposed OTC monograph reforms and the EU's stricter cosmetic ingredient bans to determine whether to pursue dual-track development or geographic prioritization.
Market Dynamics
Phototherapy device miniaturization is compressing the cost-per-treatment gap between clinic-based laser systems and home-use LED arrays, forcing dermatology chains to bundle procedural protocols with maintenance topicals for patient retention.
Growth Catalysts
- Schedule H1 tightening in India:Hydroquinone's prescription-only reclassification is redirecting formulation R&D toward tranexamic acid and botanical complexes, opening premium positioning for compliant alternatives.
- Medical aesthetic chains in South Korea:Bundled laser toning protocols with sustained topical regimens are extending patient lifetime value and normalizing maintenance therapy as standard care.
- Tyrosinase inhibitor innovation:Next-generation melanin pathway modulators with improved epidermal penetration profiles are expanding addressable patient populations beyond refractory melasma cases.
Market Restraints
- REACH dossier requirements:European safety documentation for arbutin and kojic acid is extending product development timelines by 18-24 months and inflating pre-market investment thresholds.
- Device energy threshold harmonization:Divergent FDA and EU MDR classification standards for intense pulsed light systems are forcing manufacturers to maintain dual technical file architectures.
- Specialized dermatology workforce concentration:Qualified phototherapy technicians cluster in metropolitan hubs, limiting service line expansion into secondary cities.
Strategic Opportunities
- Home-use LED convergence with telemedicine:Remote monitoring platforms paired with patient-administered phototherapy devices are opening subscription-based recurring revenue models outside traditional clinic settings.
- Post-inflammatory hyperpigmentation in darker skin phototypes:Underserved patient segments with Fitzpatrick types IV-VI represent unmet need for pigment-specific laser wavelength protocols.
- Botanical extraction traceability mandates:EU cosmetic ingredient transparency requirements favor vertically integrated suppliers with certified sustainable sourcing capabilities.
Industry Challenges
- Clinical evidence generation timelines:MDR-compliant post-market surveillance for reclassified intense pulsed light devices demands extended follow-up cohorts that strain smaller manufacturer balance sheets.
- Formulation stability at elevated temperatures:Tranexamic acid complexes and botanical actives degrade under tropical distribution conditions, requiring cold-chain infrastructure investments in emerging markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dyschromia Therapeutics Market |
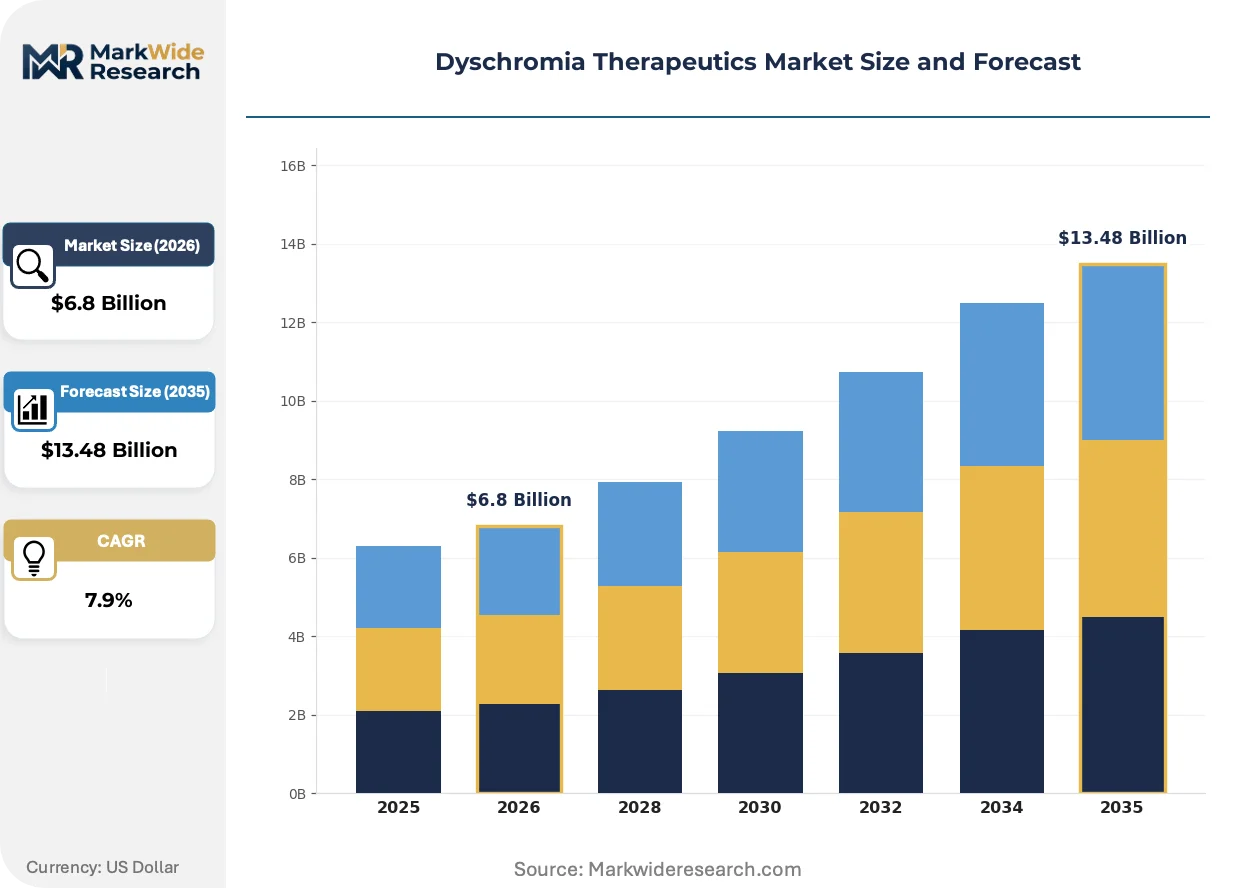
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Gels, Serums, Laser Treatments Delivery Mode: Topical, Injectable, Oral, Phototherapy End User: Dermatology Clinics, Hospitals, Home Care, Aesthetic Centers Treatment Duration: Short-term, Long-term, Maintenance, One-time |
| Companies Covered | Nestle Skin Health S.A., Pierre Fabre, Bayer AG, Beiersdorf, Bausch Health Companies Inc., AbbVie Inc., SkinCeuticals, Rubedo Life Sciences, Galderma S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dyschromia Therapeutics Market Shifts & Advancements
Dual-wavelength laser systems capable of simultaneous epidermal and dermal pigment targeting are compressing treatment protocols from multi-session regimens toward single-visit outcomes, reshaping clinic throughput economics and patient acquisition strategies.
Picosecond-domain lasers operating at 755 nm and 1064 nm wavelengths are expanding into refractory dermal melasma cases previously managed with extended topical courses alone. Academic medical centers in the United States and South Korea are adopting these platforms for pigment fragmentation with reduced thermal collateral. The technology is expanding into maintenance protocols previously reserved for Q-switched systems, compressing the addressable market for older device categories.
REACH enforcement through ECHA is hardening documentation requirements for skin-lightening actives, forcing reformulation investments away from established hydroquinone alternatives. Manufacturers must now submit extensive safety dossiers for arbutin derivatives and kojic acid complexes before market entry. The regulation is accelerating geographic prioritization decisions, with some suppliers deprioritizing European launch sequences in favor of Asian markets with less stringent cosmetic ingredient frameworks.
Patient acquisition through social media dermatology content is displacing traditional physician referral networks for aesthetic dyschromia treatments. Instagram and TikTok educational content from certified dermatologists in South Korea and the United States drives direct appointment bookings, bypassing primary care gatekeepers. This channel shift concentrates demand among younger demographics with higher price elasticity and stronger preference for bundled maintenance protocols.
Dyschromia Therapeutics Market Segmentation
Patient retention economics and reimbursement pathway fragmentation create distinct competitive arenas across product formats. Understanding where value concentrates versus where volume scales enables portfolio prioritization decisions for manufacturers and service providers.
Product Type:
Upgrade cycles in topical formulations are compressing as botanical actives displace legacy hydroquinone complexes, while laser platform refresh rates extend due to capital intensity and clinic ROI thresholds.
- Creams:Emulsion-based vehicles combining tyrosinase inhibitors with penetration enhancers dominate prescription volumes through established pharmacy channels. Demand clusters in the United States and India where dermatology access expansion drives first-line therapy protocols for melasma management.
- Serums:High-concentration aqueous formulations deliver tranexamic acid and vitamin C complexes with faster epidermal uptake profiles. Aesthetic centers in South Korea bundle these into post-laser maintenance subscriptions, extending patient lifetime value through recurring purchase patterns.
- Gels:Alcohol-based matrices suit humid climates and oily skin phototypes with reduced comedogenic risk. The format gains traction in Southeast Asian markets where tropical distribution conditions challenge cream stability.
- Laser Treatments:Picosecond and Q-switched platforms operating at 755 nm and 1064 nm wavelengths fragment dermal pigment with selective photothermolysis. Metropolitan dermatology chains in the United States and South Korea deploy these for refractory cases and premium service tier differentiation.
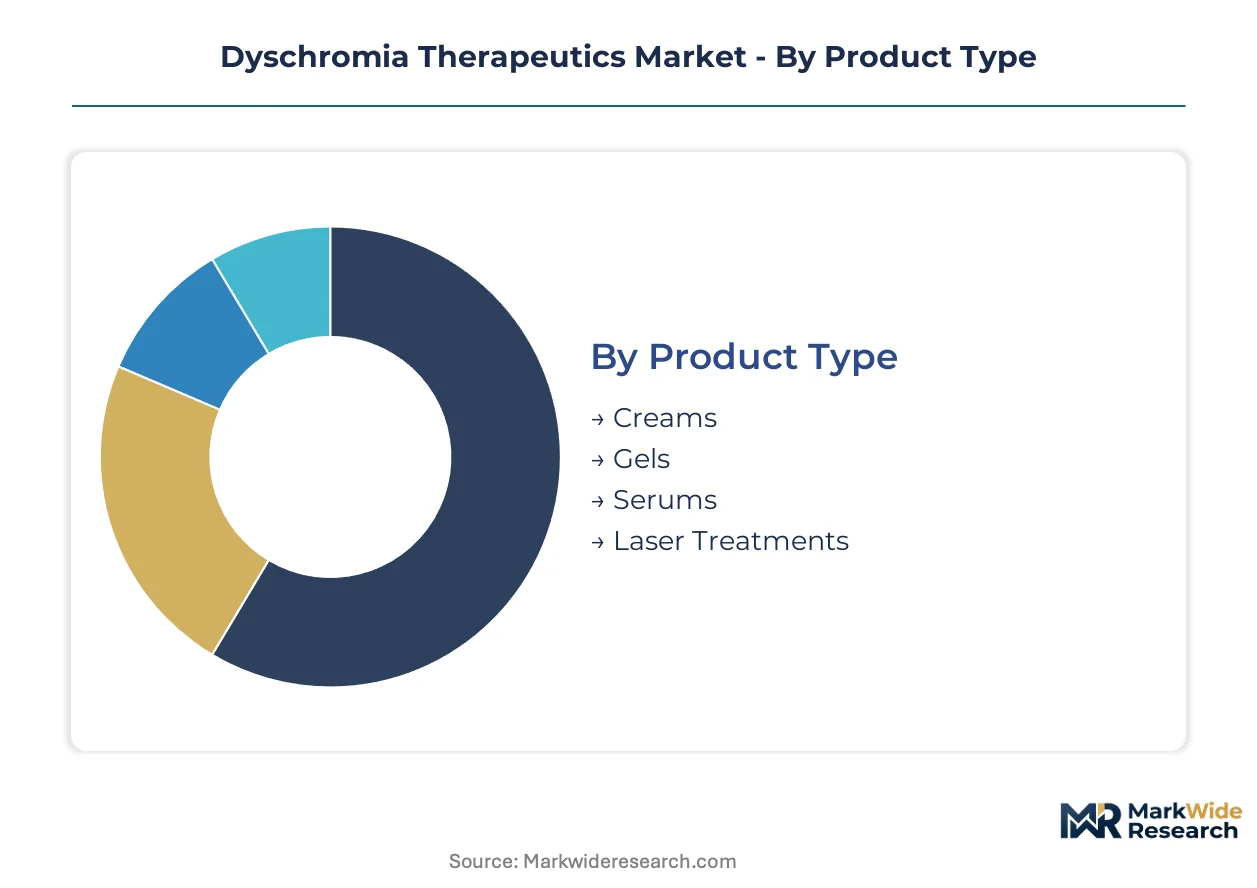
Creams sit at the top of the volume ranking, with serums climbing the fastest as aesthetic bundling normalizes maintenance therapy.
Delivery Mode:
Cost tier stratification separates clinic-administered modalities from patient-directed alternatives, with reimbursement eligibility determining addressable population scale.
- Topical:Patient-administered creams and serums leverage pharmacy distribution with minimal clinical supervision. India's Schedule H1 tightening redirects demand toward compliant tranexamic acid formulations available through prescription channels.
- Phototherapy:LED arrays and laser systems deliver targeted energy doses for pigment fragmentation. Home-use device miniaturization narrows the efficacy gap with clinical systems, enabling subscription-based remote monitoring models.
- Injectable:Tranexamic acid microinjections and mesotherapy cocktails target refractory melasma with direct dermal delivery. The modality concentrates in aesthetic centers across South Korea and Brazil where procedural bundling justifies premium positioning.
- Oral:Systemic agents including tranexamic acid tablets and polypodium leucotomos extracts modulate melanin pathway activity from within. Prescription volumes remain constrained by hepatotoxicity monitoring requirements and limited FDA approvals.
Topical delivery commands the broadest patient access, while phototherapy gains share fastest through device convergence with telemedicine platforms.
End User:
Customer type determines protocol complexity, with institutional settings managing refractory cases and home care capturing maintenance-phase economics.
- Dermatology Clinics:Specialized facilities combine diagnostic expertise with procedural capabilities across laser and phototherapy modalities. United States metropolitan hubs concentrate qualified technician pools, limiting expansion into secondary cities.
- Aesthetic Centers:Medical aesthetic chains in South Korea bundle laser toning with sustained topical regimens, normalizing maintenance therapy as standard care and extending patient lifetime value.
- Hospitals:Academic medical centers deploy picosecond lasers for refractory dermal melasma and research protocols. The segment captures complex cases requiring multidisciplinary management.
- Home Care:Patient-directed topical applications and LED devices bypass clinical gatekeepers through direct-to-consumer channels. Social media dermatology content drives acquisition among younger demographics with stronger price elasticity.
Dermatology clinics anchor institutional volume, with aesthetic centers expanding most quickly through bundled protocol normalization.
Treatment Duration:
Maturity differentiation separates acute intervention markets from chronic management economics, with recurrence rates driving maintenance-phase revenue stability.
- Long-term:Extended topical regimens spanning 3-6 months address persistent melasma and post-inflammatory hyperpigmentation. Patient adherence challenges concentrate demand in markets with established dermatology follow-up infrastructure.
- Maintenance:Sustained low-dose therapy prevents recurrence after initial clearance, particularly for hormonal melasma subtypes. South Korean aesthetic chains have normalized this phase as standard care through subscription-based topical delivery.
- Short-term:Intensive 4-8 week protocols target acute hyperpigmentation episodes with high-concentration actives. The format suits event-driven demand and travel-related sun damage correction.
- One-time:Single-visit laser protocols using dual-wavelength systems compress multi-session regimens for clinic throughput optimization. Picosecond technology expansion reshapes economics for this segment.
Long-term protocols retain the largest patient base, with maintenance phases gaining share fastest as recurrence prevention becomes standard-of-care expectation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified phototherapy technicians cluster in metropolitan dermatology hubs across five countries, anchoring regional service capacity and shaping patient access patterns for procedural dyschromia interventions.
United States
Dermatology clinic expansion in Texas and Florida drives demand for laser toning protocols and maintenance topical bundles. FDA tightened safety requirements for hydroquinone-based formulations, accelerating reformulation investments toward botanical alternatives and tranexamic acid complexes. Academic medical centers in Boston and Los Angeles deploy picosecond lasers for refractory dermal melasma cases.
South Korea
Medical aesthetic chains normalize bundled laser toning with sustained topical regimens, extending patient lifetime value through subscription-based maintenance therapy. MFDS cosmetic ingredient frameworks enable faster botanical active approval cycles than REACH counterparts. Seoul's Gangnam district concentrates premium clinic density with integrated device and topical protocol offerings.
Germany
EMA device reclassification under EU MDR extended approval timelines for intense pulsed light systems, inflating clinical evidence requirements. REACH dossier mandates for arbutin and kojic acid stretch product development timelines by 18-24 months. Frankfurt and Munich host specialized dermatology chains navigating dual-track FDA and EU regulatory submissions.
India
Schedule H1 tightening redirected hydroquinone to prescription-only channels, opening premium positioning for tranexamic acid and botanical complexes. BIS standards for topical depigmenting agents concentrate compliance investment among organized manufacturers. Mumbai and Bangalore dermatology networks expand phototherapy service lines as melasma patient volumes rise.
France
Heritage botanical extraction capabilities in southwestern France sustain competitive positioning for arbutin and plant-derived tyrosinase inhibitors. ECHA enforcement through REACH demands extensive safety documentation for skin-lightening actives. Paris-based dermatology chains integrate prescription topicals with procedural device protocols for melasma management.
Dyschromia Therapeutics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the dyschromia therapeutics landscape, creating a tiered market structure where scale advantages clash with agility in formulation innovation. Pharmaceutical manufacturers leverage existing dermatology sales infrastructure against device specialists bundling hardware with consumable protocols. Three archetypes dominate: multinational healthcare conglomerates with dermatology divisions, pure-play aesthetic device manufacturers, and botanical extraction specialists with heritage sourcing capabilities. Competitive moves center on M&A for clinic network access and strategic partnerships bridging topical formulation with procedural device protocols.
Within the heritage botanical tier, Pierre Fabre anchors French extraction capabilities against REACH compliance pressures. Bayer AG occupies a position among pharmaceutical-scale suppliers standardizing depigmenting agents for dermatology channels. Galderma S.A. exemplifies the integrated clinic partnership model, combining prescription topical distribution with procedural device protocol development.
| Leading Market Players |
|---|
| Nestle Skin Health S.A. |
| Pierre Fabre |
| Bayer AG |
| Beiersdorf |
| Bausch Health Companies Inc. |
| AbbVie Inc. |
| SkinCeuticals |
| Rubedo Life Sciences |
| Galderma S.A. |
| Others |
Supply & Pricing Matrix
Botanical active ingredient price indices in southwestern France and South Korea cascade through formulation tiers, compressing margins for mid-market emulsion suppliers while concentrating premium pricing power with heritage extraction specialists and integrated clinic networks.
Pricing Analysis
Bundled laser-toning protocols command 40-60% price premiums over standalone topical regimens in South Korean aesthetic chains, with subscription-based maintenance models anchoring recurring revenue streams. Price differentiation rests on MFDS approval tier and botanical certification grade, with REACH-compliant arbutin derivatives carrying 25-35% markups over standard kojic acid formulations. Pricing pressure stems from home-use LED device miniaturization narrowing efficacy gaps with clinical systems. Younger demographics accessing treatments via social media channels exhibit highest price sensitivity, while refractory melasma patients in academic medical centers show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with French botanical extraction houses for certified arbutin derivatives, concentrating upstream control among three heritage suppliers in the Aquitaine region. Manufacturing capacity clusters in France, South Korea, and Germany for active pharmaceutical ingredients, with formulation finishing distributed across India and the United States. Raw material dependencies include tranexamic acid feedstock from Chinese chemical manufacturers, picosecond laser crystals from German optics specialists, and LED arrays from Taiwanese semiconductor foundries. Tariff exposure on Chinese tranexamic acid intermediates threatens cost stability for topical manufacturers. Distribution runs through dermatology clinic procurement consortia in metropolitan hubs, bypassing traditional pharmaceutical wholesale channels for procedural device bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dyschromia therapeutics market compounds steadily as recurrence-driven maintenance protocols normalize across aesthetic chains, embedding recurring revenue into patient care standards.
For Market Incumbents: To counter home-use LED convergence, anchor clinic retention through exclusive device-topical bundling agreements and deepen backward integration into botanical extraction capabilities for REACH compliance advantage. Prioritize capacity expansion in South Korea and Texas dermatology corridors where patient volumes concentrate. For New Entrants and Emerging Players: Enter via post-inflammatory hyperpigmentation protocols for Fitzpatrick types IV-VI, an underserved segment lacking pigment-specific laser wavelength standardization. Target Brazilian and Indian metropolitan markets where dermatology access expansion outpaces qualified technician supply. Pursue telemedicine-integrated home-use LED distribution as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale aesthetic device manufacturers possessing MFDS-fast-tracked botanical topical pipelines. Five-to-ten year viability hinges on regulatory navigation capabilities across divergent FDA and REACH frameworks. Acquisition targets should demonstrate integrated clinic partnership density. Watch FDA OTC monograph reform timing as the critical inflection signal for portfolio rebalancing between prescription and consumer channels.| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Extraction Certification | REACH-compliant arbutin sourcing from French heritage suppliers secures European market access against 18-24 month dossier delays. |
| Laser-Topical Bundling Agreements | Seoul-based aesthetic chains extend patient lifetime value through subscription maintenance models anchored to picosecond device protocols. |
| Telemedicine Platform Integration | Remote monitoring capabilities for home-use LED arrays open recurring revenue streams outside traditional clinic gatekeepers. |
| Dual-Wavelength Device Development | Simultaneous 755 nm and 1064 nm targeting compresses refractory melasma protocols from multi-session to single-visit outcomes. |
| Tranexamic Acid Complex Reformulation | Thermal-stable aqueous serums address tropical distribution degradation, enabling Southeast Asian market penetration. |
Research Methodology
Direct dialogue with dermatology clinic operators, aesthetic chain procurement directors, botanical extraction specialists, laser device engineers, and regulatory affairs consultants grounded qualitative insights, cross-referenced against FDA 510(k) filings, EMA device classification databases, MFDS cosmetic ingredient registries, and REACH dossier submissions through ECHA. Bottom-up patient volume modeling and top-down pharmaceutical channel revenue estimates were triangulated for convergence validation.
Bottom-up segmentation analysis tracked product format, delivery mode, end-user category, and treatment duration across the projection horizon, with CAGRs derived from procedure volume growth in metropolitan dermatology hubs and formulation upgrade cycle compression. Forecast inputs incorporated phototherapy technician density by city cluster, regulatory approval timeline differentials between FDA and EU MDR pathways, and social media-driven patient acquisition channel shifts.
Inputs from clinic network administrators and device manufacturer sales operations were available through the study window; gaps in private-label topical pricing transparency and home-use LED adherence rates introduce uncertainty bands around maintenance-phase revenue projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Pleurisy Market
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Polychondritis Disease Treatment Market
Specialty Medicine
Marfan Syndrome Treatment Market
Specialty Medicine
Hunter Syndrome Treatment Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Progressive Pulmonary Fibrosis (PPF) Treatment Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Toxic Shock Syndrome Treatment Market
Specialty Medicine
Barlow's Syndrome Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Systemic Scleroderma Treatment Market