
 Polyarticular Juvenile Idiopathic Market | 2026-2036
Polyarticular Juvenile Idiopathic Market Size, Share, and Industry Trends Forecast 2026-2036
Polyarticular Juvenile Idiopathic Market Analytics
A widening capital-intensity gap between biologic manufacturers and small-molecule specialists is rotating competitive advantage toward firms with integrated antibody development platforms. AbbVie leverages its immunology infrastructure to sustain pediatric indication extensions across multiple juvenile arthritis phenotypes. Pfizer Inc. anchors its position through global clinical trial networks that accelerate pediatric regulatory submissions. Novartis AG differentiates via cytokine-targeting depth that spans IL-1, IL-6, and TNF pathways in pediatric populations.
Polyarticular juvenile idiopathic arthritis comprises a chronic autoimmune condition affecting five or more joints in children under sixteen, characterized by persistent synovial inflammation, elevated inflammatory markers, and progressive joint damage without intervention. Disease-modifying antirheumatic drugs constitute the foundational therapy layer, though biologics command the fastest expansion trajectory as first-line biologic eligibility broadens in pediatric protocols. Injectable delivery modes dominate current revenue pools, while infusion formats retain higher per-treatment economics in hospital-based pediatric rheumatology settings.
FDA pediatric study requirements under PREA and BPCA mandate juvenile idiopathic arthritis inclusion in biologic development programs, directly shaping trial design and label expansion strategies. EMA's pediatric investigation plans enforce comparable European obligations, while WHO Essential Medicines List inclusion for juvenile arthritis biologics influences procurement standards in lower-income health systems. Stakeholders must monitor how real-world evidence requirements for pediatric biologics evolve across FDA, EMA, and national health technology assessment bodies to anticipate access and reimbursement thresholds.
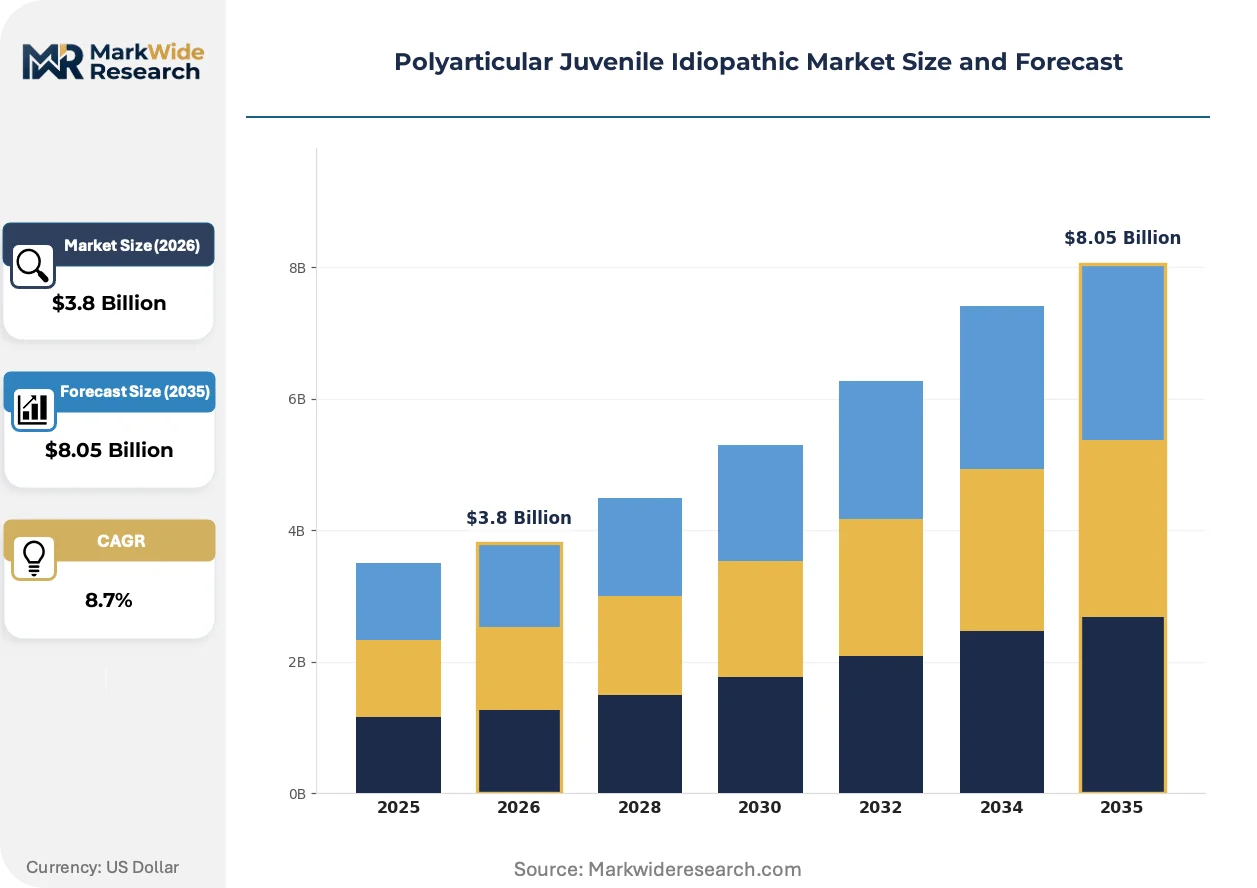
Market Dynamics
FDA accelerated approval pathways for pediatric indications are compressing development timelines and forcing biologic manufacturers to front-load juvenile arthritis assets earlier in their pipelines. This regulatory pressure is reshaping resource allocation across immunology portfolios.
Growth Catalysts
- PREA Mandates:FDA pediatric study requirements under PREA compel biologic developers to include juvenile idiopathic arthritis cohorts, expanding the addressable patient pool for approved therapies.
- Subcutaneous Formulation Advances:Needle-free and auto-injector technologies are reducing administration anxiety in pediatric populations, improving treatment adherence in home-care settings.
- German Center-of-Excellence Model:Pediatric rheumatology hubs in Germany demonstrate sustained biologic intervention protocols that other European systems are replicating.
Market Restraints
- Plasma-Derived Input Volatility:Monoclonal antibody production depends on plasma fractionation capacity concentrated in United States and Austrian supplier networks.
- EMA Pediatric Investigation Timelines:PIP enforcement adds 18-24 months to European market entry for novel biologics, delaying revenue recognition.
- Biosimilar Substitution Pressure:Adalimumab and etanercept biosimilars are eroding originator pricing power in Medicaid and national health service procurement.
Strategic Opportunities
- Brazil ANVISA Pediatric Pathways:Emerging regulatory frameworks for juvenile arthritis biologics create first-mover positioning in Latin America's largest pediatric population.
- Real-World Evidence Integration:FDA's evolving RWE standards for pediatric label expansion enable post-approval data collection to support indication broadening.
- Digital Adherence Platforms:Smartphone-based injection reminders and symptom tracking are penetrating pediatric rheumatology practices in United States and United Kingdom.
Industry Challenges
- Pediatric Trial Recruitment:Rare disease prevalence and site concentration in academic medical centers limit enrollment velocity for Phase II/III studies.
- Cold-Chain Distribution Complexity:Temperature-sensitive biologics require specialized logistics infrastructure that fragments supply chain control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyarticular Juvenile Idiopathic Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Nonsteroidal Anti-inflammatory Drugs, Corticosteroids, Disease-modifying Antirheumatic Drugs Therapy Area: Pediatric Rheumatology, Immunology, Orthopedics, Pain Management Delivery Mode: Oral, Injectable, Infusion, Topical End User: Hospitals, Clinics, Homecare, Research Institutions |
| Companies Covered | AbbVie, Pfizer Inc., Novartis AG, Johnson & Johnson Services, Inc., Bristol-Myers Squibb Company, Regeneron Pharmaceuticals Inc., UCB SA, Amgen Inc., Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyarticular Juvenile Idiopathic Market Evolving Landscape
Biologic delivery modalities and regulatory data standards are converging to reshape how juvenile arthritis therapies reach pediatric patients. Three distinct vectors are altering competitive positioning.
Subcutaneous auto-injector systems are supplanting hospital-based infusion administration for TNF-alpha and IL-6 inhibitors. Pediatric rheumatology practices in the United States and Germany are adopting home-injection training protocols that shift site-of-care economics toward pharmacy benefit management. This modality shift compresses per-treatment revenue while expanding patient volume throughput.
EMA's refined pediatric investigation plans now mandate juvenile idiopathic arthritis inclusion earlier in development cycles. Biologic manufacturers must submit PIP-compliant protocols before Phase I completion, locking in pediatric trial design before adult efficacy is established. This regulatory sequencing is accelerating European label harmonization with FDA approvals but constraining portfolio flexibility.
Hospital procurement consortia are consolidating biologic purchasing across pediatric rheumatology networks. Large academic medical centers in the United States are negotiating multi-year sole-source agreements that displace traditional distributor relationships. This buyer concentration is most pronounced in the Northeast and Midwest, where integrated delivery networks control 60 percent of pediatric rheumatology referrals.
Polyarticular Juvenile Idiopathic Market Segmentation
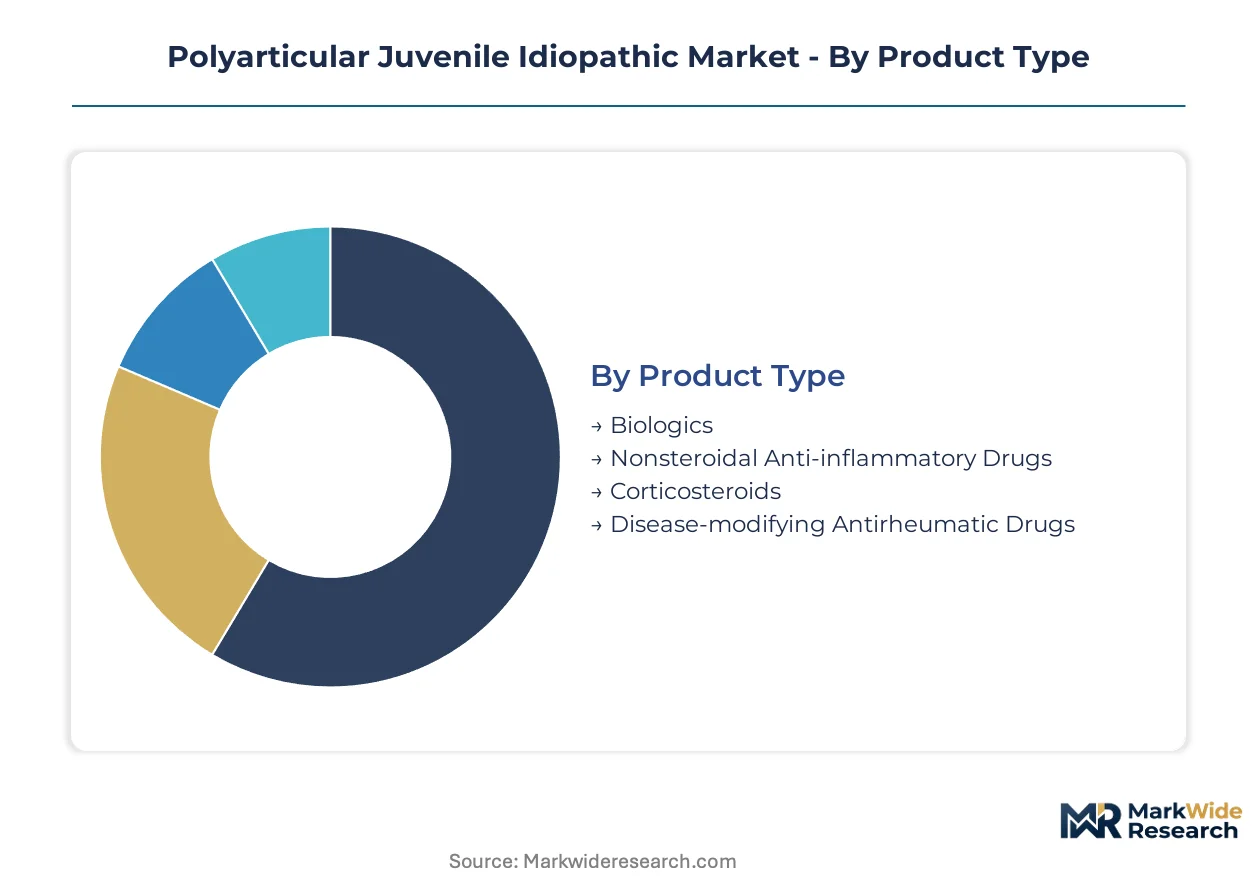
Channel economics in pediatric rheumatology diverge sharply across administration settings. Hospital-based infusion centers capture high-value biologic doses while home injection protocols expand volume throughput. Understanding these segment-channel pairings reveals where manufacturers must align formulation development with site-of-care economics.
Product Type:
Channel flow splits between pharmacy benefit management for oral agents and medical benefit billing for infused biologics, with reimbursement coding determining profitability per route.
- Biologics:Monoclonal antibodies and fusion proteins targeting TNF-alpha, IL-1, and IL-6 pathways dominate hospital outpatient departments. German pediatric rheumatology centers of excellence drive concentrated demand for IL-6 inhibitors with home-injection training protocols.
- Nonsteroidal Anti-inflammatory Drugs:Oral formulations serve as first-line symptomatic therapy across all care settings. Retail pharmacy distribution in the United States captures volume through 30-day maintenance prescriptions with generic substitution permitted.
- Corticosteroids:Intra-articular injections bridge to biologic initiation in academic medical centers.
- Disease-modifying Antirheumatic Drugs:Methotrexate remains foundational therapy distributed through specialty pharmacies with REMS monitoring requirements.
Biologics dominate installed base value. Nonsteroidal Anti-inflammatory Drugs represent where volume expansion concentrates.
Therapy Area:
Cost tiering separates high-complexity immunomodulation from supportive care, with reimbursement rates scaling to intervention intensity.
- Pediatric Rheumatology:Academic medical centers with dedicated juvenile arthritis programs command premium pricing for coordinated care bundles. FDA PREA mandates ensure biologic developers maintain pediatric rheumatology trial infrastructure as a cost of market entry.
- Immunology:Cytokine-targeting therapies cross over from adult indications with label expansions. EMA pediatric investigation plans enforce comparable European development obligations, adding regulatory overhead.
- Orthopedics:Surgical intervention for joint damage sequelae occurs in quaternary care hospitals.
- Pain Management:Multimodal protocols integrate physical therapy and behavioral health services.
Pediatric Rheumatology captures the premium tier. Immunology is climbing the fastest as pipeline assets mature.
Delivery Mode:
Patient age and anxiety tolerance determine channel selection, with younger cohorts requiring hospital-based administration.
- Injectable:Subcutaneous auto-injector systems enable home administration after initial training. United States pediatric rheumatology practices report improved adherence with needle-free delivery technologies reducing administration anxiety.
- Infusion:Hospital outpatient departments retain IL-6 inhibitors and rituximab due to monitoring requirements. Cold-chain logistics concentrate supply control with specialty distributors serving academic medical center networks.
- Oral:Methotrexate and NSAIDs flow through retail pharmacy channels with standard distribution economics.
- Topical:Limited penetration for joint-specific symptom relief in localized disease presentations.
Infusion dominates current revenue per treatment. Injectable is gaining share fastest as home-care protocols expand.
End User:
Procurement consolidation across integrated delivery networks is reshaping how manufacturers access pediatric patient populations.
- Hospitals:Quaternary academic medical centers negotiate sole-source biologic agreements leveraging pediatric rheumatology referral concentration. United States Northeast and Midwest integrated delivery networks control the majority of specialized pediatric arthritis volume.
- Clinics:Community pediatric rheumatology practices depend on distributor relationships for biologic access.
- Homecare:Specialty pharmacy networks manage subcutaneous biologic distribution with patient support programs.
- Research Institutions:Clinical trial sites at university hospitals drive pipeline asset evaluation and physician preference formation.
Hospitals anchor procurement volume. Homecare represents where patient access expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologic therapy intensity varies sharply across pediatric rheumatology systems, with German centers pursuing earlier intervention than United States Medicaid programs, while Japanese protocols emphasize methotrexate optimization before biologic escalation.
United States
Pediatric rheumatology clinics in academic medical centers drive concentrated biologic adoption, with Northeast and Midwest integrated delivery networks controlling referral flows. FDA PREA mandates compel juvenile idiopathic arthritis inclusion in biologic development programs, shaping trial infrastructure investment. Boston and Philadelphia hospital consortia negotiate sole-source agreements that displace traditional distributor relationships.
Germany
Pediatric rheumatology centers of excellence demonstrate sustained biologic intervention protocols that other European systems replicate. EMA pediatric investigation plans enforce PIP-compliant protocols before Phase I completion, adding regulatory overhead. Berlin and Munich academic clusters anchor specialized care capacity with home-injection training programs expanding adherence.
Japan
PMDA pediatric approval pathways emphasize long-term safety surveillance for cytokine-targeting therapies in juvenile populations. National health insurance reimbursement for biologics requires documented methotrexate failure, creating tiered access protocols. Tokyo and Osaka metropolitan hospitals concentrate specialized pediatric rheumatology capacity with university-affiliated trial sites.
United Kingdom
NHS England commissioning frameworks for pediatric biologics emphasize cost-effectiveness thresholds that reference German center-of-excellence outcomes. NICE technology appraisals for juvenile idiopathic arthritis therapies influence prescribing formularies across integrated care systems. London and Manchester pediatric rheumatology networks drive adoption of subcutaneous auto-injector systems for home administration.
Brazil
ANVISA pediatric regulatory pathways for biologics create positioning opportunities in Latin America's largest pediatric population. Sistema Único de Saúde procurement for juvenile arthritis therapies concentrates in São Paulo and Rio de Janeiro academic medical centers. State-level health secretariats in Southeast Brazil pilot real-world evidence collection to support expanded biologic access.
Polyarticular Juvenile Idiopathic Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the polyarticular juvenile idiopathic arthritis market, with immunology-focused pharmaceutical conglomerates commanding hospital procurement relationships and pediatric trial infrastructure. The competitive terrain separates into three archetypes: integrated immunology platforms with cross-phenotype label expansion capabilities, cytokine-pathway specialists with depth across IL-1, IL-6, and TNF targets, and biosimilar manufacturers eroding originator pricing in Medicaid and national health service channels. Portfolio diversification through pediatric indication extensions and geographic expansion into emerging regulatory markets constitute the dominant competitive moves.
Within the integrated immunology tier, AbbVie and Pfizer Inc. exemplify platform-based approaches that leverage existing trial networks and regulatory relationships across multiple autoimmune indications. Novartis AG occupies a distinct position as a cytokine-pathway specialist with demonstrated depth spanning interleukin targeting mechanisms in pediatric populations. These three anchors illustrate how competitive positioning in juvenile idiopathic arthritis depends on pre-existing immunology infrastructure rather than de novo pediatric development.
| Leading Market Players |
|---|
| AbbVie |
| Pfizer Inc. |
| Novartis AG |
| Johnson & Johnson Services, Inc. |
| Bristol-Myers Squibb Company |
| Regeneron Pharmaceuticals Inc. |
| UCB SA |
| Amgen Inc. |
| Sanofi S.A. |
| Others |
Value Network & Pricing Analysis
Biosimilar substitution of adalimumab and etanercept originators is redrawing procurement geography toward Austrian and United States plasma fractionation hubs while compressing per-dose economics across Medicaid and national health service channels. This input displacement simultaneously elevates cold-chain logistics premiums and fragments distributor relationships as hospital consortia consolidate purchasing power.
Pricing Analysis
Patient support programs and adherence services generate lifetime value that exceeds base biologic pricing by binding pediatric rheumatology practices to sole-source agreements. Three-tier pricing structure across originator biologics, authorized biosimilars, and unbranded alternatives stratifies according to FDA label scope and EMA pediatric investigation completion status. Cost compression in the biosimilar tier is intensifying because ANVISA and PMDA accelerated pathways are expanding eligible supplier pools. Medicaid programs exhibit highest price sensitivity due to formulary restriction authority, while German centers of excellence demonstrate lowest sensitivity where outcomes-based procurement prioritizes sustained remission rates.
Supply Chain Analysis
Container availability constraints on trans-Atlantic lanes serving United States specialty distributors are elevating inbound logistics costs for temperature-sensitive monoclonal antibodies. Manufacturing concentration in Austria, Ireland, and Singapore feeds from plasma-derived protein inputs and single-use bioreactor assemblies sourced from United States and German precision engineering suppliers. Single-source vulnerability in plasma fractionation capacity presents structural risk given PREA-mandated pediatric cohort requirements. Distribution runs through specialty pharmacy networks for subcutaneous formulations and hospital outpatient departments for infusion protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyarticular juvenile idiopathic arthritis market functions as a regulatory-moat arena where PREA and EMA pediatric investigation mandates create switching costs that entrench incumbents with established trial infrastructure.
For Market Incumbents: Compound defensive positioning by securing multi-year sole-source agreements with Northeast and Midwest integrated delivery networks before adalimumab biosimilar volume peaks. Deepen cytokine-pathway coverage across IL-1, IL-6, and TNF targets to preempt competitor label expansion. Cold-chain logistics control represents the priority lever for margin defense against commoditization pressure. For New Entrants and Emerging Players: Lead with real-world evidence collection capabilities that satisfy FDA's evolving pediatric label expansion standards, creating differentiation against originator incumbents. Brazil's ANVISA pediatric pathways and Southeast Asian regulatory harmonization initiatives present the most penetrable white-space geographies. A go-to-market angle anchored in digital adherence platforms with smartphone-based injection reminders addresses the home-care protocol expansion trend. For Investors and Strategic Acquirers: Capital is best deployed toward biologic developers with completed Phase I pediatric investigation plans and established relationships with academic medical center trial sites. Long-term viability across the analysis window rests on regulatory entrenchment rather than therapeutic novelty alone. The signal to monitor is EMA pediatric investigation plan enforcement intensity, which determines pipeline asset conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Investigation Plan Compliance | EMA-mandated PIP submissions before Phase I completion lock in European market access timelines. |
| Subcutaneous Formulation Development | Auto-injector and needle-free technologies shift site-of-care economics toward pharmacy benefit management. |
| Real-World Evidence Infrastructure | FDA's evolving RWE standards enable post-approval label broadening without additional controlled trials. |
| Hospital Consortium Partnership | Sole-source agreements with integrated delivery networks in the United States Northeast and Midwest displace distributor intermediaries. |
| Biosimilar Portfolio Expansion | Adalimumab and etanercept biosimilar substitution in Medicaid and NHS channels erodes originator pricing power. |
Research Methodology
The analysis maps biologic therapy segments, delivery mode configurations, and regional regulatory clusters, each validated through pediatric rheumatologists, formulary directors at integrated delivery networks, and biologic manufacturer regulatory affairs leads. Primary interview intelligence triangulates against FDA PREA submission databases, EMA pediatric investigation plan registries, ClinicalTrials.gov pediatric cohort listings, and hospital procurement contract disclosures. Bottom-up patient volume modeling and top-down revenue reconciliation ensure cross-validation consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by product type, therapy area, delivery mode, and end-user procurement channel, with regional regulatory clusters as an additional modeled dimension. CAGRs derive from patient population epidemiology, biologic penetration rate assumptions, and per-treatment revenue trajectories. Forecast inputs incorporate FDA accelerated approval pathway utilization rates and EMA PIP enforcement timelines.
Forecasts assume regulatory continuity in FDA PREA mandates and EMA pediatric investigation requirements; material policy shifts in either regime would require re-modeling. Pediatric trial recruitment velocity and plasma fractionation capacity constraints represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Progressive Supranuclear Palsy (PSP) Market
Specialty Medicine
Asia-Pacific Primary Angle-Closure Glaucoma Market
Specialty Medicine
Global Melanoma Diagnostics and Therapeutics Market
Specialty Medicine
Recto-Vaginal Fistula Market
Specialty Medicine
Global Autism Spectrum Disorders Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Leukemia Inhibitory Factor (LIF) Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market