
 Genital Warts (Condyloma Acuminatum) Market | 2026-2036
Genital Warts (Condyloma Acuminatum) Market Size, Share, and Industry Trends Forecast 2026-2036
Genital Warts (Condyloma Acuminatum) Market Foresight
Combination therapy bundling is repositioning how prescribers select first-line regimens, moving away from single-modality protocols toward integrated topical-plus-procedural protocols. Merck & Co. leverages its vaccine infrastructure to anchor HPV prevention narratives that indirectly shape treatment-seeking behavior for breakthrough infections. Verrica Pharmaceuticals specializes in topical nitric oxide-releasing platforms, competing against legacy cryotherapy and surgical alternatives with patient convenience claims. AbbVie Inc. extends its immunology portfolio into dermatology channels where off-label prescribing patterns for condyloma management persist.
Genital warts (condyloma acuminatum) constitute benign epithelial proliferations caused by human papillomavirus types 6 and 11, typically presenting as soft, cauliflower-like lesions on anogenital mucosa and requiring histopathological confirmation when atypical morphology obscures clinical diagnosis. The condition serves primarily as a treatable marker of HPV exposure, with management goals centered on lesion clearance, symptom relief, and reduction of viral transmission rather than definitive viral eradication. Among product type segments, creams and solutions occupy the volume base due to outpatient accessibility, while immunotherapy represents the fastest-expanding therapy area as intralesional agents gain formulary traction. Vaccines command premium positioning within prevention-oriented channels, whereas surgical excision segments retain concentrated margin pools in hospital outpatient departments where recurrence rates drive repeat procedure economics.
FDA oversight of topical prescription therapies and EMA marketing authorization pathways for HPV-related indications create divergent access timelines that manufacturers must navigate across Atlantic markets. OSHA bloodborne pathogen standards and CDC sexual health clinic guidelines shape procedural safety requirements and staff training protocols that influence service delivery costs. Stakeholders must monitor how payer policy evolution around preventive versus curative HPV interventions reallocates investment between vaccine development portfolios and symptomatic treatment platforms.
Market Dynamics
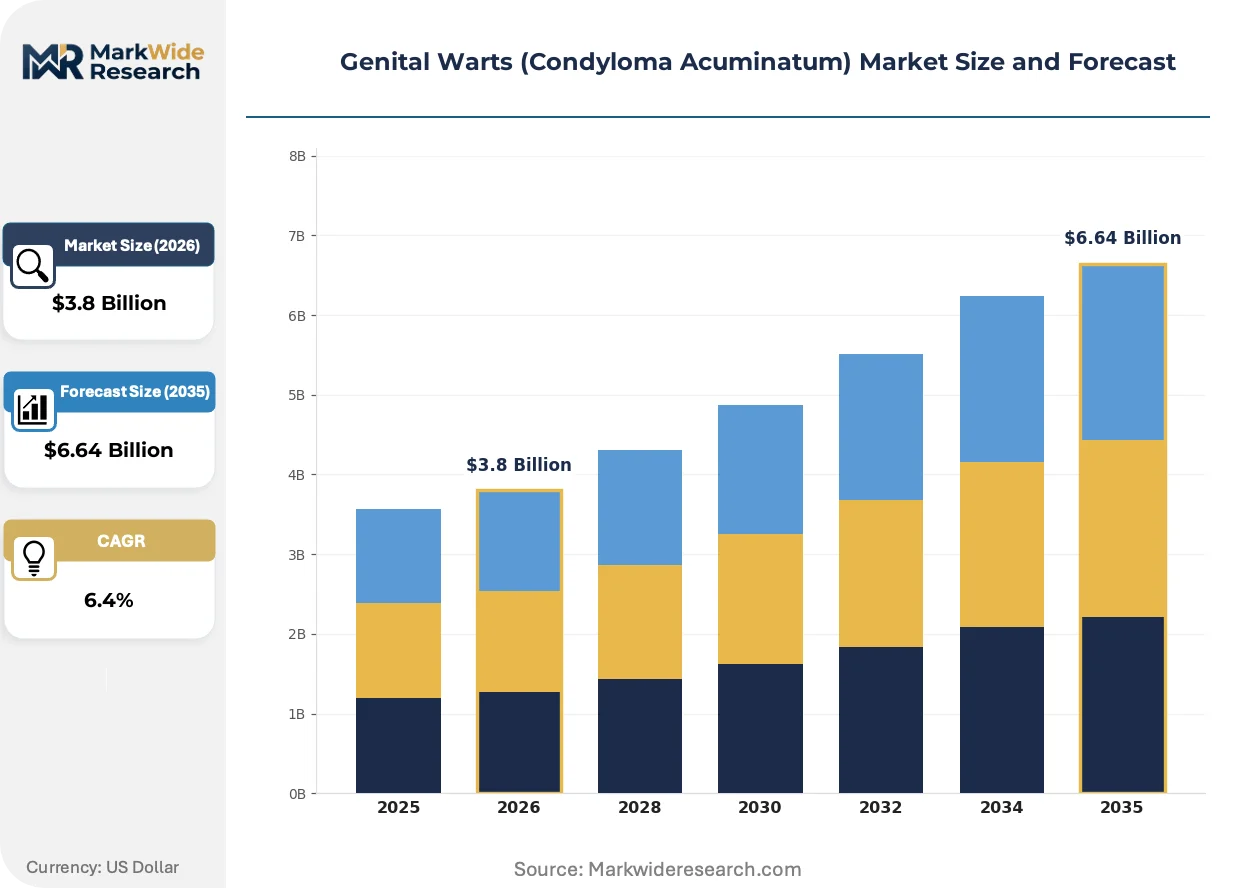
The Genital Warts (Condyloma Acuminatum) Market is restructuring around combination therapy protocols that bundle topical immunomodulators with procedural interventions, compressing standalone cryotherapy margins while elevating formulary positioning for integrated regimens.
Growth Catalysts
- FDA 505(b)(2) Pathway:Streamlined approval mechanisms for topical HPV therapies are accelerating market entry timelines for reformulated immunomodulators, expanding prescriber choice in outpatient dermatology settings.
- Patient-Initiated Care:Direct-to-consumer telehealth platforms are channeling symptomatic individuals toward clinic-based procedural services faster than traditional referral pathways.
- HPV Vaccination Gaps:Breakthrough infections among partially vaccinated cohorts are sustaining incident case volumes that feed recurrent treatment demand across sexual health clinics.
Market Restraints
- Lesion Recurrence Rates:High post-procedural recurrence necessitates repeat interventions, straining payer budgets and capping reimbursement expansion for ablative techniques.
- Specialized Provider Concentration:Trained dermatology and gynecology proceduralists cluster in urban tertiary centers, limiting rural access and concentrating service delivery costs.
- Topical Efficacy Ceilings:Patient-applied therapies face adherence drop-off and incomplete clearance rates that preserve procedural alternatives as necessary fallback options.
Strategic Opportunities
- Intralesional Immunotherapy:Candida antigen and interferon formulations are capturing formulary slots previously reserved for surgical modalities, creating margin expansion in office-based settings.
- Home-Based Nitric Oxide:Patient-administered topical platforms are penetrating pharmacy benefit structures where convenience claims override traditional site-of-care requirements.
- EMA Centralized Procedures:Harmonized marketing authorization pathways are enabling simultaneous multi-country launches that reduce regulatory fragmentation costs for topical developers.
Industry Challenges
- Histopathology Bottlenecks:Atypical lesion confirmation requires dermatopathology expertise that concentrates in academic medical centers, delaying definitive diagnosis and treatment initiation.
- OSHA Compliance Burden:Bloodborne pathogen standards for cryotherapy and electrosurgical procedures impose staff training and equipment sterilization costs that elevate per-procedure overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genital Warts (Condyloma Acuminatum) Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Laser Treatment, Immunotherapy, Cryotherapy, Surgical Excision Product Type: Creams, Solutions, Vaccines, Tablets End User: Hospitals, Dermatology Clinics, Sexual Health Clinics, Pharmacies Delivery Mode: Topical, Oral, Injectable, Surgical |
| Companies Covered | Verrica Pharmaceuticals, Merck & Co., AbbVie Inc., Sanofi S.A., Perrigo Company PLC, Novan Inc., Bausch Health, Glenmark Pharmaceuticals, Taro Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genital Warts (Condyloma Acuminatum) Market Shifts & Advancements
Topical-procedural convergence is collapsing traditional treatment hierarchies, with immunomodulatory platforms capturing indications previously managed through ablative intervention alone.
Nitric oxide-releasing topical formulations are unifying antimicrobial, antiviral, and wound-healing functions in single-application platforms. Sexual health clinics and retail dermatology chains are adopting these systems for home-based initiation protocols. This convergence is compressing the addressable market for standalone cryotherapy devices while elevating pharmacy benefit management complexity.
EMA marketing authorization pathways for HPV-related indications are tightening evidentiary requirements for recurrence rate claims. Manufacturers must now submit twelve-month clearance data rather than eight-week endpoints. Dermatology clinics in Germany, France, and Italy are adjusting informed consent protocols to reflect these extended observation windows.
Direct-pay models are displacing traditional insurance preauthorization for cosmetic-adjacent procedures. Cash-based sexual health clinics in Florida, Texas, and California are bundling lesion clearance with HPV screening services. This channel shift is most visible in metropolitan markets where high-deductible health plans have eroded payer-mediated access for recurrent cases.
Genital Warts (Condyloma Acuminatum) Market Segmentation
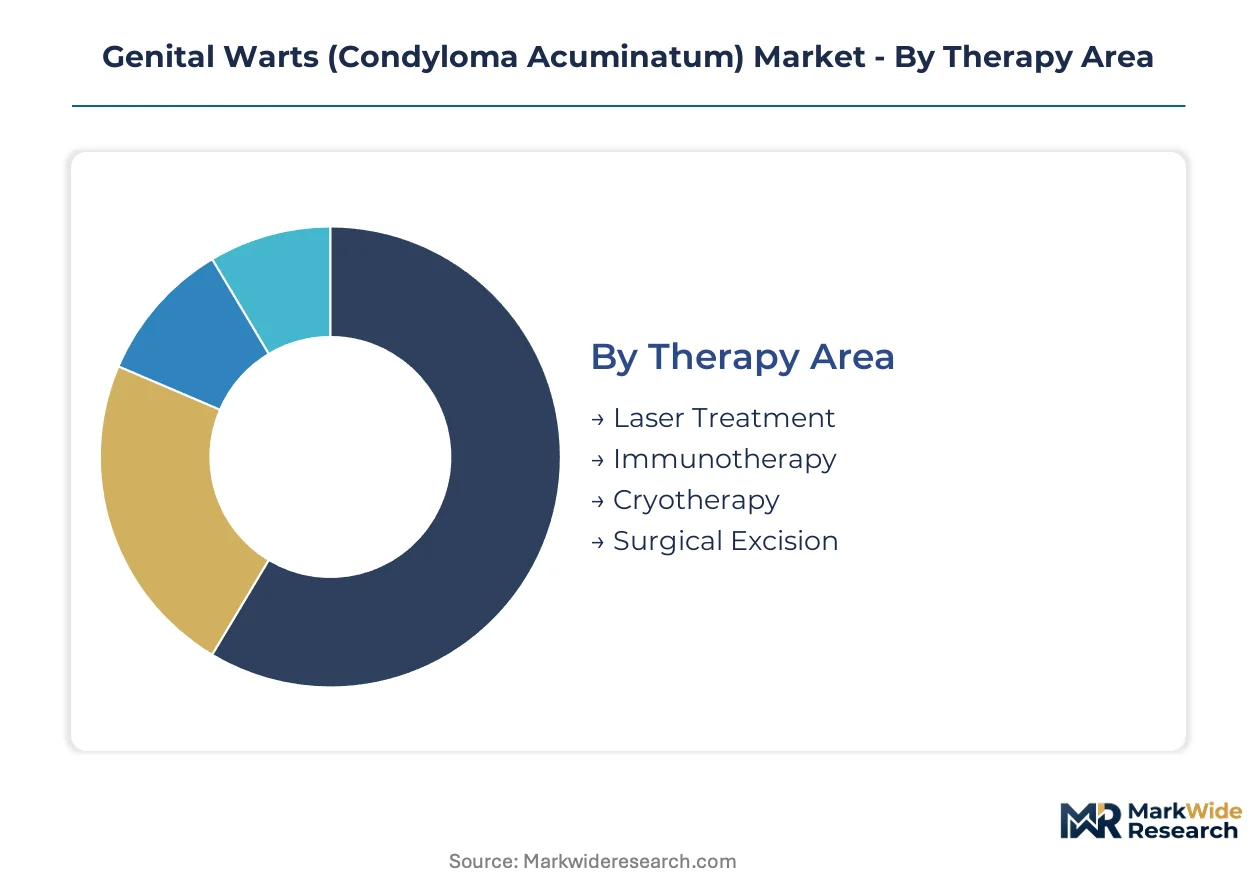
Genital warts treatment selection hinges on lesion burden, anatomical site, and patient preference for self-administered versus provider-delivered care. Segment boundaries blur as combination protocols merge topical and procedural modalities into unified regimens.
Therapy Area:
Integration depth varies sharply: cryotherapy and surgical excision function as standalone interventions, while immunotherapy increasingly embeds within multi-modality protocols.
- Cryotherapy:Liquid nitrogen application destroys lesional tissue through freeze-thaw cycles, with portable spray devices enabling point-of-care deployment. Demand clusters in urban dermatology clinics across the United States where private payer coverage for outpatient procedures continues expanding.
- Immunotherapy:Intralesional Candida antigen and interferon formulations stimulate cell-mediated antiviral responses. Sexual health clinics in Germany and France are adopting these agents as first-line alternatives to ablative techniques, driven by EMA marketing authorization pathways that streamline formulary access.
- Laser Treatment:Carbon dioxide and pulsed-dye laser systems target extensive or recalcitrant lesions in hospital outpatient departments.
- Surgical Excision:Electrosurgical and scissor excision methods retain utility for bulky lesions requiring histopathological submission.
Cryotherapy leads volumes today; immunotherapy is gaining share fastest.
Product Type:
Cost tier stratification separates premium-positioned vaccines from mass-market topicals and generic oral agents.
- Creams:Patient-applied imiquimod and podofilox formulations dominate outpatient prescribing due to pharmacy benefit accessibility. Dermatology clinics in Texas and Florida favor these for initial lesion management where direct-pay models bypass insurance preauthorization friction.
- Vaccines:Prophylactic HPV vaccines command premium pricing within prevention-oriented channels, with Merck & Co. leveraging existing infrastructure to anchor vaccination narratives that shape treatment-seeking behavior for breakthrough infections.
- Solutions:Podophyllin resin and trichloroacetic acid preparations require provider application in supervised settings.
- Tablets:Systemic immunomodulators occupy niche positioning for recalcitrant or disseminated disease.
Creams anchor volume today; vaccines exhibit the steepest expansion trajectory.
End User:
Customer type fragmentation reflects divergent service intensity: hospitals manage complex cases while retail channels capture convenience-driven demand.
- Dermatology Clinics:Specialized proceduralists concentrate in metropolitan markets, offering integrated topical-plus-cryotherapy protocols. These settings absorb the highest per-patient revenue as recurrence rates drive repeat intervention economics.
- Sexual Health Clinics:Public health-funded sites in the United Kingdom and Australia provide anonymous screening bundled with lesion clearance, capturing price-sensitive patients outside private insurance networks.
- Hospitals:Academic medical centers handle atypical lesions requiring dermatopathology confirmation and operating-room excision.
- Pharmacies:Retail chains in California and New York are expanding telehealth-linked prescribing for patient-initiated topical therapy.
Dermatology clinics lead volumes today; sexual health clinics are climbing the fastest.
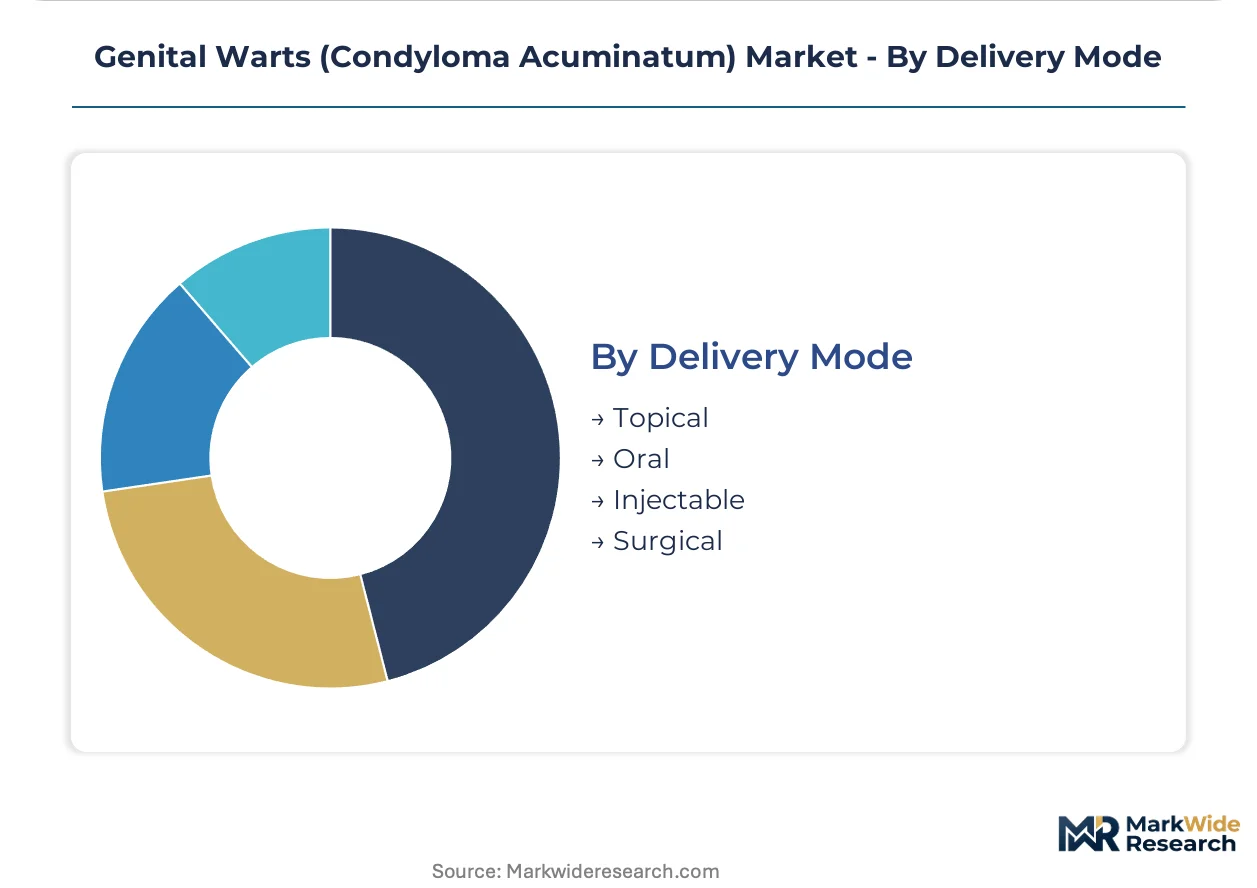
Delivery Mode:
Application maturity separates established topical and surgical routes from emerging oral and injectable platforms.
- Topical:Self-administered creams and solutions dominate prescription volume through pharmacy benefit structures. Verrica Pharmaceuticals' nitric oxide-releasing platforms compete on convenience claims against legacy cryotherapy in this channel.
- Surgical:Provider-delivered excision and ablation retain concentrated margin pools where OSHA bloodborne pathogen standards elevate per-procedure overhead.
- Injectable:Intralesional immunotherapy and interferon formulations are penetrating office-based settings as formulary alternatives.
- Oral:Systemic agents remain limited by off-label prescribing patterns and payor resistance to coverage expansion.
Topical delivery leads volumes today; injectable modes are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The genital warts treatment industry traces its modern commercial roots to United States dermatology practices of the 1980s, where cryotherapy protocols first standardized outpatient lesion management. Subsequent FDA approvals for topical immunomodulators established the country as the primary development and revenue hub for HPV-related therapeutics.
United States
Private payer coverage expansion for outpatient cryotherapy and laser procedures drives procedural volume concentration in metropolitan dermatology clinics. FDA 505(b)(2) pathway streamlines topical therapy approvals, accelerating market entry for reformulated immunomodulators. Florida, Texas, and California host the densest clusters of cash-based sexual health clinics bundling lesion clearance with HPV screening services.
Germany
Sexual health clinics in Berlin and Munich are adopting intralesional immunotherapy as first-line alternatives to ablative techniques, shifting formulary positioning toward Candida antigen formulations. EMA centralized procedures enable harmonized marketing authorization that reduces regulatory fragmentation costs for topical developers. The Rhine-Ruhr corridor concentrates dermatopathology expertise for atypical lesion confirmation.
United Kingdom
Public health-funded sexual health clinics provide anonymous screening bundled with lesion clearance, capturing price-sensitive patients outside private insurance networks. NHS England commissioning guidelines influence regional procurement patterns for patient-applied therapies versus provider-delivered procedures. London and Manchester anchor the highest-volume service delivery networks.
France
Dermatology clinics in Paris and Lyon are adjusting informed consent protocols to reflect EMA-mandated twelve-month clearance data requirements rather than eight-week endpoints. ANSM oversight of topical prescription therapies creates divergent access timelines compared to Atlantic markets. The Île-de-France region dominates histopathology capacity for complex case confirmation.
Australia
TGA marketing authorization pathways for HPV-related indications shape product launch sequencing across Asia-Pacific markets. Sexual health clinics in Sydney and Melbourne operate under integrated public health frameworks that bundle preventive vaccination with symptomatic treatment access. Victoria and New South Wales concentrate the national proceduralist workforce.
Genital Warts (Condyloma Acuminatum) Market Competitive Landscape
The competitive structure tilts toward pharmaceutical incumbents with established dermatology channel access rather than device-centric specialists. Large-cap drug manufacturers leverage existing immunology and vaccine infrastructure to anchor HPV-related portfolios, while mid-tier topical developers compete on patient convenience claims. Three archetypes dominate: vaccine-origin incumbents, topical-specialist disruptors, and diversified dermatology platforms. M&A activity concentrates on nitric oxide-releasing platform acquisitions, while strategic partnerships between telehealth providers and retail pharmacy chains reshape patient-initiated care pathways.
Among vaccine-origin incumbents, Merck & Co. exemplifies the archetype leveraging preventive infrastructure to shape treatment-seeking behavior for breakthrough infections. Verrica Pharmaceuticals occupies a position within the topical-specialist tier, competing against legacy procedural alternatives with patient-administered platform claims. AbbVie Inc. sits within the diversified dermatology platform category, extending immunology portfolio reach into channels where off-label prescribing patterns persist for condyloma management.
| Leading Market Players |
|---|
| Verrica Pharmaceuticals |
| Merck & Co. |
| AbbVie Inc. |
| Sanofi S.A. |
| Perrigo Company PLC |
| Novan Inc. |
| Bausch Health |
| Glenmark Pharmaceuticals |
| Taro Pharmaceutical Industries |
| Others |
Supply & Pricing Matrix
Formulary tier divergence between premium immunotherapy agents and commodity cryotherapy supplies manifests in both pricing power and procurement configurations. Pharmaceutical manufacturers command price premiums through FDA 505(b)(2) exclusivity windows, while device distributors compete on logistics efficiency for liquid nitrogen and electrosurgical equipment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates patented intralesional immunomodulators from branded topical creams and generic podofilox preparations. Price differentiation rests on EMA marketing authorization status and outpatient versus inpatient site-of-care designation. Cost compression in procedural tiers is intensifying because private payers are narrowing cryotherapy reimbursement bands. Sexual health clinics exhibit highest price sensitivity, while hospital outpatient departments absorb premium positioning for laser systems.
Supply Chain Analysis
Workforce availability for trained dermatology proceduralists concentrates supply capacity in the United States, Germany, and the United Kingdom. Raw material dependencies span liquid nitrogen for cryotherapy devices, interferon-alpha for intralesional formulations, and nitric oxide-releasing compounds for topical platforms. Supply chain risk centers on single-source vulnerability for specialized immunotherapy antigens. Distribution runs through pharmacy benefit managers for patient-applied therapies and direct-to-clinic channels for procedural equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The genital warts treatment market functions as a stable compounder. Recurrence-driven repeat intervention economics sustain predictable revenue streams across therapy cycles.
For Market Incumbents: Cement formulary positioning by acquiring intralesional immunotherapy platform capabilities before EMA centralized procedures enable competitor entry. Deepen backward integration into nitric oxide-releasing compound supply to defend margin position against Verrica Pharmaceuticals' convenience claims. Prioritize dermatology clinic channel control where repeat procedure volumes concentrate. For New Entrants and Emerging Players: FDA 505(b)(2) pathway in the United States opens a window for reformulated topical immunomodulators with streamlined bioequivalence requirements. Target underpenetrated sexual health clinic networks in Texas and Florida where direct-pay models bypass insurance preauthorization friction. Pursue telehealth-linked prescribing partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier topical developers lack the capital to navigate extended EMA twelve-month clearance data requirements. Five-to-ten year viability favors platforms combining home-based initiation with clinic-based escalation protocols. Watch for FDA breakthrough therapy designations for antiviral topicals as the signal to watch for inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA 505(b)(2) submissions accelerate market entry for reformulated immunomodulators against legacy cryotherapy. |
| Manufacturing Scale-Up | Nitric oxide-releasing platform production expansion captures pharmacy benefit management contracts from procedural alternatives. |
| Hospital System Partnership | Dermatology clinic network alliances secure preferred formulary status for integrated topical-plus-procedural protocols. |
| Reimbursement Strategy | Private payer coverage expansion for outpatient laser procedures broadens access in metropolitan United States markets. |
| Pipeline Diversification | Intralesional Candida antigen formulations capture sexual health clinic formulary slots previously reserved for surgical modalities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged dermatology clinic administrators, sexual health clinic procurement managers, formulary directors at pharmacy benefit managers, and regulatory affairs specialists at topical therapy developers. Secondary validation drew from FDA 510(k) filings, EMA marketing authorization databases, ClinicalTrials.gov HPV intervention records, and CMS outpatient procedure reimbursement schedules. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation anchored market sizing.
Comparable historical periods anchored the projection horizon across therapy area, product type, end user channel, and delivery mode segmentation dimensions. CAGRs were derived from regression analysis of incident case volumes, recurrence-adjusted treatment episodes, and pricing trajectory assumptions. Forecast inputs incorporated HPV vaccination coverage gaps among partially immunized cohorts and EMA-mandated extended clearance observation windows.
Revisions become necessary when EMA evidentiary requirements tighten further, FDA approval timelines compress for competing platforms, or payer policy shifts redirect investment between preventive vaccines and symptomatic treatments. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Hemophilia Market
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
Lateral Epicondylitis (Tennis Elbow) Treatment Market
Specialty Medicine
Global Constipation Treatment Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Open Angle Glaucoma Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Global Myopia and Presbyopia Treatment Market
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Global Pheochromocytoma Market