
 Parathyroid Disorders Market | 2026-2036
Parathyroid Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Parathyroid Disorders Market Outlook
Market Context with Strategic Players
Buyer concentration across hospital systems is decoupling from traditional clinic-based referral patterns as integrated delivery networks centralize parathyroid disorder management. Amgen leverages its biologics manufacturing scale to dominate recombinant hormone therapy supply to these consolidated purchasers. Radius Health differentiates through bone-targeted anabolic agents that address hyperparathyroidism-induced skeletal complications. Abbott Laboratories controls diagnostic testing workflows that precede therapeutic intervention, anchoring patient identification upstream of treatment decisions.
Technical Definition and Structural Segments
Parathyroid disorders encompass pathological conditions arising from dysregulated parathyroid hormone secretion or receptor signaling, including primary and secondary hyperparathyroidism alongside hypoparathyroidism, with diagnostic thresholds typically defined by serum calcium, phosphate, and intact PTH measurements. These conditions drive metabolic bone disease, renal osteodystrophy, and cardiovascular calcification, creating sustained demand for mineral metabolism management across nephrology and endocrinology practices. The calcimimetics segment leads in revenue intensity due to chronic dialysis patient populations requiring continuous therapy, while vitamin D analogues sustain volume leadership through generic accessibility and established reimbursement. Injectable delivery modes capture premium positioning in hospital settings, though subcutaneous formulations are gaining traction in home care transitions.
Regulatory Frame and Forward-Looking Close
The FDA's orphan drug program and breakthrough therapy designation pathways accelerate development timelines for novel hypoparathyroidism treatments, while EMA's centralized marketing authorization process shapes European market entry strategies for hormone replacement products. The WHO's essential medicines criteria influence national formulary inclusion for calcium supplements and vitamin D derivatives across emerging markets. Stakeholders must monitor evolving pharmacovigilance requirements for long-term parathyroid hormone therapy safety data as regulatory scrutiny intensifies for chronic endocrine interventions.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while calcimimetic therapy protocols expand into outpatient dialysis centers, forcing manufacturers to restructure distribution networks around integrated delivery networks rather than specialty pharmacies.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The pathway accelerates clinical validation for novel hypoparathyroidism hormone replacements, compressing development timelines from standard review periods.
- Home dialysis penetration:Patients managing secondary hyperparathyroidism through peritoneal and home hemodialysis require portable calcimimetic formulations, expanding addressable prescription volumes beyond clinic-based administration.
- Biomarker-guided dosing algorithms:Real-time PTH and calcium monitoring through connected diagnostic platforms enables precision titration, improving therapeutic adherence and reducing hospitalization events.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthetic parathyroid hormone production relies on contract manufacturers in Switzerland and specialized peptide synthesis facilities with limited redundant capacity.
- EMA pharmacovigilance requirements:Post-authorization safety studies for chronic hormone replacement impose multi-year data collection obligations that delay label expansions and geographic extensions.
- Generic vitamin D analogue substitution:Established calcitriol and doxercalciferol formulations capture price-sensitive segments, limiting branded calcimimetic penetration in cost-constrained reimbursement environments.
Strategic Opportunities
- Pediatric hypoparathyroidism protocols:Unmet need in congenital and post-surgical pediatric populations creates whitespace for age-appropriate dosing formulations and companion diagnostic development.
- Subcutaneous autoinjector convergence:Combination of recombinant hormone engineering with wearable drug delivery systems enables patient-administered replacement therapy outside infusion center infrastructure.
- Japan's Sakigake designation:Priority review incentives for first-in-class endocrine therapies accelerate market entry timelines and strengthen negotiating position with national health insurers.
Industry Challenges
- Endocrine surgery workforce density:Parathyroidectomy volume concentrates in high-volume tertiary centers, limiting patient access to curative intervention and perpetuating medical management dependencies.
- Multi-hormone replacement complexity:Coordinating calcium, vitamin D, and PTH therapy across nephrology, endocrinology, and pharmacy benefit managers fragments care continuity and complicates outcomes measurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parathyroid Disorders Market |
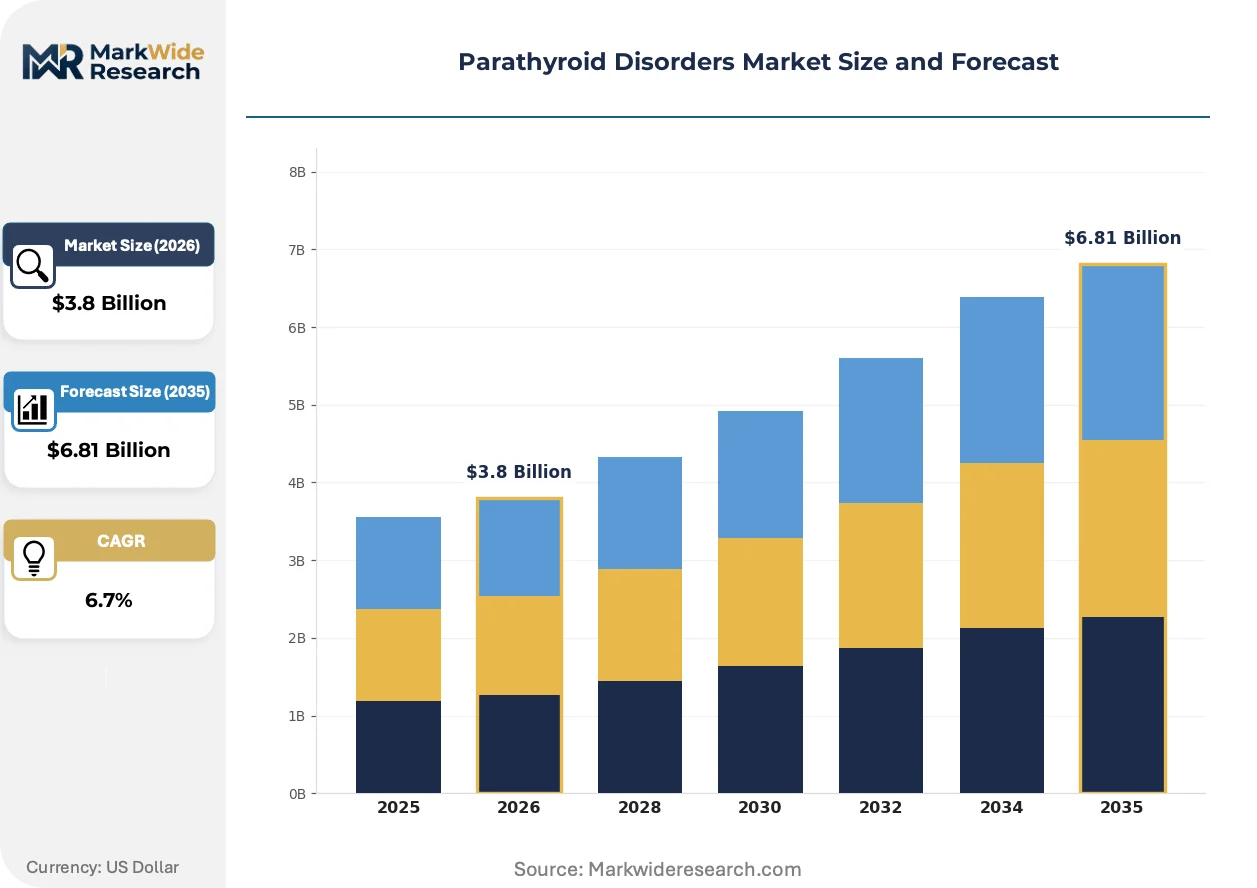
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Supplements, Vitamin D Analogues, Bisphosphonates, Calcimimetics Therapy Area: Hyperparathyroidism, Hypoparathyroidism, Primary Hyperparathyroidism, Secondary Hyperparathyroidism End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous |
| Companies Covered | Radius Health, Bayer Healthcare, Amgen, Novartis, Genentech, Eli Lilly, Abbott Laboratories, Merck, Ascendis Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parathyroid Disorders Market Strategic Shifts
Digital biomarker integration and decentralized care models are restructuring how parathyroid disorders are monitored and managed, shifting clinical decision-making from episodic laboratory testing toward continuous metabolic surveillance.
Extended-release calcimimetic formulations are expanding into home-based dialysis populations previously restricted to thrice-weekly clinic administration. Fresenius Medical Care and DaVita are piloting direct-to-patient distribution models that bypass traditional specialty pharmacy intermediaries. This channel restructuring is compressing reimbursement capture for wholesale distributors while enabling pharmaceutical manufacturers to retain margin through direct contracting with dialysis organizations.
EMA's revised MDR classification for active implantable endocrine devices is tightening clinical evidence requirements for parathyroid hormone delivery systems. Manufacturers must now submit prospective safety data from European patient registries prior to CE marking renewal. The hormone replacement device segment is responding by consolidating post-market surveillance obligations through contracted academic medical centers in Germany and the Netherlands.
Consolidated purchasing by US hospital systems is displacing fragmented clinic-level procurement for calcimimetic therapies. IDNs such as Kaiser Permanente and Mayo Clinic are negotiating multi-year sole-source agreements that bundle diagnostic testing with therapeutic supply. This concentration is most visible in the Southwest and Upper Midwest, where dominant health systems control referral patterns for chronic kidney disease-mineral and bone disorder management.
Parathyroid Disorders Market Segmentation
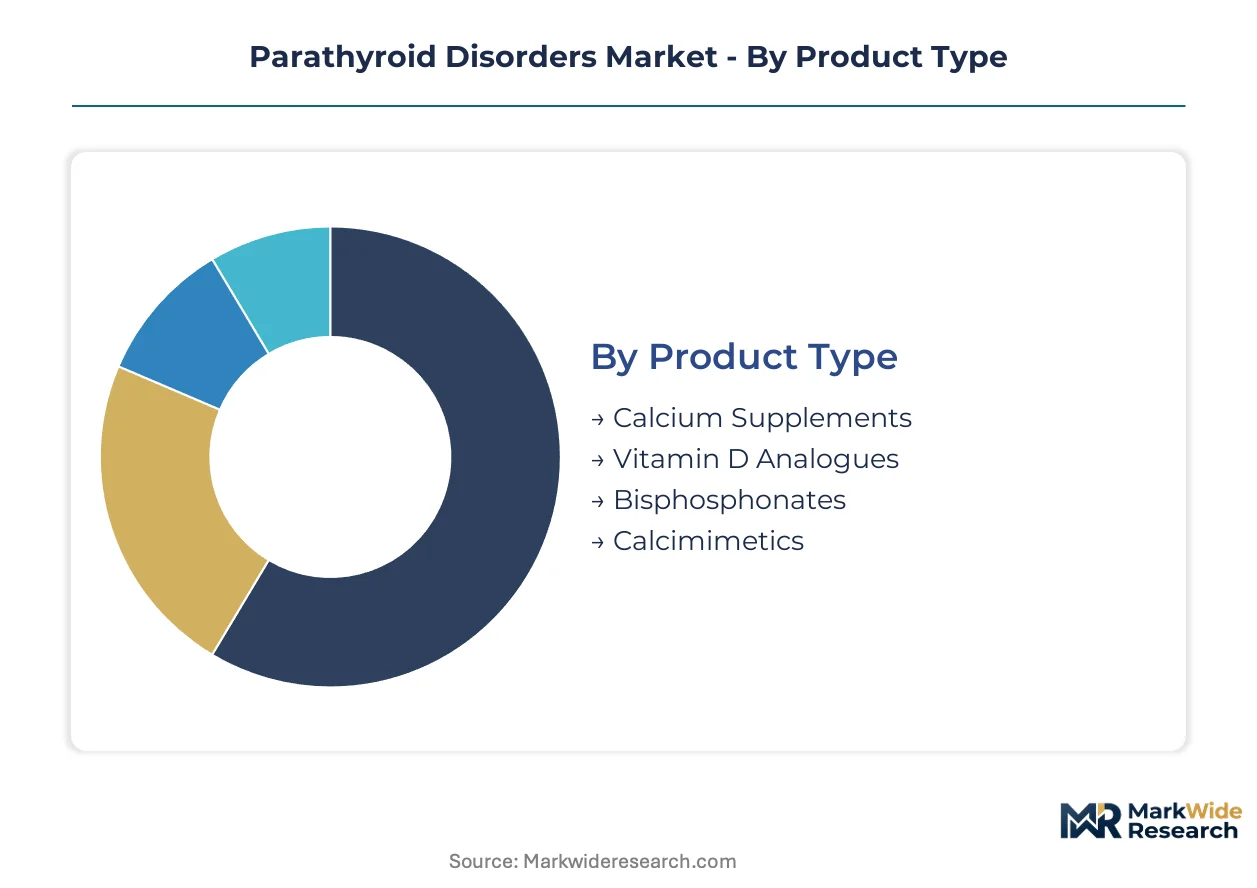
Parathyroid disorder treatments fragment across pharmacological mechanisms, care settings, and administration routes. Each dimension carries distinct margin profiles and regulatory pathways that reshape competitive positioning.
Product Type:
Volume leadership sits with established mineral supplements while premium capture concentrates in receptor-targeted synthetic hormones.
- Calcimimetics:Allosteric modulators of the calcium-sensing receptor enable PTH suppression without surgical intervention. Dialysis-dependent populations in the United States drive prescription volumes through Medicare reimbursement pathways. Chronic administration requirements sustain recurring revenue intensity unmatched by intermittent therapies.
- Vitamin D Analogues:Synthetic calcitriol and doxercalciferol formulations manage mineral absorption in secondary hyperparathyroidism. Generic substitution pressure in Medicaid programs compresses branded pricing power despite established clinical utility.
- Calcium Supplements:Elemental calcium carbonate and citrate formulations anchor first-line hypoparathyroidism management.
- Bisphosphonates:Anti-resorptive agents address skeletal complications from sustained hyperparathyroidism.
Today's leader: Calcimimetics. Tomorrow's challenger: Vitamin D Analogues.
Therapy Area:
Secondary disease states outnumber primary conditions in addressable population while congenital deficiencies command orphan drug premiums.
- Secondary Hyperparathyroidism:Renal osteodystrophy-driven PTH elevation affects stage 5 chronic kidney disease patients universally requiring intervention. Fresenius Medical Care and DaVita clinic networks standardize calcimimetic protocols across their combined patient bases.
- Hypoparathyroidism:Post-surgical and autoimmune etiologies create permanent hormone deficiency requiring lifelong replacement. FDA breakthrough therapy designation for recombinant PTH products accelerates development timelines in this historically underserved segment.
- Primary Hyperparathyroidism:Sporadic adenoma-driven disease often resolves through parathyroidectomy rather than chronic pharmacotherapy.
- Hyperparathyroidism:Aggregate category spanning both primary and secondary etiologies with divergent treatment algorithms.
Secondary Hyperparathyroidism generates current prescription volumes; Hypoparathyroidism presents the steepest expansion trajectory as hormone replacement therapies advance through regulatory pipelines.
End User:
Site-of-care migration from inpatient infusion centers toward residential administration restructures distribution economics and patient monitoring requirements.
- Hospitals:Tertiary endocrinology departments manage acute hypercalcemic crises and initiate complex multi-hormone replacement protocols. Integrated delivery networks in the United States consolidate purchasing leverage through multi-year therapeutic contracts.
- Home Care:Peritoneal dialysis and subcutaneous autoinjector adoption enable patient-managed calcimimetic administration outside clinic supervision. Remote PTH monitoring platforms support safety surveillance in dispersed populations.
- Clinics:Outpatient nephrology practices handle stable maintenance dosing for established patients.
- Long-term Care Facilities:Skilled nursing environments manage mineral metabolism in elderly patients with polypharmacy complexity.
Institutional procurement dominates current revenue capture; Home Care channels are gaining share fastest as wearable delivery systems mature.
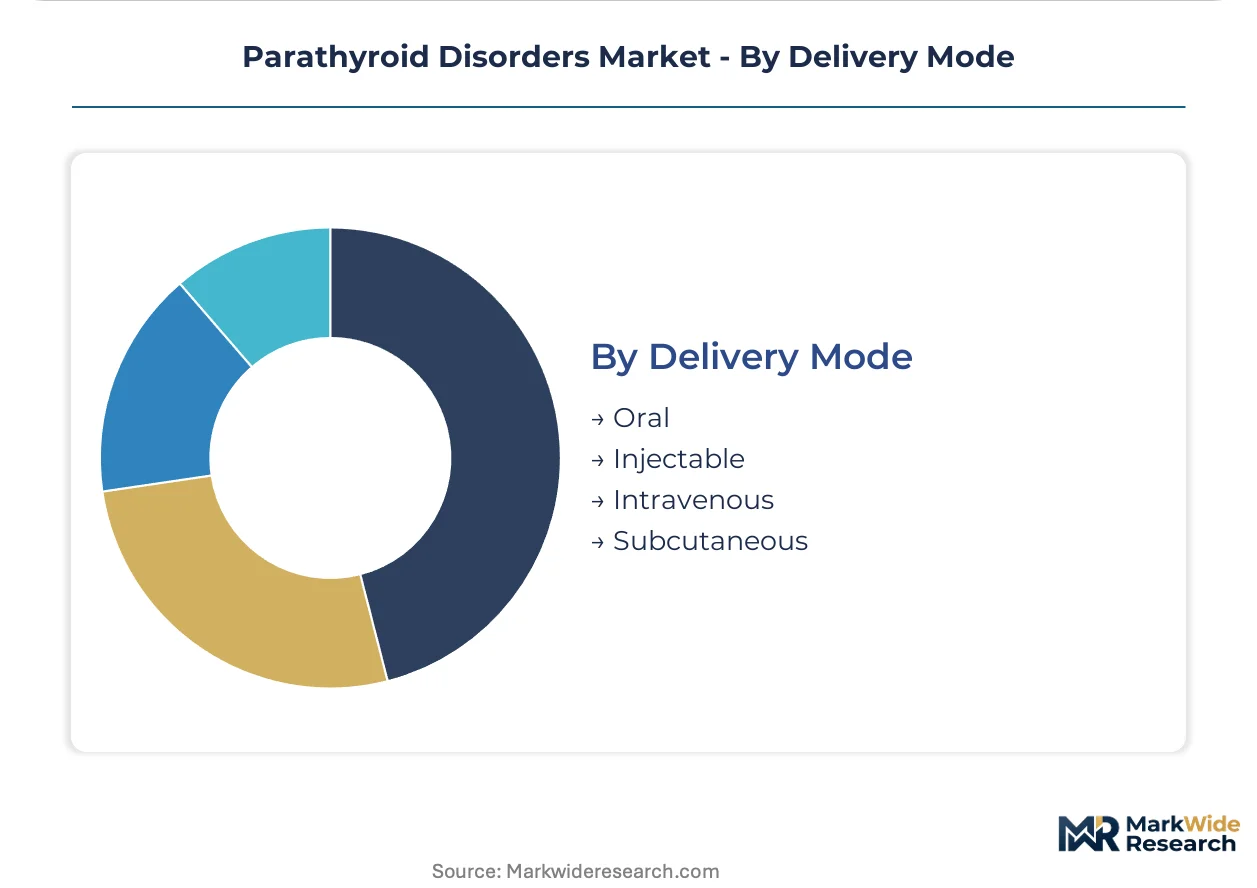
Delivery Mode:
Pharmacokinetic requirements for calcium homeostasis dictate route selection, with chronic daily needs favoring non-invasive administration.
- Oral:Immediate and extended-release tablets dominate calcium and vitamin D supplementation. Patient adherence challenges in polypharmacy regimens drive demand for combination formulations and once-daily dosing.
- Subcutaneous:Recombinant PTH replacement requires injection delivery; autoinjector device convergence improves patient acceptance outside infusion infrastructure.
- Intravenous:Acute hypercalcemia management and dialysis clinic calcimimetic administration employ IV routes.
- Injectable:Broad category encompassing intramuscular and depot formulations for hormone replacement.
Oral administration sustains volume leadership through patient preference; Subcutaneous delivery is climbing the fastest as biotechnology enables home-based peptide therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized endocrine surgery training programs in the United States, Germany, and Japan anchor geographic demand concentration for parathyroid disorder therapeutics. These workforce clusters concentrate tertiary referral volumes and shape regional adoption patterns for calcimimetic and hormone replacement protocols.
United States
Medicare reimbursement for cinacalcet in dialysis populations drives prescription volumes through Fresenius Medical Care and DaVita clinic networks. FDA breakthrough therapy designations for hypoparathyroidism hormone replacements accelerate development timelines. The Mayo Clinic in Rochester anchors multi-hormone replacement protocols that diffuse through integrated delivery networks across the Upper Midwest.
Germany
EMA centralized marketing authorization shapes European market entry for recombinant PTH products. Post-authorization safety study requirements impose multi-year data collection obligations that delay label expansions. The University Hospital Heidelberg cluster coordinates pharmacovigilance registries for chronic endocrine interventions across the Baden-Württemberg region.
Japan
PMDA's Sakigake designation accelerates priority review for first-in-class endocrine therapies. National health insurer negotiations favor domestic manufacturers with established reimbursement track records. The Tokyo metropolitan area concentrates tertiary endocrinology departments that pilot wearable drug delivery systems for home-based hormone replacement.
Switzerland
Swissmedic's stringent pharmacovigilance standards for peptide therapeutics influence manufacturing quality benchmarks across European supply chains. Specialized peptide synthesis facilities in Basel-Stadt and Vaud cantons supply active pharmaceutical ingredients for synthetic hormone production. Lonza's contract manufacturing infrastructure anchors redundant capacity planning for biologic hormone therapies.
India
CDSCO accelerated approval pathways for orphan endocrine conditions expand access to imported hormone replacement therapies. Cost-constrained public procurement favors generic vitamin D analogues over branded calcimimetics. The Delhi-NCR cluster concentrates nephrology referral networks that manage secondary hyperparathyroidism across northern Indian dialysis populations.
Parathyroid Disorders Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the parathyroid disorder therapeutic landscape. The market structure concentrates revenue capture among biotechnology manufacturers with biologics manufacturing scale and diagnostic-anchored healthcare conglomerates. Three archetypes dominate: large-cap biopharmaceuticals with recombinant hormone platforms, diversified diagnostics-therapeutics conglomerates controlling patient identification workflows, and emerging specialty endocrine companies pursuing orphan drug premiums. Competitive dynamics center on sole-source contracting with integrated delivery networks and breakthrough therapy designation races for hypoparathyroidism replacement therapies.
Among large-cap biopharmaceuticals, Amgen exemplifies scale-driven manufacturing dominance in recombinant hormone supply. Radius Health occupies a position within the bone-targeted therapeutic archetype addressing hyperparathyroidism skeletal complications. Abbott Laboratories anchors the diagnostic-therapeutic convergence model, controlling upstream patient identification through testing workflows that precede intervention decisions.
| Leading Market Players |
|---|
| Radius Health |
| Bayer Healthcare |
| Amgen |
| Novartis |
| Genentech |
| Eli Lilly |
| Abbott Laboratories |
| Merck |
| Ascendis Pharma |
| Others |
Value Chain & Pricing Dynamics
Orphan drug premium tiers diverge sharply from generic vitamin D analogue commoditization, with FDA breakthrough designation commanding sole-source contracting leverage while Medicaid formularies drive volume substitution. This bifurcation concentrates manufacturing investment in Swiss peptide synthesis facilities for recombinant hormones while Indian and Chinese API producers absorb calcium and vitamin D volume production.
Pricing Analysis
Capacity additions in Indian generic API manufacturing are reshaping price floors for vitamin D analogues and elemental calcium formulations. Three-tier pricing structure across premium calcimimetics, standard branded vitamin D, and economy generic calcium separates reimbursement capture tiers. Cost compression in the vitamin D segment intensifies because Medicaid preferred drug lists mandate therapeutic substitution. Dialysis clinic procurement managers show highest price sensitivity for chronic administration products, while hospital pharmacy directors accept premium positioning for acute hypercalcemia interventions.
Supply Chain Analysis
Dual-sourcing requirements from Fresenius Medical Care and DaVita mandate multi-supplier qualification for cinacalcet active pharmaceutical ingredients. Manufacturing concentration centers on Switzerland for synthetic parathyroid hormone peptides, India for generic vitamin D intermediates, and China for calcium carbonate raw material. Synthetic hormone production draws from specialized fermentation and peptide synthesis inputs with limited redundant capacity. Single-source vulnerability in Swiss contract manufacturing creates supply continuity exposure for orphan drug hormone replacements. Distribution runs through integrated delivery network central warehouses rather than fragmented specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in parathyroid disorder therapeutics rests on home-based administration formats reducing infusion center overhead and enabling direct-to-patient premium capture.
For Market Incumbents: Deepen backward integration into peptide synthesis capacity in Basel-Stadt canton to secure hormone replacement API supply against Swiss manufacturing bottlenecks. Fortify sole-source contracting with Kaiser Permanente and Mayo Clinic IDNs before calcimimetic patent cliffs accelerate. Lock in multi-year diagnostic-therapeutic bundles that anchor Abbott Laboratories' upstream patient identification workflows to downstream drug supply commitments. For New Entrants and Emerging Players: Wearable subcutaneous autoinjector convergence offers entry wedge into pediatric hypoparathyroidism populations underserved by adult-dosed infusion formats. White-space concentrates in congenital hormone deficiency protocols requiring age-appropriate formulation development. Japan's Sakigake designation pathway provides fastest regulatory validation for first-in-class endocrine delivery systems, enabling priority reimbursement negotiation with national health insurers before US FDA review completion. For Investors and Strategic Acquirers: Consolidation pressure builds where endocrine surgery workforce density concentrates parathyroidectomy volume in tertiary centers, perpetuating medical management dependencies and chronic pharmaceutical demand. Long-term viability favors platform companies combining diagnostic testing workflows with therapeutic supply contracts rather than single-product hormone replacement specialists. Signal to watch: FDA breakthrough therapy designation awards for hypoparathyroidism candidates, which accelerate development timelines and strengthen negotiating position with consolidated hospital purchasers.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA breakthrough designation compresses review timelines for hypoparathyroidism hormone replacements. |
| Manufacturing Scale-Up | Swiss peptide synthesis capacity expansion secures recombinant PTH supply for orphan drug demand. |
| Reimbursement Strategy | Medicare bundled payment alignment with dialysis clinic networks anchors cinacalcet prescription volumes. |
| Hospital System Partnership | IDN sole-source agreements with Kaiser Permanente consolidate calcimimetic procurement leverage. |
| Regulatory Approval Pathway | Japan Sakigake designation accelerates PMDA priority review for wearable hormone delivery systems. |
Study Parameters
Coverage spans the United States, Germany, Japan, Switzerland, and India, with primary inputs from each market's stakeholder ecosystem. Drug development executives at recombinant hormone manufacturers, regulatory affairs leads navigating FDA and EMA orphan pathways, hospital procurement managers at integrated delivery networks, and payer access specialists at Medicare Advantage plans provided qualitative intelligence. Secondary validation drew from FDA breakthrough therapy designation announcements, EMA centralized marketing authorization submissions, ClinicalTrials.gov hypoparathyroidism protocol registrations, and CMS Medicare dialysis reimbursement databases. Bottom-up prescription volume modeling triangulated against top-down therapeutic class expenditure estimates.
Granularity-level modeling distinguished calcimimetic, vitamin D analogue, and hormone replacement product categories with separate pricing and volume trajectories. Therapy area segmentation separated secondary hyperparathyroidism dialysis populations from hypoparathyroidism orphan indications with distinct reimbursement pathways. Administration route modeling captured oral, subcutaneous, and intravenous delivery modes with site-of-care migration assumptions across the projection horizon. CAGRs derived from patient population epidemiology, treatment penetration curves, and pricing elasticity by payer type. Forecast inputs incorporated home dialysis penetration rates and wearable drug delivery adoption curves specific to endocrine therapeutic administration.
The model holds under stable Medicare reimbursement for calcimimetics and continued FDA orphan drug incentive continuity; deviation in dialysis provider consolidation pace or EMA pharmacovigilance requirement tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Gastrointestinal Stromal Tumors Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Europe Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Epidermal Nevus Syndrome Market
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market
Specialty Medicine
Geographic Atrophy Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Global Vasculitis Treatment Market