
 Achondroplasia Treatment Market | 2026-2036
Achondroplasia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Achondroplasia Treatment Market Analysis
Recombinant C-type natriuretic peptide is pivoting achondroplasia treatment away from purely surgical limb-lengthening protocols toward chronic pharmacologic management. BioMarin Pharmaceutical leverages its first-mover approval to anchor the CNP analog segment with established manufacturing scale and payer contracts. Ascendis Pharma competes through its TransCon technology platform, which sustains extended-release profiles that differentiate dosing convenience. BridgeBio Pharma specializes in precision genetic medicine approaches, positioning its pipeline to address FGFR3 pathway modulation directly.
Achondroplasia treatment encompasses pharmacologic, surgical, and supportive interventions targeting the FGFR3 mutation-driven skeletal dysplasia characterized by disproportionate short stature, foramen magnum stenosis, and recurrent otitis media; the primary therapeutic goal is improvement in linear growth velocity and reduction in skeletal complication burden through modulation of aberrant bone growth signaling. Growth Hormones occupies a mature position with limited efficacy evidence, while Gene Therapy represents the fastest-expanding segment as adeno-associated viral delivery systems advance toward clinical translation. Surgical Interventions retains significant margin pools in specialized orthopedic centers performing limb-lengthening procedures, though procedural volume growth moderates as pharmacologic alternatives diffuse.
FDA maintains stringent requirements for pediatric rare disease therapies through its Office of Rare Diseases, while EMA's Committee for Orphan Medicinal Products shapes European access pathways for achondroplasia interventions; both frameworks elevate clinical trial standards and post-market surveillance obligations that filter development-stage participants. The EU AI Act and GDPR impose additional constraints on algorithmic diagnostic tools used in skeletal dysplasia screening programs, affecting digital health entrants. Stakeholders must monitor evolving FDA guidance on gene therapy manufacturing and EMA adaptive pathway decisions to align portfolio timelines with regulatory access windows.
Market Dynamics
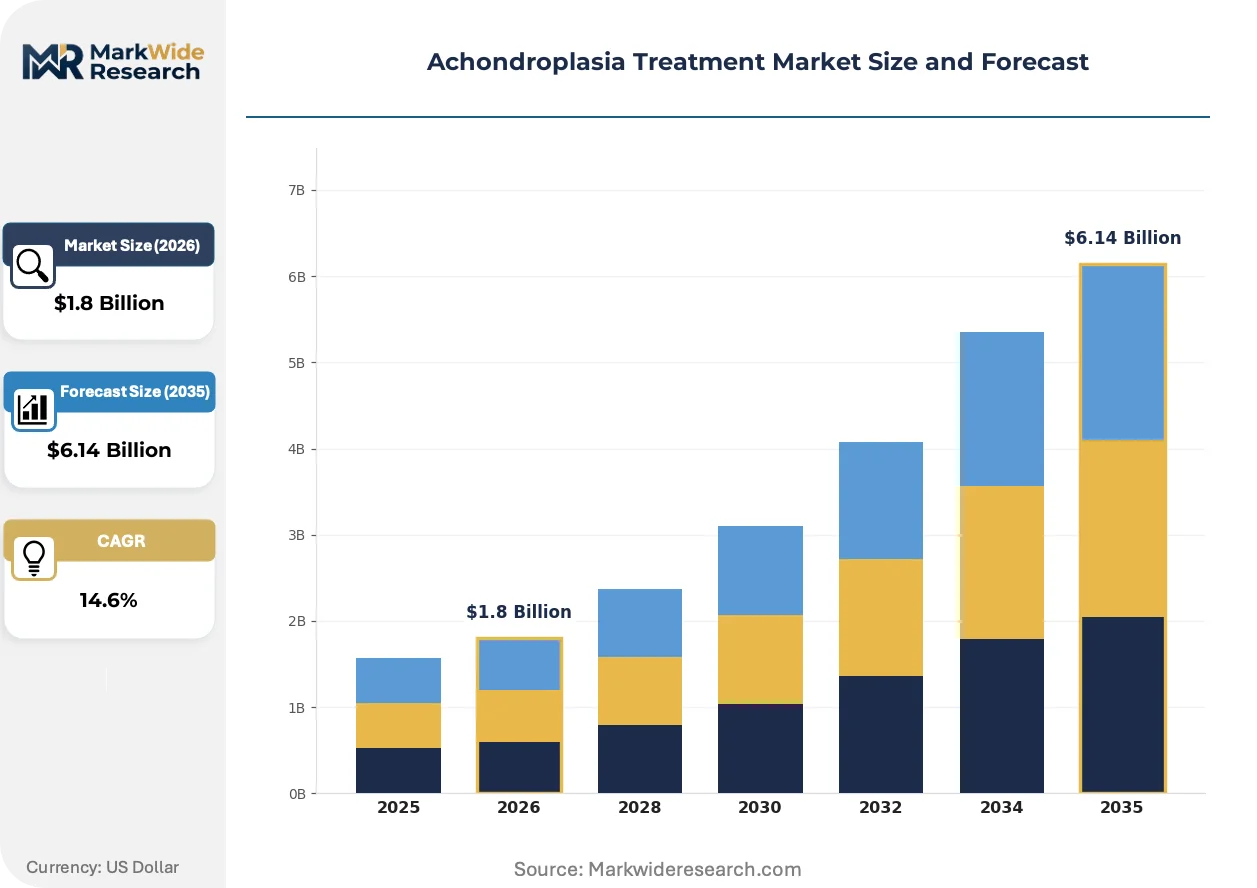
The transition from surgical limb-lengthening toward chronic CNP analog pharmacotherapy is restructuring treatment protocols, reimbursement frameworks, and site-of-care economics across pediatric endocrinology and orthopedic networks.
Growth Catalysts
- EMA Adaptive Pathway Expansion:The Committee for Orphan Medicinal Products is accelerating conditional approval timelines for FGFR3-targeted therapies, compressing development-to-commercialization cycles for rare disease biologics.
- TransCon Sustained-Release Platforms:Extended-release peptide engineering is reducing injection frequency burdens, improving pediatric adherence rates and caregiver acceptance in chronic management protocols.
- United States:Specialized skeletal dysplasia clinic expansion within major pediatric hospital networks is creating concentrated prescriber bases and streamlined prior authorization pathways for novel therapies.
Market Restraints
- Biologic Manufacturing Concentration:Recombinant CNP analog production relies on mammalian cell culture capacity concentrated among contract manufacturers in Switzerland and Germany, creating single-source vulnerability for peptide supply.
- FDA Post-Market Surveillance Obligations:The Office of Rare Diseases mandates extended pediatric safety monitoring that extends trial timelines and elevates regulatory compliance costs for development-stage entrants.
- Limb-Lengthening Substitution:Established orthopedic surgical protocols retain preference among families seeking definitive stature correction, limiting pharmacotherapy penetration in aesthetic-motivated patient segments.
Strategic Opportunities
- Gene Therapy Convergence:AAV-mediated FGFR3 knockdown approaches, when combined with CNP analog priming, offer potential curative intervention pathways that could displace chronic pharmacologic management.
- EU AI Act Diagnostic Exemption Navigation:Algorithmic skeletal dysplasia screening tools face GDPR and AI Act constraints that create first-mover advantage for compliant digital health platforms securing CE marking under MDR.
- Brazil:ANVISA's expanded access program for rare diseases presents early commercialization opportunity ahead of formal registration, leveraging compassionate use frameworks to build clinical evidence and prescriber relationships.
Industry Challenges
- Pediatric Endocrinology Workforce Scarcity:Fellowship-trained specialists capable of managing complex skeletal dysplasia cases remain concentrated at academic medical centers, limiting community-based treatment expansion.
- Multi-Stakeholder Reimbursement Coordination:Payer contracts must align hospital, physician, and pharmacy benefit structures across distinct billing codes, creating administrative friction in integrated care delivery models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Achondroplasia Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Growth Hormones, Surgical Interventions, Gene Therapy, Supportive Care Therapy Area: Pediatric Care, Orthopedic Treatments, Genetic Disorders, Rehabilitation Services Delivery Mode: Intravenous, Subcutaneous, Oral, Intraosseous End User: Hospitals, Clinics, Home Care, Specialized Treatment Centers |
| Companies Covered | BioMarin Pharmaceutical, Ascendis Pharma, BridgeBio Pharma, RIBOMIC, Pfizer, Novartis, Sanofi, Novo Nordisk, PhaseBio Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Achondroplasia Treatment Market Emerging Trajectories
Pharmacologic intervention is displacing procedural dominance in achondroplasia management, with technology platforms and regulatory frameworks converging to enable precision genetic medicine at scale.
TransCon peptide engineering is decentralizing treatment administration from hospital-based infusion centers toward home-based injection protocols. Pediatric endocrinology practices in the United States and Germany are adopting these extended-release formulations to reduce caregiver burden and clinic capacity constraints. This shift is compressing site-of-care economics and redistributing margin capture from hospital systems toward specialty pharmacy networks.
EMA's MDR and EU AI Act are imposing algorithmic transparency requirements on diagnostic imaging tools used in skeletal dysplasia screening programs. Manufacturers of AI-assisted radiographic classification systems must now document training data provenance and clinical validation endpoints to secure CE marking. European pediatric hospital networks are responding by consolidating vendor relationships around platforms with established regulatory documentation packages.
Caregiver advocacy organizations are driving preference shifts toward therapy options with demonstrated functional outcome metrics beyond linear growth velocity. Parent-led foundations in the United States and United Kingdom are pressuring manufacturers to publish foramen magnum stenosis and sleep apnea endpoint data, reshaping clinical trial design and commercial messaging priorities. This behavioral shift is most visible in patient registry participation rates and treatment persistence metrics across North American specialty pharmacies.
Achondroplasia Treatment Market Segmentation
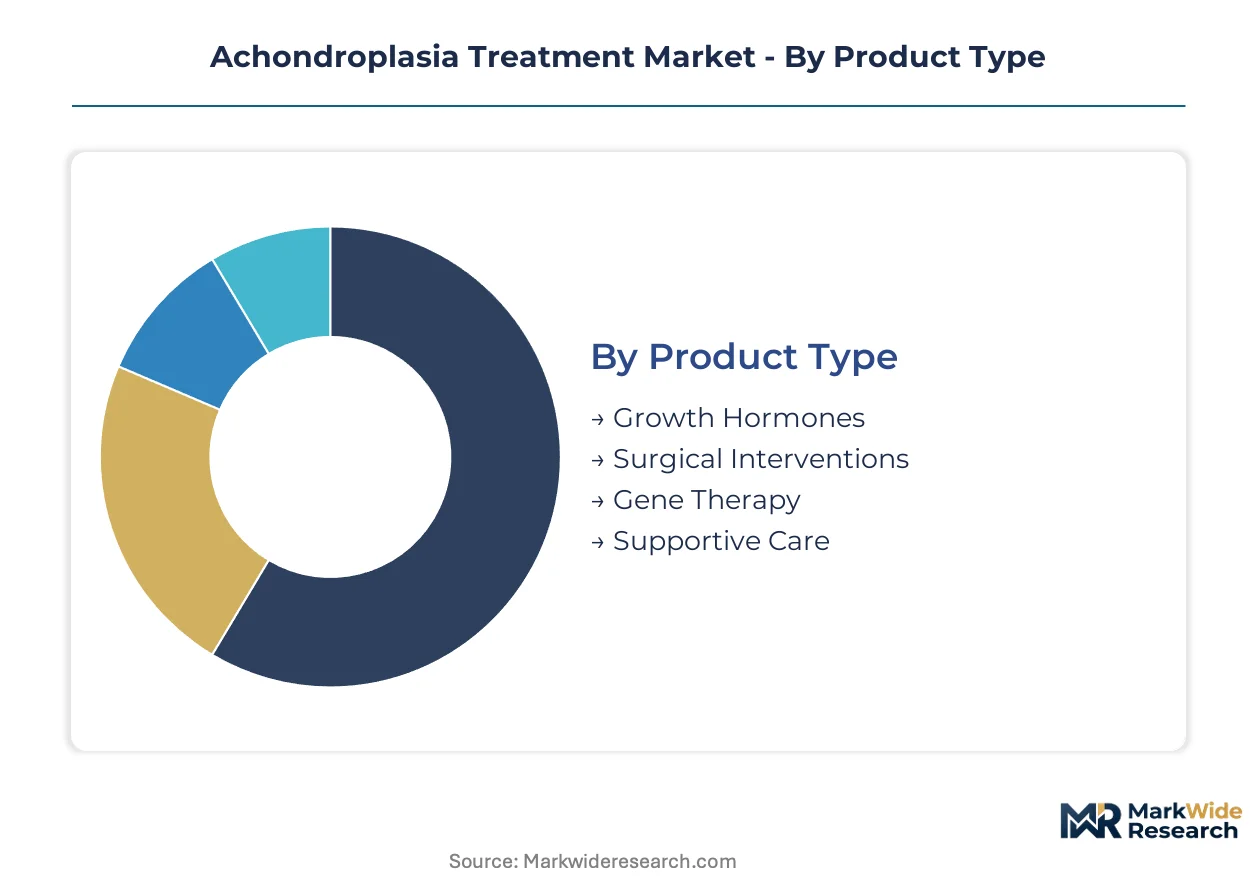
Achondroplasia treatment segmentation reveals shifting clinical priorities as chronic pharmacologic protocols displace episodic surgical interventions. Therapeutic modality selection increasingly hinges on patient age, FGFR3 mutation severity, and site-of-care capabilities rather than historical procedural preferences.
Product Type:
Replacement cycles favor sustained-release biologics over episodic surgical protocols, compressing revenue recognition windows while extending patient lifetime value per treated individual.
- Surgical Interventions:Limb-lengthening osteotomies and craniovertebral decompression procedures utilize external fixation frames and precision-guided distraction osteogenesis. Demand clusters at academic orthopedic centers in the United States and Germany where fellowship-trained specialists manage complex skeletal dysplasia caseloads; procedural volume faces erosion as CNP analog therapy captures growth-modification cases earlier in disease progression.
- Gene Therapy:AAV-mediated FGFR3 knockdown and antisense oligonucleotide approaches target root-cause mutation correction. Pipeline activity concentrates in Boston and Basel biotech clusters where manufacturing scale-up for rare disease viral vectors commands specialized CDMO capacity; regulatory capital requirements filter participation to well-capitalized developers with FDA Office of Rare Diseases rapport.
- Growth Hormones:Recombinant human growth hormone protocols show limited efficacy in FGFR3-driven short stature. Prescription persistence lags other pediatric endocrinology indications due to disappointing linear growth outcomes.
- Supportive Care:Sleep apnea devices, hearing interventions, and physical therapy address comorbidity burden. Disperses across community providers with limited concentration economics.
Volume placements concentrate in Surgical Interventions; the faster expansion belongs to Gene Therapy.
Therapy Area:
Cost tier stratification separates high-complexity genetic interventions from standardized rehabilitation protocols, concentrating margin capture at tertiary academic centers.
- Pediatric Care:Early intervention protocols targeting growth-plate modulation before skeletal maturity. Endocrinology practices at US children's hospitals anchor prescriber concentration; prior authorization complexity favors integrated specialty pharmacy relationships.
- Genetic Disorders:Precision medicine approaches addressing FGFR3 pathway dysregulation. Clinical trial infrastructure requirements limit participation to major metropolitan medical centers with dedicated skeletal dysplasia programs.
- Orthopedic Treatments:Deformity correction and spinal stabilization procedures. Volume moderates as pharmacologic alternatives delay or obviate surgical necessity.
- Rehabilitation Services:Physical and occupational therapy for functional optimization. Fragmented across outpatient networks with limited pricing power.
Patient flows concentrate in Pediatric Care; Genetic Disorders are gaining share fastest.
Delivery Mode:
Application context dictates route selection, with chronic outpatient administration favoring patient-controlled modalities over facility-dependent infusion.
- Subcutaneous:Weekly CNP analog injections via prefilled syringes or auto-injector devices. TransCon extended-release formulations enable home administration, reducing clinic burden at US pediatric endocrinology practices.
- Intravenous:Gene therapy vectors and surgical adjuncts requiring controlled infusion environments. Hospital-based administration preserves reimbursement advantages under medical benefit structures.
- Oral:Limited current applicability for peptide-based achondroplasia therapeutics; gastrointestinal degradation challenges bioavailability.
- Intraosseous:Experimental direct bone-targeted delivery approaches in preclinical development.
Administration volumes concentrate in Subcutaneous; Intravenous maintains premium pricing per episode.
End User:
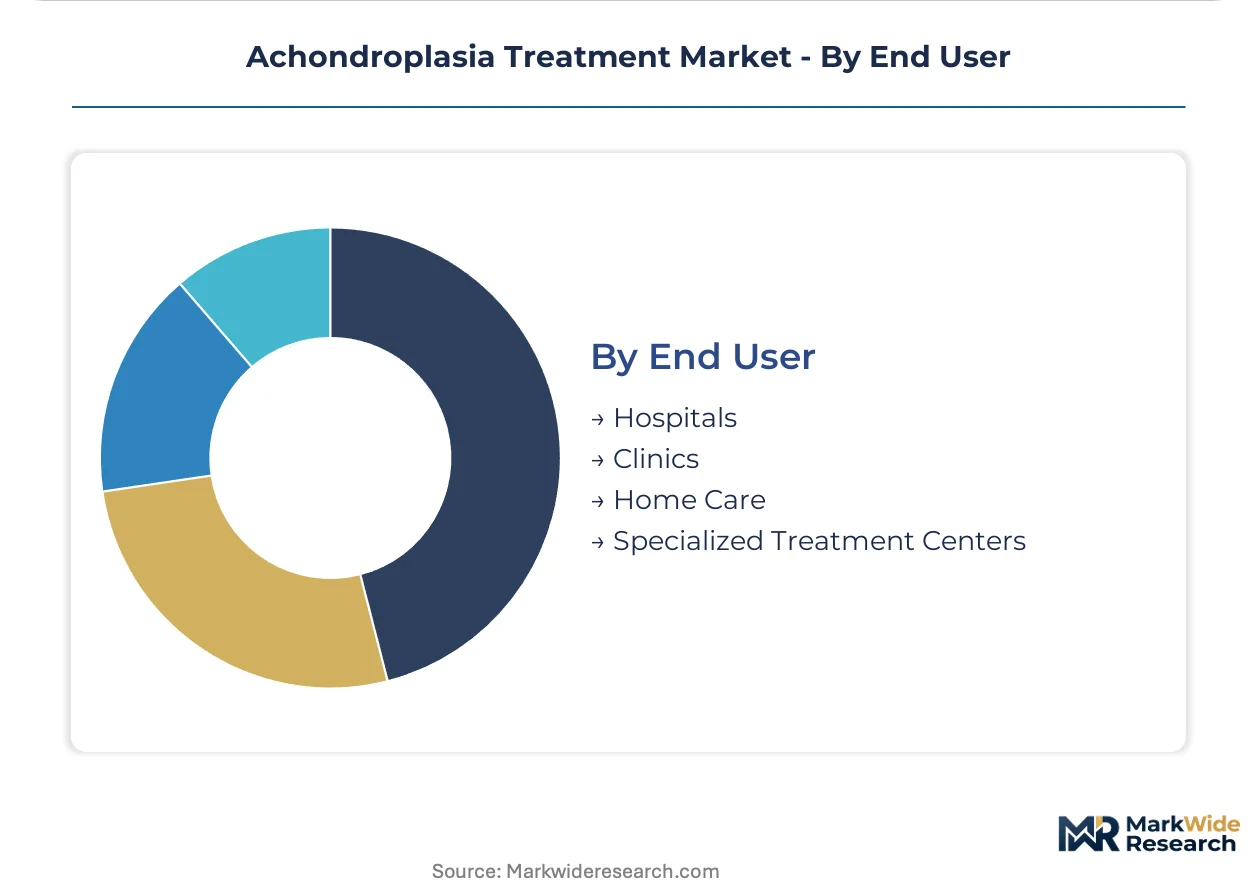
Customer type segmentation reflects site-of-care economics migration from inpatient procedural revenue toward chronic outpatient medication management.
- Specialized Treatment Centers:Dedicated skeletal dysplasia clinics at US academic medical centers and European university hospitals. Concentrated expertise enables complex case management and clinical trial enrollment; these sites anchor KOL networks and payer contracting leverage for novel therapies.
- Home Care:Subcutaneous injection administration by trained caregivers following specialty pharmacy distribution. Reduces travel burden for rural and exurban patient populations across the American Midwest and Southern Germany.
- Hospitals:Surgical intervention sites and emergency management of foramen magnum stenosis complications. Retains high-acuity case concentration.
- Clinics:Community endocrinology and orthopedic practices with limited skeletal dysplasia specialization. Referral relationships to academic centers predominate.
Patient encounters concentrate in Specialized Treatment Centers; Home Care is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for achondroplasia therapeutics clusters in markets with established pediatric rare disease infrastructure and mature reimbursement pathways for biologic therapies. The United States anchors prescriber concentration through specialized skeletal dysplasia clinic networks, while European markets advance under adaptive regulatory frameworks.
United States
FDA's Office of Rare Diseases has streamlined pediatric orphan drug pathways, accelerating conditional approvals for FGFR3-targeted interventions. Major children's hospital networks in Boston, Philadelphia, and Houston operate dedicated skeletal dysplasia centers that concentrate case volumes and anchor clinical trial enrollment. Prior authorization frameworks through commercial payers increasingly cover CNP analog therapy, expanding access beyond Medicaid populations.
Germany
The country's statutory health insurance system reimburses pharmacologic growth modification under orphan drug provisions administered by the Federal Joint Committee. Heidelberg and Berlin university hospitals maintain Europe's highest surgical limb-lengthening caseloads, though procedural volumes moderate as TransCon extended-release formulations diffuse into outpatient protocols. EMA's Committee for Orphan Medicinal Products coordinates closely with Germany's national regulator on pediatric indication expansions.
Japan
PMDA's Sakigake designation system compresses review timelines for rare disease biologics, attracting pipeline investment from both domestic and foreign developers. Tokyo and Osaka pediatric endocrinology departments participate in multinational Phase III trials for CNP analogs, leveraging the country's standardized growth monitoring infrastructure. The Ministry of Health, Labour and Welfare's expanded access programs enable pre-approval utilization in severe cases.
Brazil
ANVISA's expanded access framework for rare diseases permits compassionate use of investigational achondroplasia therapies ahead of formal registration. São Paulo's pediatric hospital networks concentrate specialized expertise, serving as referral hubs for Latin American patients seeking advanced interventions. The national health system SUS is developing rare disease centers of excellence to decentralize care from southeastern metropolitan cores.
United Kingdom
NICE's Highly Specialised Technologies evaluation pathway determines National Health Service coverage for ultra-rare disease interventions, creating predictable access conditions for CNP analog therapies. London's Great Ormond Street Hospital and Birmingham Children's Hospital anchor clinical research networks for genetic skeletal disorders. The MHRA's post-Brexit recognition framework maintains alignment with EMA orphan drug standards while enabling independent accelerated assessments.
Achondroplasia Treatment Market Vendor Landscape
Portfolio diversification through CNP analog platform extensions dominates the current landscape as developers seek dosing convenience differentiation. The market structure concentrates around three strategic archetypes: first-mover biologics specialists with established manufacturing scale, TransCon technology platform owners leveraging sustained-release engineering, and precision genetic medicine developers targeting root-cause FGFR3 pathway modulation. Competitive positioning hinges on regulatory rapport with FDA and EMA rare disease offices, payer contracting leverage at specialized treatment centers, and manufacturing capacity reservations at mammalian cell culture CDMOs.
Within the biologics specialist tier, BioMarin Pharmaceutical and Ascendis Pharma exemplify contrasting platform strategies—recombinant peptide manufacturing scale versus extended-release formulation engineering. BridgeBio Pharma occupies a position representing precision genetic medicine approaches, with pipeline assets targeting direct FGFR3 pathway modulation. These three developers anchor the competitive dynamic, each leveraging distinct technical capabilities to secure prescriber preference and reimbursement favorable positioning.
| Leading Market Players |
|---|
| BioMarin Pharmaceutical |
| Ascendis Pharma |
| BridgeBio Pharma |
| RIBOMIC |
| Pfizer |
| Novartis |
| Sanofi |
| Novo Nordisk |
| PhaseBio Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
EMA's MDR sustainability and traceability mandates gate qualified supply access for recombinant CNP analog manufacturers, while simultaneously creating premium-tier pricing eligibility for facilities demonstrating mammalian cell culture carbon footprint reduction. Compliance documentation burdens filter contract manufacturing participation toward Swiss and German CDMOs with established environmental management certifications, compressing available capacity and anchoring price premiums at the production source.
Pricing Analysis
Volume placements concentrate in Surgical Interventions while margin capture clusters in Gene Therapy development-stage licensing. Three-tier pricing structure across premium, standard, and economy levels separates TransCon extended-release formulations from daily injection protocols and from supportive care bundles. Pricing pressure stems from Medicaid rebate obligations in the United States and statutory health insurance reference pricing in Germany. Pediatric hospital systems demonstrate highest price sensitivity due to bundled reimbursement constraints, while specialty pharmacy networks retain pricing leverage through limited distribution arrangements.
Supply Chain Analysis
Regional distribution centers in Basel, Switzerland and Frankfurt, Germany anchor hub-and-spoke patterns for temperature-controlled biologics movement. Active pharmaceutical ingredient production rests on mammalian cell culture capacity concentrated in Switzerland, Germany, and the United States. Supply chain risk centers on single-source vulnerability for recombinant peptide starting materials and specialized viral vector manufacturing for gene therapy candidates. Distribution runs through integrated specialty pharmacy networks in North America and hospital-centric procurement consortia in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where FDA post-market surveillance obligations and EMA adaptive pathway capital requirements force subscale developers toward partnership or exit. Manufacturing scale and regulatory rapport have become binary survival filters.
For Market Incumbents: Deploy manufacturing capacity reservations as the priority defensive lever. Secure multi-year mammalian cell culture commitments at Swiss and German CDMOs before competitor lock-up. Anchor payer contracting leverage through integrated specialty pharmacy relationships that compress prior authorization friction for CNP analog therapies. Counter TransCon extended-release substitution threats by accelerating internal sustained-release platform investments. For New Entrants and Emerging Players: Specialty pharmacy networks represent the most penetrable channel infrastructure for subcutaneous CNP analog distribution. Target Brazil's ANVISA expanded access framework as a pre-registration commercialization beachhead where compassionate use builds clinical evidence without full regulatory capital deployment. Pursue white-space positioning in algorithmic skeletal dysplasia screening tools compliant with EU AI Act transparency requirements. For Investors and Strategic Acquirers: EMA conditional approval decisions for FGFR3-targeted therapies are the leading indicator that gene therapy convergence timelines are compressing. Position acquisition screening around precision genetic medicine developers with AAV manufacturing scale-up partnerships and established FDA Office of Rare Diseases rapport. Long-term viability over the next decade hinges on curative intervention displacement of chronic pharmacologic management.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III enrollment at US children's hospitals anchors FDA priority review eligibility for CNP analogs. |
| Manufacturing Scale-Up | Mammalian cell culture capacity reservations at Swiss CDMOs secure supply continuity for recombinant peptide production. |
| Regulatory Approval Pathway | EMA adaptive pathway engagement compresses development-to-commercialization cycles for rare disease biologics. |
| Licensing Agreement | TransCon technology platform partnerships extend dosing convenience differentiation against daily injection competitors. |
| Pipeline Diversification | AAV-mediated FGFR3 knockdown programs position developers for curative intervention displacement of chronic therapy. |
Methodological Framework
Document review covered FDA orphan drug designations, EMA Committee for Orphan Medicinal Products opinions, and ClinicalTrials.gov protocol registrations, complemented by interviews with pediatric endocrinologists, specialty pharmacy formulary directors, and rare disease payer access specialists. Secondary validation drew from SEC 10-K filings of publicly traded developers, hospital procurement database extracts, and GPO contract documentation. Bottom-up patient flow modeling and top-down therapeutic modality revenue triangulation anchored segmentation outputs.
Market size and growth trajectory outputs reflect multi-dimensional segmentation across therapeutic modality, patient age cohort, administration route, and regional regulatory cluster. CAGRs were derived from patient prevalence epidemiology, treatment penetration assumptions, and pricing evolution across the projection horizon. Forecast inputs incorporated pediatric endocrinology workforce density by metropolitan statistical area, prior authorization approval rate trends, and manufacturing capacity utilization at mammalian cell culture facilities.
Caveats apply where FDA gene therapy manufacturing guidance revisions, EMA adaptive pathway eligibility contractions, or mammalian cell culture supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding CNP analog reimbursement persistence, gene therapy clinical translation timelines, and competitive entry sequencing. Periodic stress-testing of base assumptions against regulatory filing cadence and manufacturing capacity expansion announcements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Polymyalgia Rheumatica Treatment Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Paediatric Sports Medicine Market
Specialty Medicine
Global Thyroid Disorder Market
Specialty Medicine
Global Focal Segmental Glomerulosclerosis Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Sjogrens Syndrome Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Multiple Endocrine Neoplasia Market