
 Global Consumer Healthcare Products Market | 2026-2036
Global Consumer Healthcare Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Consumer Healthcare Products Market Foresight
The EU Green Deal is pivoting formulation priorities across European consumer health portfolios toward biodegradable packaging and plant-derived excipients. Johnson & Johnson anchors its European OTC operations through pharmacy-centric distribution networks that emphasize pharmacist counseling. Bayer AG differentiates via its specialist position in topical analgesics and dermatological self-care. Nestlé S.A. extends its consumer health reach through science-backed nutritional supplement lines that compete with traditional pharmaceutical offerings.
Consumer healthcare products comprise over-the-counter medicines, dietary supplements, and personal care items formulated for self-administration without prescription oversight, typically manufactured through direct compression, wet granulation, or soft-gel encapsulation processes yielding standardized dosages for symptom relief and wellness maintenance. Vitamins and personal care categories dominate current revenue pools due to recurring purchase behavior and shelf visibility in mass retail channels. Digestive care and pain relief segments attract faster velocity as post-pandemic stress-related conditions and dietary shifts expand self-treatment behavior. E-commerce platforms reshape end-user access by collapsing traditional wholesale-to-pharmacy timelines and enabling direct-to-consumer subscription models for nutritional support products.
FDA oversight of OTC monographs in the United States, EMA's evolving borderline product classifications in Europe, and China's NMPA accelerated review pathways for traditional medicine-derived supplements collectively determine which formulations achieve market access and label claims. REACH compliance in Europe and evolving state-level CBD regulations in the United States add compliance layers that favor established manufacturers with dedicated regulatory affairs capacity. Stakeholders must monitor how pharmacovigilance data requirements and digital health platform integrations reshape competitive moats between legacy pharmaceutical operators and agile direct-to-consumer entrants.
Market Dynamics
Self-medication behavior among aging demographics is compressing the traditional prescription-to-OTC transition timeline, while EU Green Deal packaging mandates force simultaneous reformulation of container materials and supply chain logistics across European manufacturing footprints.
Growth Catalysts
- REACH-compliant biodegradable excipients:European manufacturers are accelerating plant-derived capsule shell adoption to preempt ECHA enforcement timelines on petroleum-based alternatives.
- China's NMPA traditional medicine pathways:Accelerated review tracks for herbal-derived supplements are shortening market entry cycles for digestive and immune support formulations.
- Pharmacy chain digitization:Tier-one Chinese cities are deploying AI-powered shelf management systems that personalize OTC recommendations based on purchase history and symptom inputs.
Market Restraints
- API concentration in Indian manufacturing clusters:Over-reliance on Hyderabad and Ahmedabad for bulk vitamin precursors creates single-point vulnerability for global supplement supply.
- FDA OTC monograph modernization delays:Stalled administrative proceedings leave sunscreen and antacid categories in regulatory limbo, blocking innovation investment.
- Plant-based excipient cost premiums:Hydroxypropyl methylcellulose and pullulan alternatives command 40-60% price deltas versus gelatin, compressing margin structures for mass-market positioning.
Strategic Opportunities
- German pharmacy counseling integration:OTC brands embedding pharmacist training modules capture preferential shelf placement in the country's 20,000+ Apotheke network.
- Subscription-based nutritional support:Direct-to-consumer platforms bypass wholesale markups while capturing recurring revenue through personalized regimen algorithms.
- EU AI Act health application carve-outs:Symptom-checker integrations on packaging create defensible data assets while navigating emerging liability frameworks.
Industry Challenges
- Pharmacovigilance data infrastructure gaps:Legacy OTC manufacturers lack real-world evidence collection systems comparable to prescription drug surveillance networks, exposing them to post-market label revision risks.
- Cross-border e-commerce customs complexity:Divergent national classifications for borderline products between food, cosmetic, and pharmaceutical categories trigger detention and relabeling costs.
- Soft-gel encapsulation technician scarcity:Specialized knowledge of rotary die and seamless encapsulation processes concentrates among aging workforces in Italy and Japan.
Report Scope
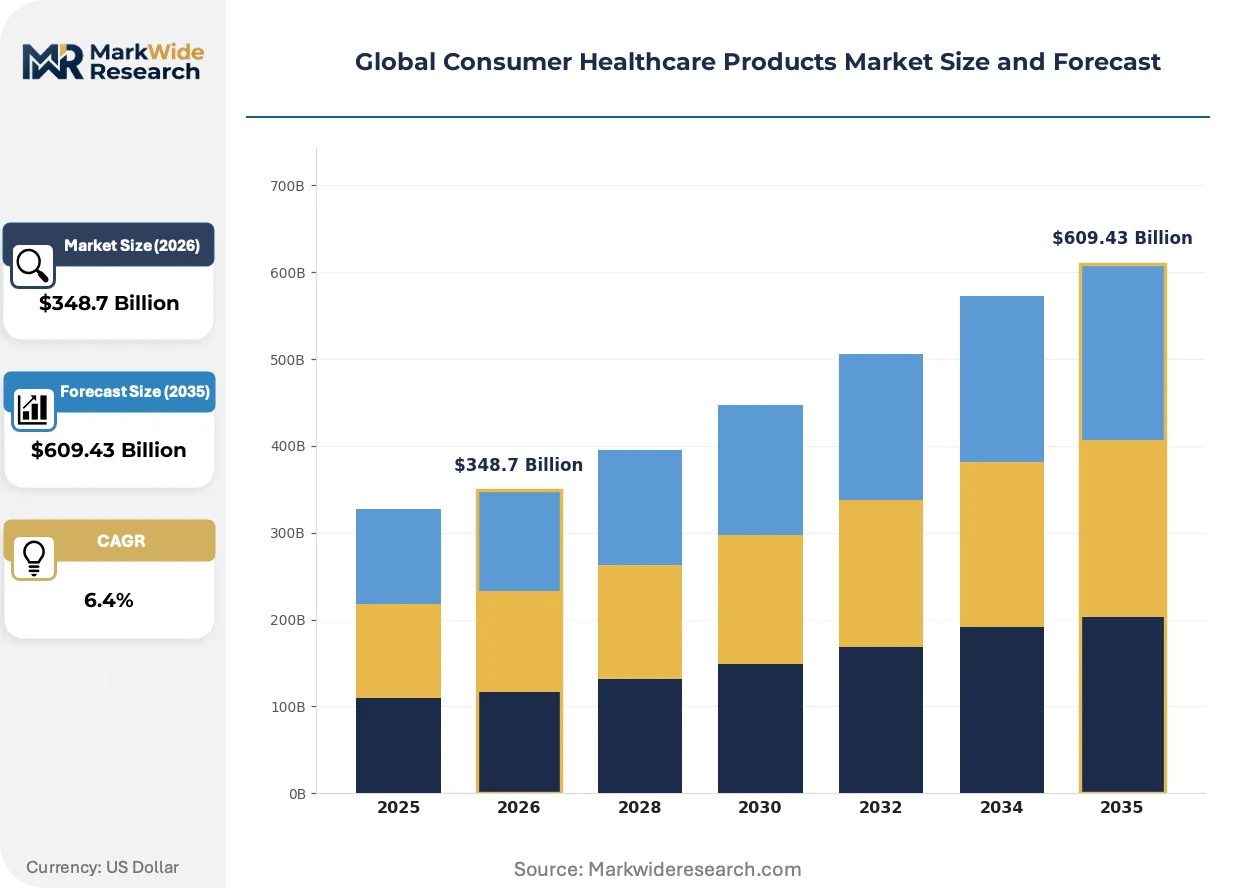
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Consumer Healthcare Products Market |
| Market Size in 2026 | $348.7 Billion |
| Market Size in 2035 | $609.43 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
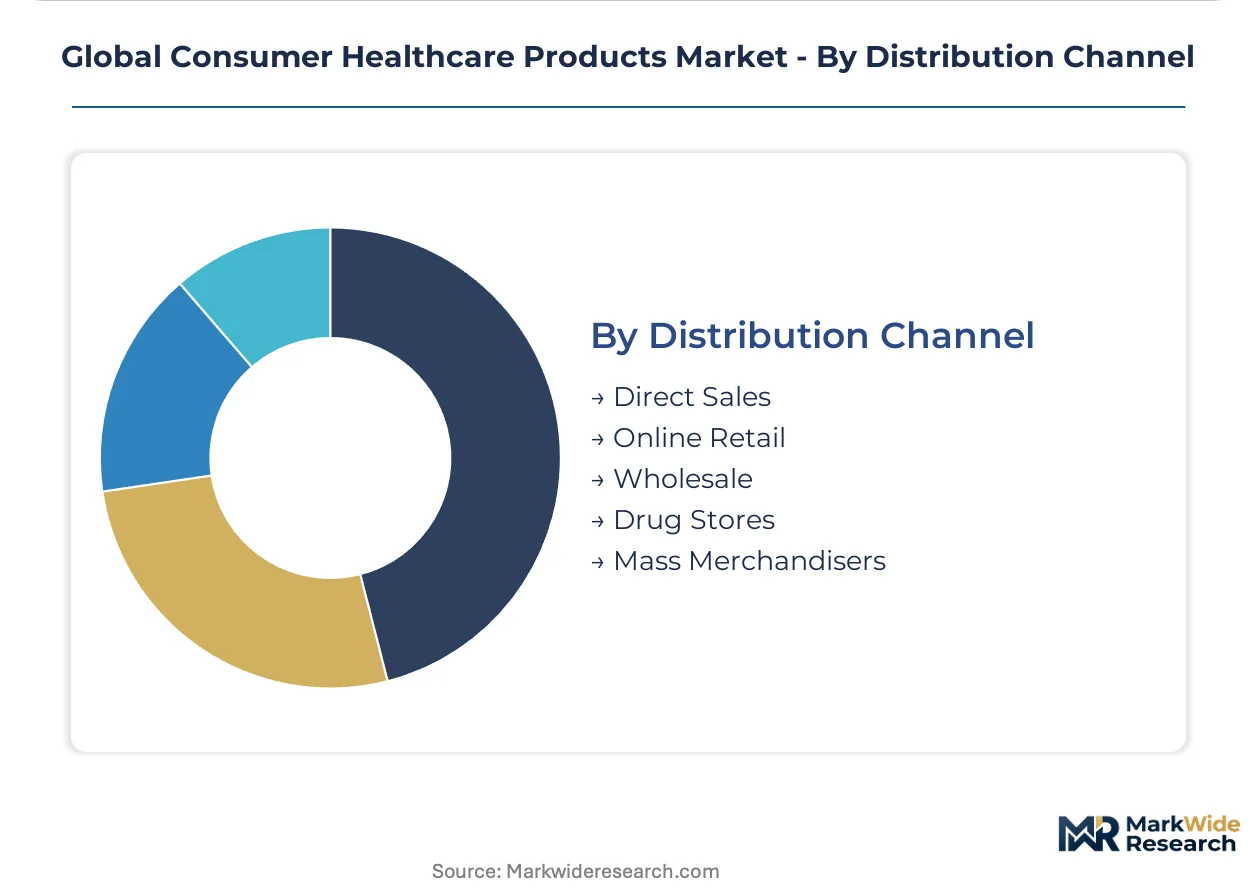
| Segmentation | Product Type: Vitamins, Personal Care, Oral Care, Digestive Care, Pain Relief Application: Wellness, Preventive Care, Symptom Management, Nutritional Support, First Aid End User: Pharmacies, Supermarkets, E-commerce Platforms, Specialty Stores, Healthcare Providers Distribution Channel: Direct Sales, Online Retail, Wholesale, Drug Stores, Mass Merchandisers |
| Companies Covered | GlaxoSmithKline plc, Johnson & Johnson, Pfizer Inc., Bayer AG, Procter & Gamble, Sanofi S.A., Abbott Laboratories, Reckitt Benckiser Group plc, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Consumer Healthcare Products Market Shifts & Advancements
Digital health platform integration is collapsing the distance between symptom onset and product acquisition, while sustainable packaging mandates force material science investments that reshape competitive cost structures.
Continuous manufacturing systems for solid-dose OTC products are rewriting batch economics for pain relief and digestive categories. Mid-sized European contract manufacturers are adopting these lines to serve private-label pharmacy chains demanding shorter lead times. The technology is compressing minimum viable production runs from hundreds of thousands to tens of thousands of units, enabling regional flavor and dosage customization.
EMA's evolving borderline product classification guidance is forcing portfolio resegmentation between food supplements and medicinal products. Manufacturers with dual-category registrations face compliance cost duplication, while those betting exclusively on one classification risk stranding assets if rulings shift. Dermatological topicals and oral care products with active pharmaceutical ingredients sit in the highest uncertainty zone.
Subscription bundling of vitamins with diagnostic biomarker testing is displacing single-transaction retail purchasing among urban professionals in Shanghai and Seoul. Pharmacy chains are responding with their own membership programs, but lack the data integration depth of pure-play digital health platforms. The model concentrates lifetime value capture among brands owning both product and testing infrastructure.
Global Consumer Healthcare Products Market Segmentation
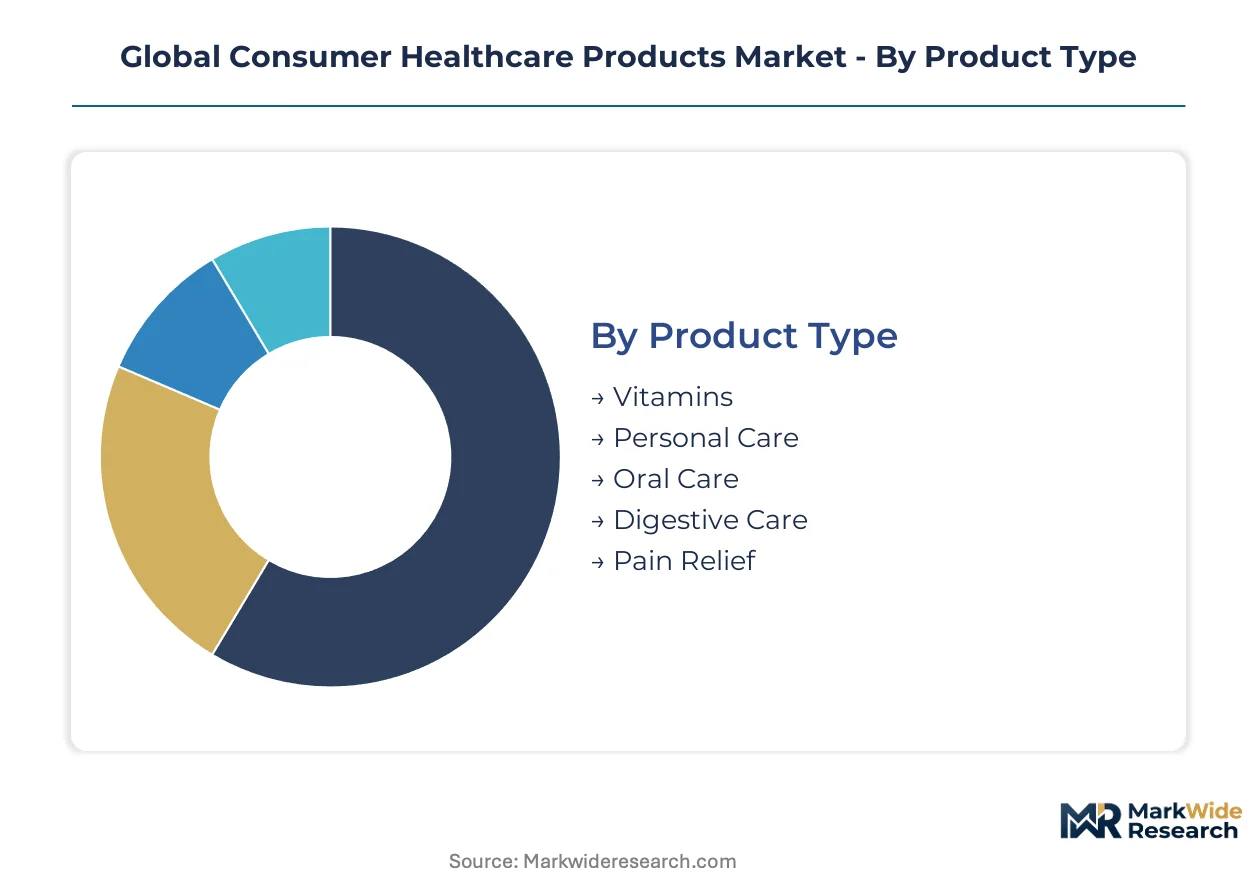
Consumer healthcare products fragment across multiple demand axes that determine formulation priorities, packaging specifications, and channel economics. Understanding how product types, applications, and distribution pathways intersect reveals where margin pools concentrate and where substitution risks threaten incumbent positions.
Product Type:
Upgrade cycles in consumer healthcare track shifting wellness priorities rather than obsolescence, with consumers trading up from basic symptom relief toward preventive formulations and clean-label positioning.
- Vitamins:Multivitamin complexes and single-nutrient supplements dominate pharmacy shelf space through recurring purchase patterns. Demand concentrates in China's tier-one cities where pharmacy digitization enables personalized regimen recommendations based on purchase history.
- Personal Care:Dermatological self-care products including topical analgesics and skin health formulations carry premium positioning through pharmacist counseling integration. German Apotheke networks drive preferential placement for brands embedding training modules that elevate professional recommendation rates.
- Oral Care:Toothpaste and mouthwash formulations with active pharmaceutical ingredients sit in EMA borderline classification uncertainty between cosmetic and medicinal categories.
- Digestive Care:Probiotic and enzyme supplements benefit from post-pandemic dietary shift awareness and aging population self-medication trends across European markets.
- Pain Relief:Topical and oral analgesic categories face FDA OTC monograph modernization delays that stall ingredient innovation in the United States.
Volume placements concentrate in Vitamins; the faster expansion belongs to Digestive Care.
Application:
Cost tier differentiation separates premium positioned products with clinical validation from economy alternatives competing on shelf price and promotional intensity.
- Wellness:General health maintenance products target employed urban demographics with disposable income for discretionary supplementation. Subscription bundling with diagnostic biomarker testing displaces single-transaction retail purchasing among professionals in Shanghai and Seoul.
- Preventive Care:Immune support and cardiovascular health formulations attract pharmacy chain investment in AI-powered recommendation systems that match products to risk profiles.
- Symptom Management:Cold, flu, and allergy relief products face compressed margins from private-label competition in mass retail channels.
- Nutritional Support:Condition-specific formulations for pregnancy, athletic performance, or senior nutrition command price premiums through science-backed positioning.
- First Aid:Wound care and emergency treatment supplies concentrate procurement decisions in healthcare provider and institutional channels.
Revenue gravity sits with Wellness; Preventive Care is gaining share fastest through platform-enabled personalization.
End User:
Customer type determines service intensity requirements, with professional channels demanding training support and direct-to-consumer platforms requiring algorithmic engagement infrastructure.
- Pharmacies:Community and chain pharmacies anchor European OTC distribution through regulatory frameworks requiring pharmacist involvement in self-medication guidance.
- Supermarkets:Mass retail placement prioritizes shelf visibility and promotional mechanics over professional recommendation.
- E-commerce Platforms:Direct-to-consumer channels collapse wholesale-to-pharmacy timelines and enable subscription models that capture recurring revenue through personalized regimen algorithms.
- Specialty Stores:Nutrition and natural health retailers serve enthusiast segments willing to pay clean-label and certified organic premiums.
- Healthcare Providers:Hospital and clinic dispensing channels concentrate demand for clinical-grade formulations with documented efficacy profiles.
Transaction volume concentrates in Pharmacies; E-commerce Platforms show the steepest expansion trajectory as digital health integration accelerates.
Distribution Channel:
Supply concentration in Indian API manufacturing clusters shapes channel risk profiles, with direct sales and captive distribution offering hedge against external supply disruption.
- Direct Sales:Manufacturer-controlled channels bypass wholesale markups and capture customer data for regimen optimization.
- Online Retail:Third-party marketplace presence expands reach but exposes brands to price comparison and margin compression.
- Wholesale:Traditional distributor networks retain importance for pharmacy and institutional channel access despite digitization pressure.
- Drug Stores:Dedicated pharmacy chains in China deploy AI-powered shelf management systems that personalize OTC recommendations.
- Mass Merchandisers:Big-box retailers concentrate volume for vitamins and personal care through promotional pricing and private-label competition.
Shipment volume concentrates in Drug Stores; Online Retail climbs the fastest as cross-border e-commerce customs frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters in India and China supply active pharmaceutical ingredients to formulation plants across Germany, the United States, and Japan, creating a geographic divide between bulk chemical production and finished consumer healthcare goods.
United States
FDA OTC monograph modernization delays have stalled sunscreen and antacid category innovation, leaving manufacturers dependent on legacy ingredient approvals. State-level CBD regulations continue diverging, forcing national brands to maintain multiple label variants. New Jersey and Pennsylvania host concentrated soft-gel encapsulation capacity serving North American private-label demand.
Germany
The EU Green Deal's sustainable packaging mandates are compelling reformulation of supplement containers across the country's manufacturing footprint. REACH-compliant biodegradable excipient adoption accelerates as ECHA enforcement timelines approach. Bavaria's specialized chemical producers supply plant-derived capsule shells to European OTC brands.
China
NMPA accelerated review pathways for traditional medicine-derived supplements shorten market entry cycles for digestive and immune support formulations. Tier-one cities deploy AI-powered pharmacy shelf management systems that personalize OTC recommendations. Yangtze River Delta manufacturing hubs integrate continuous processing lines for solid-dose production.
India
API concentration in Hyderabad and Ahmedabad creates single-point vulnerability for global vitamin precursor supply. CDSCO's evolving borderline product classifications between food supplements and pharmaceuticals generate compliance uncertainty. Gujarat's excipient producers expand hydroxypropyl methylcellulose capacity to serve European gelatin substitution demand.
Japan
PMDA's stringent stability testing requirements for functional foods extend development timelines for probiotic and enzyme supplement entrants. METI's support for continuous manufacturing technology adoption enables shorter production runs for regional flavor customization. Osaka-based encapsulation specialists preserve rotary die process knowledge amid workforce aging.
Global Consumer Healthcare Products Market Competitive Landscape
The competitive structure tilts toward diversified healthcare conglomerates with prescription-to-OTC portfolio breadth. Consolidation among legacy pharmaceutical operators has reduced the number of independent OTC specialists capable of navigating multi-jurisdictional regulatory frameworks. Three archetypes dominate: science-backed nutritional supplement platforms, pharmacy-centric counseling-integrated brands, and mass-market personal care operators with dermatological positioning. Capacity expansion in continuous manufacturing systems and strategic partnerships for biodegradable packaging sourcing represent the primary competitive moves reshaping manufacturing economics.
Among diversified healthcare conglomerates, Johnson & Johnson, Bayer AG, and Nestlé S.A. exemplify distinct strategic positioning archetypes within the consumer healthcare segment. Johnson & Johnson represents the pharmacy-centric counseling-integrated model through its emphasis on professional recommendation channels. Bayer AG occupies a position within the science-backed topical and dermatological self-care specialization tier. Nestlé S.A. anchors the nutritional supplement platform approach, competing directly with traditional pharmaceutical offerings through wellness-oriented positioning. These three entities collectively illustrate how conglomerate-scale operators leverage regulatory affairs capacity and multi-category registration expertise to navigate EMA borderline classification uncertainties and FDA OTC monograph complexities.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Pfizer Inc. |
| Bayer AG |
| Procter & Gamble |
| Sanofi S.A. |
| Abbott Laboratories |
| Reckitt Benckiser Group plc |
| Nestlé S.A. |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between pharmacist-counseled premium SKUs and mass-market economy alternatives manifests in both pricing power and sourcing configurations, with EU Green Deal compliance costs concentrating in European manufacturing footprints while Indian and Chinese API supply anchors commodity-tier economics.
Pricing Analysis
Margin tightening in mass-market vitamin and personal care tiers reflects gelatin-to-plant-based excipient substitution costs and REACH compliance investments. Three-tier pricing structure across premium pharmacist-recommended, standard retail, and economy private-label levels tracks certification depth and counseling integration. Cost-down pressure on standard-tier oral care accelerates because EMA borderline classification uncertainty forces dual-registration compliance spend. Pharmacy chains in Germany exhibit lowest price sensitivity due to regulatory counseling requirements, while supermarket mass merchandisers in China face highest sensitivity from AI-enabled price comparison tools.
Supply Chain Analysis
Active pharmaceutical ingredient supply rests on Hyderabad and Ahmedabad manufacturing clusters for vitamin precursors, Yangtze River Delta hubs for excipient processing, and Bavarian specialty chemical producers for plant-derived capsule shells. Raw material dependencies include hydroxypropyl methylcellulose, pullulan alternatives, and petroleum-derived gelatin stocks. Single-source vulnerability concentrates in Indian API concentration, exposing formulation plants to regional disruption. Distribution runs through pharmacy-centric wholesale networks in Europe, AI-managed drug store chains in China, and direct-to-consumer platforms collapsing traditional wholesale-to-retail timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous manufacturing technology is displacing batch processing systems across solid-dose OTC production, compressing minimum viable runs and enabling regional customization that legacy infrastructure cannot match.
For Market Incumbents: Extend regulatory affairs capacity into dual-category registration expertise to hedge EMA borderline classification shifts, and deepen backward integration into biodegradable excipient supply through partnerships with Bavarian and Gujarat producers. Threat concentration sits with agile direct-to-consumer entrants capturing subscription revenue through diagnostic bundling.
For New Entrants and Emerging Players: Digital health platforms represent the most penetrable channel for bypassing wholesale markups and capturing recurring revenue through personalized regimen algorithms. White-space concentration sits in tier-one Chinese cities where pharmacy AI systems lack integrated diagnostic infrastructure, and in German Apotheke networks seeking training-embedded brand partnerships. Go-to-market execution should prioritize biomarker testing bundling to displace single-transaction retail purchasing.
For Investors and Strategic Acquirers: Re-rating potential sits with contract manufacturers possessing continuous processing lines and plant-derived excipient sourcing relationships given EU Green Deal enforcement timelines. Long-term viability over the next decade favors operators with regulatory affairs scale spanning FDA OTC monograph, EMA borderline, and NMPA traditional medicine pathways. Watch FDA administrative proceedings on sunscreen and antacid modernization as inflection signal for innovation investment release.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Mid-sized European contract manufacturers deploy shorter-run lines to serve private-label pharmacy chains demanding regional flavor customization. |
| Biodegradable Packaging Transition | REACH-compliant container reformulation preempts ECHA enforcement timelines while reshaping competitive cost structures across European footprints. |
| Pharmacy AI Integration | Tier-one Chinese drug chains deploy shelf management systems that personalize OTC recommendations based on symptom inputs and purchase history. |
| Subscription Model Launch | Direct-to-consumer platforms capture recurring revenue through diagnostic biomarker bundling that displaces single-transaction retail purchasing. |
| Dual-Category Registration Investment | Portfolio resegmentation between food supplements and medicinal products hedges EMA borderline classification uncertainty for dermatological topicals. |
Research Methodology
Multi-period observation of NMPA approval timelines, EMA borderline classification rulings, and FDA OTC monograph proceedings anchored the trend analysis, supplemented by interviews with regulatory affairs directors at diversified healthcare conglomerates, pharmacy chain category managers in Germany and China, contract manufacturing executives, and excipient procurement leads. Secondary validation drew from FDA docket filings, EMA public assessment reports, NMPA traditional medicine registration databases, and customs trade data on API flows. Bottom-up volume modeling and top-down value reconciliation triangulated market sizing across product type, application, end user, and distribution channel dimensions.
An input-output matrix framework mapped formulation demand to API and excipient supply concentrations, with segmentation modeling spanning vitamins, personal care, oral care, digestive care, and pain relief categories across wellness, preventive care, symptom management, nutritional support, and first aid applications. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory pathway acceleration and channel digitization rates. Forecast inputs included pharmacist counseling integration depth, continuous manufacturing adoption curves, and biodegradable packaging cost premium elasticity.
Several conditions sit outside the modeled scope, including potential FDA OTC monograph modernization administrative actions, REACH enforcement timeline acceleration, and geopolitical disruption to Indian API manufacturing clusters. Forecasts reflect assumptions on regulatory pathway stability and excipient substitution cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Italy Hand Sanitizer Market
Healthcare Products
United States Infrared Sauna Market
Healthcare Products
Artificial Saliva Market
Healthcare Products
Global Life Science Products Market
Healthcare Products
Birth Tissue Products Market
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
Ejiao Health Products Market
Healthcare Products
Menstrual Sponge Market
Healthcare Products
Organ Care Products Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
Blood and Blood Components Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
Nursing Products Market
Healthcare Products
Isolation Gowns Market