
 Europe Alcohol Ingredients Market | 2026-2036
Europe Alcohol Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Alcohol Ingredients Market Foresight
Natural botanical extracts is repositioning synthetic flavor economics across European alcohol formulation. DSM-Firmenich AG leverages its integrated flavor and fragrance pipeline to dominate premium spirit applications. Kerry Group plc anchors its position through specialized yeast and fermentation solutions for craft breweries. Cargill Incorporated competes on sweetener and texturizer scale for mass-market beer producers.
Europe alcohol ingredients encompass flavorings, sweeteners, coloring agents, preservatives, and fermentation inputs formulated to meet beverage-specific sensory, stability, and regulatory requirements, with ethanol-soluble compounds typically specified at 40-60% active concentration for optimal dispersion in distilled products. These inputs serve primarily to standardize taste profiles, extend shelf life, and enable product differentiation across beer, wine, spirits, and ready-to-drink cocktails. Flavorings command the dominant margin pool given premiumization trends in spirits and craft beverages, while yeast and enzyme concentrates represent the fastest-expanding category driven by craft brewery proliferation. Application demand concentrates in beer production due to volume scale, though spirits distillation generates higher per-unit ingredient value.
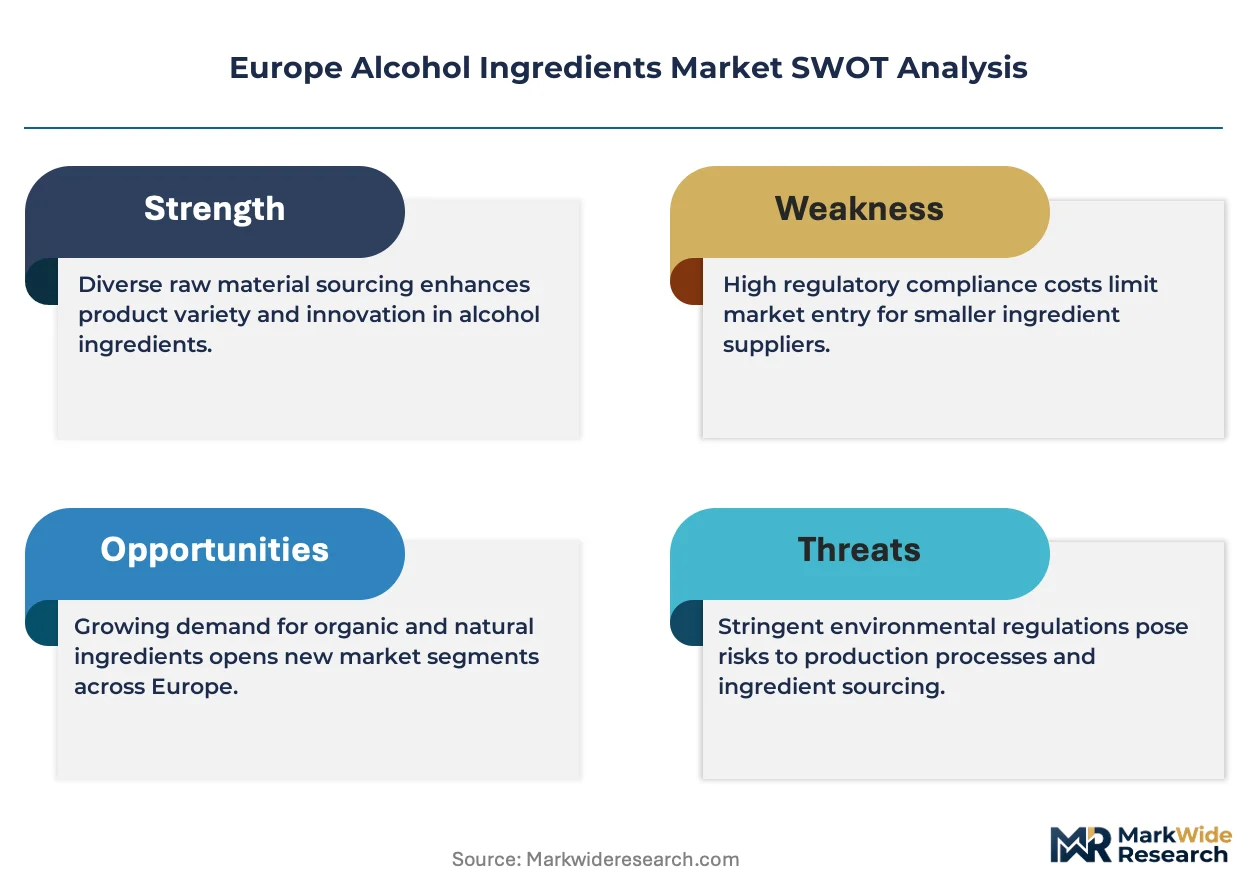
EMA food additive assessments, EFSA flavoring substance evaluations, and EU REACH chemical registration requirements collectively govern ingredient approval timelines and compositional limits across member states. These frameworks elevate compliance costs for new entrants while favoring incumbents with established safety dossiers and centralized regulatory affairs capabilities. Stakeholders must monitor evolving EU Green Deal sustainability mandates for agricultural input traceability and carbon footprint disclosure.
Market Dynamics
The EU Green Deal's carbon footprint disclosure mandates are compressing formulation timelines for alcohol ingredient suppliers. EFSA additive assessments now require extensive botanical origin documentation, forcing reformulation investments across the value chain.
Growth Catalysts
- EU Farm to Fork Strategy:Tightening additive disclosure rules compel manufacturers toward certified natural extracts, expanding addressable premium for botanical suppliers.
- Craft brewery proliferation:Small-batch producers across Germany and France drive specialized yeast and enzyme concentrate procurement volumes.
- Spirits premiumization:Southern European distillers concentrate demand for high-margin flavoring compounds in ultra-premium segments.
Market Restraints
- Regulatory friction:EMA food additive assessment timelines extend 18-24 months, freezing product launch schedules for novel compounds.
- Input cost volatility:Agricultural commodity swings in wheat and barley concentrate margin pressure on fermentation input suppliers.
- Supply concentration risk:Botanical extract sourcing clusters in Mediterranean growing regions, exposing processors to climate-driven harvest variability.
Strategic Opportunities
- Emerging RTD cocktails:Ready-to-drink format expansion creates formulation demand for shelf-stable, ethanol-soluble flavor systems.
- CSRD traceability mandates:Corporate Sustainability Reporting Directive requirements position agricultural input provenance as a competitive differentiator.
- Technology convergence:Precision fermentation and enzymatic biotransformation enable novel terpene production without botanical cultivation constraints.
Industry Challenges
- REACH registration complexity:Chemical substance dossier preparation consumes 12-18 months for novel alcohol-soluble compounds, delaying commercialization.
- Integration friction:Legacy distillery equipment requires retrofitting for enzyme-optimized mashing processes, elevating capital deployment requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Alcohol Ingredients Market |
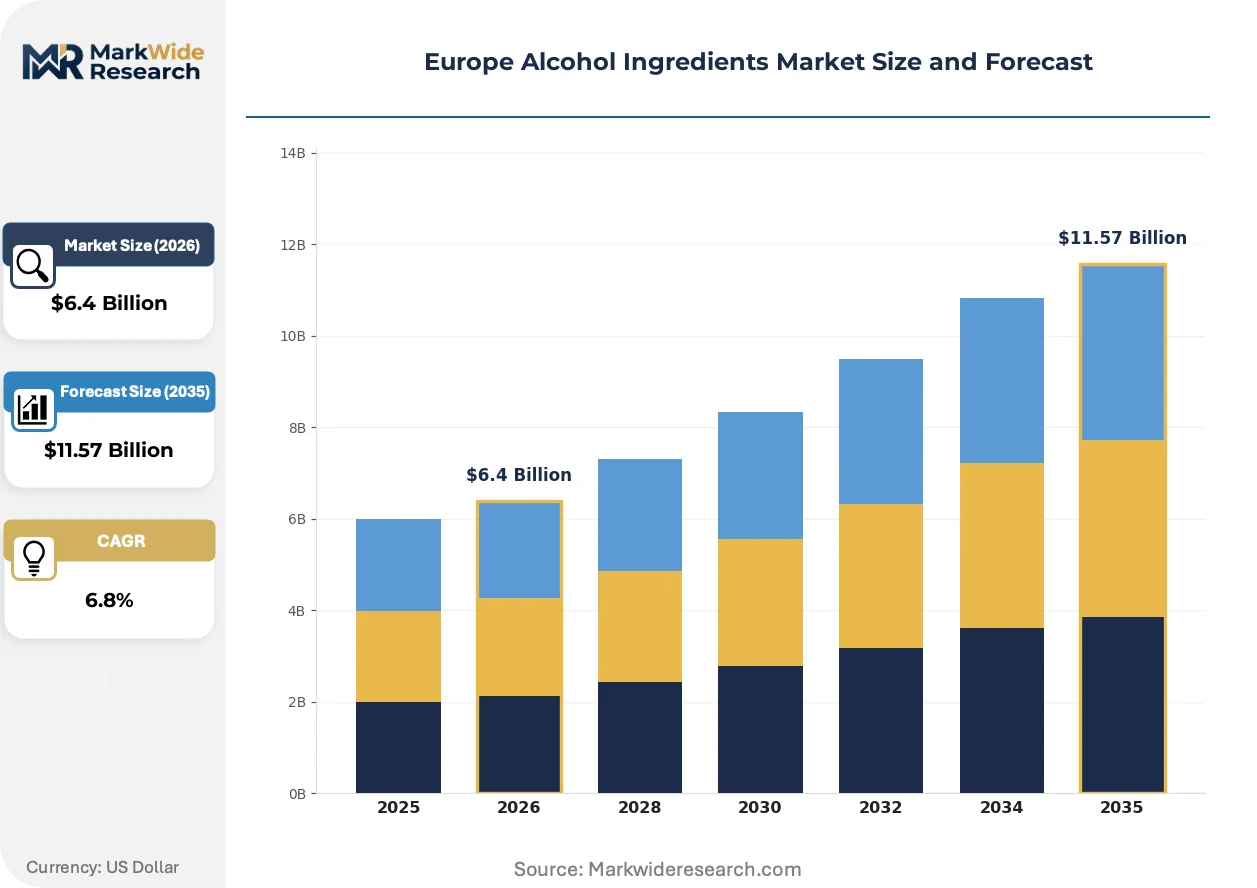
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Flavorings, Sweeteners, Coloring Agents, Preservatives Application: Beer Production, Wine Making, Spirits Distillation, Cocktails End User: Beverage Manufacturers, Restaurants, Retail Stores, Breweries Form: Liquid, Powder, Concentrate, Crystal |
| Companies Covered | Sensient Technologies, Archer Daniels Midland Company, DSM-Firmenich AG, Bio Springer SA, Cargill Incorporated, Kerry Group plc, Angel Yeast, Chr. Hansen, Lallemand Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Alcohol Ingredients Market Shifts & Advancements
Natural botanical extraction methods are compressing synthetic flavor economics across European formulation labs. Distillers and breweries face simultaneous pressure from sustainability mandates and premium positioning requirements.
Supercritical CO2 extraction technology is overtaking solvent-based methods for essential oil recovery from juniper, citrus, and spice matrices. Premium gin and vermouth producers in France and Spain are adopting these systems at 40% capacity expansion rates. The shift is overtaking hexane-dependent supply chains and enabling organic certification compliance without residue concerns.
EFSA flavoring substance evaluations now require expanded toxicological data packages for botanical candidates. The industrial consequence is a 30% expansion of safety dossier preparation costs for novel extract submissions. Small and mid-sized flavor houses face particular pressure, driving consolidation toward centralized regulatory affairs capabilities.
Buyer concentration among contract bottlers is compressing ingredient supplier negotiation leverage. Major spirits co-packers in the Netherlands and Poland now mandate carbon intensity scoring for all fermentation inputs. Southern European brand owners are responding by dual-sourcing botanicals through vertically integrated agricultural partnerships rather than spot-market procurement.
Europe Alcohol Ingredients Market Segmentation
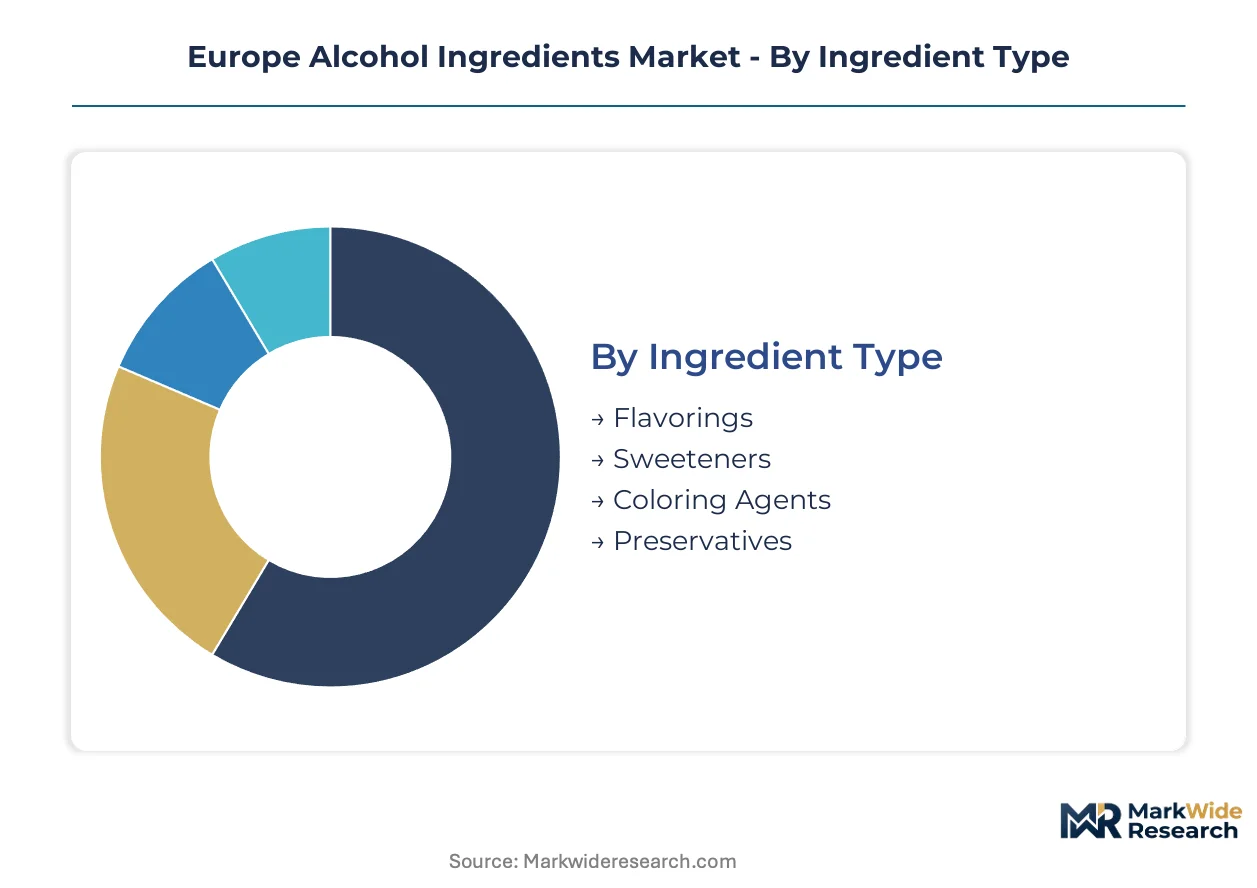
Ingredient specification tiers determine margin capture across European alcohol formulation. Distillers and brewers select input categories based on sensory target, regulatory pathway, and equipment compatibility rather than commodity pricing alone.
Ingredient Type:
Formulation upgrades follow distinct replacement cycles: natural extracts displace synthetics on three-to-five-year horizons, while preservative systems refresh annually for compliance alignment.
- Flavorings:Botanical extracts and essential oil concentrates typically deliver 40-60% active compounds for ethanol dispersion. Southern European gin and vermouth distillers in Spain and France drive procurement of juniper, citrus, and spice-derived profiles under EFSA flavoring substance evaluation requirements.
- Sweeteners:Fermentable sugars and non-nutritive alternatives standardize taste across mass-market beer and ready-to-drink cocktails. Cargill Incorporated anchors supply relationships with large-scale lager producers seeking cost-stable glucose and fructose inputs.
- Coloring Agents:Caramel and anthocyanin-based color systems meet EMA food additive specifications for visual consistency in dark spirits and aperitifs.
- Preservatives:Sorbates and benzoates extend shelf stability in low-alcohol formulations and wine-based beverages.
Volume placements concentrate in Sweeteners; the faster expansion belongs to Flavorings.
Application:
Production scale and per-unit ingredient value diverge sharply across beverage categories, with fermentation volume running inverse to flavoring intensity.
- Beer Production:Enzyme concentrates and specialized yeast strains dominate input procurement for German and Czech lager facilities. Kerry Group plc supplies fermentation solutions tailored to craft brewery equipment constraints in Bavaria and Bohemia.
- Wine Making:Sulfur dioxide management and malolactic bacteria cultures stabilize vintage consistency across French and Italian appellations.
- Spirits Distillation:High-margin botanical formulations command premium positioning in ultra-premium gin, whiskey, and vermouth segments.
- Cocktails:Ready-to-drink formats demand shelf-stable, ethanol-soluble flavor systems with extended stability profiles.
Beer Production generates the largest absolute tonnage; Spirits Distillation yields the steepest expansion trajectory for specialized inputs.
End User:
Procurement sophistication varies by buyer scale, with contract bottlers imposing carbon intensity scoring that filters supplier eligibility.
- Beverage Manufacturers:Multinational spirits houses and beer conglomerates centralize ingredient sourcing through long-term supply agreements with documented provenance.
- Restaurants:On-premise mixology programs drive small-batch botanical and bittering agent demand for house-infused spirits.
- Retail Stores:Private-label alcohol brands specify cost-optimized ingredient grades for price-competitive positioning.
- Breweries:Craft operators across Belgium and the Netherlands prioritize yeast strain diversity and enzyme-optimized mashing over commodity inputs.
Beverage Manufacturers dominate procurement volume; Breweries are gaining share fastest through specialized fermentation input demand.
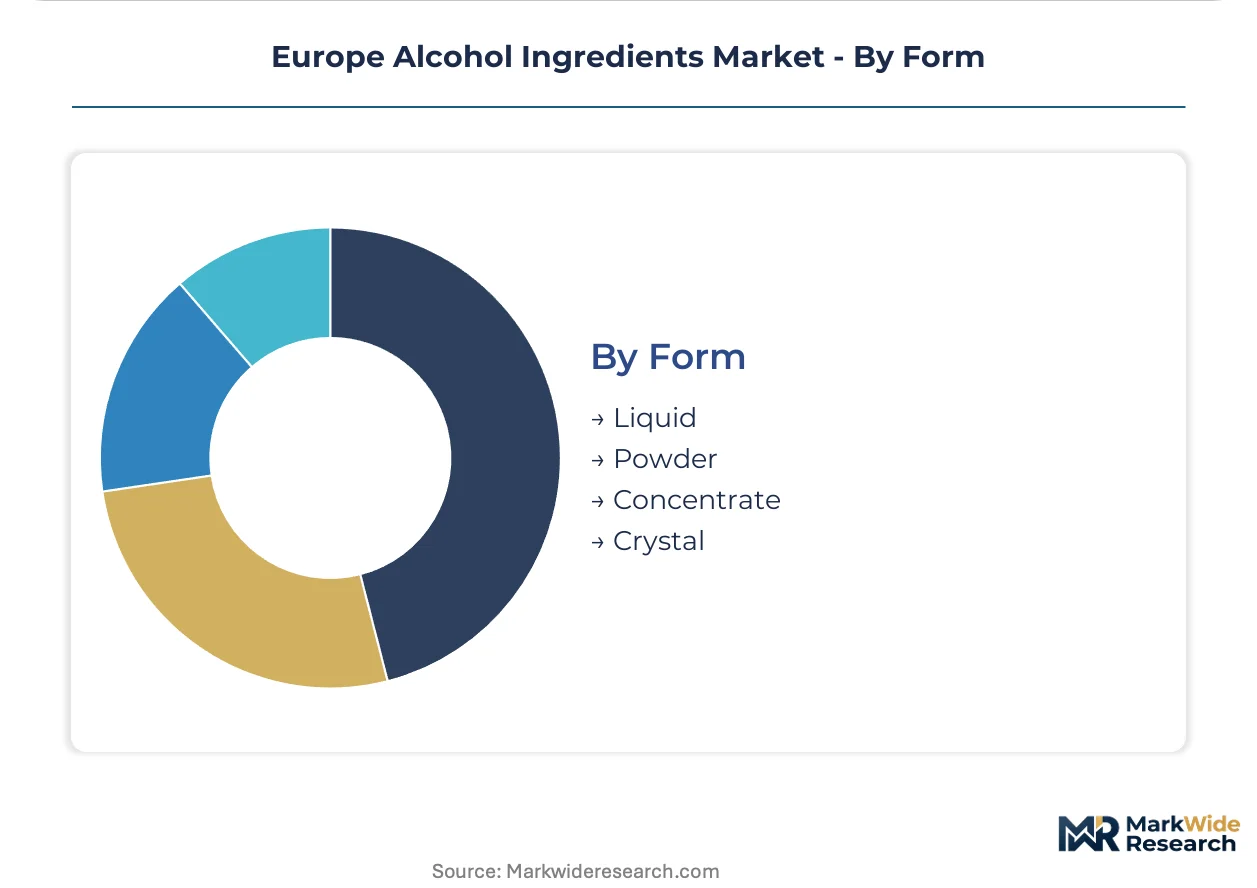
Form:
Physical state selection hinges on dissolution kinetics, storage economics, and equipment retrofit requirements across legacy distillery infrastructure.
- Liquid:Pre-dissolved extracts and syrup concentrates enable rapid batch integration without hydration steps. DSM-Firmenich AG leverages liquid delivery systems for premium spirit flavoring applications.
- Powder:Spray-dried botanicals and dry yeast cultures reduce transport costs and extend ambient shelf stability.
- Concentrate:High-potency flavor and color systems minimize dosage volumes for concentrated production economics.
- Crystal:Purified sweetener and acidulant formats support precise dosing in large-scale blending operations.
Liquid forms anchor current procurement; Concentrate formats are climbing the fastest as manufacturers optimize logistics and storage footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spirits premiumization concentrates procurement demand across Southern European distilleries, while craft brewery expansion reshapes fermentation input requirements in Central Europe. EFSA flavoring evaluations and EU Green Deal carbon mandates filter supplier eligibility across member states. Germany, France, Spain, Italy, and the Netherlands anchor distinct demand clusters.
Germany
Craft brewery proliferation across Bavaria and Baden-Württemberg drives specialized yeast and enzyme concentrate procurement. REACH registration requirements govern novel alcohol-soluble compound commercialization timelines. The Munich-Regensburg corridor anchors fermentation solution supply relationships with mid-scale lager producers.
France
Ultra-premium gin and vermouth distillers in Cognac and Île-de-France expand juniper and citrus botanical sourcing. EFSA expanded toxicological data requirements elevate safety dossier preparation costs for extract submissions. The Provence-Alpes-Côte d'Azur region concentrates supercritical CO2 extraction capacity for essential oil recovery.
Spain
Southern European brand owners dual-source botanicals through vertically integrated agricultural partnerships rather than spot markets. EU Farm to Fork Strategy disclosure mandates compel certified natural extract procurement. Andalusian growing regions supply climate-exposed harvest volumes for bittering agents and spice-derived profiles.
Italy
Malolactic bacteria cultures and sulfur dioxide management systems stabilize vintage consistency across Tuscan and Piedmont appellations. EMA food additive assessments extend 18-24 month approval timelines for novel preservatives. The Emilia-Romagna cluster concentrates contract bottling capacity with carbon intensity scoring requirements.
Netherlands
Major spirits co-packers mandate carbon intensity scoring for all fermentation inputs, filtering supplier eligibility. CSRD traceability requirements position agricultural input provenance as a procurement differentiator. Rotterdam-Antwerp logistics hubs concentrate bulk sweetener and texturizer distribution for mass-market beer producers.
Europe Alcohol Ingredients Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents extend from core ingredient categories into adjacent formulation systems. The market structures around three tiers: integrated flavor-and-fragrance conglomerates with centralized regulatory affairs, specialized fermentation input suppliers with craft brewery relationships, and commodity-scale sweetener and texturizer producers. Strategic archetypes include the full-spectrum formulator, the fermentation specialist, and the agricultural commodity processor. M&A activity and capacity expansion in precision fermentation represent the dominant competitive moves.
Within the integrated formulator tier, DSM-Firmenich AG exemplifies the full-spectrum archetype spanning flavor, fragrance, and nutritional ingredient pipelines. Kerry Group plc occupies a position among fermentation specialists, anchoring supply relationships through yeast and enzyme concentrate portfolios. Cargill Incorporated represents the agricultural commodity processor archetype, leveraging grain origination scale for sweetener and texturizer supply to mass-market producers.
| Leading Market Players |
|---|
| Sensient Technologies |
| Archer Daniels Midland Company |
| DSM-Firmenich AG |
| Bio Springer SA |
| Cargill Incorporated |
| Kerry Group plc |
| Angel Yeast |
| Chr. Hansen |
| Lallemand Inc |
| Others |
Supply & Pricing Matrix
Carbon intensity scoring mandates from Dutch and Polish contract bottlers are forcing ingredient suppliers toward certified provenance documentation, compressing margins on uncertified botanicals while expanding premium capture for traceable supply chains. This procurement shift rewards backward-integrated agricultural partnerships over spot-market sourcing.
Pricing Analysis
Volume placements concentrate in mass-market sweeteners and texturizers where Cargill Incorporated competes on commodity scale, while margin capture concentrates in specialized flavorings and fermentation inputs where DSM-Firmenich AG and Kerry Group plc command premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates certified organic botanical extracts from conventional grades and commodity fermentation inputs. Pricing pressure stems from EFSA expanded toxicological data requirements that elevated safety dossier preparation costs by approximately one-third for novel extract submissions. Mass-market beer producers exhibit highest price sensitivity due to thin margins on volume production, while ultra-premium spirits distillers absorb cost premiums for provenance-verified ingredients.
Supply Chain Analysis
Regional distribution centers in Rotterdam-Antwerp and Milan-Bologna hubs concentrate bulk sweetener and fermentation input flows before final-mile delivery to brewery and distillery facilities. Botanical extract sourcing clusters in Spain, France, and Italy where Mediterranean growing regions supply juniper, citrus, and spice-derived profiles. Raw material dependencies center on wheat and barley for fermentation substrates, essential oil-bearing crops for flavoring compounds, and specialized yeast strains for craft brewing applications. Supply chain risk concentrates in climate-driven harvest variability across Southern European growing regions with limited geographic diversification. Distribution runs through contract bottler networks that mandate carbon intensity documentation as a supplier eligibility filter.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EFSA regulatory dossier requirements and EU Green Deal traceability mandates is forcing smaller flavor houses toward acquisition or exit, creating asymmetric advantage for incumbents with centralized regulatory affairs capabilities.
For Market Incumbents: Deepen backward integration into Mediterranean botanical cultivation to secure climate-resilient supply and organic certification pathways. Expand precision fermentation capacity for terpene production independent of agricultural harvest cycles. Kerry Group plc's craft brewery relationships demonstrate how specialized yeast portfolios defend against commodity substitution. For New Entrants and Emerging Players: Direct-to-distillery digital platforms bypass incumbent distributor markups for small-batch botanical procurement. Target craft brewery enzyme concentrates in Germany and Czechia where equipment retrofit demand outpaces established supplier capacity. White-space exists in shelf-stable ethanol-soluble flavor systems for ready-to-drink cocktail formats. For Investors and Strategic Acquirers: The window for entry favors mid-tier fermentation specialists with documented craft brewery relationships and REACH-compliant compound libraries. Long-term viability rests on precision fermentation technology platforms that decouple production from botanical cultivation constraints. Watch for EMA approval timeline compression as signal for regulatory capacity becoming scarcer than technical capability.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | DSM-Firmenich AG leverages biotransformation to produce novel terpenes without Mediterranean climate exposure. |
| Backward Integration into Cultivation | Spanish distillers secure organic certification pathways through vertically controlled Andalusian growing partnerships. |
| Regulatory Affairs Centralization | Consolidated safety dossier capabilities compress 18-24 month EMA timelines for flavoring substance approvals. |
| Carbon Intensity Certification | Rotterdam-Antwerp logistics hubs filter supplier eligibility through documented agricultural input provenance. |
| Craft Brewery Channel Expansion | Kerry Group plc anchors Bavarian supply relationships through enzyme-optimized mashing technical support. |
Research Methodology
EFSA flavoring substance evaluation databases, EU REACH registration filings, and customs trade statistics formed the secondary backbone for supply chain mapping and regulatory timeline analysis. Primary interviews with distillery procurement directors, craft brewery technical managers, and botanical extract processors validated input cost structures and formulation upgrade cycles. Bottom-up triangulation across ingredient category volumes and top-down reconciliation against beverage production statistics anchored market sizing.
Historical trendline analysis across natural extract adoption rates, craft brewery establishment patterns, and spirits premiumization indices informed projection modeling. Segmentation dimensions included ingredient type, application category, end-user scale, and physical form factor across the analysis window. CAGRs derived from regression analysis of premium spirits flavoring intensity trends and fermentation input procurement volumes. Industry-specific forecast inputs incorporated EMA approval pipeline data and EU Farm to Fork Strategy implementation schedules.
The model holds under stable regulatory assessment timelines and moderate climate variability; deviation in EMA resource constraints or extreme Mediterranean drought events would shift botanical supply economics and premium pricing capture. Forecasts reflect documented assumption sets regarding craft brewery proliferation rates and carbon disclosure mandate enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Egg Phosphatidylcholine Market
Ingredients
Corn-Based Ingredients Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Hydroxytyrosol Market
Ingredients
Tryptose Market
Ingredients
Eucalyptus Oil Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Calcium Caseinate Market
Ingredients
North America Gelatin Market
Ingredients
Cooking Oil Market
Ingredients
Acetylated Starch Market
Ingredients
Low-Odor Fish Protein Hydrolysates from Med Species Market
Ingredients
Potato Starch Market
Ingredients
US Ingredients Market
Ingredients
Diastatic Malt Market
Ingredients
Brazil Starch Derivatives Market