
 Asia Pacific and Latin America Sugar Confectionery Market | 2026-2036
Asia Pacific and Latin America Sugar Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific and Latin America Sugar Confectionery Market Outlook
Consolidation among Southeast Asian convenience retail chains is repositioning procurement leverage toward volume-driven sugar confectionery suppliers. Nestlé SA leverages its dairy-to-confectionery backward integration to secure cost advantages in Thai and Philippine distribution. Mayora Indah anchors Indonesian domestic demand through dense traditional trade coverage. Ferrero International SA differentiates via premium gifting formats that command shelf positioning in Latin American duty-free and specialty channels.
Asia Pacific and Latin America sugar confectionery encompasses sweet, shelf-stable products formulated from sucrose, glucose syrups, and hydrocolloid gelling agents, manufactured through cooking, depositing, or starch molding processes primarily for recreational consumption and impulse purchase occasions. Hard candy formulations retain dominant volume share due to low per-unit cost and ambient stability, though margin pools concentrate in gummies where gelatin and pectin processing complexity creates formulation barriers. Organic and natural formulation segments attract investment as Brazilian and Thai consumers scrutinize ingredient panels, while sugar-free variants remain niche outside diabetic-positioned product lines.
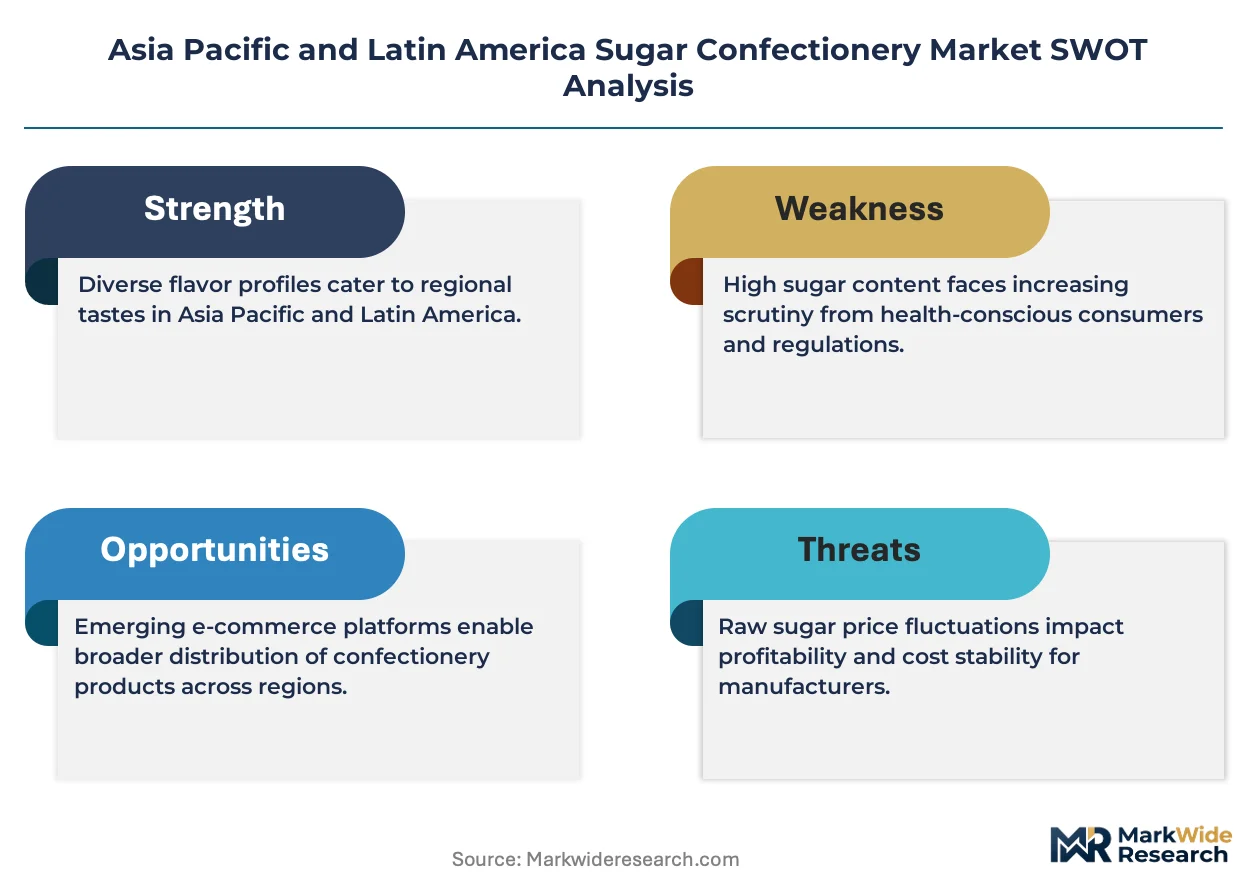
FSSAI labeling requirements in India and ANVISA nutritional disclosure rules in Brazil compel manufacturers to reformulate or redesign packaging, directly shaping R&D allocation across the market. EFSA-aligned standards adopted by several Latin American regulators further constrain additive palettes and colorant approvals, raising compliance costs for imported confectionery. Stakeholders must monitor evolving front-of-pack warning label regimes across Mexico, Chile, and Colombia to anticipate demand shifts toward reduced-sugar and natural-positioned portfolios before regulatory deadlines crystallize competitive repositioning requirements.
Market Dynamics
Convenience retail consolidation across Southeast Asia and Latin America is concentrating procurement leverage among a shrinking pool of high-volume buyers, forcing sugar confectionery suppliers to restructure volume-commitment contracts and margin-sharing mechanisms to retain shelf access.
Growth Catalysts
- Front-of-pack warning mandates:Mexico's impending sugar warning label requirements are accelerating reformulation investments toward reduced-sugar portfolios before enforcement deadlines crystallize competitive positioning.
- Urban impulse channels:Brazilian convenience store chains are expanding dedicated confectionery gondolas in São Paulo and Rio de Janeiro metropolitan zones, capturing commuter and transit-hub foot traffic.
- Pectin substitution technology:Clean-label gummy formulations using pectin instead of gelatin are unlocking vegetarian-positioned SKUs for Indonesia's Muslim-majority consumer base.
Market Restraints
- Glucose syrup price volatility:Brazilian sugar-ethanol arbitrage fluctuations are destabilizing input cost forecasting for hard candy manufacturers dependent on domestic corn-derived sweetener supply.
- Single-source gelatin dependency:Southeast Asian gummy producers rely on concentrated Thai and Indonesian rendering capacity, creating vulnerability to bovine disease outbreaks and export quota restrictions.
- EFSA-aligned additive constraints:Titanium dioxide and synthetic colorant approvals are narrowing across Latin American regulators adopting European safety standards, forcing costly natural pigment substitution.
Strategic Opportunities
- Philippine traditional trade digitization:Sari-sari store inventory management apps are creating direct-to-retailer distribution bypass opportunities for mid-tier confectionery brands.
- India PLI scheme alignment:Food processing infrastructure incentives under India's production-linked incentive framework are attracting contract manufacturing investment for export-oriented natural confectionery.
- Starch molding automation:Robotics integration with depositing lines is unifying quality consistency and labor cost reduction for Colombian hard candy exporters targeting Andean Community markets.
Industry Challenges
- Halal certification timeline compression:Indonesia's BPJPH authority is extending audit durations for multi-ingredient confectionery, delaying new product launches during Ramadan peak demand windows.
- Legacy ERP integration:Brazilian manufacturers operating on fragmented inventory systems face friction synchronizing with retailer EDI requirements for real-time promotional performance tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific and Latin America Sugar Confectionery Market |
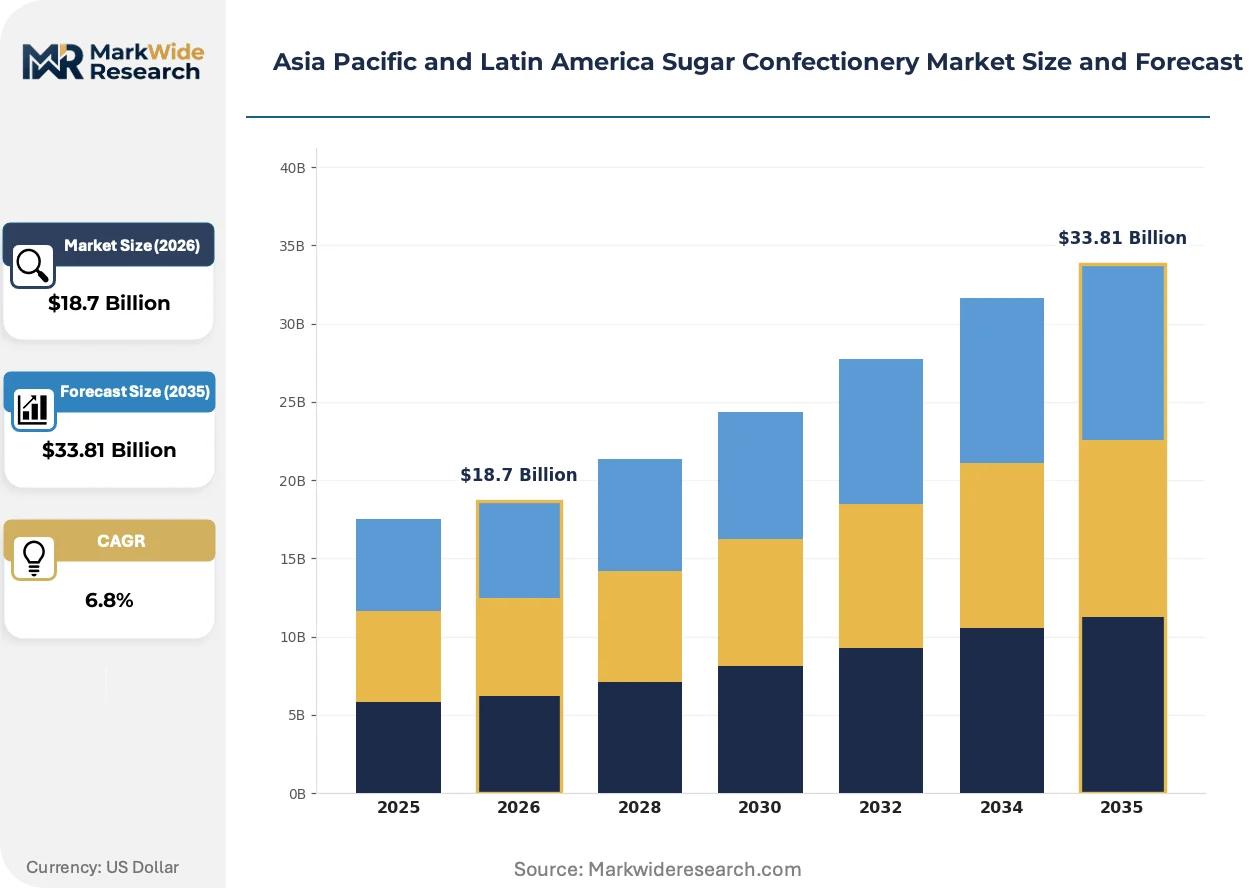
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Candy, Gummies, Marshmallows, Lollipops Consumer Age Group: Children, Teenagers, Adults, Seniors Formulation: Organic, Sugar-Free, Traditional, Natural Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops |
| Companies Covered | Nestlé SA, Grupo Bimbo, Ferrero International SA, Lotte Confectionery, Perfetti Van Melle, Mars Incorporated, The Hershey Company, Mayora Indah, Mondelēz International Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific and Latin America Sugar Confectionery Market Strategic Shifts
Reformulation science and retail format evolution are converging to reshape how sugar confectionery reaches consumers across Asia Pacific and Latin America, with regulatory pressure acting as the primary accelerant of technical change.
Encapsulated flavor-release technology is unifying taste intensity with sugar reduction targets in hard candy applications. Thai and Philippine manufacturers are adopting spray-dried flavor matrices at accelerated rates to maintain sensory impact in 30% reduced-sugar formulations. This convergence is compressing the performance gap between full-sugar and reformulated variants in blind consumer testing.
ANVISA's updated nutritional disclosure framework in Brazil is mandating added sugar line-item reporting on all packaged confectionery labels. Industrial consequence includes mandatory packaging redesign cycles and reformulation cost allocation debates between brand owners and contract manufacturers. Premium gifting segments are responding fastest, leveraging clean-label positioning as a differentiation mechanism in duty-free and specialty retail channels.
Young adult consumers in Jakarta, Bangkok, and Mexico City are rotating toward portion-controlled single-serve formats over traditional family-size sharing bags. Convenience store chains are displacing supermarket confectionery aisle dominance by locating impulse coolers and checkout displays in high-footfall transit locations. This behavioral shift concentrates margin capture in urban core retail zones while eroding rural traditional trade volume share.
Asia Pacific and Latin America Sugar Confectionery Market Segmentation
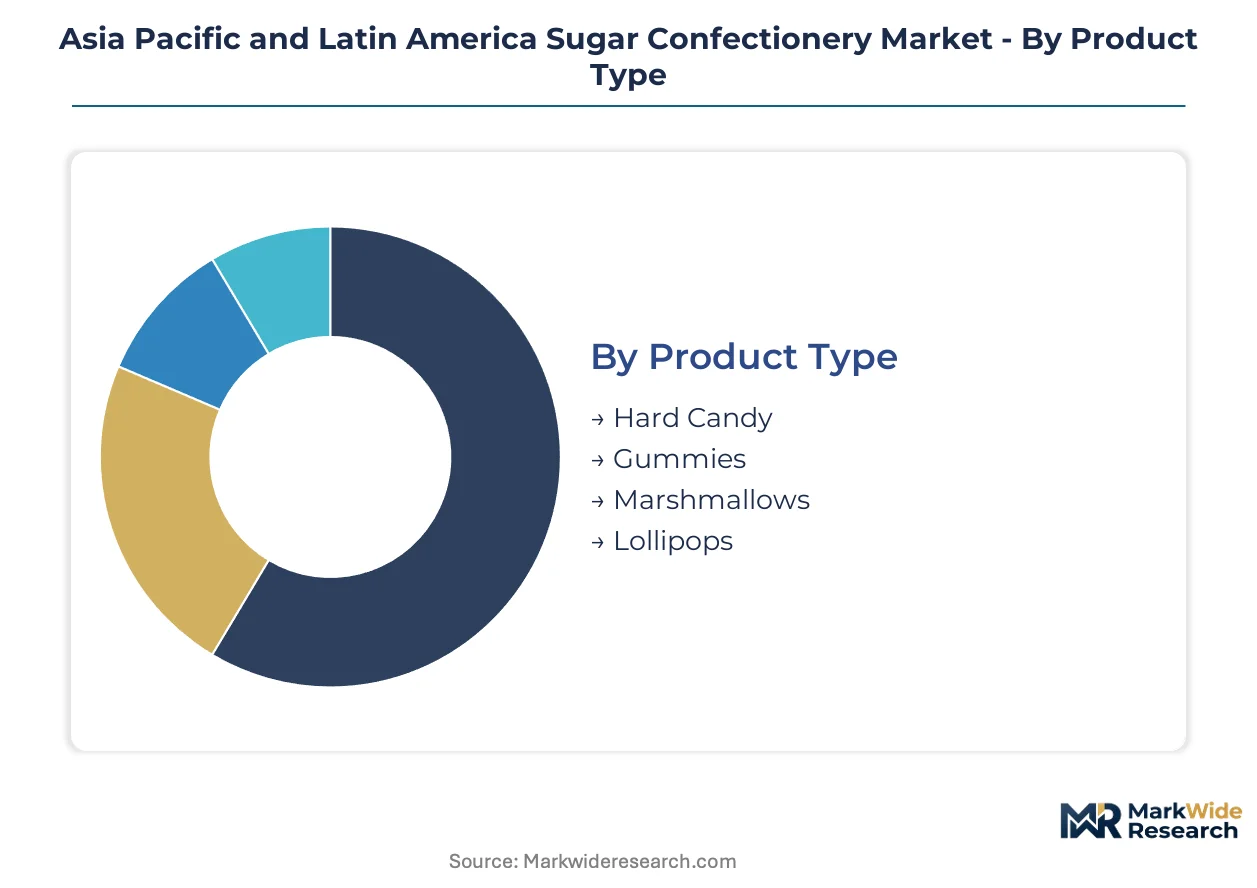
Segmentation in Asia Pacific and Latin America sugar confectionery reveals how formulation complexity, channel concentration, and demographic targeting fragment procurement patterns and margin pools. Manufacturers must align production assets with distinct technical specifications across gelatin-based, pectin-based, and reduced-sugar platforms.
Product Type:
Gelatin replacement technologies and depositing automation differentiate manufacturing economics across format categories.
- Hard Candy:Sucrose-glucose formulations cooked to amorphous solid state deliver ambient stability and lowest per-unit production cost. Demand concentrates in Brazilian and Indonesian traditional trade channels where price elasticity governs repeat purchase.
- Gummies:Hydrocolloid gel matrices using gelatin or pectin require controlled moisture management and starch molding or depositing lines. Southeast Asian urban centers drive premium uptake as young adult consumers rotate toward texture-differentiated snacking formats.
- Marshmallows:Aerated sugar-egg white or gelatin whips occupy niche gifting and hot beverage adjacency applications.
- Lollipops:Hard candy variants on sticks target child-oriented impulse occasions with higher packaging-to-product cost ratios.
Hard candy leads on scale; gummies lead on momentum.
Consumer Age Group:
Purchasing authority and health consciousness diverge sharply across life stages, reshaping channel strategy and formulation investment.
- Adults:Self-directed purchasers scrutinize ingredient panels and portion control, driving clean-label and reduced-sugar R&D allocation. Jakarta, Bangkok, and São Paulo metropolitan convenience networks capture commuter-driven impulse volume.
- Children:Pester-power dynamics concentrate demand in brightly colored, character-licensed formats with parental gatekeeping on sugar content tightening in Indian and Brazilian households.
- Teenagers:Social sharing occasions and digital-native discovery patterns favor novelty formats and limited-edition collaborations.
- Seniors:Sugar-free and dental-friendly positioning addresses diabetic prevalence and oral health constraints, though absolute volume remains constrained by narrower distribution.
Adults command procurement volume; teenagers expand most quickly through social commerce channels.
Formulation:
Regulatory disclosure mandates and religious dietary requirements are bifurcating production lines between conventional and certified-clean platforms.
- Traditional:Full-sucrose formulations with synthetic colorants and flavors retain cost advantage and dominant volume in price-sensitive rural trade. FSSAI and ANVISA labeling requirements are compressing growth trajectories as front-of-pack warnings proliferate.
- Natural:Plant-derived colorants and flavor systems command shelf positioning premiums in Brazilian and Thai urban specialty retail. EFSA-aligned additive constraints are accelerating technical migration from synthetic pigment portfolios.
- Organic:Certified supply chains with documented agricultural inputs attract premium gifting segments in duty-free and e-commerce channels.
- Sugar-Free:Polyol-based formulations address diabetic and dental-positioned demand, remaining niche outside therapeutic use cases.
Traditional formulations anchor volume; natural variants gain share fastest on clean-label differentiation.
Distribution Channel:
Retail format consolidation is reallocating margin capture between high-volume chain buyers and fragmented traditional trade.
- Convenience Stores:Checkout-located impulse coolers and gondolas in São Paulo, Rio de Janeiro, Jakarta, and Bangkok transit hubs capture foot-traffic-driven purchase. Brazilian and Indonesian chain expansion is concentrating procurement leverage among fewer high-volume buyers.
- Supermarkets:Aisle-dominant family-size and sharing formats face erosion as urban consumers rotate toward single-serve occasions.
- Online Retail:Direct-to-consumer gifting and subscription formats bypass traditional distributor markups, though cold-chain constraints limit gelatin-based product reach.
- Specialty Shops:Premium imported and artisan-positioned SKUs command margin in Latin American duty-free and Asian mall-based confectionery boutiques.
Convenience stores dominate transaction frequency; online retail climbs fastest on urban logistics maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates sugar confectionery manufacturing capacity through São Paulo's industrial corridor, while Indonesia's Java-based producers dominate Southeast Asian export flows through Batam and Jakarta port infrastructure.
Brazil
ANVISA's nutritional disclosure mandates are accelerating packaging redesign investments across domestic manufacturers. São Paulo metropolitan convenience chains are expanding dedicated confectionery gondolas to capture commuter foot traffic. The country's sugar-ethanol arbitrage fluctuations are destabilizing glucose syrup input costs for hard candy producers in the Campinas industrial cluster.
India
FSSAI front-of-pack warning label requirements are compressing traditional full-sugar formulation growth trajectories. Maharashtra and Gujarat food processing zones are attracting PLI scheme investment for export-oriented natural confectionery manufacturing. Mumbai and Delhi-NCR urban convenience networks are displacing supermarket aisle dominance through transit-located impulse cooler placement.
Indonesia
BPJPH halal certification timeline extensions are delaying new product launches during Ramadan peak demand windows. Java-based producers leverage dense traditional trade coverage through sari-sari store digitization platforms. Surabaya and Jakarta manufacturing clusters are adopting pectin substitution technologies to unlock vegetarian-positioned SKUs for the Muslim-majority consumer base.
Thailand
EFSA-aligned additive constraints are narrowing titanium dioxide and synthetic colorant approvals across domestic regulators. Bangkok metropolitan convenience retail consolidation is concentrating procurement leverage among high-volume chain buyers. Chonburi and Pathum Thani industrial zones are integrating spray-dried flavor matrices for 30% reduced-sugar hard candy formulations.
Mexico
Impending front-of-pack sugar warning label requirements are accelerating reformulation investments before enforcement deadlines crystallize competitive positioning. Mexico City metro convenience chains are capturing impulse purchase volume through checkout display expansion. Nuevo León manufacturing facilities are facing margin pressure from natural pigment substitution costs driven by regulatory alignment with European safety standards.
Asia Pacific and Latin America Sugar Confectionery Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The vendor base organizes around three strategic archetypes: multinational packaged food conglomerates with backward integration into dairy and cocoa supply chains, regional specialists anchored in dense traditional trade coverage, and premium-positioned gifting format specialists commanding duty-free shelf access. Dominant competitive moves include M&A-driven portfolio diversification into adjacent snacking categories and strategic partnerships with convenience retail chains for exclusive SKU placement.
Within the multinational conglomerate tier, Nestlé SA and Mars Incorporated exemplify scale-driven procurement leverage through integrated supply chain control. Among Asia-Pacific specialists, Lotte Confectionery and Mayora Indah occupy positions shaped by regional taste preference adaptation and traditional trade penetration depth. Ferrero International SA anchors the premium gifting archetype through format differentiation in Latin American duty-free channels.
| Leading Market Players |
|---|
| Nestlé SA |
| Grupo Bimbo |
| Ferrero International SA |
| Lotte Confectionery |
| Perfetti Van Melle |
| Mars Incorporated |
| The Hershey Company |
| Mayora Indah |
| Mondelēz International Inc. |
| Others |
Value Chain & Pricing Dynamics
Convenience retail chain consolidation across São Paulo and Jakarta is forcing volume-commitment contract renegotiations that compress supplier margins while demanding SKU proliferation. This procurement leverage shift feeds back into manufacturing economics, pushing suppliers toward automation investments and ingredient substitution to defend viability.
Pricing Analysis
Capacity additions in Thailand and Indonesia are reshaping price floors for gelatin-based gummy formulations as depositing line automation spreads through Chonburi and Surabaya industrial zones. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and volume scale, with halal-certified and natural-positioned SKUs commanding shelf access premiums. Pricing pressure stems from Brazilian sugar-ethanol arbitrage volatility destabilizing glucose syrup input costs. Traditional trade buyers in rural Indonesia exhibit highest price sensitivity, while duty-free channels in Latin America absorb premium markups with least resistance.
Supply Chain Analysis
Single-source vulnerability sits with concentrated Thai and Indonesian gelatin rendering capacity, creating exposure to bovine disease outbreaks and export quota restrictions. Manufacturing draws from Brazilian corn-derived sweetener supply, Indian flavor compound production, and Chinese packaging material inputs. Tariff exposure runs through shifting ANVISA and FSSAI additive approval frameworks that force reformulation cycles. Distribution runs through consolidated convenience store chains in metropolitan Brazil and Indonesia, bypassing traditional distributor layers for direct-to-retailer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's PLI scheme production incentives and Brazil's ANVISA compliance cost burdens, rewarding footprint optimization across regulatory jurisdictions.
For Market Incumbents: Deploy pectin substitution R&D to unlock vegetarian-positioned SKUs before BPJPH halal certification timelines compress further. Anchor shelf positioning through exclusive SKU partnerships with expanding Indonesian convenience chains. Defend against private-label encroachment by accelerating encapsulated flavor-release technology adoption for reduced-sugar formulations. For New Entrants and Emerging Players: The mid-tier price gap between Ferrero-grade premium gifting and economy hard candy creates entry space for clean-label specialists. Target Philippine sari-sari store digitization platforms for direct distribution bypass. Penetrate fastest through pectin-based gummy launches targeting Jakarta and Bangkok young adult convenience shoppers. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing dense traditional trade coverage and backward integration into dairy or cocoa inputs. Long-term viability favors archetypes with formulation flexibility across natural, reduced-sugar, and halal-certified platforms. Monitor BPJPH audit duration trends and EFSA-aligned additive restriction spreads as inflection signals for portfolio repositioning requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Pectin Substitution Technology Deployment | Unlocks vegetarian SKUs for Indonesia's Muslim-majority base while reducing gelatin single-source risk. |
| Encapsulated Flavor-Release Adoption | Maintains sensory intensity in 30% reduced-sugar formulations mandated by FSSAI and ANVISA labeling. |
| Convenience Chain Direct Partnership | Bypasses distributor markups while securing checkout-located impulse cooler placement in São Paulo and Jakarta. |
| Spray-Dried Flavor Matrix Integration | Compresses performance gaps between full-sugar and reformulated variants in Thai and Philippine manufacturing. |
| Sari-Sari Store Digitization Platform Entry | Creates direct-to-retailer distribution channels for mid-tier brands in Philippine traditional trade. |
Study Parameters
Coverage spans Asia Pacific and Latin America, with primary inputs from each region combining interviews with category buyers at convenience retail chains, formulation R&D directors at confectionery manufacturers, halal certification auditors, and regulatory affairs leads navigating FSSAI and ANVISA frameworks. Secondary validation draws from customs trade records, Nielsen retail audit data, BPJPH certification timelines, and EFSA additive safety assessments. Bottom-up SKU-level volume estimates triangulate against top-down category expenditure models.
Granularity-level framing models product type, consumer age group, formulation platform, and distribution channel dimensions at country-level resolution across the analysis window. CAGRs derive from segment-specific volume trajectories weighted by pricing tier evolution and channel mix shifts. Forecast inputs incorporate glucose syrup cost volatility indices, convenience store expansion pipelines, and front-of-pack warning label implementation schedules.
Caveats apply where regulatory deadline accelerations, gelatin supply disruptions, or convenience chain M&A activity could materially shift the outlook. Forecasts reflect documented assumptions about reformulation cost pass-through rates and traditional trade digitization adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Sugar Free Lollipops Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
Confectionery Fats Market
Confectionery
Premium Chocolate Market
Confectionery
Sugar-Free Gummy Market
Confectionery
Middle East and Africa Confectionery Market
Confectionery
Bangladesh Candy Market
Confectionery
Diet Candy Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Europe Sugar Confectionery Market
Confectionery
Low-Calorie Jelly Market
Confectionery
Gummy Candy Market
Confectionery
Low-Calorie Dark Chocolate Market
Confectionery
US Dark Chocolate Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
Carob Chocolate Market