
 Balsam Bottle Market | 2026-2036
Balsam Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Balsam Bottle Market Outlook
Modular dropper-and-cap bundling is consolidating as the default procurement format for pharmaceutical and cosmetic laboratories. DWK Life Sciences leverages its borosilicate glass manufacturing depth to anchor European laboratory supply chains. Pretium Packaging competes through controlled-dispersion closure engineering across North American personal care accounts. ABGIL sustains its position in Indian pharmaceutical exports with specialized amber glass formulations for light-sensitive balsam compounds.
A balsam bottle is a narrow-necked container engineered for controlled dispensing of resinous, volatile, or viscous liquid formulations, typically manufactured from borosilicate glass or pharmaceutical-grade polyethylene terephthalate with thermal shock resistance exceeding 160°C and compliance with USP Class VI biocompatibility standards. Its primary commercial purpose centers on preserving aromatic integrity and preventing oxidation in essential oils, tinctures, and therapeutic concentrates. Dropper bottles lead volume across pharmaceutical end users where dosing precision commands premium positioning, while biodegradable material alternatives represent the fastest-expanding segment as cosmetics brands in France and California face extended producer responsibility mandates. Glass material dominance persists in European homeopathic and ayurvedic applications where inert surface properties justify higher unit economics against plastic substitution.
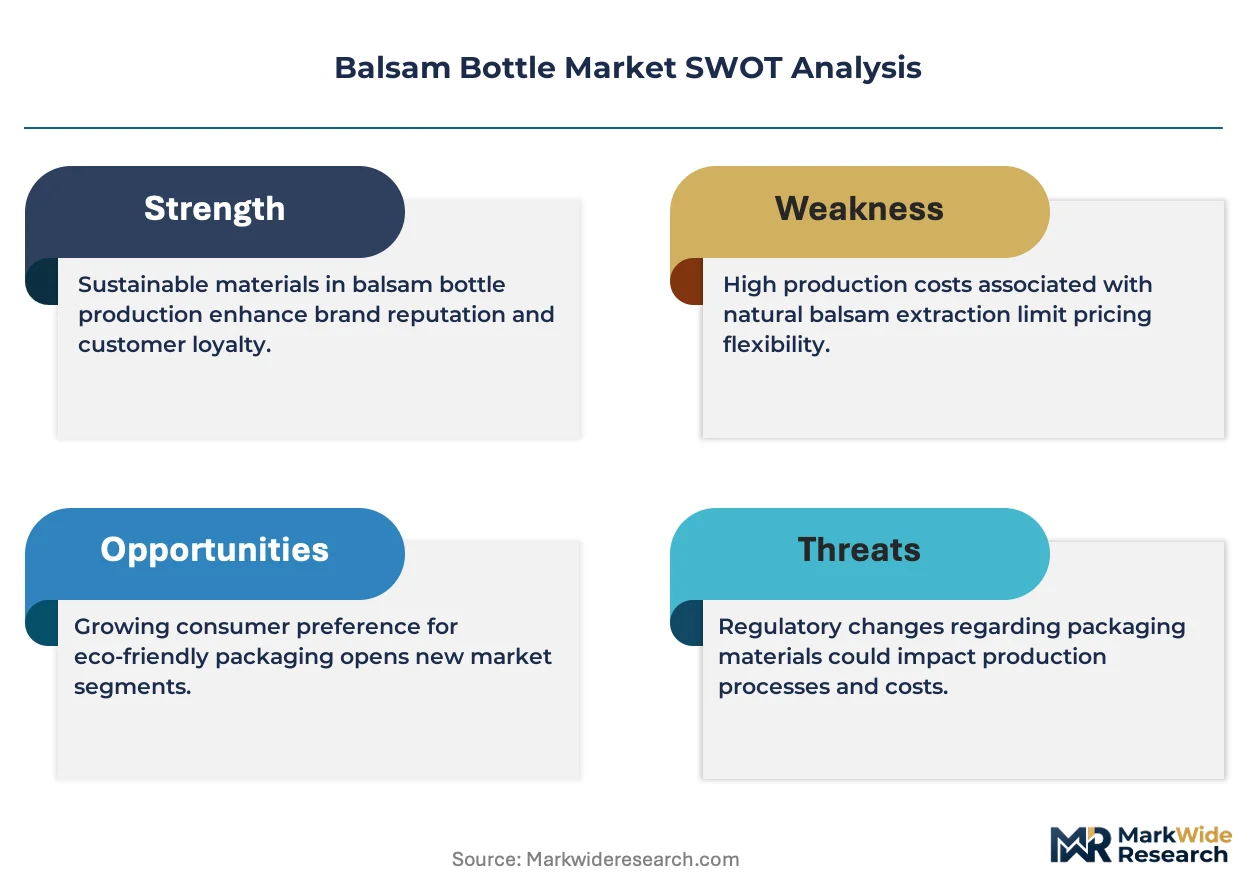
FDA pharmaceutical packaging regulations and EU REACH chemical safety frameworks jointly constrain material selection and migration testing protocols for balsam bottle manufacturers serving cross-border markets. Germany's Federal Institute for Drugs and Medical Devices and India's Central Drugs Standard Control Organization enforce divergent stability-testing requirements that fragment quality certification burdens for multi-territory suppliers. Stakeholders must monitor evolving extended producer responsibility legislation in California and the European Union, where post-consumer recycling quotas threaten to restructure cost allocation across glass-dominant supply chains.
Market Dynamics
EU REACH compliance and FDA pharmaceutical packaging standards are tightening material migration limits simultaneously, redirecting procurement toward borosilicate glass and certified child-resistant closures across German and North American laboratory supply chains.
Growth Catalysts
- REACH Migration Limits:Tightened EU thresholds for chemical leaching from packaging materials are disqualifying conventional soda-lime glass, accelerating borosilicate substitution in pharmaceutical balsam bottling.
- Homeopathic Formulation Demand:German Rhine-Main manufacturing corridor operations are expanding amber glass procurement for light-sensitive tincture and essential oil products.
- California Extended Producer Responsibility:Post-consumer recycling quotas for cosmetics packaging are forcing brand owners to specify biodegradable dropper assemblies and certified recyclable closures.
Market Restraints
- Borosilicate Supply Concentration:European specialty glass production clusters in Germany and Czechia, creating single-source vulnerability for North American pharmaceutical bottlers.
- Certification Timeline Friction:FDA USP Class VI biocompatibility testing and EU MDR compliance documentation extend new product qualification cycles by 8-14 months.
- Plastic Substitution Pressure:Pharmaceutical-grade polyethylene terephthalate with equivalent thermal shock resistance remains 40-60% lower cost, eroding glass unit economics in volume applications.
Strategic Opportunities
- Indian Pharmaceutical Export Channel:CDSCO stability-testing alignment with EU standards is opening consolidated supply contracts for European homeopathic distributors.
- Modular Dropper-Cap Bundling:Controlled-dispersion closure engineering integrated with calibrated glass pipettes commands premium positioning in precision-dosing therapeutic segments.
- Biodegradable Material Mandates:France's AGEC law and California SB 54 implementation are creating first-mover advantage for compostable dropper bulb and collar suppliers.
Industry Challenges
- Borosilicate Glassblowing Skill Scarcity:Thermal forming expertise for thin-walled pharmaceutical neck finishes is concentrating among aging German and Italian craft specialists.
- Cross-Border Certification Burden:Divergent stability-testing requirements between Germany's Federal Institute for Drugs and Medical Devices and India's Central Drugs Standard Control Organization fragment quality documentation for multi-territory suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Balsam Bottle Market |
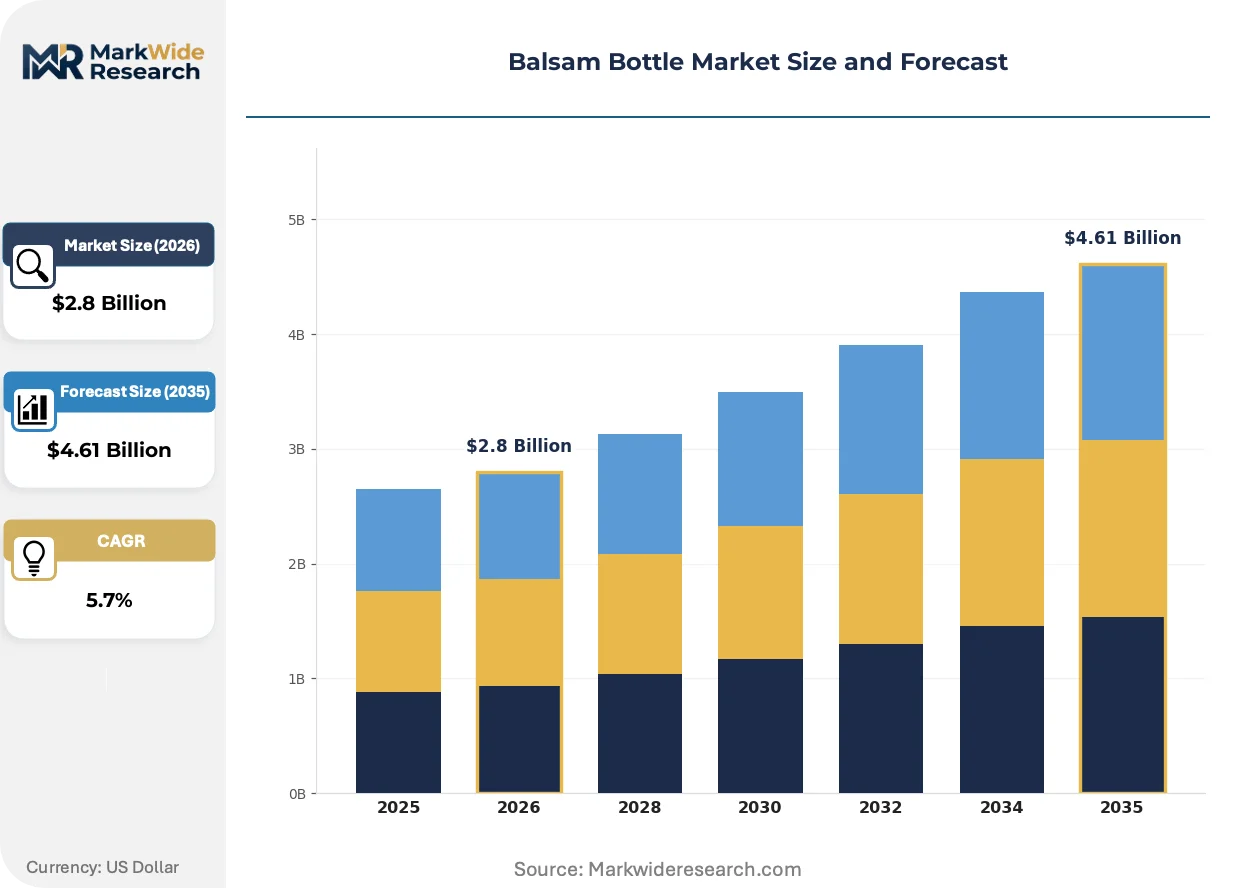
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dropper Bottles, Spray Bottles, Liquid Bottles, Jar Bottles Material: Glass, Plastic, Aluminum, Biodegradable Closure Type: Child-Resistant Caps, Screw Caps, Pump Dispensers, Dropper Inserts End User: Cosmetics, Pharmaceuticals, Food & Beverage, Home Care |
| Companies Covered | DWK Life Sciences, ABGIL, SeaSideLand, Daigger Scientific, Karl Hecht, TED PELLA, INC, Cole-Parmer, Pretium Packaging, Sonoco Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Balsam Bottle Market Strategic Shifts
Modular dropper-and-cap bundling is consolidating as the default procurement format, while regulatory tightening on material migration and extended producer responsibility mandates are reshaping specification priorities across cosmetics and pharmaceutical end uses.
Dropper assembly technology is modularizing around interchangeable borosilicate glass pipettes, silicone bulbs, and child-resistant collars that laboratories can configure to formulation viscosity. Pharmaceutical compounders in Germany and the United States are standardizing on this platform approach to reduce SKU proliferation. The shift is compressing supplier margins on standalone components while rewarding integrated system providers with multi-year service contracts.
REACH Annex XVII restrictions on phthalates and heavy metals in closure elastomers are forcing reformulation of traditional dropper bulb compounds. European compounders are certifying medical-grade silicone alternatives ahead of 2025 enforcement deadlines. Amber glass balsam bottles for light-sensitive essential oils face the steepest cost adjustment, as reformulated closure assemblies represent 15-20% of total unit cost.
Cosmetics brand procurement teams are unbundling after-sales technical support from component supply contracts. French and California personal care companies now source dropper assemblies through specialized distributors while retaining independent laboratory testing relationships. The disintermediation is fragmenting volume commitments and compressing payment terms to 45-60 days from historical 90-day laboratory supply conventions.
Balsam Bottle Market Segmentation
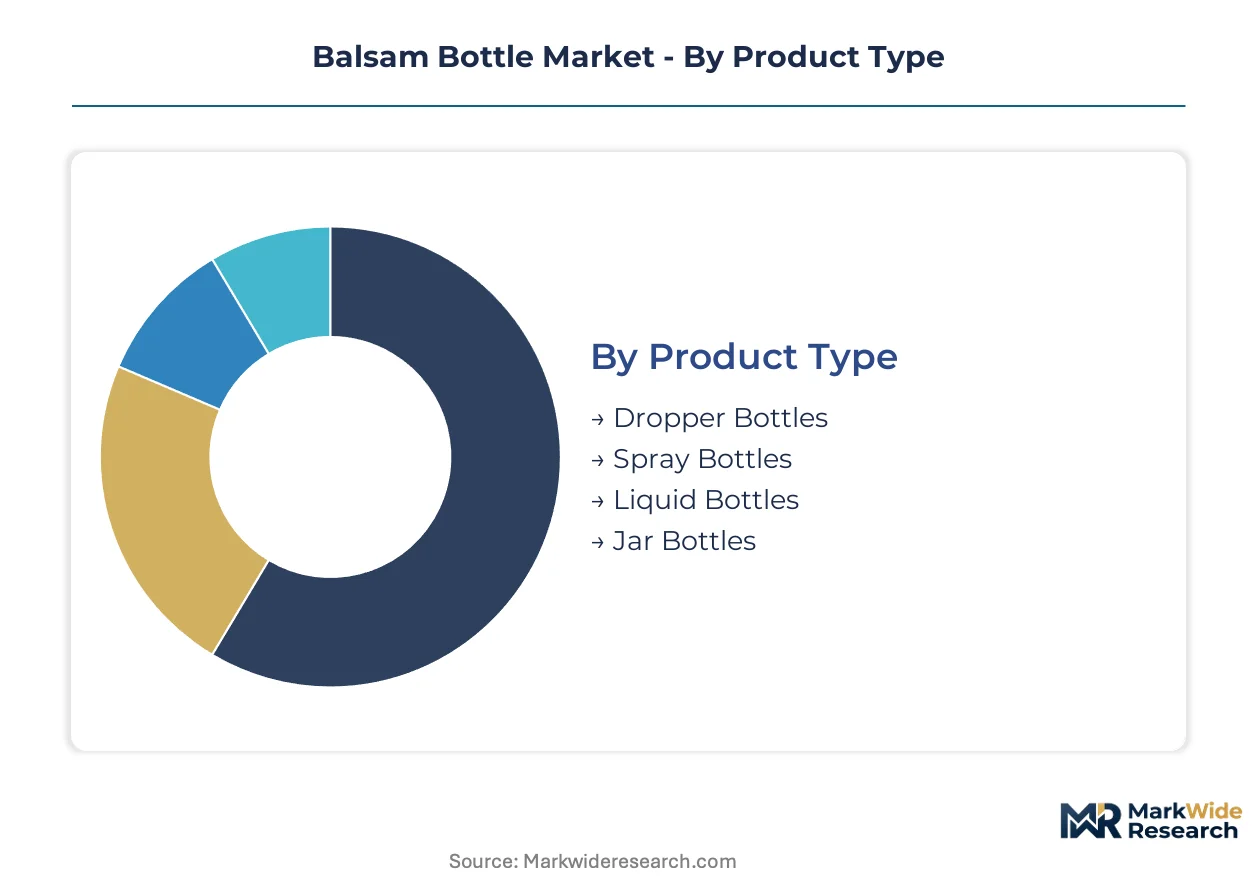
Balsam bottle procurement patterns diverge sharply across formulation viscosity, regulatory exposure, and dispensing precision requirements. Laboratories and brand owners configure specifications around thermal shock resistance, migration testing protocols, and extended producer responsibility mandates rather than unit cost alone.
Product Type:
Upgrade cycles in pharmaceutical and cosmetics laboratories are compressing as modular dropper-and-cap bundling replaces standalone bottle procurement, forcing suppliers to reengineer neck finish tolerances and pipette calibration standards simultaneously.
- Dropper Bottles:Borosilicate glass construction with thermal shock resistance exceeding 160°C dominates tincture and essential oil applications. German Rhine-Main manufacturing corridor laboratories specify calibrated glass pipettes combined with medical-grade silicone bulbs for homeopathic formulations requiring dosing precision.
- Spray Bottles:Fine-mist actuator engineering with particle size distribution control between 20-50 microns serves cosmetic toner and hydrosol segments. California personal care brands facing extended producer responsibility mandates are specifying recyclable aluminum actuators over conventional polypropylene.
- Liquid Bottles:Narrow-neck configurations with controlled-dispersion orifices for viscous resinous formulations.
- Jar Bottles:Wide-mouth designs for semi-solid balm and ointment applications in ayurvedic and homeopathic distribution.
Dropper bottles sit at the top of the volume ranking, with spray bottles climbing the fastest as cosmetic hydrosol applications expand.
Material:
Cost tier stratification separates premium inert surfaces from volume-grade alternatives, with certification grade rather than raw material cost driving purchasing decisions in regulated end uses.
- Glass:Borosilicate and amber soda-lime formulations command pharmaceutical and homeopathic procurement where USP Class VI biocompatibility and light-blocking properties justify premium positioning. EU REACH migration limits are disqualifying conventional soda-lime alternatives in European laboratory supply chains.
- Biodegradable:Compostable polylactic acid and cellulose-based polymers are gaining specification in French cosmetics packaging following AGEC law implementation. California SB 54 post-consumer recycling quotas are accelerating brand-owner trials of biodegradable dropper bulb alternatives.
- Plastic:Pharmaceutical-grade polyethylene terephthalate with equivalent thermal shock resistance at 40-60% lower unit cost.
- Aluminum:Lightweight barrier protection for volatile essential oil formulations in travel-size and sample applications.
Glass dominates value concentration, while biodegradable alternatives are expanding most quickly under extended producer responsibility frameworks.
Closure Type:
Application-specific dispensing mechanics determine closure selection, with child-resistant and precision-dosing configurations capturing disproportionate margin in regulated segments.
- Child-Resistant Caps:Certified push-and-turn mechanisms with torque testing to ISO 8317 standards serve pharmaceutical tincture and concentrated essential oil applications. FDA pharmaceutical packaging standards and EU MDR compliance documentation extend qualification cycles by 8-14 months for new closure introductions.
- Dropper Inserts:Calibrated borosilicate glass pipettes with interchangeable silicone bulbs enable modular configuration to formulation viscosity. German and United States pharmaceutical compounders are standardizing on this platform approach to reduce SKU proliferation.
- Screw Caps:Standard threaded closures for non-regulated cosmetic and home care applications with lower certification burden.
- Pump Dispensers:Metered-dose actuators for viscous serum and treatment oil formulations in premium cosmetics positioning.
Child-resistant caps anchor premium pricing tiers, with dropper inserts gaining share fastest through modular bundling adoption.
End User:
Customer type fragmentation separates laboratory-specified pharmaceutical procurement from brand-driven cosmetics purchasing, with divergent technical support and payment term expectations.
- Pharmaceuticals:Homeopathic and ayurvedic compounders in Germany and India specify amber glass with light-blocking properties and certified child-resistant closures. CDSCO stability-testing alignment with EU standards is opening consolidated supply contracts for European distributors sourcing from Indian pharmaceutical exporters.
- Cosmetics:French and California personal care companies are unbundling after-sales technical support from component supply contracts, sourcing through specialized distributors while retaining independent laboratory testing relationships. This disintermediation is compressing payment terms to 45-60 days from historical 90-day conventions.
- Food & Beverage:Flavor extract and botanical concentrate applications with food-contact compliance requirements.
- Home Care:Aromatic oil and diffuser refill applications with lower regulatory exposure and price sensitivity.
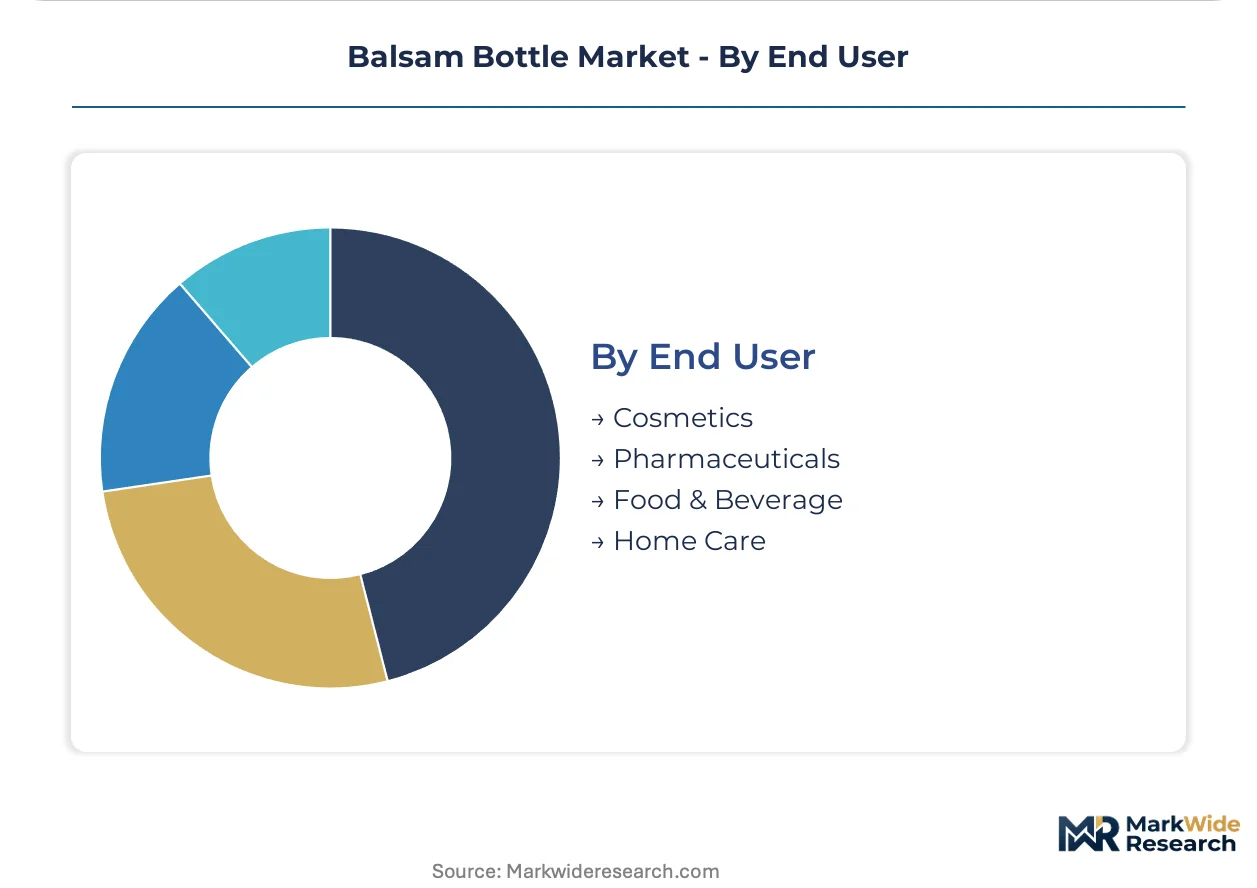
Pharmaceuticals command the highest specification intensity, with cosmetics exhibiting the steepest procurement practice transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical glassblowing traditions in Germany's Rhine-Main corridor established the technical foundations for modern balsam bottle manufacturing. German craftsmanship standards migrated to North American and Indian production facilities through equipment licensing and technical training programs. Today's supply chains reflect this heritage while adapting to divergent regulatory frameworks across major manufacturing regions.
United States
FDA pharmaceutical packaging standards and California SB 54 extended producer responsibility mandates are reshaping procurement specifications for dropper-configured glass bottles. EPA guidelines on volatile organic compound emissions influence coating and printing processes for closure assemblies. New Jersey and Pennsylvania host concentrated pharmaceutical packaging distribution operations serving compound pharmacies and essential oil formulators.
Germany
EMA medical device regulations and EU REACH Annex XVII chemical restrictions are disqualifying conventional soda-lime glass from laboratory supply chains. The Federal Institute for Drugs and Medical Devices enforces stability-testing protocols that extend product qualification timelines. Frankfurt's logistics hub anchors the Rhine-Main manufacturing corridor where homeopathic bottling operations cluster near specialty chemical suppliers.
India
CDSCO stability-testing alignment with EU standards is opening consolidated export contracts for European homeopathic distributors. The PLI scheme for pharmaceutical manufacturing incentivizes domestic glass packaging capacity expansion. Gujarat and Maharashtra host amber glass formulation facilities serving ayurvedic and light-sensitive tincture applications.
France
AGEC law implementation and extended producer responsibility mandates are forcing cosmetics brands to specify biodegradable dropper assemblies. ANSM pharmaceutical packaging oversight converges with EU MDR compliance documentation requirements. Paris-based personal care companies are unbundling technical support from component supply contracts, compressing payment terms.
China
NMPA pharmaceutical packaging standards and GB material safety specifications are tightening migration limits for borosilicate glass imports. The dual carbon goals policy framework accelerates domestic renewable energy integration in glass melting operations. Yangtze River Delta chemical parks host contract manufacturing for European cosmetics brands seeking cost-competitive dropper assembly production.
Balsam Bottle Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade and material-purity dimensions. The vendor base stratifies between integrated borosilicate glass manufacturers, specialized closure engineering firms, and regional distributors with formulation-testing capabilities. Three archetypes dominate: European laboratory supply specialists with thermal-forming depth, North American controlled-dispersion engineers, and Indian amber-glass exporters with CDSCO-EU alignment. Capacity expansion and modular dropper-cap bundling represent the dominant competitive vectors.
Within the European specialist tier, DWK Life Sciences and Karl Hecht exemplify borosilicate manufacturing depth anchored in German craft traditions. Pretium Packaging occupies a position among North American controlled-dispersion closure engineers serving personal care accounts. ABGIL represents Indian pharmaceutical export specialists with amber glass formulation capabilities for light-sensitive compounds. These three anchors illustrate how geographic regulatory alignment and material certification grade determine competitive positioning across fragmented procurement channels.
| Leading Market Players |
|---|
| DWK Life Sciences |
| ABGIL |
| SeaSideLand |
| Daigger Scientific |
| Karl Hecht |
| TED PELLA, INC |
| Cole-Parmer |
| Pretium Packaging |
| Sonoco Products |
| Others |
Value Chain & Pricing Dynamics
Specialty borosilicate glass price indices cascade through pharmaceutical packaging supply chains into three distinct procurement tiers. German and Czechia glassworks anchor premium pricing for REACH-certified formulations, while Indian amber glass facilities compete on unit economics for export-oriented homeopathic distributors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USP Class VI-certified borosilicate assemblies from conventional soda-lime alternatives and pharmaceutical-grade PET substitutes. Certification grade and thermal shock resistance specifications drive price differentiation, with modular dropper-cap bundling commanding premium positioning. Cost compression in standard-tier soda-lime glass is intensifying because REACH migration limits are disqualifying conventional formulations. Volume pharmaceutical compounders exhibit highest price sensitivity, while German homeopathic laboratories prioritize certification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for borosilicate glass pipettes and medical-grade silicone bulbs across German and North American pharmaceutical procurement. Supply concentrates in Germany, Czechia, and India for specialty glass formation, with silicone elastomer compounding anchored in German and Italian craft facilities. Raw material dependencies include high-purity silica sand, boron oxide, and medical-grade silicone feedstocks. Single-source vulnerability concentrates in thin-walled pharmaceutical neck finish glassblowing expertise. Distribution runs through specialized laboratory supply distributors and direct contracts with cosmetics brand procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU REACH Annex XVII enforcement and FDA pharmaceutical packaging standards jointly expand specification requirements for migration-tested materials.
For Market Incumbents: Deepen backward integration into borosilicate glass melting capacity to defend margin position against pharmaceutical-grade PET substitution pressure. Expand captive supply of medical-grade silicone bulb compounding ahead of 2025 phthalate restriction deadlines. Certification investment in CDSCO-EU alignment opens consolidated supply contracts for Indian pharmaceutical export channels. For New Entrants and Emerging Players: Launch via specialized distributor partnerships serving French and California cosmetics brands facing AGEC law and SB 54 extended producer responsibility mandates. Biodegradable dropper assemblies represent the most penetrable white-space segment. Target modular dropper-cap bundling configurations to capture premium positioning in precision-dosing therapeutic applications. For Investors and Strategic Acquirers: Consolidation pressure builds where aging German and Italian glassblowing craft specialists lack succession planning for thermal forming expertise. Five-to-ten year viability favors integrated system providers with multi-year service contracts over standalone component suppliers. Watch CDSCO-EU stability-testing harmonization progress as inflection indicator for Indian pharmaceutical export channel consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Melting | Captive glass supply secures margin against PET substitution and REACH compliance cost inflation. |
| Medical-Grade Silicone Bulb Certification | Pre-qualified elastomer compounds accelerate FDA and EU MDR closure qualification timelines. |
| Modular Dropper-Cap Platform Launch | Interchangeable pipette configurations reduce SKU proliferation for German pharmaceutical compounders. |
| CDSCO-EU Alignment Investment | Consolidated stability-testing documentation unlocks multi-territory supply contracts for Indian exporters. |
| Biodegradable Assembly Development | Compostable dropper alternatives capture first-mover positioning under France AGEC and California SB 54 mandates. |
Study Parameters
Direct dialogue with pharmaceutical procurement managers, cosmetics brand supply chain directors, borosilicate glass manufacturing engineers, and laboratory distributor category buyers grounded qualitative findings. Secondary validation drew from ECHA REACH substance database entries, FDA pharmaceutical packaging guidance documents, CDSCO stability-testing protocols, and EU MDR technical documentation. Bottom-up demand modeling across dropper bottle, spray bottle, liquid bottle, and jar bottle configurations triangulated against top-down market sizing.
Segment-level value outputs across material type, closure configuration, and end-user application combined with regional regulatory cluster analysis. CAGRs derived from weighted average of historical procurement volume trends and projected qualification timeline impacts. Forecast inputs incorporated extended producer responsibility mandate implementation schedules and borosilicate glass production capacity expansion announcements.
Several conditions sit outside the modeled scope, including sudden raw material price shocks, unilateral regulatory enforcement delays, and disruptive substitution by novel barrier polymer technologies. Deviation in REACH Annex XVII enforcement timing or CDSCO-EU harmonization progress would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Global Shortenings Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Mexico Alcohol E-Commerce Market
Alcoholic Beverages
Alcohol Enzymes Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Beer Fermenter Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
Bright Beer Tank Market
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
Global Spiced/Flavored Rum Market
Alcoholic Beverages
Electrolyte Beer Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market