
 United States Edible Meat Market | 2026-2036
United States Edible Meat Market Size, Share, and Industry Trends Forecast 2026-2036
United States Edible Meat Market Analytics
Aftermarket service revenue from value-added processing and portion-ready packaging is tilting margin pools away from commodity slaughter toward branded prepared meats. Tyson Foods Inc. leverages vertical integration from feedlots to case-ready products. JBS SA anchors its position through large-scale beef and pork processing infrastructure. Cargill Inc. differentiates via supply chain transparency tools and direct rancher partnerships.
Edible meat encompasses muscle tissue and associated fat from cattle, swine, poultry, and ovine species, processed under USDA-inspected facilities maintaining temperatures below 40°F through cold chain distribution to preserve microbial safety and shelf stability. Its primary commercial purpose centers on delivering protein-centric food products to retail and food service channels. Poultry leads volume throughput due to feed conversion efficiency and shorter production cycles. Fresh processing retains dominant share in retail channels, while cured and smoked methods capture premium positioning in specialty distribution. Food service channels concentrate demand for bulk and tray pack formats, whereas vacuum seal formats expand in e-commerce fulfillment.
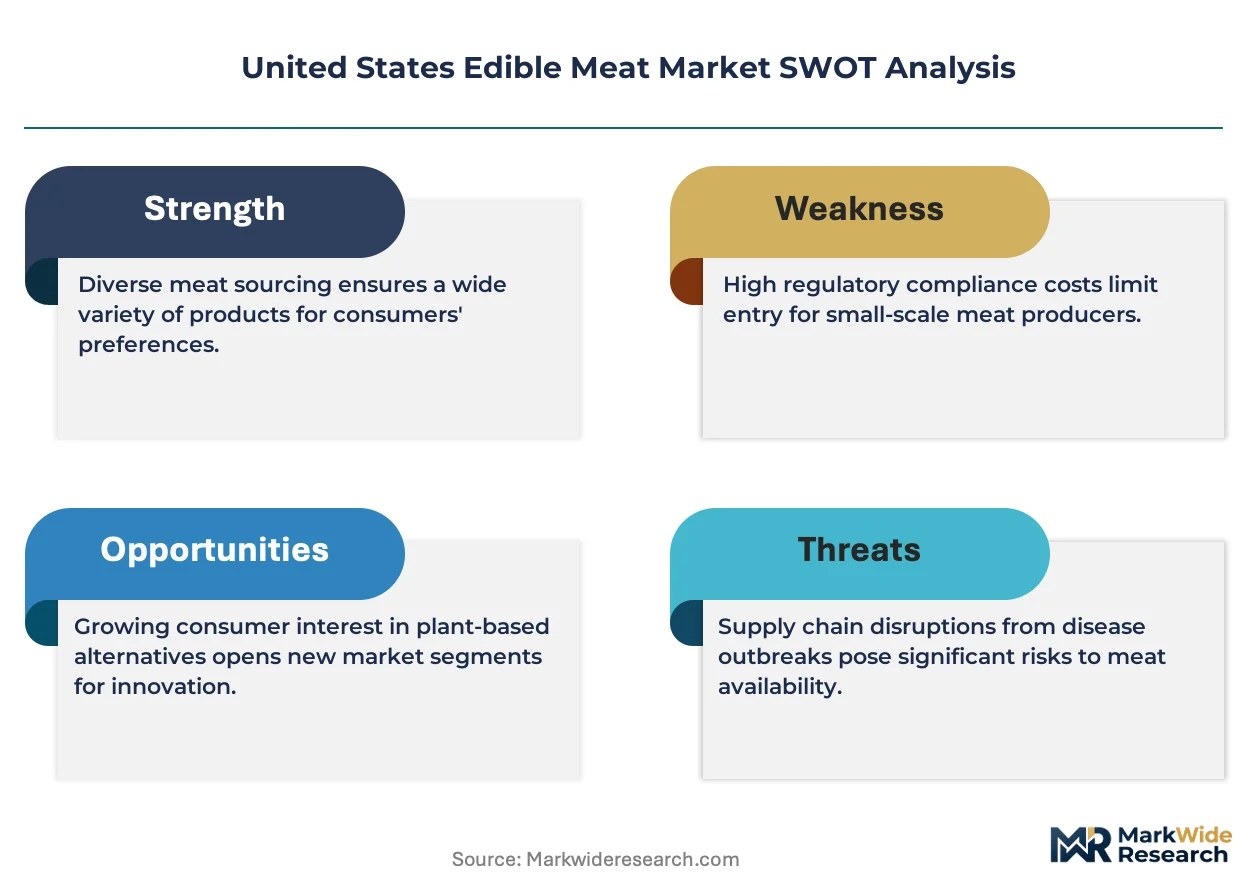
USDA Food Safety and Inspection Service mandates pathogen reduction and HACCP compliance across all interstate commerce, elevating capital requirements for market entry. FDA oversees feed additives and veterinary drug residues under overlapping jurisdiction with FSIS. State-level California Proposition 12 and Massachusetts Question 3 rules on confinement standards reshape sourcing geography and compliance costs for national suppliers. Stakeholders must monitor divergence between federal baseline standards and proliferating state animal welfare mandates to avoid supply disruption.
Market Dynamics
State-level animal welfare mandates are fragmenting sourcing geography and forcing national suppliers to maintain parallel compliance systems, while restaurant chains concentrate procurement power around premium cut specifications.
Growth Catalysts
- California Proposition 12:Confinement standard mandates create certified supply premiums that reward early compliance investments by integrated packers.
- Feed conversion efficiency gains:Poultry sector throughput expansion captures protein demand rotation away from red meat categories.
- Nebraska-Iowa-Texas processing corridor concentration:Cold chain infrastructure density reduces logistics friction for case-ready distribution.
Market Restraints
- Feed grain price volatility:Corn and soybean meal input swings compress margin predictability across cattle and swine operations.
- Federal-state regulatory divergence:Massachusetts Question 3 layering atop USDA FSIS baseline forces dual-track compliance architecture.
- Plant-based protein substitution:Pea and mycoprotein alternatives capture flexitarian trial in coastal urban markets.
Strategic Opportunities
- Portion-ready packaging automation:Labor cost arbitrage through robotics integration at break-pack facilities.
- Direct rancher data partnerships:Blockchain traceability tools unlock premium retail shelf placement and export qualification.
- Texas panhandle feedlot density:Geographic clustering supports captive biogas capture for Scope 3 emissions reduction.
Industry Challenges
- HACCP validation specialist scarcity:USDA FSIS compliance documentation requires trained personnel that rural processing communities cannot retain.
- Legacy ERP integration with cold chain IoT:Temperature logging sensor networks demand middleware investment that mid-tier packers defer.
- Animal welfare audit backlog:Third-party certification queue delays market access for suppliers seeking premium channel entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Edible Meat Market |
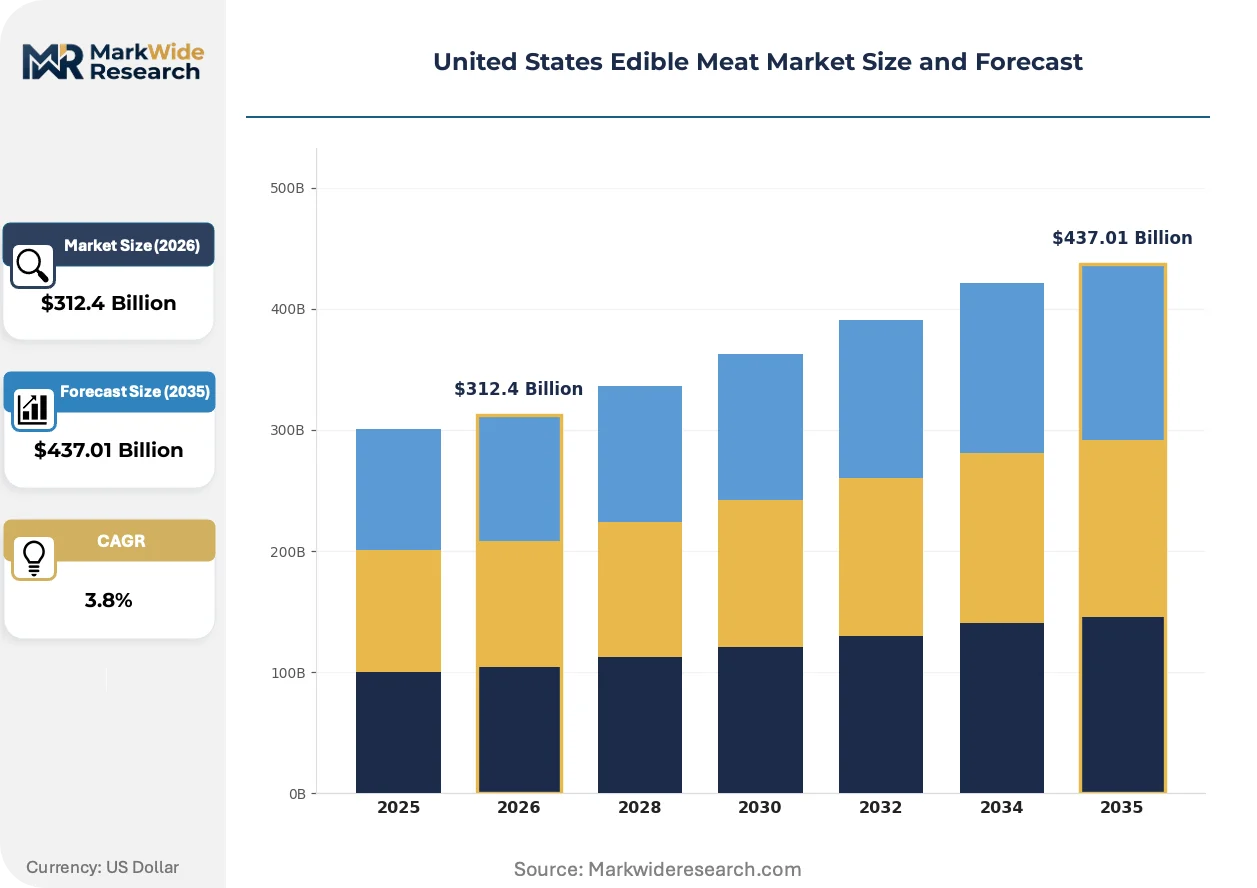
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $437.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Lamb Processing Method: Fresh, Cured, Smoked, Frozen Distribution Channel: Retail, Food Service, Online, Wholesale Packaging Type: Tray Pack, Vacuum Seal, Canned, Bulk |
| Companies Covered | Tyson Foods Inc., JBS SA, Cargill Inc., Hormel Foods Corporation, Perdue Farms Inc., Smithfield Foods Inc., National Beef Packing Company, WH Group Limited, Conagra Brands Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Edible Meat Market Evolving Landscape
Automation and data transparency tools are compressing traditional slaughter-to-retail timelines while fragmenting competitive advantage sources across the value chain.
High-pressure processing technology is migrating from niche ready-to-eat applications toward fresh poultry and ground beef categories. Food service distributors operating central kitchens adopt HPP for pathogen reduction without thermal degradation. Extended shelf-life outcomes enable longer distribution radius from centralized fabrication facilities, compressing regional plant count requirements.
USDA FSIS mandates pathogen reduction performance standards that elevate testing frequency and documentation burden. Small and very small establishments face disproportionate compliance cost absorption relative to volume throughput. Interstate suppliers are consolidating fabrication operations into fewer, larger inspected facilities to amortize laboratory and quality personnel overhead.
Restaurant chain procurement teams now specify exact cut dimensions and trim specifications rather than accepting commodity USDA graded carcasses. This disintermediation of traditional meat purveyor roles forces packers to invest in portion-control equipment and culinary liaison staff. The specification-driven model concentrates most visibly in fast-casual chains operating across Texas, Florida, and California metropolitan corridors.
United States Edible Meat Market Segmentation
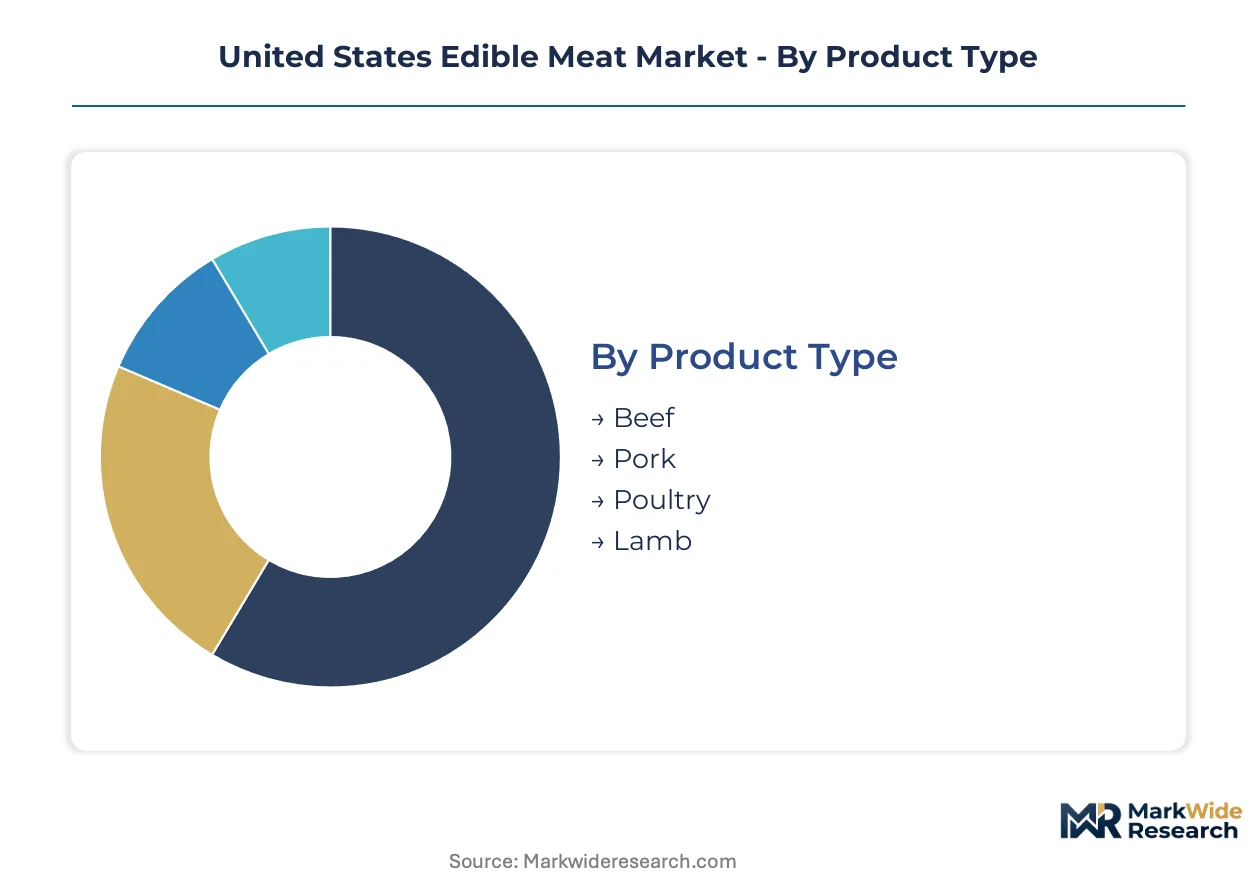
Segmentation reveals how margin pools shift across the value chain. Processing intensity, channel requirements, and packaging automation drive divergent investment returns for packers and distributors.
Product Type:
After-sales service intensity varies sharply by species, with poultry demanding continuous veterinary support and feed optimization versus beef's focus on genetics and finishing programs.
- Beef:USDA-graded carcasses from grain-finished cattle dominate premium retail and steakhouse channels. Demand concentrates in Texas, Nebraska, and Iowa processing corridors where feedlot density supports captive supply chains.
- Pork:Lean muscle composition and rapid finishing cycles position pork for processed meat applications and export qualification. Iowa and North Carolina processing clusters capture scale advantages through integrated farrow-to-finish operations.
- Poultry:Broiler operations in Georgia, Arkansas, and Alabama leverage feed conversion efficiency and vertical coordination to supply case-ready retail and quick-service restaurant specifications.
- Lamb:Smaller-scale production centered in Colorado and Texas serves ethnic retail and fine-dining channels with limited national distribution reach.
By volume, Poultry leads. By growth pace, Beef is ahead.
Processing Method:
Cost tier stratification separates commodity slaughter from value-added fabrication, with capital intensity determining competitive entry barriers.
- Fresh:Refrigerated muscle cuts distributed within days of fabrication retain dominant retail share. Cold chain density in the Midwest and Southeast reduces spoilage risk for case-ready programs.
- Cured:Nitrite and salt preservation extends shelf life for deli and breakfast meat categories. HACCP validation requirements elevate compliance costs that favor large integrated packers.
- Smoked:Thermal processing and wood combustion generate premium positioning in specialty retail and barbecue-focused food service segments.
- Frozen:Blast freezing enables inventory carry and export qualification for distant markets, particularly from West Coast port access points.
By volume, Fresh leads. By margin expansion, Cured is climbing the fastest.
Distribution Channel:
Customer type fragmentation forces packers to maintain parallel product specifications and logistics capabilities.
- Retail:Grocery and club store channels demand case-ready tray packs with exact trim specifications and barcode traceability.
- Food Service:Restaurant chains and institutional buyers concentrate procurement around portion-controlled cuts and bulk formats.
- Online:Direct-to-consumer and third-party marketplace fulfillment requires vacuum-seal durability and insulated packaging investment.
- Wholesale:Independent distributors and meat purveyors aggregate regional demand for sub-primal fabrication and custom cutting.
By volume, Retail leads. By channel investment intensity, Online is gaining share fastest.
Packaging Type:
Supply concentration in automated packaging equipment shapes competitive differentiation across format categories.
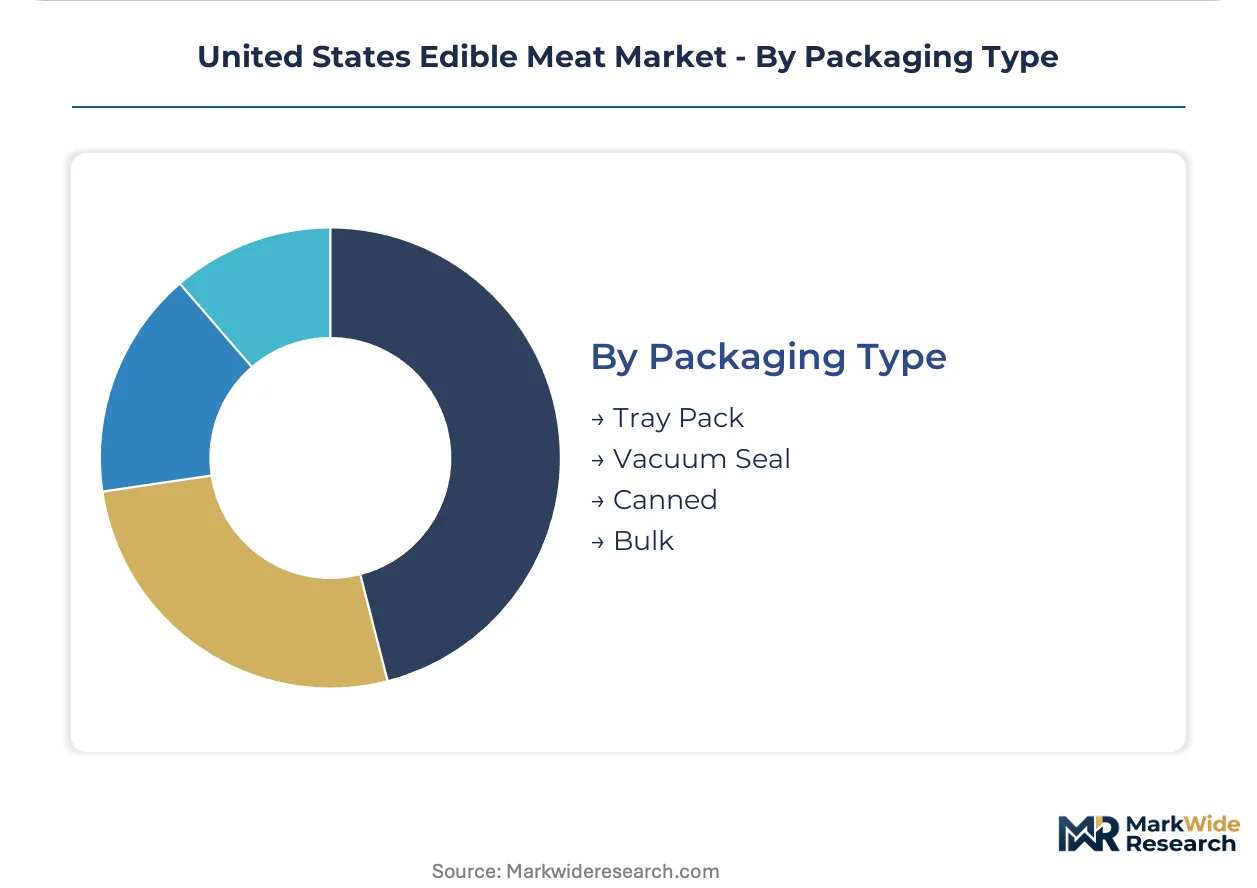
- Tray Pack:Modified atmosphere packaging dominates retail fresh meat cases with clear film overwrap and absorbent pad integration.
- Vacuum Seal:Barrier film evacuation extends shelf life for e-commerce fulfillment and export shipment requirements.
- Canned:Retort processing for shelf-stable products serves emergency preparedness and military procurement channels.
- Bulk:Food service and further processing customers receive sub-primal cuts in polyethylene-lined corrugated containers.
By volume, Tray Pack leads. By technology migration, Vacuum Seal shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across US sub-regions diverge sharply by species preference and channel mix, with protein demand tilting toward poultry in the Southeast and premium beef commanding share in Texas and California metropolitan corridors.
Texas
Steakhouse chains and independent barbecue operators drive disproportionate demand for USDA Prime and Choice graded carcasses. State environmental regulators enforce concentrated animal feeding operation permits that shape feedlot placement in the Panhandle. The Amarillo-Lubbock corridor hosts dense cattle finishing infrastructure where packers source captive supply for case-ready programs.
Nebraska
Grain-fed beef production dominates protein output, with corn belt proximity delivering feed cost advantages to integrated cattle operations. Nebraska Department of Environmental Quality administers water discharge permits that influence processing facility siting decisions. The Greater Omaha area concentrates large-scale beef fabrication plants serving national retail and food service distribution networks.
Iowa
Pork processing volume exceeds all other species, leveraging integrated farrow-to-finish operations that supply both domestic and export channels. State-level nutrient management plans regulate manure application rates across the hog-dense counties of north-central Iowa. Siouxland and Des Moines metro processing clusters capture scale efficiencies through automated cutting and packaging lines.
California
Flexitarian dietary shifts and ethnic diversity reshape protein procurement toward poultry and plant-forward alternatives in coastal urban markets. Proposition 12 confinement standards mandate certified supply chains that elevate compliance costs for out-of-state suppliers. The Central Valley maintains poultry processing concentration while Los Angeles and San Francisco distribution hubs handle premium import and specialty meat flows.
Georgia
Broiler production volume leads national output, with vertical coordination between hatcheries, growout operations, and processing plants optimizing feed conversion metrics. Georgia Department of Agriculture enforces poultry health monitoring protocols that influence interstate shipment qualifications. The Gainesville processing corridor anchors case-ready poultry supply for quick-service restaurant chains across the Southeast.
United States Edible Meat Market Competitive Landscape
Capability concentration sits with integrated packers controlling cold chain infrastructure and USDA certification expertise; scale advantage sits with diversified protein conglomerates amortizing compliance costs across species. The market structure tilts toward oligopoly at the national level, with top-tier processors commanding procurement leverage over feedlot operators and growout farms. Two archetypes dominate: vertically integrated packers with captive supply chains, and specialized fabricators focused on portion-ready value addition. Competitive moves center on automation capital deployment and direct rancher data partnerships that secure premium channel access.
Among diversified protein conglomerates, Tyson Foods Inc. and JBS SA occupy positions exemplifying scale-driven consolidation across beef, pork, and poultry categories. Cargill Inc. represents the supply chain transparency archetype, leveraging direct producer relationships and digital traceability tools to differentiate in premium retail channels. These three entities anchor the competitive structure through contrasting strategic postures: operational scale, geographic diversification, and sustainability-linked procurement systems.
| Leading Market Players |
|---|
| Tyson Foods Inc. |
| JBS SA |
| Cargill Inc. |
| Hormel Foods Corporation |
| Perdue Farms Inc. |
| Smithfield Foods Inc. |
| National Beef Packing Company |
| WH Group Limited |
| Conagra Brands Inc. |
| Others |
Value Network & Pricing Analysis
Feed grain price volatility determines both pricing tier spreads and supply chain shape across the US edible meat market, compressing margins in cattle and swine operations while forcing packers to consolidate fabrication capacity around the Nebraska-Iowa-Texas corridor to amortize fixed costs.
Pricing Analysis
Long-term offtake contracts between integrated packers and restaurant chains dominate premium cut procurement, while spot markets clear commodity-grade carcasses. Three-tier pricing structure across premium, standard, and economy levels separates USDA Prime from Choice and Select grades. Pricing pressure stems from plant-based protein substitution capturing flexitarian trial in coastal urban markets. Quick-service restaurant chains exhibit highest price sensitivity, whereas steakhouse operators absorb premiums for exact cut specifications.
Supply Chain Analysis
State-level animal welfare mandates function as de facto export-control regimes limiting interstate supplier flows, with California Proposition 12 and Massachusetts Question 3 creating certified supply premiums that reshape sourcing geography. Geographic supply concentration centers on Texas, Nebraska, and Iowa for beef; Iowa and North Carolina for pork; Georgia, Arkansas, and Alabama for poultry. Raw material dependencies include corn and soybean meal for feed rations, veterinary pharmaceuticals for herd health, and packaging films for case-ready distribution. Single-source vulnerability concentrates in the Texas Panhandle feedlot belt. Distribution runs through cold chain networks anchored by Omaha, Sioux City, and Amarillo processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense imperative as mycoprotein and pea protein alternatives capture protein demand rotation in metropolitan corridors.
For Market Incumbents: Entrench position through captive biogas capture at Texas Panhandle feedlot density clusters for Scope 3 emissions reduction, while deepening backward integration into portion-ready packaging automation to extract labor cost arbitrage from break-pack facilities.
For New Entrants and Emerging Players: Ethnic retail lamb channels in Colorado and Texas represent the most penetrable entry point given limited national distribution reach and absence of integrated packer dominance. Direct rancher data partnerships leveraging blockchain traceability tools unlock premium retail shelf placement without competing on feedlot scale.
For Investors and Strategic Acquirers: Mid-tier fabricators with HACCP validation expertise and legacy ERP integration capabilities present acquisition targets as compliance documentation requirements elevate capital barriers. Watch for animal welfare audit queue delays as inflection indicator for premium channel access bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Portion-Ready Packaging Automation | Robotics integration at break-pack facilities extracts labor cost arbitrage from Tyson Foods and JBS SA operations. |
| Direct Rancher Data Partnerships | Blockchain traceability tools unlock premium retail shelf placement for Cargill Inc. and Hormel Foods Corporation. |
| Captive Biogas Capture | Texas Panhandle feedlot clustering supports Scope 3 emissions reduction for National Beef Packing Company. |
| HACCP Validation Specialist Training | USDA FSIS compliance documentation requires personnel retention that rural processing communities struggle to maintain. |
| Cold Chain IoT Integration | Temperature logging sensor networks demand middleware investment that mid-tier packers like Perdue Farms Inc. defer. |
Research Methodology
Operator-level perspectives from feedlot managers, USDA FSIS compliance officers, restaurant chain procurement directors, and cold chain logistics coordinators anchored the qualitative base. Secondary validation drew from USDA NASS production statistics, FSIS establishment directories, state environmental permit databases, and SEC 10-K protein segment disclosures. Bottom-up volume modeling triangulated against top-down expenditure flow analysis.
Scenario-bracketing across feed grain price bands, regulatory compliance cost trajectories, and plant-based substitution rates framed the projection horizon. Segmentation dimensions modeled included species type, processing method intensity, distribution channel requirements, and packaging automation tier. CAGRs derived from historical throughput trajectories adjusted for capacity expansion announcements and state-level mandate implementation timelines. Industry-specific inputs incorporated feed conversion efficiency trends and cold chain infrastructure density metrics.
Stress conditions across corn and soybean meal volatility bands, California Proposition 12 enforcement intensity, and quick-service restaurant procurement consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and protein demand rotation velocity. Material shifts in federal-state regulatory divergence or breakthrough mycoprotein cost parity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Global Red Meat Market
Meat Products
Asia-Pacific Processed Meat Market
Meat Products
3D Printed Meat Market
Meat Products
Meat Tenderizer Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
Chilled Meat Market
Meat Products
Europe Bacon Market
Meat Products
Meat-Based FPP Market
Meat Products
Low-Fat Chorizo Market
Meat Products
Grass-Fed Meat Market
Meat Products
Organic Eggs Market
Meat Products
Pork Belly Meat Market
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
Middle East Red Meat Market
Meat Products
GCC Edible Meat Market
Meat Products
Beef Tallow Market