
 Confectionery Processing Equipment Market | 2026-2036
Confectionery Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Confectionery Processing Equipment Market Analysis
Artisan producers is collapsing into industrial-scale automation as craft confectioners scale output without sacrificing batch consistency. Bühler AG leverages its Swiss engineering heritage to dominate high-capacity chocolate tempering systems. Robert Bosch GmbH sustains competitive positioning through integrated packaging-to-processing workflows. Aasted ApS specializes in continuous enrobing technology that reduces manual intervention for mid-tier manufacturers.
Confectionery processing equipment encompasses machinery engineered to transform raw sugar, cocoa mass, and fat-based matrices into finished sweets through controlled thermal, mechanical, and aeration processes, typically operating within temperature bands of 28°C to 85°C depending on crystallization stage and product format. Its primary commercial purpose is to standardize throughput, reduce waste, and enforce food safety protocols across high-volume manufacturing environments. Chocolate Confectionery commands the largest installed base due to persistent consumer preference for cocoa-based indulgence products in Western Europe and North America. Continuous Processing represents the fastest-expanding technology segment as manufacturers replace batch kettles with extrusion-depositing hybrids to compress cycle times. Hard Candy applications retain mature margin pools in Asia-Pacific markets where traditional boiled-sugar formats dominate local portfolios.
FDA food-contact material regulations and EU MDR-equivalent hygiene standards for processing surfaces dictate stainless-steel grade specifications and clean-in-place protocol integration across export-oriented equipment lines. REACH chemical compliance and CE marking requirements constrain coating pan resin selections and electrical component sourcing for European-bound machinery. Stakeholders must monitor evolving ESG disclosure rules under CSRD and emerging state-level energy efficiency mandates that will reshape capital equipment procurement criteria for confectionery manufacturers.
Market Dynamics
Continuous extrusion-depositing hybrids are compressing batch cycle times and forcing mid-scale confectioners to retool or exit, while FDA and EU hygiene mandates recertify entire installed bases.
Growth Catalysts
- EU Hygiene Directives:Stainless-steel grade upgrades and clean-in-place protocol integration are accelerating replacement demand for legacy coating pans and tempering lines across export-oriented manufacturers.
- Clean-label consumer pull:Artisan producers are automating tempering and depositing to maintain batch consistency at scaled output without artificial stabilizers.
- Solingen-Hanover engineering cluster:Precision manufacturing concentration in Germany supplies integrated chocolate processing lines to mid-scale operators throughout Central Europe.
Market Restraints
- Stainless-steel input volatility:Grade 316L and 304 price swings compress margin on large-capacity tempering vessels and enrobing tunnels.
- REACH chemical compliance:Coating pan resin selections face constrained sourcing for European-bound machinery, extending procurement timelines.
- Technical skill concentration:Continuous processing system operation requires specialized thermal engineering expertise scarce outside Swiss and German technical institutes.
Strategic Opportunities
- India FSSAI modernization:Domestic confectionery manufacturers are upgrading from manual batch kettles to semi-automated depositing systems to meet evolving food safety standards.
- Energy efficiency mandates:Emerging state-level requirements in the US and EU Green Deal alignment are reshaping capital equipment procurement criteria toward heat-recovery tempering systems.
- Extrusion-enrobing convergence:Hybrid systems combining continuous forming with precision enrobing are opening white space in functional confectionery and protein-fortified formats.
Industry Challenges
- CE marking timeline compression:EU MDR-equivalent hygiene certifications for processing surfaces now require extended validation protocols, delaying commercial deployment.
- Legacy system integration:Retrofitting continuous processing lines into existing batch-oriented facilities demands custom mechanical bridging and control system harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Confectionery Processing Equipment Market |
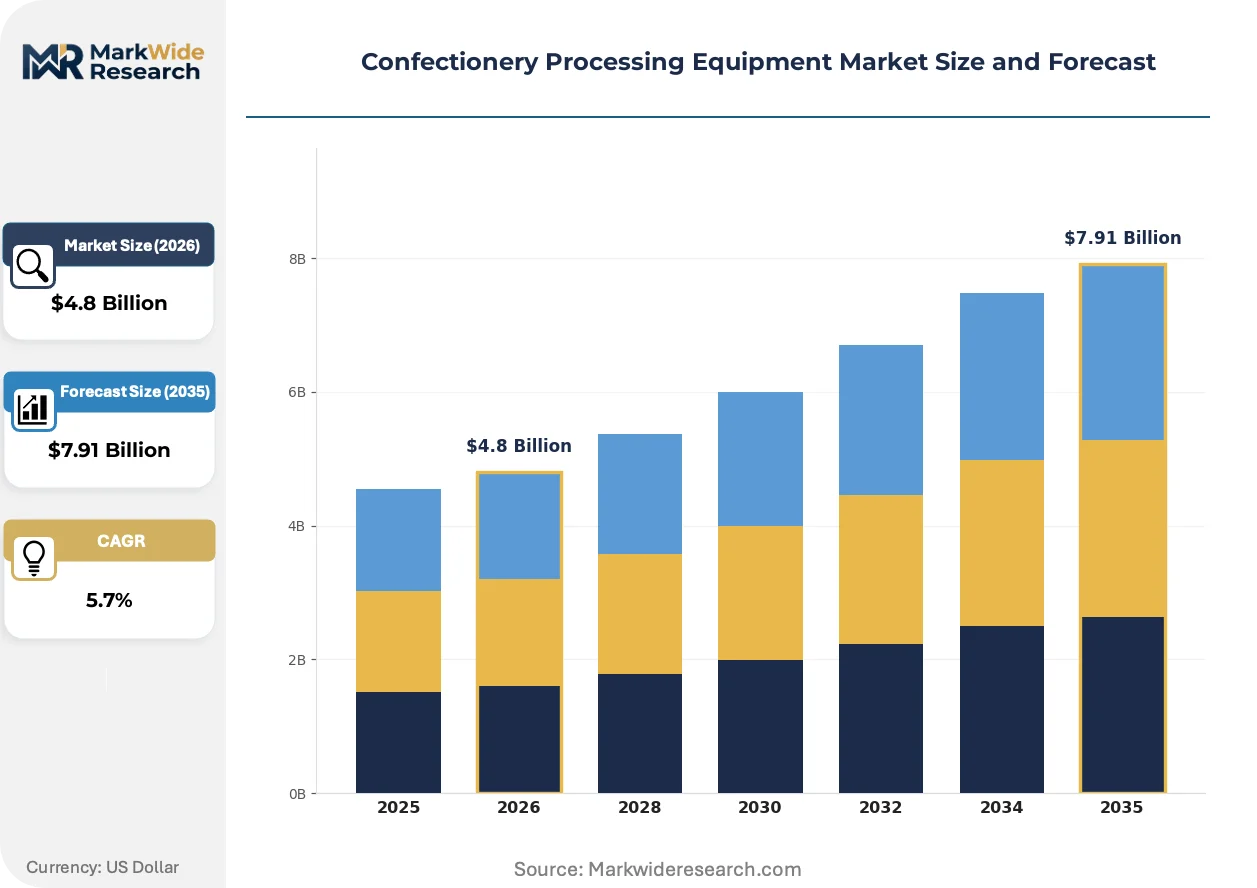
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Melting Tanks, Candy Depositors, Sugar Cookers, Coating Pans Technology: Batch Processing, Continuous Processing, Extrusion, Mixing End User: Artisan Producers, Industrial Manufacturers, Retailers, Food Service Application: Chocolate Confectionery, Hard Candy, Gum Products, Novelty Treats |
| Companies Covered | Robert Bosch GmbH, Bühler AG, GEA Group, Alfa Laval, JBT Corporation, Baker Perkins Limited, Heat and Control, Inc., Aasted ApS, Sollich KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Confectionery Processing Equipment Market Emerging Trajectories
Equipment intelligence and thermal precision are converging to eliminate manual intervention points, while regulatory disclosure requirements and service model unbundling reshape vendor-customer relationships.
Continuous enrobing technology is bifurcating the mid-tier manufacturer segment. Aasted ApS and comparable specialists deploy sensor-guided chocolate curtains that maintain temper stability across variable throughput. Mid-scale operators in Belgium and Switzerland are adopting these systems to compress labor content. The technology is bifurcating competitive position between automated continuous lines and manual batch operations.
CSRD disclosure rules are mandating granular ESG reporting across European confectionery supply chains. Equipment vendors must now document embodied carbon and energy efficiency metrics for tempering and depositing systems. German and Austrian manufacturers face the steepest compliance curves as their institutional investor bases demand audited sustainability data.
After-sales service unbundling is fragmenting traditional full-service contracts. Mid-scale confectioners in France and Italy now procure spare parts and remote diagnostics through specialized third-party channels rather than captive vendor networks. This pattern is most visible among hard candy producers seeking to reduce total cost of ownership on mature boiling and pulling equipment.
Confectionery Processing Equipment Market Segmentation
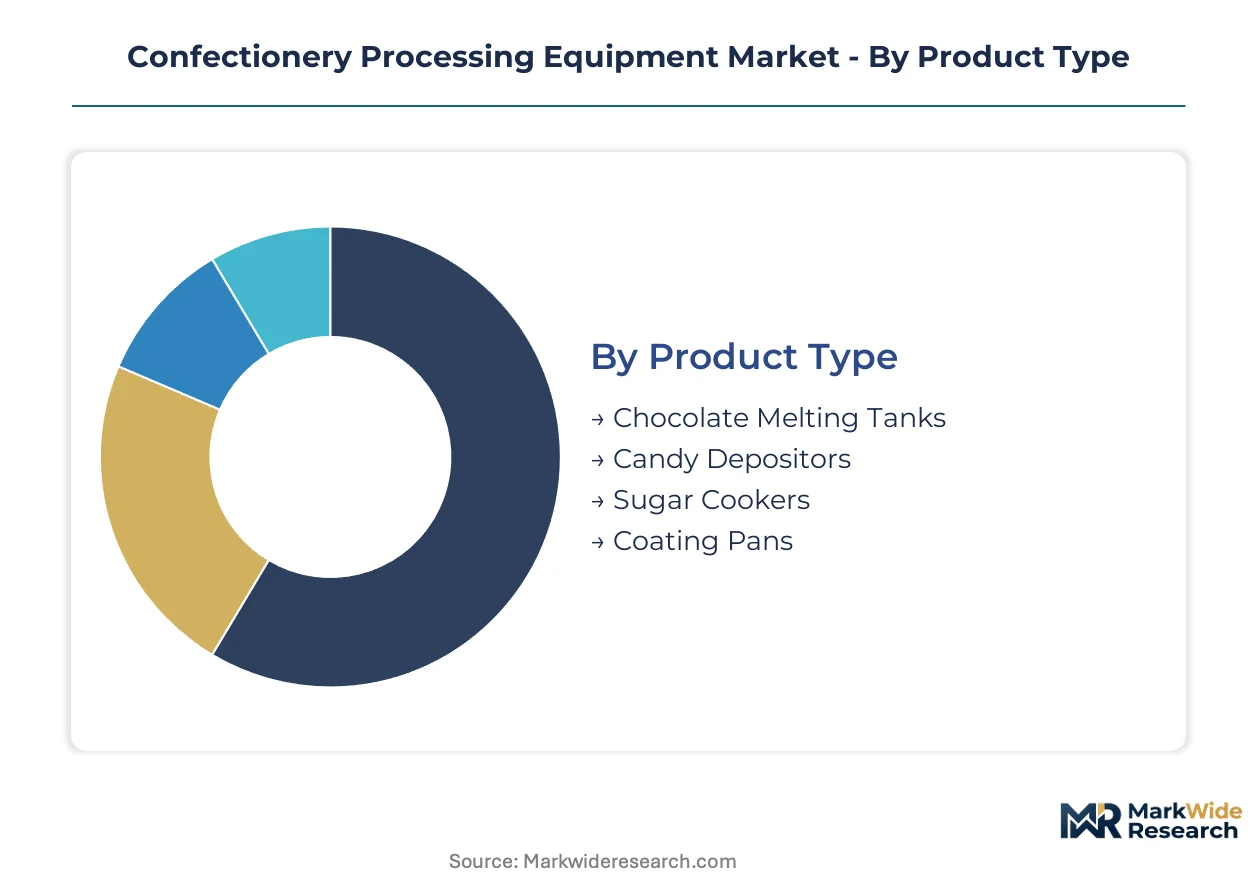
Equipment specification varies sharply across confectionery formats, with thermal control requirements and throughput scale dictating capital allocation patterns. Regulatory compliance tiers—FDA food-contact standards versus EU hygiene directives—further stratify procurement decisions by export destination.
Product Type:
FDA stainless-steel grade mandates and EU clean-in-place protocol requirements differentiate equipment certification tiers across export markets.
- Chocolate Melting Tanks:Jacketed vessels with precise temperature control maintain cocoa butter crystallization between 28°C and 32°C for tempering consistency. Demand concentrates among Belgian and Swiss mid-scale manufacturers automating batch-to-continuous transitions to meet clean-label output requirements without artificial stabilizers.
- Candy Depositors:Piston-driven or servo-controlled systems deposit viscous sugar masses into molds at controlled temperatures and speeds. German precision engineering clusters around Solingen and Hanover supply integrated depositing lines to Central European operators scaling artisan production.
- Sugar Cookers:Steam-jacketed kettles with vacuum capabilities control boiling curves for hard candy and caramel matrices.
- Coating Pans:Rotating drums with controlled airflow apply sugar or chocolate shells to centers; REACH compliance constrains resin selections for European-bound units.
Established volume favors Chocolate Melting Tanks; emerging adoption favors Candy Depositors.
Technology:
Capital intensity and labor substitution potential separate technology tiers, with continuous systems commanding premium pricing against batch alternatives.
- Continuous Processing:Extrusion-depositing hybrids compress cycle times through integrated forming, cooling, and cutting stages. Adoption accelerates among mid-tier manufacturers in France and Italy replacing manual batch kettles to reduce labor content and enforce batch consistency.
- Batch Processing:Discrete kettle and pan operations retain foothold among artisan producers and specialty format manufacturers.
- Extrusion:Screw-driven forming systems shape viscous masses into ropes or sheets prior to cutting or enrobing.
- Mixing:High-shear and planetary mixers aerate fat-sugar matrices for nougat and marshmallow applications.
Capital deployment concentrates on Continuous Processing; margin preservation sustains Batch Processing among craft operators.
End User:
Scale requirements and technical staffing depth determine equipment complexity thresholds across customer categories.
- Industrial Manufacturers:High-throughput lines with SCADA integration and clean-in-place automation serve multinational confectioners. These operators in Germany and Austria face steep CSRD disclosure curves demanding documented energy efficiency and embodied carbon metrics from equipment vendors.
- Artisan Producers:Small-batch tempering and depositing systems balance automation with recipe flexibility.
- Retailers:Private-label manufacturers procure semi-automated lines for store-brand confectionery production.
- Food Service:Compact melting and dispensing units serve hotel and restaurant in-house confectionery operations.
Equipment specification complexity peaks with Industrial Manufacturers; automation penetration climbs fastest among Artisan Producers.
Application:
Regional consumption patterns and format maturity shape application-specific equipment demand curves.
- Chocolate Confectionery:Tempering, enrobing, and molding systems dominate installed value through persistent Western European and North American preference for cocoa-based indulgence products. Swiss and Belgian manufacturers anchor precision equipment demand for praline and tablet production.
- Hard Candy:Boiling, pulling, and forming equipment serves traditional sugar confectionery formats retaining strength in Asia-Pacific markets.
- Gum Products:Specialized mixing and extrusion systems process elastomer bases with flavor and sweetener matrices.
- Novelty Treats:Flexible depositing and molding lines accommodate seasonal and licensed character formats with rapid changeover requirements.
Revenue concentration rests with Chocolate Confectionery; format diversification drives Novelty Treats equipment flexibility requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters export integrated chocolate processing lines to mid-scale manufacturers across Belgium, Switzerland, and France. Solingen and Hanover anchor this trade corridor with specialized tempering and enrobing capabilities.
Germany
Demand concentrates among mid-scale manufacturers automating batch-to-continuous transitions for clean-label output. EU hygiene directives and CE marking requirements accelerate stainless-steel grade upgrades across coating pans and tempering vessels. The Solingen-Hanover engineering corridor supplies precision depositing systems to Central European confectioners scaling artisan production.
United States
Industrial manufacturers face emerging state-level energy efficiency mandates reshaping capital equipment procurement toward heat-recovery tempering systems. FDA food-contact material regulations dictate stainless-steel specifications and clean-in-place protocol integration for export-oriented lines. Midwest confectionery hubs in Illinois and Wisconsin drive replacement demand for legacy batch kettles with continuous extrusion-depositing hybrids.
Belgium
Mid-scale praline and tablet producers automate tempering to maintain batch consistency without artificial stabilizers. REACH chemical compliance constrains coating pan resin selections for European-bound machinery, extending procurement timelines. The Brussels-Antwerp corridor concentrates demand for sensor-guided chocolate enrobing systems that compress labor content.
Switzerland
Artisan producers scaling output drive premium-tier demand for precision tempering systems maintaining cocoa butter crystallization between 28°C and 32°C. CSRD disclosure rules mandate granular ESG reporting across equipment supply chains, forcing vendors to document embodied carbon metrics. The Zurich-Basel axis anchors technical expertise for continuous processing system operation scarce outside German technical institutes.
India
Domestic confectionery manufacturers upgrade from manual batch kettles to semi-automated depositing systems to meet evolving FSSAI food safety standards. BIS certification requirements and FSSAI modernization programs reshape equipment procurement criteria for mid-tier operators. Maharashtra and Gujarat industrial corridors concentrate demand for entry-level continuous processing lines serving traditional boiled-sugar formats.
Confectionery Processing Equipment Market Vendor Landscape
Listed leaders compete with private specialists across engineering heritage and service model dimensions. The vendor base stratifies between consolidated multinationals with integrated packaging-to-processing workflows and mid-cap precision specialists dominating niche thermal applications. Three archetypes predominate: Swiss-German engineering houses with continuous processing expertise, diversified industrial conglomerates with captive food technology divisions, and Danish-British specialists in enrobing and depositing subsystems. Competitive moves center on strategic partnerships for clean-in-place protocol integration and geographic expansion into FSSAI-modernizing markets.
Among Swiss-German engineering houses, Bühler AG and Robert Bosch GmbH exemplify divergent scale strategies within premium-tier positioning. Bühler AG occupies a position as a heritage-engineering archetype, while Robert Bosch GmbH represents diversified industrial conglomerate integration into food processing workflows. Aasted ApS anchors the Danish specialist tier, sitting within the continuous enrobing technology segment where sensor-guided systems reduce manual intervention for mid-tier manufacturers. These three entities collectively represent the competitive spectrum from integrated conglomerate to focused subsystem specialist.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Bühler AG |
| GEA Group |
| Alfa Laval |
| JBT Corporation |
| Baker Perkins Limited |
| Heat and Control, Inc. |
| Aasted ApS |
| Sollich KG |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with German precision engineering houses lock in stainless-steel grade specifications and clean-in-place protocol integration for mid-scale confectioners across Belgium and Switzerland, anchoring both supply access and five-year price visibility against Grade 316L volatility.
Pricing Analysis
Current-generation continuous extrusion-depositing hybrids command 40-60% premiums over prior-generation batch kettles, while next-generation sensor-guided enrobing systems with SCADA integration sit at the apex. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked EU-compliant lines from FDA-tier North American specifications and entry-level BIS-certified units for India. Pricing pressure stems from stainless-steel input volatility compressing margins on large-capacity tempering vessels. Artisan producers in France and Italy exhibit highest price sensitivity, prioritizing spare parts unbundling over full-service contracts, while industrial manufacturers in Germany accept premium positioning for documented energy efficiency metrics under CSRD disclosure rules.
Supply Chain Analysis
Germany and Switzerland anchor precision manufacturing for tempering and enrobing systems, while Denmark specializes in continuous enrobing subsystems and Italy retains footholds in coating pan fabrication. Stainless-steel Grade 316L and 304, servo-controlled depositing mechanisms, and vacuum-capable sugar cooking kettles constitute critical component tiers. Single-source vulnerability concentrates in Swiss-German thermal engineering expertise for continuous processing system operation. Distribution runs through direct vendor relationships for integrated lines and specialized third-party channels for spare parts and remote diagnostics among hard candy producers in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service unbundling is expanding faster than hardware sales as mid-scale confectioners in France and Italy procure spare parts and remote diagnostics through specialized third-party channels, transforming vendor-customer relationships into recurring-revenue architectures.
For Market Incumbents: Secure clean-in-place protocol integration partnerships with stainless-steel fabricators to defend against emerging Danish-British subsystem specialists capturing enrobing share. Backward integration into Grade 316L sourcing buffers margin compression from commodity volatility. Investment in heat-recovery tempering technology addresses emerging state-level energy efficiency mandates in the US Midwest. For New Entrants and Emerging Players: Differentiate on FSSAI modernization readiness for India's Maharashtra and Gujarat industrial corridors, where domestic manufacturers upgrade from manual batch kettles to semi-automated depositing systems. Target entry-level continuous processing lines for traditional boiled-sugar formats. Partner with German technical institutes to bridge capability scarcity in thermal engineering expertise. For Investors and Strategic Acquirers: Danish-British enrobing specialists with sensor-guided chocolate curtain technology represent attractive acquisition targets as continuous processing bifurcates the mid-tier segment. Long-term viability hinges on CSRD disclosure compliance capabilities and documented embodied carbon metrics. Watch for FSSAI modernization program acceleration as inflection indicator for India market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-in-Place Protocol Integration | CE marking and FDA compliance now require validated CIP systems, reshaping equipment certification tiers. |
| Backward Integration into Stainless-Steel Sourcing | Grade 316L price volatility compresses margins on tempering vessels, favoring captive supply arrangements. |
| Heat-Recovery Tempering System Development | EU Green Deal alignment and US state-level mandates reshape procurement criteria toward energy efficiency. |
| FSSAI Modernization Partnership Programs | India's Maharashtra and Gujarat corridors drive demand for entry-level continuous processing lines. |
| After-Sales Service Unbundling | Mid-scale French and Italian confectioners now procure spare parts through specialized third-party channels. |
Methodological Framework
Operator-level perspectives from plant engineers at Belgian praline manufacturers, maintenance directors at German industrial confectioners, procurement leads at Swiss chocolate houses, and aftermarket service heads at Italian hard candy producers anchored the qualitative base. These primary insights combined with secondary validation from CE marking databases, FDA food-contact material filings, FSSAI modernization program disclosures, and EU ESG reporting frameworks under CSRD. Bottom-up equipment shipment tracking and top-down confectionery production capacity analysis provided triangulation across modeling approaches.
Sensitivity analysis around stainless-steel price volatility, regulatory timeline compression for CE marking, and FSSAI enforcement intensity informed scenario boundaries across the projection horizon. Segmentation dimensions modeled include equipment product type, processing technology tier, end-user scale category, and confectionery application format. CAGRs derived from installed base replacement cycles and greenfield capacity additions. Industry-specific forecast inputs encompass EU hygiene directive implementation pace and India BIS certification adoption curves.
Material uncertainties — Grade 316L commodity swings, CE marking validation delays, and FSSAI enforcement variability — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization between EU and FDA food-contact standards and continuity of German-Swiss engineering cluster dominance. Recalibration cycles align with material shifts in stainless-steel pricing, energy efficiency mandate adoption, and CSRD disclosure rule evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food & Beverages
Veggie Burger Market
Food & Beverages
Tuberose Extract Market
Food & Beverages
Sheep Milk Cheese Market
Food & Beverages
Food Acidulants Market
Food & Beverages
Bypass Fat Supplement Market
Food & Beverages
Allergen Free Food Market
Food & Beverages
South America Agar Market
Food & Beverages
Low Calorie Cookies Market
Food & Beverages
Resistant Starch Market
Food & Beverages
Food Thickening Agents Market
Food & Beverages
Portable Juicer Market
Food & Beverages
Africa Plant Protein Ingredients Market
Food & Beverages
Commercial Deep Fryer Parts and Accessories Market
Food & Beverages
Coffee Pods and Capsules Market
Food & Beverages
Spain Organic Food Market
Food & Beverages
Asia-Pacific Frozen Pizza Market