
 Collagen Supplements Market | 2026-2036
Collagen Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Collagen Supplements Market Analysis
Asset-light contract manufacturing and white-label financing is reshaping how mid-sized brands enter the collagen supplements space without capital-intensive production facilities. Vital Proteins LLC leverages its direct-to-consumer infrastructure to sustain premium positioning across North American markets. Everest NeoCell LLC anchors its competitive stance through specialized bovine-sourced formulations. BioTechUSA dominates Central European distribution through controlled pharmacy and fitness retail channels.
Collagen supplements comprise hydrolyzed amino acid chains derived from animal connective tissue or marine sources, primarily delivering glycine, proline, and hydroxyproline to support dermal matrix integrity and joint cartilage maintenance. Powder formats lead volume sales due to formulation flexibility in functional beverages and meal replacements, while marine collagen commands price premiums among clean-label consumers. The online distribution channel captures the fastest growth trajectory as subscription models reduce customer acquisition costs for emerging entrants.
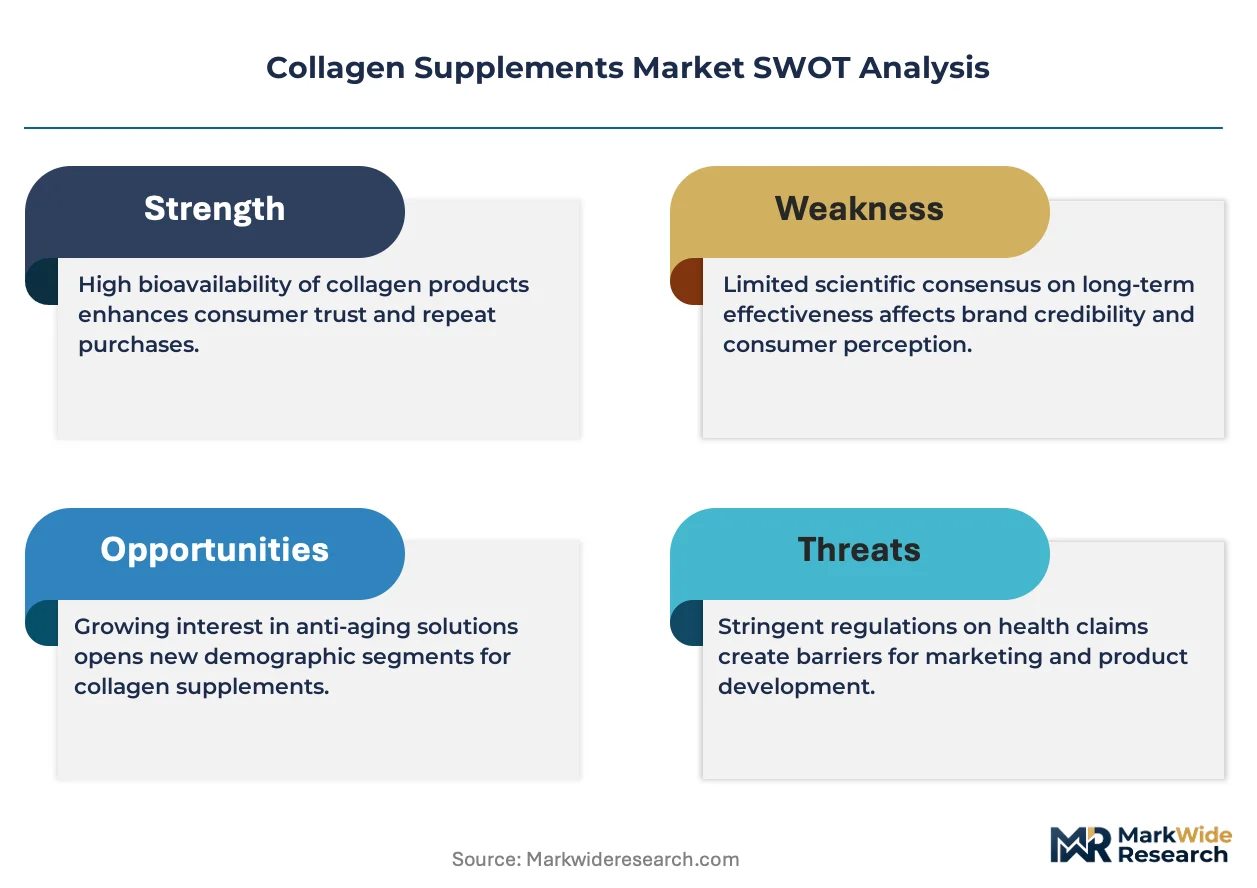
FDA New Dietary Ingredient notifications and EFSA health claim assessments create divergent compliance burdens for cross-border collagen marketers, with the EU's stricter substantiation requirements limiting certain structural and beauty-positioned SKUs. The report indicates stakeholders must monitor evolving EFSA opinions on collagen-specific health claims and adapt label architectures accordingly. Procurement decisions around source traceability and third-party certification will separate compliant suppliers from enforcement-vulnerable competitors.
Market Dynamics
The collagen supplements sector is experiencing structural compression as contract manufacturing networks expand, enabling mid-sized brands to launch formulations without captive production assets. This asset-light entry model is reshaping competitive density and margin pressure across North American and European markets.
Growth Catalysts
- Regulatory pathway maturation:The FDA's New Dietary Ingredient notification framework provides clearer entry protocols for novel collagen peptide structures, reducing pre-market uncertainty for innovative formulations.
- Functional beverage integration:Hydrolyzed collagen peptides are penetrating ready-to-drink protein portfolios and meal replacement lines, expanding addressable occasions beyond traditional supplement capsules.
- Subscription commerce infrastructure:Direct-to-consumer platforms with automated replenishment are compressing customer acquisition costs for emerging entrants in the United States.
Market Restraints
- Bovine supply concentration:Premium hide and bone sourcing clusters in Brazilian and Argentine processing facilities, exposing formulators to livestock cycle volatility and export tariff friction.
- Marine collagen cost structure:Wild-caught fish scale and skin procurement from North Atlantic fisheries carries 40-60% raw material premiums over terrestrial alternatives, limiting mass-market penetration.
- EFSA substantiation barriers:The European Food Safety Authority's strict health claim assessment protocols block structural and beauty-positioned SKUs from EU markets, fragmenting product architectures.
Strategic Opportunities
- Pharmacy channel expansion:Controlled pharmacy and fitness retail networks in Germany, Poland, and Czech Republic remain underpenetrated by marine collagen specialists.
- Clean-label certification convergence:MSC marine stewardship and grass-fed bovine certifications are creating premium price tiers that command shelf space in UK and Netherlands health stores.
- Sports nutrition cross-selling:Post-workout recovery positioning aligns collagen with branched-chain amino acid portfolios, opening access to gym-based distribution in urban Australia.
Industry Challenges
- Third-party certification timelines:NSF Certified for Sport and Informed Choice testing protocols add 12-16 week delays to product launches, compressing seasonal marketing windows.
- Source traceability integration:Blockchain-enabled supply chain verification requires capital investment in data infrastructure that strains mid-tier brand balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collagen Supplements Market |
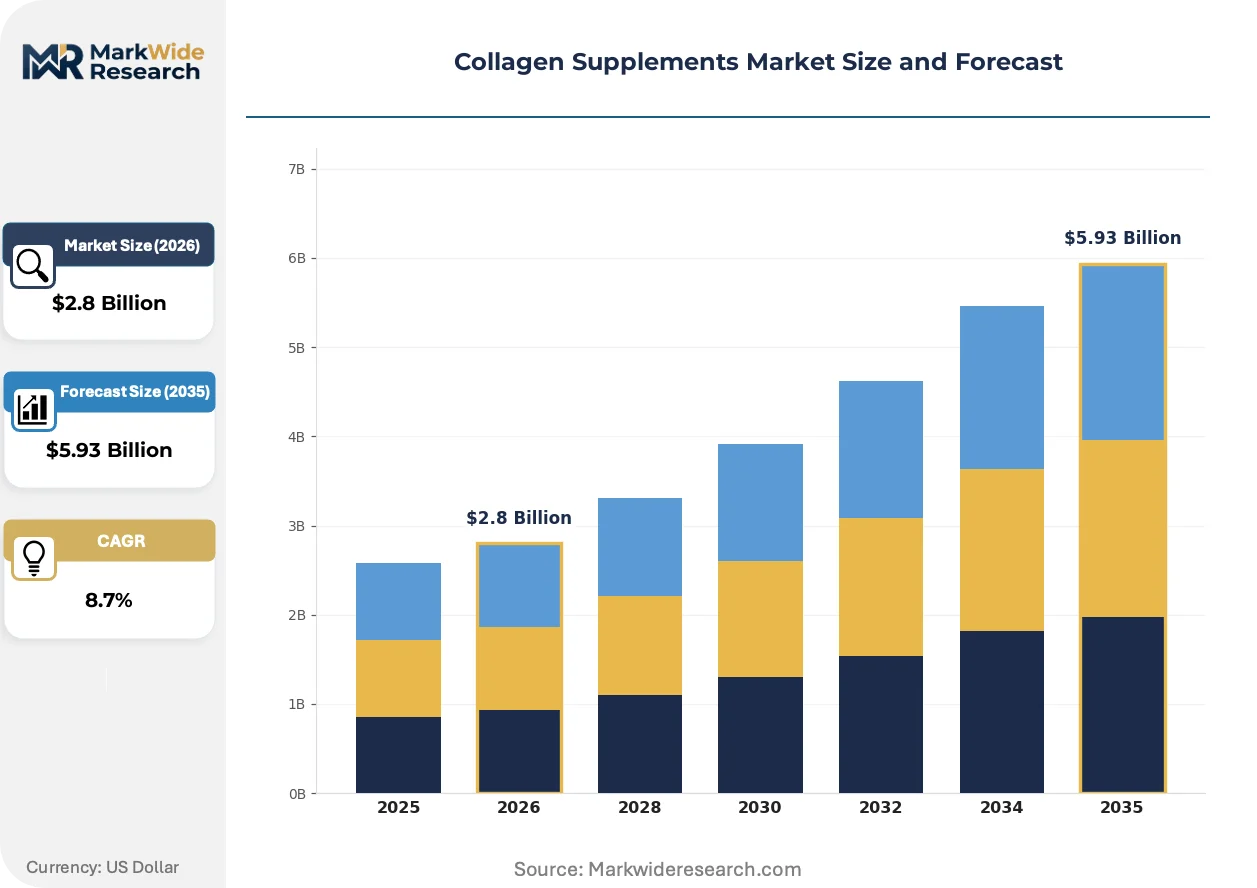
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Marine Collagen Source: Bovine, Porcine, Marine, Vegetarian Form: Powder, Liquid, Capsules, Tablets Distribution Channel: Online, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Vital Proteins LLC, Optimum Nutrition, Inc, Everest NeoCell LLC, Nestlé Health Science, Ancient Nutrition, Further Food, BioTechUSA, Codeage LLC, Youtheory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collagen Supplements Market Emerging Trajectories
Enzymatic hydrolysis and precision fermentation technologies are collapsing traditional extraction economics, enabling novel collagen structures from non-animal substrates. These process innovations are compressing development timelines and expanding the addressable ingredient base beyond conventional bovine and marine sources.
Precision fermentation of recombinant collagen proteins is collapsing the cost structure of laboratory-cultivated alternatives. Biotech ingredient suppliers in Singapore and California are scaling pilot facilities. This technology is collapsing the premium pricing power of wild-caught marine collagen in clean-label segments.
EFSA's evolving opinions on collagen-specific health claims are tightening label architectures across European markets. The regulator's draft assessments on joint mobility and skin elasticity claims are forcing reformulators toward vaguer functional positioning. French and Italian brands are responding by pivoting toward cosmetic-grade ingestible positioning outside the novel food framework.
Fitness-focused millennials in the United States are consolidating purchase decisions around subscription-enabled direct brands. Traditional mass retail and pharmacy channels are losing traffic to Instagram-native entrants with influencer-backed education. This behavioral shift is most visible in coastal metropolitan markets where gym penetration and wellness expenditure cluster.
Collagen Supplements Market Segmentation
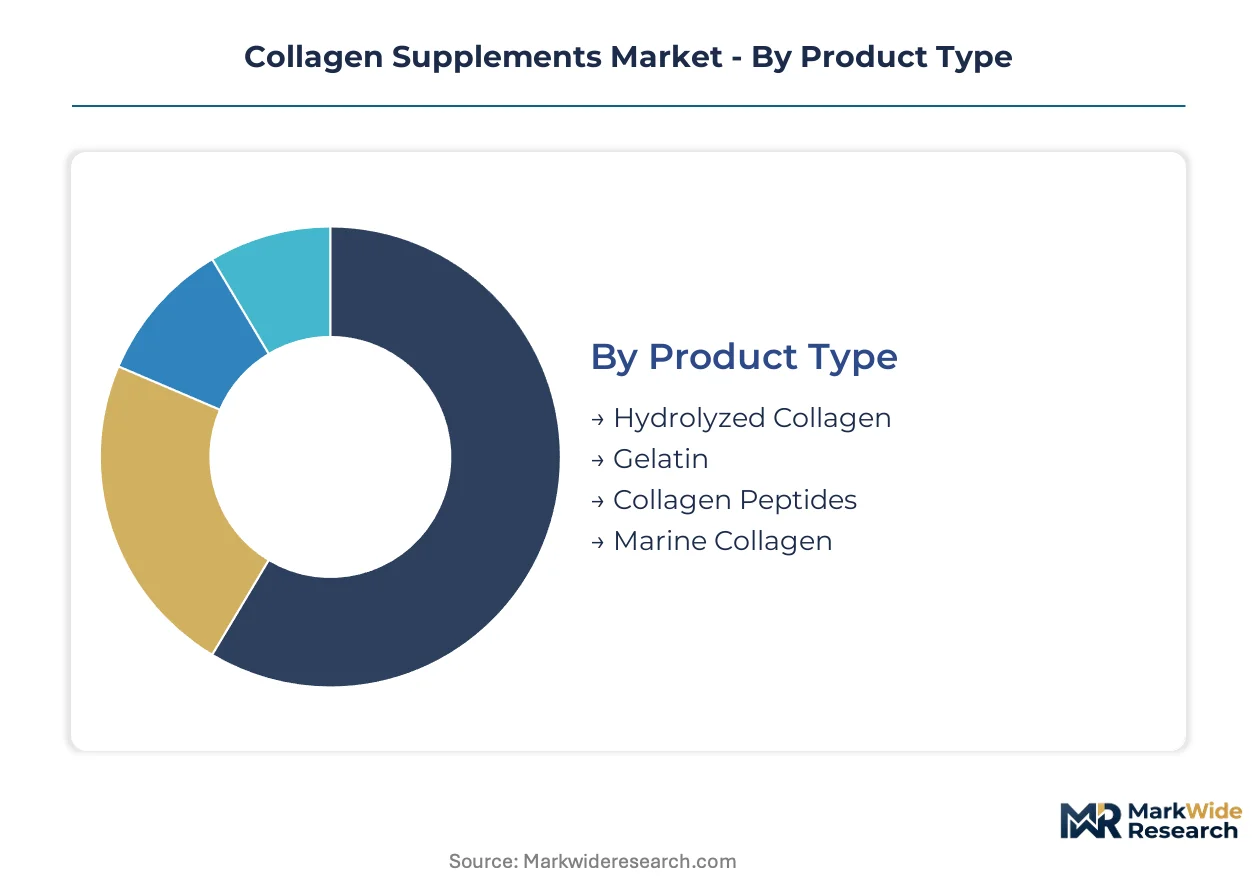
Collagen supplement segmentation reveals divergent margin profiles and inventory velocities across product architectures. Manufacturers optimize working capital by matching production cycles to channel-specific demand patterns.
Product Type:
Hydrolyzed Collagen turns inventory fastest through beverage integration, while Gelatin moves slowest due to industrial bulk contracting cycles.
- Hydrolyzed Collagen:Enzymatically cleaved peptide chains with molecular weights below 10 kDa enable cold-water solubility for RTD applications. Fitness-focused millennials in the United States drive replenishment velocity through subscription-enabled direct brands.
- Collagen Peptides:Standardized bioactive fractions optimized for dermal matrix and joint cartilage support claims. Controlled pharmacy networks in Germany and Poland concentrate demand for clinically positioned SKUs with third-party substantiation.
- Gelatin:Partially hydrolyzed collagen with gelling functionality for food and pharmaceutical encapsulation. Industrial buyers in Brazil and Argentina negotiate annual volume contracts with limited formulation flexibility.
- Marine Collagen:Wild-caught fish scale and skin derivatives delivering Type I collagen dominance for clean-label positioning. MSC certification requirements extend procurement timelines for UK and Netherlands health store distribution.
Hydrolyzed Collagen anchors the volume base while Marine Collagen gains share at the steepest rate.
Source:
Cost tier stratification separates commodity bovine inputs from premium marine and fermentation-derived alternatives.
- Bovine:Hide and bone-derived Types I and III collagen from Brazilian and Argentine processing facilities. Livestock cycle volatility and export tariff friction expose formulators to margin compression.
- Marine:North Atlantic wild-caught fish scale procurement carrying raw material premiums over terrestrial alternatives. Singapore and California biotech suppliers are scaling precision fermentation pilots to collapse this premium structure.
- Porcine:Skin and tendon-derived collagen optimized for pharmaceutical-grade applications. Religious dietary restrictions limit addressable markets in Middle Eastern and South Asian geographies.
- Vegetarian:Recombinant collagen proteins from precision fermentation of yeast or bacterial substrates. EFSA novel food assessments create 18-24 month approval timelines for EU market entry.
Bovine sources dominate tonnage while fermentation-derived alternatives are expanding most quickly.
Form:
Application flexibility determines channel access and price realization across delivery formats.
- Powder:Bulk hydrolyzed peptides enabling consumer formulation in functional beverages and meal replacements. Gym-based distribution in urban Australia and coastal US metropolitan markets concentrates demand.
- Liquid:Ready-to-consume shots and vials with immediate bioavailability positioning. Pharmacy and fitness retail channels in Central Europe favor this format for clinical credibility.
- Capsules:Pre-measured dosing for compliance-focused consumers seeking joint and skin maintenance protocols. Amazon-native brands in the United States optimize capsule SKUs for subscription replenishment algorithms.
- Tablets:Compressed formulations with extended shelf stability for mass retail distribution. Supermarket buyers in France and Italy demand tablet formats for promotional merchandising efficiency.
Powder formats capture the largest volume share while Liquid climbs the fastest through pharmacy channel expansion.
Distribution Channel:
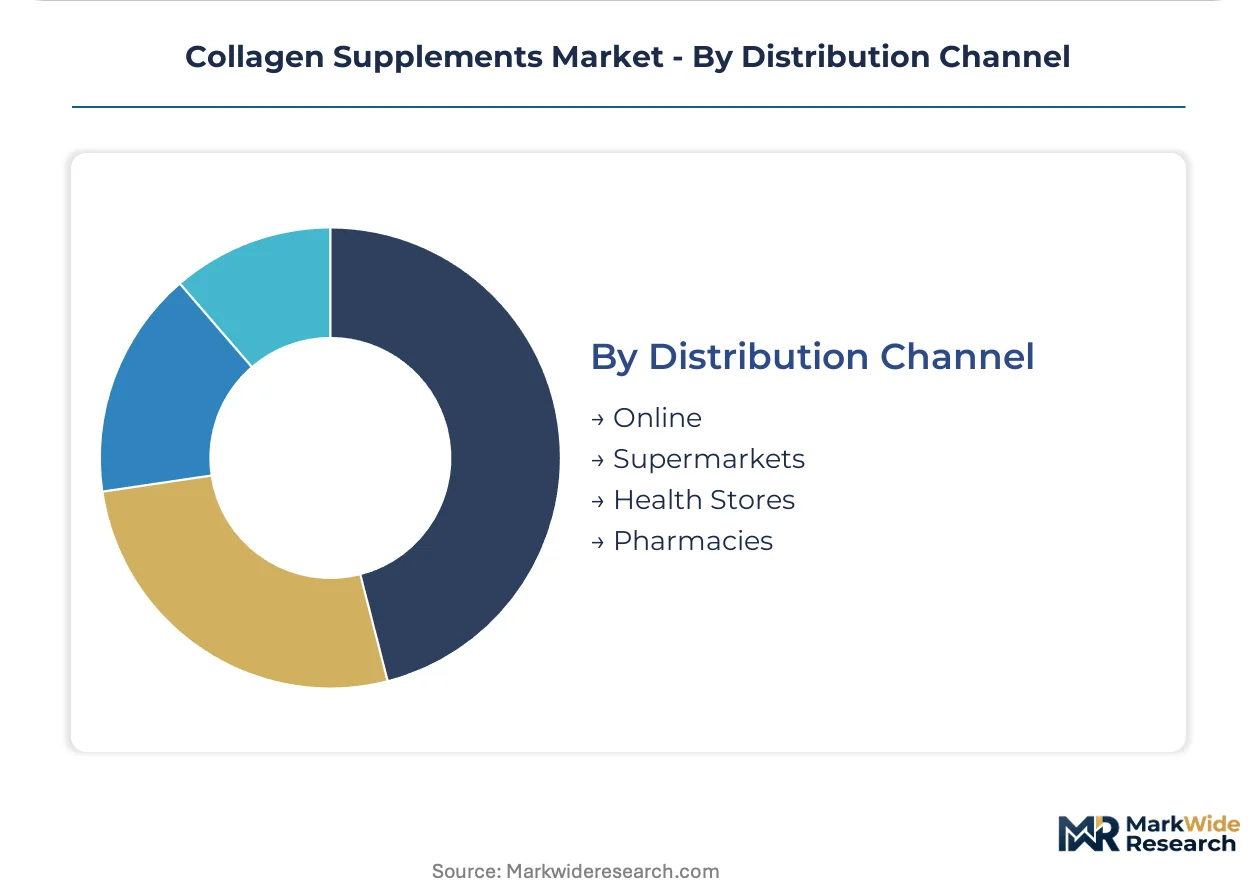
Customer acquisition economics separate high-velocity digital platforms from relationship-dependent physical retail.
- Online:Direct-to-consumer platforms with automated replenishment compressing acquisition costs for emerging entrants. Instagram-native brands with influencer-backed education are consolidating millennial purchase decisions in the United States.
- Health Stores:Specialist retail with trained staff enabling premium positioning for certified clean-label SKUs. UK and Netherlands independents command shelf space for MSC marine stewardship and grass-fed bovine tiers.
- Supermarkets:Mass retail with promotional intensity and private-label competition pressuring branded margins. French and Italian chains are expanding ingestible cosmetic positioning to circumvent EFSA health claim restrictions.
- Pharmacies:Controlled networks with clinical credibility requirements and pharmacist recommendation dynamics. German, Polish, and Czech pharmacy chains remain underpenetrated by marine collagen specialists.
Online channels lead expansion velocity while Health Stores sustain the highest per-unit price realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness-focused millennials concentrate purchase power in United States coastal metropolitan markets, while pharmacy-controlled networks in Central Europe sustain clinically positioned demand. Subscription-enabled direct brands reshape acquisition economics in English-speaking markets. EFSA regulatory friction fragments product architectures across continental Europe.
United States
Instagram-native entrants with influencer-backed education consolidate millennial purchase decisions in coastal metropolitan markets. FDA New Dietary Ingredient notifications provide clearer entry protocols for novel collagen peptide structures. Greater Los Angeles and New York Metro clusters anchor direct-to-consumer brand headquarters and fulfillment infrastructure.
Germany
Controlled pharmacy networks concentrate demand for clinically positioned SKUs with third-party substantiation. EFSA health claim assessment protocols block structural and beauty-positioned products from EU market entry. Bavaria and North Rhine-Westphalia house distribution headquarters serving Central European fitness retail channels.
United Kingdom
Health store independents command shelf space for MSC marine stewardship and grass-fed bovine certification tiers. MHRA oversight aligns with EFSA substantiation requirements for ingestible cosmetic positioning. London and Southeast England clusters sustain premium clean-label brand headquarters and specialist retail relationships.
Australia
Gym-based distribution in urban markets concentrates post-workout recovery positioning alongside branched-chain amino acid portfolios. TGA regulatory frameworks govern therapeutic claim substantiation for pharmacy-channel entrants. Sydney and Melbourne metropolitan areas anchor sports nutrition cross-selling infrastructure.
Singapore
Biotech ingredient suppliers scale precision fermentation pilots to collapse wild-caught marine collagen premium structures. HSA novel food assessments create approval timelines for recombinant protein market entry. The city-state's biomanufacturing corridor anchors laboratory-cultivated alternative development.
Collagen Supplements Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent margin profiles and inventory velocities. The vendor base stratifies between mass-market nutrition conglomerates and premium-positioned direct-to-consumer specialists. Three archetypes dominate: subscription-enabled digital natives, pharmacy-network incumbents, and contract-manufacturing-dependent mid-tier entrants. Competitive moves concentrate on M&A for channel access and portfolio diversification into adjacent functional beverage lines.
Among North American direct-to-consumer specialists, Vital Proteins LLC and Ancient Nutrition occupy positions within the premium-tier subscription vector. Everest NeoCell LLC anchors the specialized bovine-sourced formulation archetype. BioTechUSA represents the pharmacy-controlled network model across Central European markets.
| Leading Market Players |
|---|
| Vital Proteins LLC |
| Optimum Nutrition, Inc |
| Everest NeoCell LLC |
| Nestlé Health Science |
| Ancient Nutrition |
| Further Food |
| BioTechUSA |
| Codeage LLC |
| Youtheory |
| Others |
Supply Flow & Price Mechanics
Panama Canal transit corridors anchor freight cost dynamics for Brazilian hide and bone exports, compressing margin structures for North American formulators while amplifying price differentiation between terrestrial and marine collagen tiers. This logistics chokepoint concentrates supply-side bargaining power among Argentine and Brazilian processors, forcing downstream brands to absorb tariff volatility or shift procurement toward fermented alternatives.
Pricing Analysis
Cost-plus contracts indexed to Brazilian livestock futures dominate raw material procurement, with hide and bone processors passing through feed cost fluctuations to formulators. Price differentiation hinges on MSC marine stewardship certification and third-party NSF sport testing tiers. Pricing pressure stems from precision fermentation pilots in Singapore collapsing wild-caught marine premiums. Industrial bulk buyers in Brazil exhibit highest price sensitivity; clean-label health store independents in the Netherlands show least.
Supply Chain Analysis
Supplier financing facilities with 90-day extended terms are emerging from Argentine processing cooperatives to lock in annual volume commitments from mid-tier brands. Raw material sourcing draws from Brazilian hide processors, North Atlantic wild-caught fisheries, and Singapore biomanufacturing pilots. Supply chain risk centers on single-source vulnerability for Type I marine collagen from Icelandic and Norwegian fisheries. Distribution runs through direct-to-consumer subscription platforms, controlled pharmacy networks, and specialist health store independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Collagen supplements function as a service-attach business where subscription replenishment algorithms and personalized nutrition consulting layers expand faster than standalone product sales. Recurring revenue from automated direct-to-consumer platforms now outpaces traditional retail velocity.
For Market Incumbents:Entrench pharmacy channel control in Germany and Poland through exclusive clinical substantiation partnerships that block private-label erosion. Deepen backward integration into Brazilian hide processing to neutralize livestock cycle volatility threatening margin stability. Precision fermentation entrants from Singapore represent the most acute substitution threat requiring monitoring.
For New Entrants and Emerging Players:Central European pharmacy networks in the Czech Republic and urban Australian gym-based distribution represent the most penetrable entry points with limited incumbent saturation. Marine collagen specialists remain absent from German pharmacist recommendation dynamics. Direct-to-consumer launch with influencer-backed education on post-workout recovery protocols offers lowest customer acquisition cost trajectory.
For Investors and Strategic Acquirers:Contract-manufacturing-dependent mid-tier brands with established subscription infrastructure and clean-label certification portfolios offer the strongest acquisition profile for platform consolidation. Long-term viability rests on defensible sourcing relationships and regulatory navigation capabilities across FDA and EFSA frameworks. Watch for EFSA draft opinions on joint mobility claims as the critical inflection signal for European market access restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Singapore and California biotech facilities are collapsing wild-caught marine collagen cost premiums through recombinant protein production. |
| Pharmacy Channel Expansion | German and Polish controlled networks remain underpenetrated by marine collagen specialists seeking clinical credibility positioning. |
| Subscription Platform Integration | Automated replenishment algorithms compress customer acquisition costs for Instagram-native brands targeting coastal US millennials. |
| Clean-Label Certification Convergence | MSC marine stewardship and grass-fed bovine tiers command shelf space in UK and Netherlands health store independents. |
| Sports Nutrition Cross-Selling | Post-workout recovery positioning aligns collagen with branched-chain amino acid portfolios in urban Australian gym distribution. |
Methodological Framework
Desk research of FDA New Dietary Ingredient notifications, EFSA health claim assessment archives, and customs trade data preceded structured interviews with brand managers at direct-to-consumer supplement companies, procurement leads at Brazilian hide processors, pharmacy category buyers in Germany, and regulatory affairs specialists navigating novel food pathways. Primary fieldwork with subscription platform operators and health store independents in the UK and Netherlands combined with secondary validation against NSF and Informed Choice certification databases. Bottom-up SKU velocity analysis and top-down market sizing triangulated volume estimates.
Assumptions around FDA notification pathway stability and EFSA substantiation stringency were held fixed across the projection horizon, while livestock cycle volatility and precision fermentation cost curves were stress-tested through sensitivity scenarios. Segmentation modeling incorporated product type, source origin, delivery format, and distribution channel dimensions with regional regulatory cluster overlays. CAGRs were derived from fitted growth curves against historical replenishment velocity patterns and channel expansion trajectories. Forecast inputs included gym penetration rates in metropolitan Australia and influencer marketing spend efficiency ratios.
Practitioners should monitor EFSA draft opinion releases, Brazilian export tariff adjustments, and Singapore biomanufacturing capacity announcements for early signals requiring forecast reassessment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Dietary Supplements Market
Nutritional Supplements
US Ketones Market
Nutritional Supplements
Bone Broth Protein Powder Market
Nutritional Supplements
Conjugated Linoleic Acid Market
Nutritional Supplements
Concentrate Protein Market
Nutritional Supplements
Effervescent Product Market
Nutritional Supplements
Direct Fed Microbials Market
Nutritional Supplements
Coral Calcium Supplements Market
Nutritional Supplements
Australia Whey Protein Market
Nutritional Supplements
Vitamin Shot Market
Nutritional Supplements
Elderberry Extract Market
Nutritional Supplements
Phytoestrogen Supplements Market
Nutritional Supplements
Vegan Collagen Powder Market
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
Prickly Pear Seed Oil Nutricosmetic Bases Market
Nutritional Supplements
Vietnam Collagen Supplements Market