
 Chocolate Spread Market | 2026-2036
Chocolate Spread Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Spread Market Analysis
Premium hazelnut content tiers is collapsing the gap between artisanal positioning and mass-market accessibility across retail channels. Ferrero Group leverages its vertically integrated hazelnut supply from Turkish orchards to sustain margin control at scale. Nestle anchors European shelf presence through co-manufacturing partnerships with regional dairies. Hershey Co. competes in North American private-label supply, differentiating through cocoa sourcing transparency programs.
Chocolate spread is a fat-based confectionery paste containing cocoa solids, sugar, and vegetable or dairy fats, typically emulsified to achieve a smooth, spreadable consistency at ambient temperatures; industrial formulations specify fat content between 15% and 35% to balance mouthfeel with shelf stability. The product serves as a topping for bread and bakery applications, an ingredient in dessert manufacturing, and a standalone snack. Hazelnut Spread dominates value pools due to established consumer preference and premium pricing power, while Cocoa Spread extends into foodservice bulk applications where cost efficiency governs procurement. Almond Spread occupies the fastest-growing niche as allergen-aware households and specialty cafes diversify beyond traditional formulations.
EU regulators enforce maximum contaminant thresholds for ochratoxin A in cocoa-derived products through EFSA guidance, while FDA food-labeling rules in the United States mandate added-sugar disclosure that pressures reformulation timelines. India's FSSAI import clearance requirements for cocoa butter equivalents create non-tariff barriers for foreign manufacturers entering that market. Stakeholders must monitor evolving sugar-tax legislation across priority export markets and calibrate R&D pipelines toward clean-label emulsification systems before regulatory deadlines crystallize.
Market Dynamics
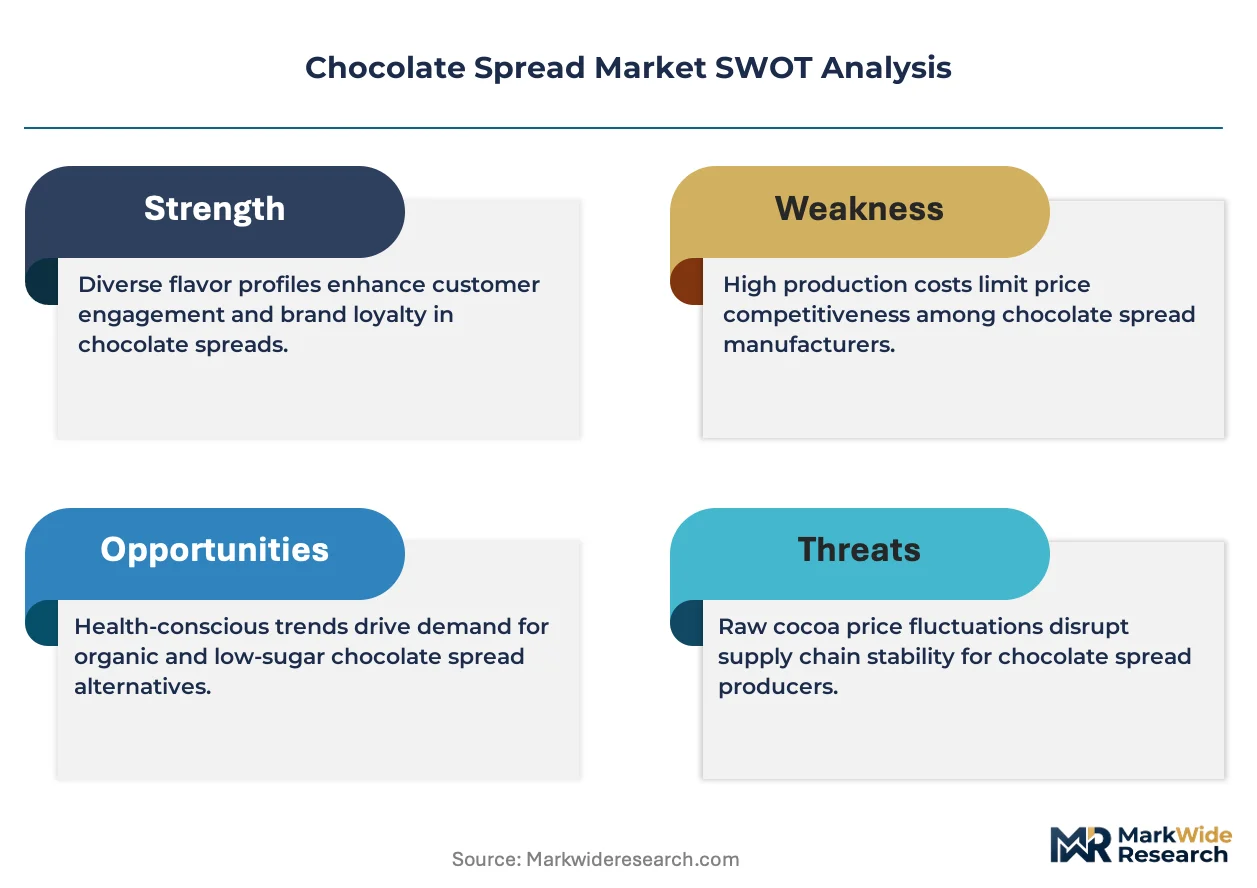
Clean-label reformulations and EU sugar-reduction mandates are compressing formulation margins while forcing R&D reinvestment across the chocolate spread value chain.
Growth Catalysts
- Breakfast convenience migration:European households are consolidating morning meal occasions into single-serve spread formats. German retail channels report shelf-space expansion for portion-controlled SKUs.
- EFSA contaminant thresholds:Stricter ochratoxin A limits in cocoa-derived products are accelerating supplier consolidation toward certified orchards. Turkish hazelnut processors with in-house testing capabilities capture preferential sourcing contracts.
- Plant-based fat emulsification:Novel enzymatic interesterification processes enable palm oil reduction without texture degradation. Specialty ingredient houses in the Netherlands commercialize clean-label alternatives at industrial scale.
Market Restraints
- Cocoa butter equivalent import barriers:India's FSSAI clearance requirements create 90-120 day entry delays for foreign manufacturers. Domestic compounders exploit regulatory friction to defend local market position.
- Hazelnut supply concentration:Turkish orchards supply 70% of global kernel volume. Climate volatility in the Black Sea region transmits price shocks directly to finished goods margins.
- Sugar taxation proliferation:France, the United Kingdom, and South Africa maintain tiered levies on added-sugar products. Reformulation costs for multinational portfolios strain regional P&L flexibility.
Strategic Opportunities
- Almond spread white space:Allergen-aware households in California and Pacific Northwest metro areas demonstrate willingness to pay 40% premiums for alternative nut bases. Specialty cafe channels in Portland and Seattle anchor initial distribution.
- EU Green Deal procurement incentives:Public sector foodservice tenders now weight carbon footprint in award criteria. Manufacturers with verified deforestation-free cocoa supply chains access institutional volume previously captured by conventional suppliers.
- Direct-to-pantry subscription models:Recurring delivery platforms bypass traditional retail slotting fees. French and Italian consumers show highest adoption for premium hazelnut tier products.
Industry Challenges
- Clean-label emulsifier sourcing:Lecithin replacement with sunflower or rapeseed derivatives requires reformulation expertise scarce in legacy technical teams. Recruitment competition intensifies with plant-based dairy adjacent sectors.
- Dual certification timelines:Organic plus Rainforest Alliance layering extends new product development cycles by 8-14 months. Smaller regional brands lack capital reserves to absorb parallel compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Spread Market |
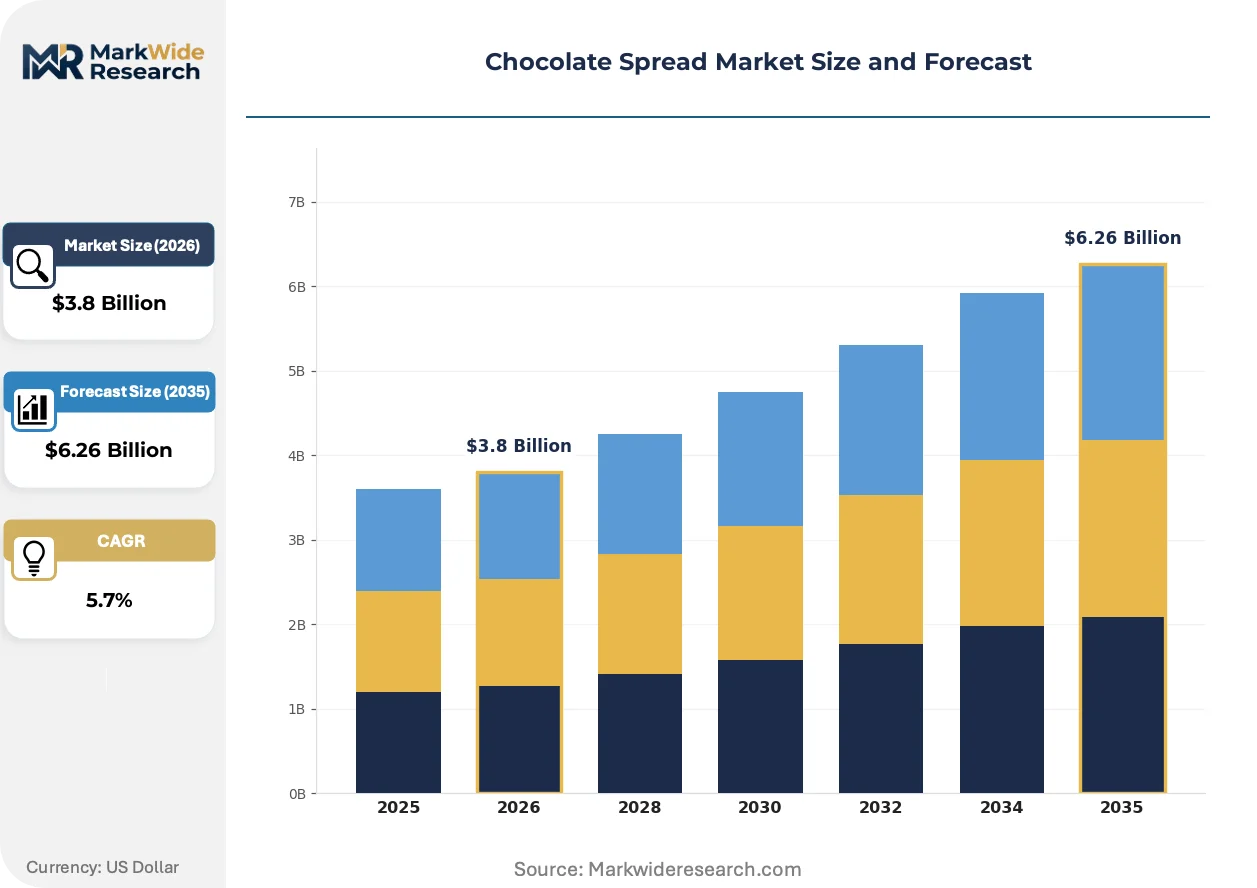
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hazelnut Spread, Cocoa Spread, Almond Spread, Fruit Spread Form: Jar, Squeeze Tube, Pouch, Bulk End User: Households, Cafes, Bakeries, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Unilever PLC, Nestle, Ferrero Group, Hero Group GmbH, Barry Callebaut, J.M. Smucker Co., Hershey Co., Zentis GmbH & Co. KG, Andros SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Spread Market Emerging Trajectories
Formulation transparency and procurement digitization are redrawing competitive boundaries between artisanal positioning and mass-market efficiency.
Enzymatic interesterification is fragmenting the traditional fat-processing hierarchy. Mid-sized European manufacturers adopt batch enzymatic systems to produce palm-free spreads without capital-intensive hydrogenation infrastructure. This technology is fragmenting supplier power previously concentrated among tropical oil majors and enabling regional dairies to enter chocolate spread co-manufacturing.
EFSA's evolving guidance on acrylamide and process contaminants is tightening thermal processing specifications. Roasting temperature protocols for hazelnuts now require real-time monitoring systems to demonstrate compliance. Premium tier producers in Italy and Germany invest most aggressively in infrared sorting and low-temperature roasting lines to maintain positioning.
Foodservice procurement is consolidating toward specification-managed contracts with verified provenance documentation. Hotel and cafe chains in France now require batch-level traceability for cocoa and hazelnut inputs. This behavior compresses spot-market participation by industrial manufacturers and rewards vertically integrated suppliers with captive orchard assets.
Chocolate Spread Market Segmentation
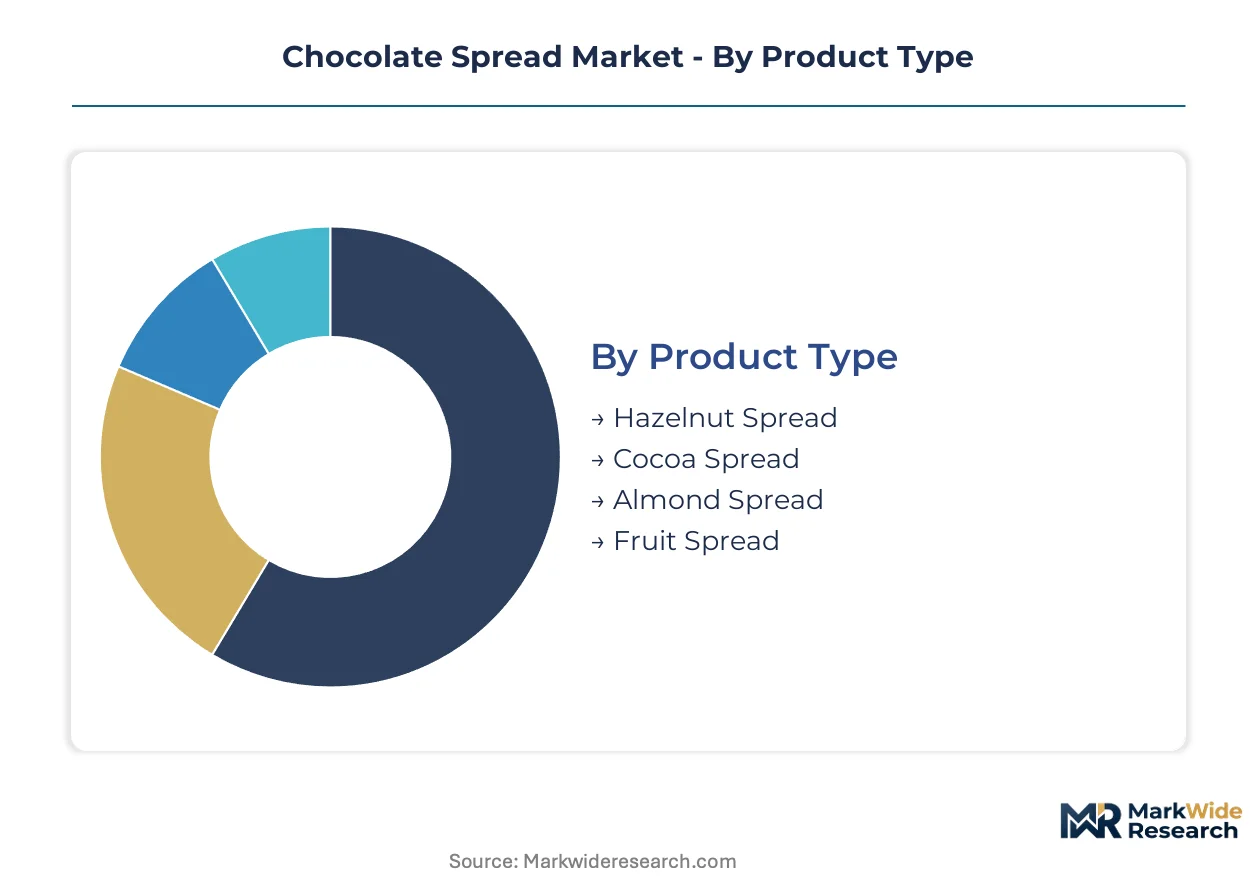
Product configuration in chocolate spread markets dictates margin capture through ingredient tiering and packaging format selection. Manufacturers optimize portfolio mix across premium nut content, convenience-oriented delivery, and institutional volume channels to align with diverging consumer willingness-to-pay.
Product Type:
Highest margin pools concentrate in nut-inclusive formulations where ingredient provenance commands premium positioning, while cocoa-dominant variants serve cost-sensitive volume applications.
- Hazelnut Spread:Contains 13% or higher hazelnut paste content emulsified with cocoa solids and vegetable fats, achieving fat content between 25% and 35% for spreadable viscosity at ambient temperatures. German and Italian households sustain demand concentration for premium tiers with single-origin Turkish hazelnut claims, though EFSA ochratoxin A thresholds now require certified orchard documentation that elevates procurement costs.
- Cocoa Spread:Formulations with cocoa mass or powder as the primary flavoring agent, typically incorporating palm oil or cocoa butter equivalents to achieve 15% to 25% fat content for industrial baking compatibility. Food manufacturers in France and Belgium anchor procurement volumes for dessert ingredient applications, with India's FSSAI import barriers creating protected market conditions for domestic compounders.
- Almond Spread:Alternative nut base formulations targeting allergen-aware households in California and Pacific Northwest metro areas, commanding 40% price premiums over conventional hazelnut variants.
- Fruit Spread:Cocoa-fruit hybrid formulations incorporating berry or citrus concentrates, occupying niche positioning in specialty cafe channels.
The dominant share belongs to Hazelnut Spread, while Almond Spread is gaining share fastest among allergen-conscious consumer segments.
Form:
Packaging cost structures and consumption occasion targeting determine profitability, with single-serve formats capturing disproportionate margin per gram despite lower absolute volume.
- Jar:Standard glass or PET container formats ranging from 200g to 750g, optimized for pantry storage and multi-use household consumption. German retail channels report sustained shelf-space dominance, though portion-control trends are compressing growth in family-size SKUs.
- Squeeze Tube:Flexible laminated packaging with dispensing closure, enabling controlled portion delivery and reduced contamination risk for on-the-go consumption. French and Italian consumers show highest adoption for premium hazelnut tier products through direct-to-pantry subscription platforms.
- Pouch:Lightweight flexible packaging for single-serve or travel-size applications, gaining traction in airline and hospitality amenity programs.
- Bulk:Industrial pails or drums from 5kg to 25kg for foodservice and manufacturing procurement, governed by specification-managed contracts with verified provenance documentation requirements.
Jar formats retain volume leadership, though Squeeze Tube configurations are expanding most quickly through convenience-oriented retail channels.
End User:
Demand fragmentation across consumption contexts creates distinct specification requirements, from clean-label household preferences to cost-engineered manufacturing inputs.
- Households:Individual consumers purchasing for breakfast and snacking applications, driving clean-label reformulation priorities and reduced-sugar product development under EU regulatory pressure.
- Cafes:Independent and chain coffee shops requiring portion-controlled formats for pastry accompaniment, with Portland and Seattle specialty channels anchoring initial almond spread distribution.
- Bakeries:Artisanal and industrial producers incorporating spreads as dessert ingredients or fillings, demanding consistent viscosity specifications for automated processing lines.
- Food Manufacturers:Industrial-scale dessert and confectionery producers procuring bulk volumes, where carbon footprint verification under EU Green Deal procurement incentives increasingly influences supplier selection.
Households command the largest addressable base, while Food Manufacturers are climbing the fastest as sustainability-linked procurement criteria reshape institutional sourcing.
Distribution Channel:
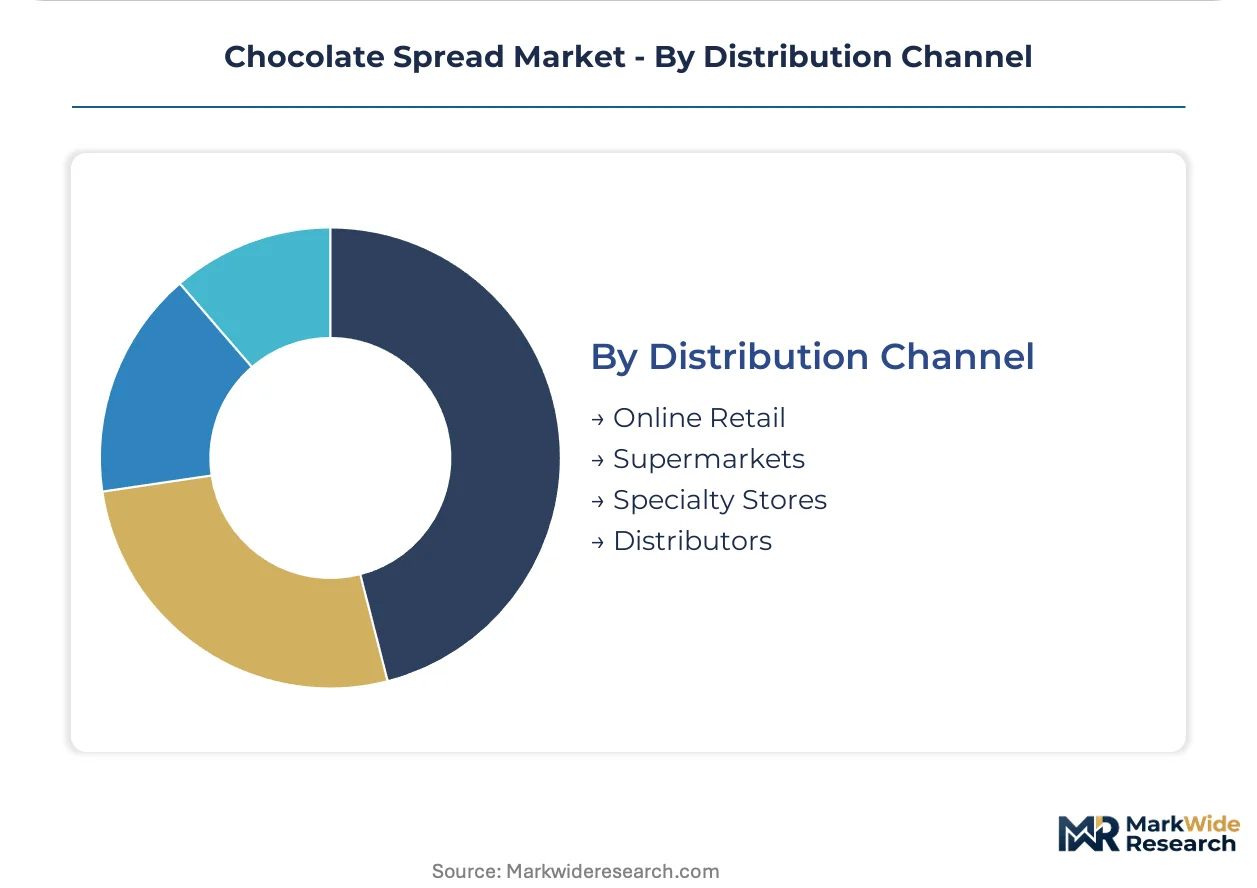
Channel selection determines margin retention through slotting fee avoidance and direct consumer relationship building, with digital platforms fragmenting traditional retail concentration.
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription models and bypass of traditional retail slotting fees, with French and Italian consumers showing highest premium product adoption.
- Supermarkets:Mass-market retail chains dominating volume distribution, where co-manufacturing partnerships with regional dairies sustain shelf presence for multinational portfolios.
- Specialty Stores:Gourmet food retailers and organic-focused independents, curating premium and alternative-nut formulations for discerning household segments.
- Distributors:Foodservice and industrial supply intermediaries managing bulk logistics and specification compliance for manufacturing and hospitality procurement.
Supermarkets maintain volume supremacy, though Online Retail is advancing most rapidly as recurring delivery platforms capture premium household segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkish orchards supply roughly seventy percent of global hazelnut kernel volume, concentrating procurement risk in the Black Sea region and transmitting climate volatility directly to finished goods margins across downstream markets.
Germany
Breakfast convenience migration drives shelf-space expansion for portion-controlled SKUs in German retail channels. EFSA ochratoxin A thresholds force certified orchard documentation that elevates procurement costs for manufacturers. The Cologne-Düsseldorf corridor anchors premium hazelnut tier distribution through direct-to-pantry subscription platforms.
Italy
Premium tier producers invest most aggressively in infrared sorting and low-temperature roasting lines to maintain positioning. EU Green Deal procurement incentives now weight carbon footprint in public sector foodservice tenders. Piedmont-based manufacturers leverage verified deforestation-free cocoa supply chains to access institutional volume.
France
Tiered sugar levies on added-sugar products strain regional P&L flexibility for multinational portfolios. EFSA guidance on acrylamide tightens thermal processing specifications for hazelnut roasting protocols. Parisian hotel and cafe chains now require batch-level traceability for cocoa and hazelnut inputs.
United States
FDA food-labeling rules mandate added-sugar disclosure that pressures reformulation timelines across North American portfolios. Allergen-aware households in California demonstrate willingness to pay forty percent premiums for alternative nut bases. Portland and Seattle specialty cafe channels anchor initial almond spread distribution.
India
FSSAI import clearance requirements for cocoa butter equivalents create ninety-to-one-hundred-twenty day entry delays for foreign manufacturers. Domestic compounders exploit regulatory friction to defend local market position. Mumbai-based industrial dessert producers procure bulk cocoa-dominant spreads for cost-sensitive manufacturing applications.
Chocolate Spread Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the chocolate spread value chain. Vertically integrated orchard owners command premium tier positioning through captive hazelnut supply, while co-manufacturing specialists compete on volume flexibility for private-label accounts. Three archetypes dominate: integrated nut processors with in-house testing capabilities, multinational confectionery houses leveraging dairy partnerships, and regional compounders shielded by import barriers. Consolidation pressures concentrate around certified orchard assets and clean-label emulsification expertise.
Within the integrated processor tier, Ferrero Group and Zentis GmbH & Co. KG exemplify upstream control strategies that sustain margin capture at scale. Among diversified confectionery houses, Nestle and Hershey Co. occupy positions anchored by co-manufacturing networks and cocoa sourcing transparency programs respectively. Barry Callebaut represents the specialist archetype focused on industrial ingredient supply.
| Leading Market Players |
|---|
| Unilever PLC |
| Nestle |
| Ferrero Group |
| Hero Group GmbH |
| Barry Callebaut |
| J.M. Smucker Co. |
| Hershey Co. |
| Zentis GmbH & Co. KG |
| Andros SAS |
| Others |
Supply Flow & Price Mechanics
EFSA ochratoxin A thresholds gate both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb certified orchard premiums or forfeit premium tier positioning while mass-market variants compete on cocoa butter equivalent sourcing efficiency.
Pricing Analysis
EU sugar-reduction mandates dictate the pricing tier structure across the chocolate spread market. Three-tier pricing structure across premium, standard, and economy levels separates single-origin Turkish hazelnut formulations from blended nut bases and cocoa-dominant spreads. Cost compression in the premium tier is intensifying because EFSA contaminant documentation requirements elevate procurement overhead. Private-label buyers in German supermarkets exhibit highest price sensitivity, while direct-to-pantry subscribers in France and Italy show lowest elasticity.
Supply Chain Analysis
Black Sea basin harvest volatility underwrites systemic margin risk across downstream markets. Turkish orchards, Italian processing facilities, and Dutch specialty ingredient houses anchor global supply. The value chain draws from hazelnut kernels, cocoa mass, and enzymatically interesterified vegetable fats. Single-source vulnerability concentrates in Turkish kernel supply exposed to climate shocks. Distribution runs through co-manufacturing partnerships with regional dairies, direct-to-pantry platforms, and foodservice specification contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from plant-based fat spreads and clean-label nut butter alternatives that capture allergen-aware and health-conscious household migration.
For Market Incumbents: Shield premium positioning by securing captive hazelnut supply through backward integration into certified Turkish orchards before competitor consolidation accelerates. Invest in enzymatic interesterification capabilities to neutralize palm oil reformulation threats from adjacent plant-based dairy sectors.
For New Entrants and Emerging Players: Anchor in Pacific Northwest specialty cafe channels where almond spread white space commands forty percent premiums and distribution relationships remain unclaimed by established hazelnut-dominant portfolios. Pursue Rainforest Alliance certification as a go-to-market wedge against legacy players with longer compliance timelines.
For Investors and Strategic Acquirers: EU Green Deal procurement incentives reshape the acquisition landscape toward vertically integrated suppliers with verified deforestation-free cocoa documentation and carbon footprint verification capabilities. Target mid-sized Italian and German manufacturers with infrared sorting infrastructure and existing public sector foodservice relationships. Watch FSSAI regulatory harmonization discussions as the signal for Indian market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Emulsification Investment | Novel enzymatic processes enable palm oil reduction without texture degradation, satisfying EFSA guidance. |
| Certified Orchard Backward Integration | Captive Turkish hazelnut supply secures preferential sourcing contracts and ochratoxin A compliance documentation. |
| Direct-to-Pantry Subscription Launch | Recurring delivery platforms bypass supermarket slotting fees and capture premium household segments in France and Italy. |
| Dual Certification Acceleration | Organic plus Rainforest Alliance layering extends product development cycles but unlocks EU Green Deal procurement volume. |
| Almond Spread White-Space Entry | Alternative nut base formulations target allergen-aware households in California and Pacific Northwest metro areas. |
Methodological Framework
Operator-level perspectives from brand managers, category buyers at European retailers, supply planners at hazelnut processors, and channel sales heads anchored the qualitative base. Primary interview insights combined with secondary validation from customs records, Nielsen retail audit data, EFSA guidance documents, and FSSAI regulatory filings. Bottom-up demand modeling triangulated against top-down market sizing across the value chain.
Sensitivity analysis framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type tier, packaging format, end-use application, and distribution channel structure. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and procurement pattern shifts. Hazelnut price volatility indices and cocoa futures curves fed directly into margin scenario testing.
Decision-makers should treat outputs as directional under stable regulatory enforcement and climate-normal harvest assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EFSA contaminant guidance evolution and Turkish orchard yield variability unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low Calorie Hard Candy Market
Confectionery
India Industrial Chocolate Market
Confectionery
Gum Base Candy Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
United States Chocolate Market
Confectionery
Cookie Dough Market
Confectionery
Milk Chocolate Market
Confectionery
Coffee Gummy Market
Confectionery
Chocolate Confectionery Market
Confectionery
Africa Compound Chocolate Market
Confectionery
Global Confectionery Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
Sugar-Free Sweets Market
Confectionery
North America Chocolate Market
Confectionery
Non-Chocolate Candy Market
Confectionery
Asia Pacific Sugar Confectionery Market