
 Asia-Pacific Prepared Mustard Market | 2026-2036
Asia-Pacific Prepared Mustard Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Prepared Mustard Market Insights
Precision fermentation for flavor modulation is reconfiguring how prepared mustard achieves consistent pungency profiles at industrial scale. Kewpie Corporation leverages its fermentation heritage to anchor premium positioning in Japan's retail condiment aisle. McCormick competes through R&D intensity, sustaining a pipeline of region-specific heat variants calibrated to local thresholds. Lee Kum Kee differentiates by extending its soy sauce distribution infrastructure into mustard placement across Chinese supermarket networks.
Prepared mustard denotes a condiment manufactured from ground Brassica juncea seeds combined with vinegar, water, salt, and stabilizers, then milled to particle sizes between 0.1 and 0.5 millimeters to control heat release and shelf stability. Yellow mustard dominates volume through its mild flavor profile and compatibility with mass-market fast-food applications. Dijon mustard captures premium margin pools in urban Australian and Japanese households, while whole grain formats are gaining traction in food service channels where texture visibility signals artisanal positioning.
FSSAI in India mandates nutritional disclosure and additive limits for packaged condiments, directly shaping reformulation investments by domestic manufacturers. Japan's Ministry of Health, Labour and Welfare enforces positive-list systems for food additives, creating compliance barriers for imported mustard variants. China's SAMR conducts periodic sampling inspections on condiment labeling accuracy, affecting market access timelines for foreign entrants. Stakeholders must monitor evolving additive approvals and front-of-pack labeling mandates across these three jurisdictions to anticipate reformulation costs and entry sequencing.
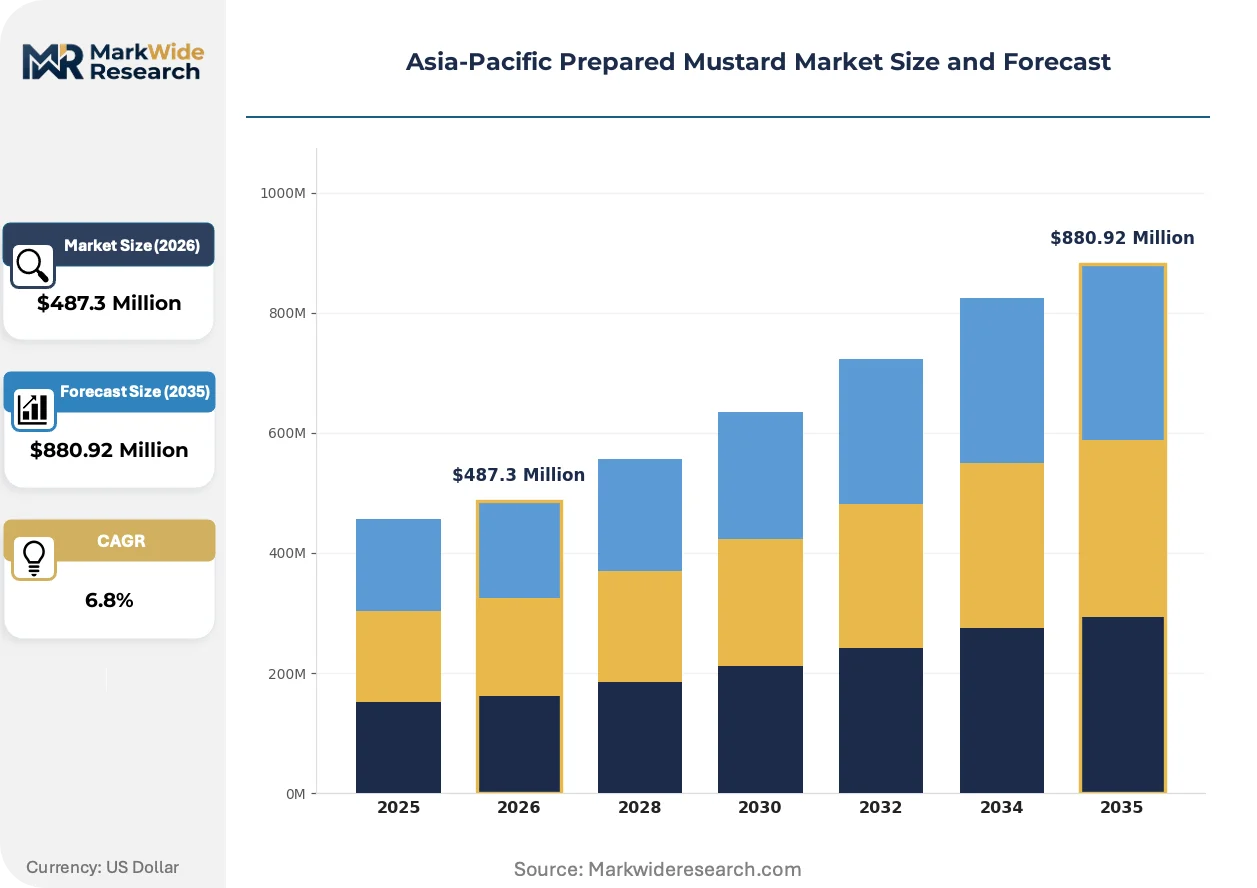
Market Dynamics
Precision fermentation for flavor modulation is reconfiguring how prepared mustard achieves consistent pungency profiles at industrial scale, compressing batch-to-batch variation and enabling cleaner-label positioning across Southeast Asian manufacturing.
Growth Catalysts
- Quick-service restaurant expansion:Southeast Asian fast-food chains are diversifying condiment procurement as consumer palates evolve toward Western-style flavor profiles.
- FSSAI labeling reform:India's tightened disclosure mandates for packaged sauces are accelerating reformulation investments toward additive-free ingredient decks.
- Urban dining penetration:Metropolitan India and China's deepening Western-style restaurant density is creating concentrated demand clusters for prepared mustard formats.
Market Restraints
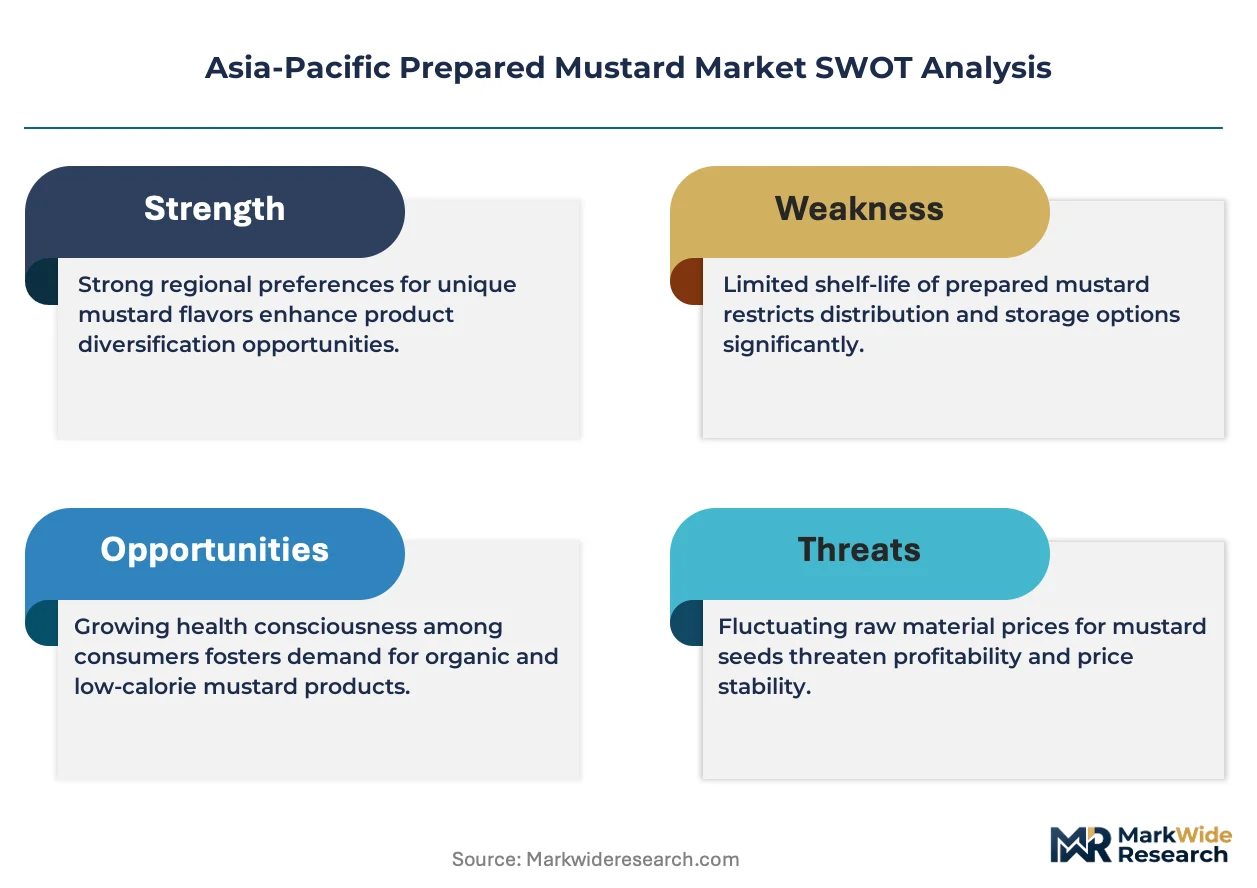
- Brassica juncea seed price volatility:Input cost fluctuations for mustard seed concentrate margins for processors lacking backward integration into seed sourcing.
- Import dependency for specialty equipment:Milling machinery for precise particle size control concentrates supply with German and Italian equipment manufacturers.
- Japan's positive-list additive barriers:The Ministry of Health, Labour and Welfare's restricted substance approvals create compliance friction for foreign mustard variants entering retail.
Strategic Opportunities
- Vietnamese food service white space:Underpenetrated quick-service channels in Ho Chi Minh City and Hanoi offer first-mover positioning for Dijon and whole-grain formats.
- Clean-label convergence:Marrying precision fermentation with reduced-sodium formulations addresses dual demand signals in Australian and Japanese premium retail.
- E-commerce condiment verticals:Direct-to-pantry subscription models are bypassing traditional supermarket slotting fees for artisanal mustard entrants.
Industry Challenges
- Fermentation technician scarcity:Industrial-scale flavor modulation requires specialized microbiology expertise that outpaces regional vocational training output.
- Dual certification timelines:Simultaneous FSSAI, SAMR, and Ministry of Health, Labour and Welfare approvals extend market entry cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Prepared Mustard Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yellow Mustard, Dijon Mustard, Honey Mustard, Whole Grain Mustard Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Packaging Type: Glass Jars, Plastic Bottles, Pouches, Tubs End User: Households, Food Service, Food Processing, Catering |
| Companies Covered | Kewpie Corporation, Unilever, MTR Foods, McCormick, Kraft Heinz, Kissan, Dabur, Colman’s Mustard, Lee Kum Kee, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Prepared Mustard Market Trends and Innovations
Active fermentation control and regulatory disclosure mandates are compressing traditional mustard manufacturing timelines while fragmenting procurement pathways across Asia-Pacific food service and retail channels.
Precision fermentation systems that modulate myrosinase enzyme activity are rendering obsolete conventional heat-blanching methods for pungency stabilization. Japanese and Australian premium manufacturers are adopting these bioreactor platforms at pilot scale. The technology is rendering obsolete fixed-formulation approaches by enabling real-time flavor profile adjustment to regional heat thresholds.
China's SAMR periodic sampling inspections on condiment labeling accuracy are forcing foreign entrants to pre-validate Chinese-language nutritional panels before shipment. Domestic manufacturers face accelerated compliance audits. The policy most affects imported Dijon and specialty whole-grain variants, which are responding by establishing in-country labeling verification partnerships.
Quick-service chains are consolidating condiment procurement through centralized commissary agreements rather than restaurant-level purchasing. This procurement compression is squeezing regional distributors and favoring manufacturers with direct food-service logistics capabilities. The shift is most visible in metropolitan China, where Yum China and domestic burger chains are standardizing mustard specifications across provincial footprints.
Asia-Pacific Prepared Mustard Market Segmentation
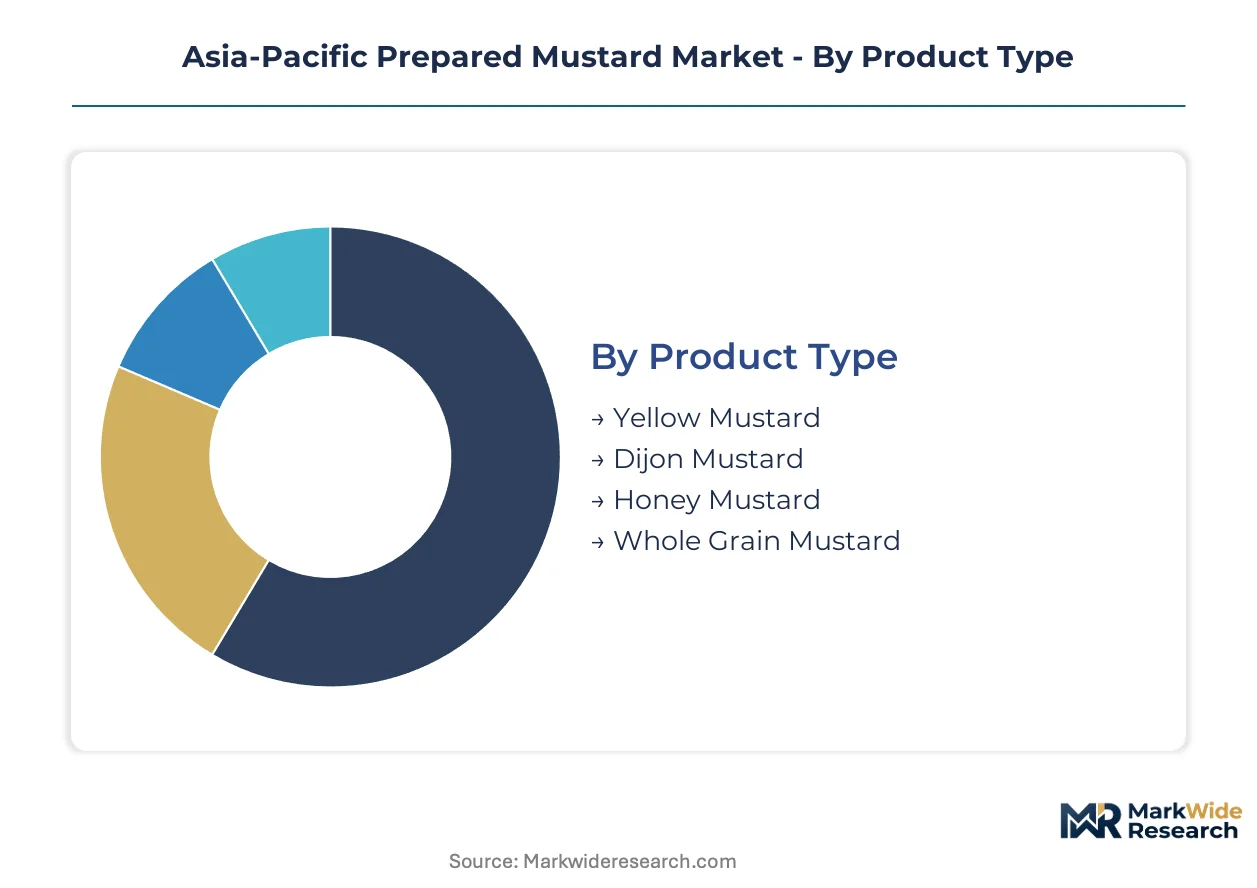
Prepared mustard formats fragment across four commercial dimensions, each governing distinct margin structures and procurement pathways. Product type determines formulation complexity and pungency calibration, while distribution channels and packaging formats shape shelf positioning and logistics economics across urban India, metropolitan China, and Australian retail corridors.
Product Type:
Mature formats anchor volume throughput while emerging variants capture premium margin expansion in food service and retail.
- Yellow Mustard:Ground Brassica juncea seeds milled to 0.1-0.3 millimeter particle size with turmeric-derived coloration deliver mild, mass-market heat profiles. Quick-service restaurants across Southeast Asia standardize procurement of this format for burger and hot dog applications, compressing supplier margins through centralized commissary contracts.
- Dijon Mustard:Wine vinegar-based emulsions with finer particle distribution (below 0.1 millimeters) achieve smooth, sharp pungency calibrated to Japanese and Australian premium household thresholds. Metropolitan Sydney and Tokyo retail channels report concentrated placement in Western-style condiment aisles alongside imported specialty sauces.
- Honey Mustard:Sweetened formulations blending invert sugar syrups with base mustard emulsions target children's palates and salad dressing applications in Australian supermarkets.
- Whole Grain Mustard:Intact seed fractions suspended in vinegar brine provide visible texture cues signaling artisanal positioning in Ho Chi Minh City and Hanoi food service channels.
Yellow mustard handles the majority of throughput; whole grain mustard is expanding most quickly on share in Southeast Asian food service.
Distribution Channel:
Channel economics stratify by inventory velocity, slotting fee structures, and direct-to-pantry bypass potential.
- Supermarkets:Multi-brand condiment aisles in Indian metros and Chinese tier-1 cities concentrate volume throughput, with FSSAI and SAMR labeling compliance costs amortized across high-velocity SKUs.
- Convenience Stores:Grab-and-go formats favor single-serve sachets and small-format plastic bottles in Japanese urban corridors where 7-Eleven and Lawson networks dominate impulse condiment purchases.
- Online Retail:Direct-to-pantry subscription models bypass traditional slotting fees, enabling artisanal mustard entrants to reach Australian and Japanese premium households without supermarket distribution infrastructure.
- Specialty Stores:Curated import assortments in Delhi and Mumbai gourmet retailers stock Dijon and whole-grain variants targeting expatriate and affluent local consumers.
Supermarkets retain the dominant throughput position; online retail is climbing the fastest as logistics networks mature.
Packaging Type:
Material selection trades shelf appeal, transport economics, and regulatory compliance across glass, plastic, and flexible formats.
- Glass Jars:Premium positioning in Japanese and Australian retail leverages inert barrier properties and visual clarity for whole-grain and Dijon variants where texture visibility drives purchase intent.
- Plastic Bottles:HDPE and PET formats dominate mass-market yellow mustard in Indian and Chinese supermarkets, reducing breakage rates and freight costs in high-volume distribution.
- Pouches:Flexible laminate structures enable single-serve food service portions and travel-size retail formats across Southeast Asian convenience channels.
- Tubs:Wide-mouth polypropylene containers target food processing and catering bulk procurement in metropolitan China where portion-control efficiency outweighs shelf aesthetics.
Plastic bottles move the highest unit volumes; pouches are gaining share fastest in food service and travel retail.
End User:
User segments diverge sharply in specification stringency, volume scale, and price elasticity across household and institutional procurement.
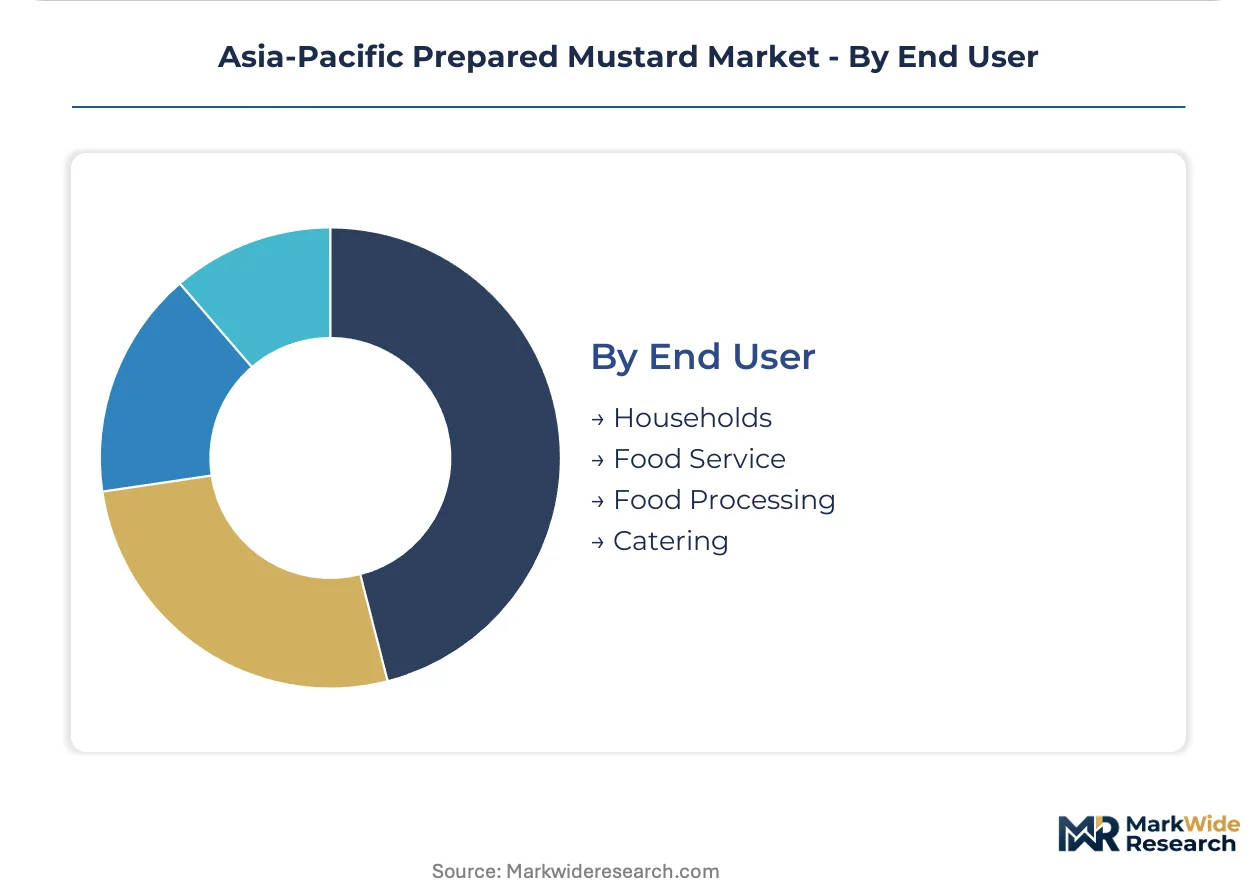
- Households:Retail-purchased formats in 150-400 gram pack sizes drive recurring replenishment cycles in urban Indian and Chinese households adopting Western-style home cooking.
- Food Service:Quick-service chains and independent restaurants specify consistent pungency profiles and pump-dispense compatibility, with Yum China and domestic burger chains standardizing mustard specifications across provincial footprints.
- Food Processing:Industrial mustard paste inputs for sauce, dressing, and ready-meal manufacturing require batch-to-batch consistency and documented myrosinase activity levels.
- Catering:Event and institutional food providers in Australian corporate and wedding segments procure bulk formats with portion-control dispensing systems.
Households generate the largest absolute demand base; food service is expanding fastest as quick-service chains consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant chains and premium retail households concentrate demand across metropolitan clusters in India, China, Japan, Australia, and Vietnam. Each market presents distinct regulatory hurdles and procurement pathways that shape entry sequencing for mustard manufacturers.
India
Urban households in Delhi, Mumbai, and Bangalore drive recurring replenishment of yellow mustard formats as Western-style home cooking penetrates middle-class kitchens. FSSAI mandates nutritional disclosure and additive limits for packaged condiments, forcing domestic reformulation toward cleaner ingredient decks. Quick-service chains in the National Capital Region consolidate procurement through centralized commissary agreements, compressing margins for regional distributors.
China
Metropolitan food service in Shanghai, Beijing, and Guangzhou generates concentrated demand as Yum China and domestic burger chains standardize mustard specifications across provincial footprints. SAMR conducts periodic sampling inspections on condiment labeling accuracy, extending market access timelines for foreign entrants lacking in-country verification partnerships. Yangtze River Delta manufacturing clusters host industrial mustard paste production for sauce and ready-meal processing.
Japan
Premium households in Tokyo and Osaka sustain Dijon mustard placement alongside imported specialty sauces in curated retail aisles. The Ministry of Health, Labour and Welfare enforces positive-list systems for food additives, creating compliance barriers for imported variants without pre-approved stabilizer portfolios. Kewpie Corporation anchors domestic fermentation expertise in Kanto-region production facilities.
Australia
Metropolitan Sydney and Melbourne retail channels report concentrated placement of whole-grain and Dijon formats targeting affluent households and expatriate consumers. TGA-aligned state food safety frameworks govern additive approvals and nutritional panel standards for imported condiments. Direct-to-pantry subscription models bypass traditional supermarket slotting fees for artisanal entrants.
Vietnam
Ho Chi Minh City and Hanoi food service channels present underpenetrated white space for Dijon and whole-grain formats as quick-service chains expand condiment procurement. General food safety administration at provincial level shapes import documentation requirements without centralized positive-list barriers. Independent restaurants in southern commercial districts drive visible-texture mustard adoption as artisanal positioning signals.
Asia-Pacific Prepared Mustard Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement pathways that diverge by scale and specification stringency. The vendor base stratifies into fermentation-heritage specialists, diversified condiment conglomerates, and regional sauce houses with distribution infrastructure advantages. Strategic archetypes include precision-fermentation premium-positioned manufacturers, commodity-scale yellow mustard processors, and soy-sauce-leveraged Asian market incumbents. Dominant competitive moves encompass backward integration into Brassica juncea seed sourcing and direct food-service logistics capability buildout.
Among fermentation-heritage specialists, Kewpie Corporation exemplifies premium positioning anchored in Japanese bioreactor expertise. Diversified conglomerates with condiment portfolios include Unilever and McCormick, occupying positions that span mass-market and specialty retail tiers. Regional sauce houses leveraging existing distribution infrastructure include Lee Kum Kee, which represents the archetype of extending soy sauce networks into adjacent condiment placement.
| Leading Market Players |
|---|
| Kewpie Corporation |
| Unilever |
| MTR Foods |
| McCormick |
| Kraft Heinz |
| Kissan |
| Dabur |
| Colman's Mustard |
| Lee Kum Kee |
| Others |
Pricing and Supply Chain Analysis
Brassica juncea seed procurement concentrates in Rajasthan and Madhya Pradesh, anchoring margin pools for processors with backward integration into Indian agricultural networks while exposing spot-market buyers to harvest-season price spikes.
Pricing Analysis
Cost-plus contracts with Brassica juncea seed indexation dominate procurement agreements between Indian crushers and condiment manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates Dijon formulations with wine vinegar base from mass-market yellow mustard and food-service bulk tubs. Pricing pressure stems from FSSAI-mandated reformulation costs pushing mid-tier producers toward additive-free ingredient decks. Quick-service chains exhibit highest price sensitivity through centralized commissary bidding, while Japanese premium households show lowest sensitivity to Dijon and whole-grain positioning.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier financing arrangements for Southeast Asian food-service distributors managing quick-service chain accounts. Seed sourcing draws from India, Canada, and Ukraine, with milling equipment dependency resting on German and Italian precision machinery manufacturers. Single-source vulnerability concentrates in myrosinase-active seed varieties required for pungency calibration. Distribution runs through commissary consolidation in metropolitan China and supermarket slotting-fee structures across Indian urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platforms are reconfiguring prepared mustard manufacturing into an ecosystem-economy inflection, where bioreactor interoperability and enzyme-activity data exchange create network effects among ingredient suppliers, equipment vendors, and finished goods manufacturers.
For Market Incumbents: Entrench fermentation-heritage positioning by expanding Kanto-region bioreactor capacity and securing exclusive myrosinase-active seed varietal contracts with Rajasthan agricultural cooperatives. Defend against precision-fermentation specialists by pre-empting clean-label certification pipelines through FSSAI and Ministry of Health, Labour and Welfare joint submissions.
For New Entrants and Emerging Players: Establish a beachhead in Vietnamese food-service channels by introducing whole-grain formats with visible texture cues for Ho Chi Minh City independent restaurants. Bypass supermarket slotting fees through direct-to-pantry subscription models targeting Australian premium households, leveraging e-commerce logistics partnerships rather than retail distribution infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional sauce houses lacking fermentation capabilities but holding soy sauce distribution infrastructure across Chinese supermarket networks. Five-to-ten year viability hinges on clean-label transition completion; watch for FSSAI additive-ban expansion as inflection signal triggering consolidation premiums for pre-compliant manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Bioreactor deployment at industrial throughput compresses batch-to-batch pungency variation for mass-market consistency. |
| Backward Integration into Seed Sourcing | Captive Brassica juncea supply from Rajasthan agricultural networks insulates margin from harvest-price volatility. |
| Clean-Label Certification Pipeline | Pre-validated FSSAI and Ministry of Health, Labour and Welfare submissions accelerate market access timelines. |
| Direct Food-Service Logistics Buildout | Commissary-direct distribution bypasses regional distributor compression from Yum China procurement consolidation. |
| E-Commerce Subscription Launch | Direct-to-pantry models circumvent Australian supermarket slotting fees for artisanal mustard entrants. |
Research Methodology
A spread of perspectives from fermentation R&D directors, quick-service chain procurement heads, FSSAI regulatory affairs specialists, and Brassica juncea seed crushers converged on the working assumptions underlying demand projections. Primary interview intelligence combined with secondary validation from customs trade records, SAMR labeling inspection disclosures, and Ministry of Health, Labour and Welfare additive approval registers. Bottom-up SKU-level demand modeling triangulated against top-down condiment category expenditure flows across Indian, Chinese, and Japanese retail audit data.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, distribution channel, packaging format, and end-user procurement archetype. CAGRs derived from trend-line extrapolation of urban household penetration rates and quick-service restaurant expansion trajectories, cross-referenced against myrosinase enzyme activity standardization timelines and precision fermentation pilot-scale adoption curves.
Stress conditions across seed price volatility bands, FSSAI enforcement intensity scenarios, and fermentation technician availability constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory trajectory and technology adoption; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Acacia Concinna Extracts Market
Spices and Condiments
Europe Dehydrated Onion Market
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Rosemary Extracts Market
Spices and Condiments
Frangipani Extract Market
Spices and Condiments
Culinary Powder Market
Spices and Condiments
Global Pickles and Pickle Products Market
Spices and Condiments
Garlic Extract Market
Spices and Condiments
Middle East and Africa Dehydrated Onion Market
Spices and Condiments
Paprika Market
Spices and Condiments
Gravy Mixes Market
Spices and Condiments
Gourmet Salts Market
Spices and Condiments
Middle East and Africa Vanilla Beans and Extract Market
Spices and Condiments
Fermented Mediterranean Pepper and Tomato Complexes Market
Spices and Condiments
Dehydrated Garlic Market