
 Plant-Based Shrimp Market | 2026-2036
Plant-Based Shrimp Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Shrimp Market Analytics
Consolidation among national food service distributors is realigning procurement priorities toward shelf-stable, high-volume plant-based seafood formats. Beyond Meat leverages its protein-extraction infrastructure to supply co-manufacturing partners. Gathered Foods Corp anchors its position through direct relationships with regional restaurant groups. New Wave Foods competes on coastal distribution density rather than national retail breadth.
Plant-based shrimp denotes a formulated seafood analog engineered from legume proteins, algal extracts, and binding hydrocolloids, typically processed through high-moisture extrusion to replicate the muscular texture of decapod crustaceans for commercial food preparation. The product type dimension shows seafood alternatives commanding the widest food service penetration while patties occupy a narrower but defensible retail niche. Distribution channel dynamics reveal online retail as the fastest-growing route despite supermarkets still capturing the majority of household purchases.
FDA allergen-labeling requirements and EU EFSA novel-food authorization pathways jointly elevate compliance costs for new entrants while validating safety claims for established suppliers. USDA organic certification and EU organic regulations create premium-tier segmentation that rewards clean-label formulations. Stakeholders must monitor evolving algal-protein sourcing standards and regional enforcement variance to anticipate which compliance investments will translate into sustained market access.
Market Dynamics
High-moisture extrusion technology is compressing texture-replication timelines while EU EFSA novel-food authorization and FDA allergen-labeling requirements jointly elevate capital barriers for new entrants.
Growth Catalysts
- EFSA Novel-Food Pathways:Established suppliers leverage completed safety dossiers to accelerate menu placements across European food service chains before competitors complete multi-year authorization cycles.
- Coastal Urban Clustering:United States metropolitan markets from San Francisco to Boston provide concentrated testing grounds for next-generation algal-protein formulations with immediate operator feedback loops.
- High-Moisture Extrusion:Equipment refinements now deliver muscular fiber alignment indistinguishable from decapod crustacean tissue, collapsing previous texture-performance gaps.
Market Restraints
- Algal-Protein Input Volatility:Fermentation-derived astaxanthin and omega-3 concentrates face supply concentration among North Atlantic bioreactor operators, exposing margins to batch-yield fluctuations.
- Clean-Label Certification Costs:USDA organic and EU organic regulations impose multi-year transition requirements on legume suppliers, restricting premium-tier volume scaling.
- Animal-Protein Price Anchoring:Wild-caught shrimp commodity pricing in Southeast Asian aquaculture markets sets psychological ceiling constraints on plant-based positioning.
Strategic Opportunities
- Online Retail Channel Expansion:Direct-to-consumer frozen distribution bypasses conventional retail slotting fees, enabling margin capture and rapid formulation iteration based on purchase-pattern data.
- IRA Clean-Energy Incentives:United States bioprocessing facility construction qualifies for tax credits that offset capital intensity of precision-fermentation infrastructure.
- Food Service Co-Manufacturing:Protein-extraction infrastructure sharing agreements allow regional restaurant groups to launch private-label analogs without captive production investment.
Industry Challenges
- High-Moisture Extrusion Technician Scarcity:Food science programs produce insufficient specialists trained in shear-cell physics and rheological optimization for seafood analogs.
- Cross-Contamination Protocol Complexity:Shellfish-allergen verification requires dedicated production lines and third-party laboratory testing that extends batch-release timelines.
- Patent Thicket Navigation:Overlapping intellectual property claims on binding hydrocolloid combinations and protein-extraction methods complicate freedom-to-operate assessments for new formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Shrimp Market |
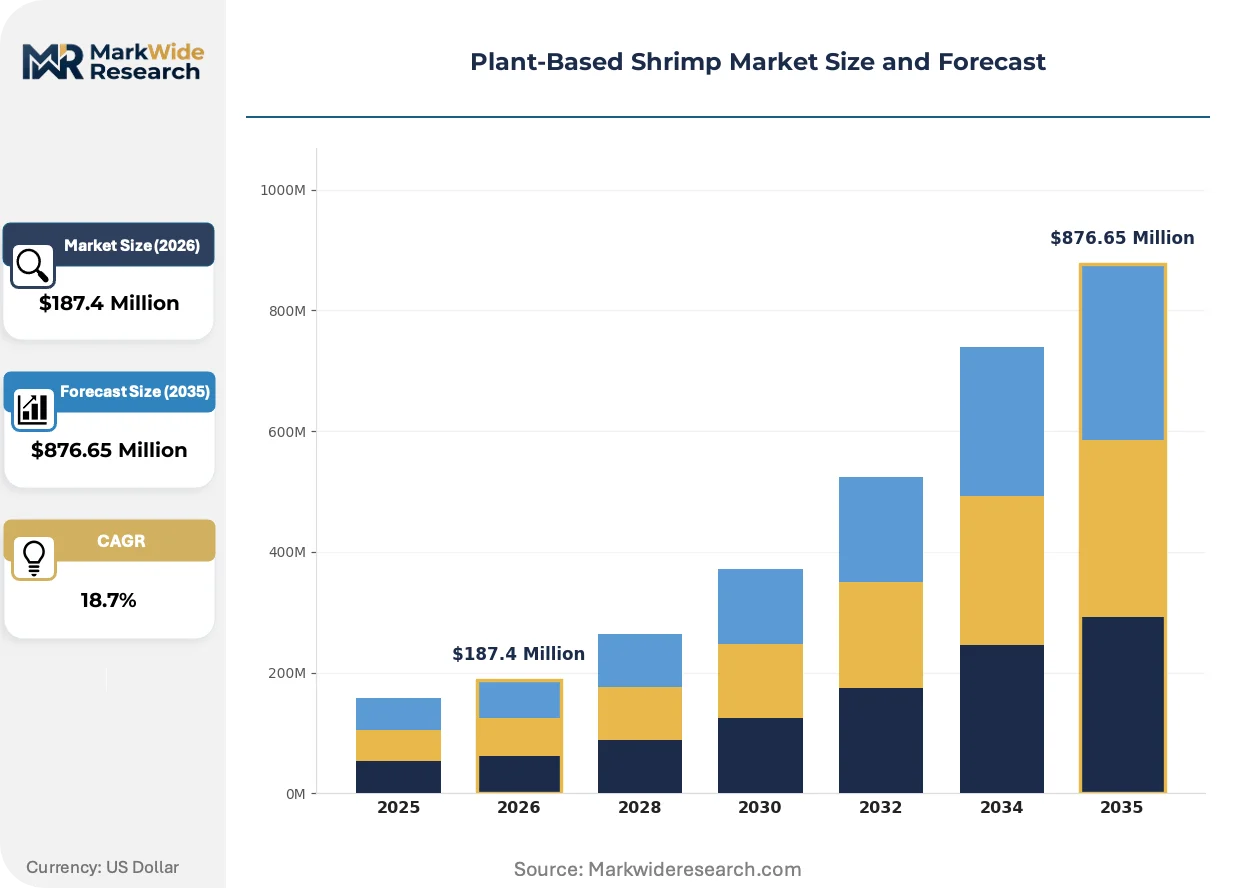
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patties, Tacos, Dishes, Seafood Alternatives End User: Restaurants, Food Services, Retail Consumers, Meal Kits Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Distributors Application: Cooking, Sushi, Salad, Appetizers |
| Companies Covered | Beyond Meat, Gathered Foods Corp, Maple Leaf Foods, New Wave Foods, Finless Foods, Ocean Hunger Foods, Thai Union, Nestlé, Impossible Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Shrimp Market Evolving Landscape
Texture-replication engineering and regulatory validation protocols are converging to redefine competitive moats, while procurement behavior shifts reward suppliers with demonstrated supply-chain transparency.
High-moisture extrusion systems equipped with real-time shear sensors are automating fiber-alignment adjustments during protein-protein interaction phases. Food service manufacturers in the United States are retrofitting existing meat-analog lines with shrimp-specific die configurations at accelerating pace. This automation is compressing pilot-to-production scale-up from eighteen months to under six, eroding first-mover texture advantages.
EU EFSA novel-food authorization timelines have stabilized following 2023 procedural clarifications, enabling predictable multi-year investment planning for algal-protein suppliers. Industrial consequence includes pre-submission consultation investments that favor capitalized incumbents over venture-stage entrants. European food service distributors now require completed EFSA dossiers as qualification criteria, shifting procurement screening burden upstream.
Direct-procurement relationships between regional restaurant groups and specialized co-manufacturers are displacing traditional broadline distributor intermediaries. This channel restructuring concentrates volume with suppliers offering formulation collaboration and transparent algal-protein sourcing documentation. Visibility is highest in United States coastal metropolitan markets where operator technical sophistication supports direct supplier engagement.
Plant-Based Shrimp Market Segmentation
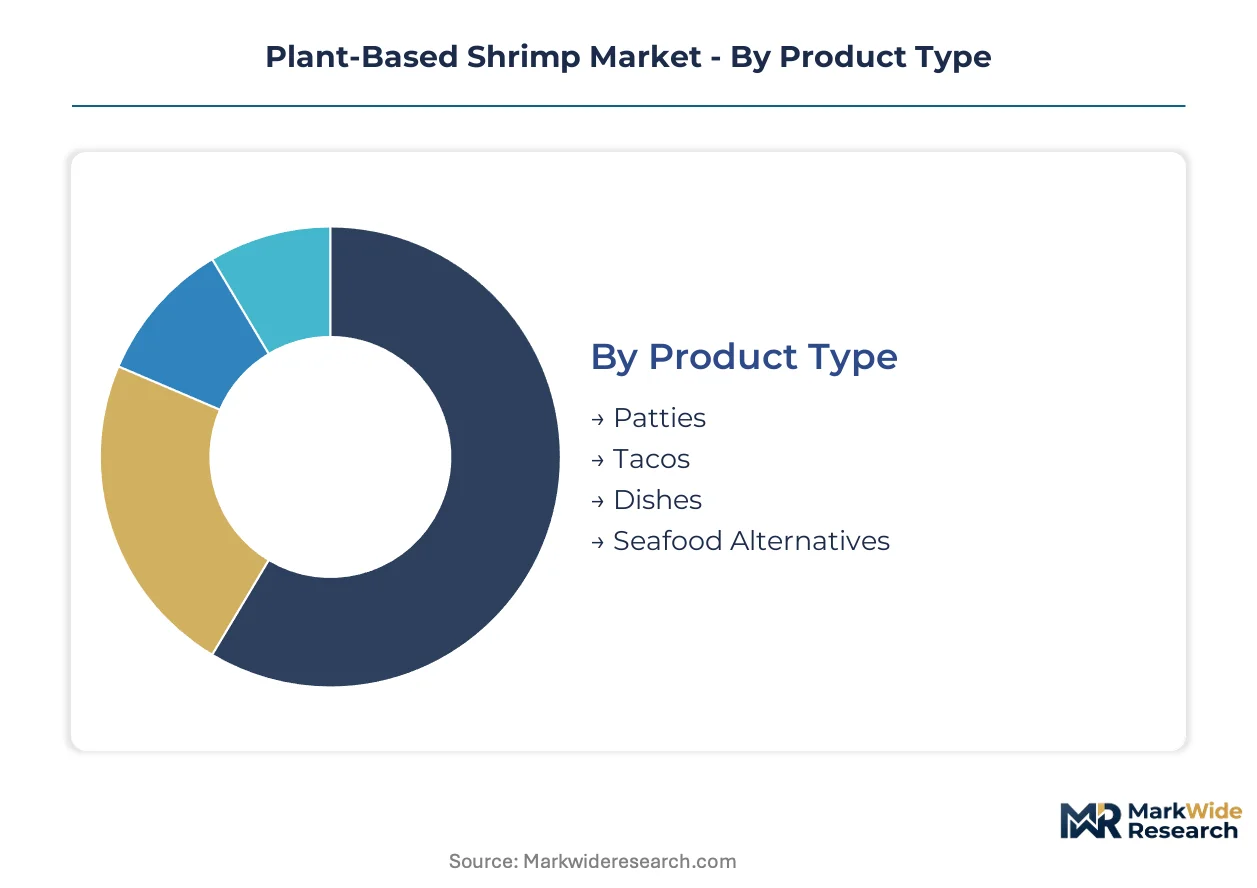
Plant-based shrimp segmentation reveals how formulation complexity and regulatory burden concentrate differently across product formats and buyer channels. Certification requirements from FDA allergen protocols to EU EFSA novel-food pathways create tiered entry barriers that reshape competitive positioning within each segment cluster.
Product Type:
FDA seafood-labeling exemptions and EU EFSA novel-food dossier requirements apply unevenly across formats, with whole-muscle analogs demanding more extensive safety validation than composite preparations.
- Seafood Alternatives:Whole-muscle formulations engineered through high-moisture extrusion replicate decapod texture for direct substitution in operator kitchens. United States coastal metropolitan food service chains concentrate procurement here, driven by immediate menu-integration potential and consumer allergen-concern mitigation.
- Dishes:Pre-formulated preparations incorporating binding hydrocolloids and algal extracts target ready-to-heat retail and meal-kit channels. Demand clusters in United States urban households seeking convenience without preparation complexity, constrained by frozen distribution infrastructure limitations.
- Patties:Compressed protein matrices with standardized dimensions suit QSR bun applications and retail freezer cases. Legume-protein suppliers with USDA organic certification capture premium-tier positioning.
- Tacos:Seasoned and pre-portioned formats align with fast-casual assembly-line operations. Regional restaurant groups in United States Southwest markets test direct co-manufacturing relationships.
Leading the category by volume: Seafood Alternatives. Growing fastest: Dishes.
End User:
Procurement sophistication varies sharply across buyer types, with technical specification capacity determining supplier qualification thresholds and contract structure flexibility.
- Food Services:National distributor consolidation favors shelf-stable, high-volume formats with transparent algal-protein sourcing documentation. United States broadline operators now require third-party allergen-verification protocols as standard qualification criteria.
- Restaurants:Independent and regional group operators prioritize formulation collaboration and texture customization over unit cost minimization. Coastal urban clusters from San Francisco to Boston provide concentrated testing grounds for next-generation extrusion technologies.
- Retail Consumers:Frozen supermarket purchases dominate household acquisition, though online direct-to-consumer channels bypass conventional slotting-fee structures. Clean-label certification awareness drives premium-tier selection.
- Meal Kits:Pre-portioned integration demands precise cook-time predictability and packaging compatibility with chilled logistics. United States subscription services evaluate suppliers on formulation stability through variable temperature exposure.
Dominating procurement volume: Food Services. Expanding most quickly: Meal Kits.
Distribution Channel:
Margin capture and data-access tradeoffs differentiate channel strategies, with direct routes enabling rapid iteration while conventional retail maintains household penetration advantages.
- Online Retail:Direct-to-consumer frozen distribution captures purchase-pattern data for formulation refinement. United States operators leverage this channel for coastal urban market testing before broader rollout.
- Supermarkets:Conventional retail freezer placement requires slotting-fee investment and category-management negotiation. National brand recognition determines shelf-position access.
- Specialty Stores:Natural-product retailers reward USDA organic and EU organic certification with preferential placement. Clean-label formulations command price premiums in this channel.
- Food Distributors:Broadline and specialty distribution remains the primary route to food service volume. Consolidation among national distributors elevates importance of supply-chain transparency documentation.
Capturing majority household purchases: Supermarkets. Steepest expansion trajectory: Online Retail.
Application:
Temperature-performance requirements and presentation standards shape formulation specifications differently across preparation contexts.
- Cooking:Heat-stable protein matrices withstand sautéing and grilling without texture degradation. United States food service operators specify performance across equipment types.
- Sushi:Raw-consumption presentation demands stringent microbial-safety protocols and visual translucency replication. FDA seafood HACCP alignment requirements elevate supplier qualification barriers.
- Salad:Chilled-service applications prioritize moisture retention and dressing-compatibility. Regional restaurant groups specify cold-holding performance duration.
- Appetizers:Bite-sized formats with breading-adhesion properties suit fryer operations and frozen retail. QSR chains evaluate on holding-time consistency.
Widest food service penetration: Cooking. Gaining share fastest: Sushi.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal metropolitan clusters in the United States generate the majority of near-term demand, while European authorization protocols and Asian aquaculture integration efforts reshape competitive access across three distinct regulatory zones.
United States
San Francisco and Boston food service operators pilot next-generation extrusion formulations with immediate feedback loops. FDA allergen-labeling requirements and USDA organic certification pathways create tiered compliance costs that favor capitalized incumbents. The Pacific Northwest and Northeast corridor concentrate testing infrastructure for high-moisture extrusion scale-up.
Germany
Industrial food service distributors demand completed EFSA novel-food dossiers as mandatory qualification criteria. EU organic regulations and the EU Green Deal sustainability frameworks reward transparent algal-protein sourcing documentation. The Rhine-Ruhr metropolitan region anchors continental procurement consolidation among broadline operators.
United Kingdom
London-based restaurant groups pursue direct co-manufacturing relationships bypassing traditional distributor intermediaries. EFSA novel-food authorization alignment post-Brexit creates parallel but converging safety validation requirements. The Southeast England corridor concentrates meal-kit subscription services evaluating formulation stability.
Thailand
Wild-caught shrimp commodity pricing from Southeast Asian aquaculture markets sets psychological ceiling constraints on plant-based positioning. The country's national food regulator aligns with ASEAN harmonized standards for novel protein safety assessment. Bangkok metropolitan food manufacturers test hybrid formulations bridging traditional seafood processing with extrusion technology.
Netherlands
Rotterdam and Amsterdam food service clusters prioritize shelf-stable, high-volume formats with supply-chain transparency documentation. EU EFSA procedural clarifications from 2023 enable predictable multi-year investment planning for fermentation infrastructure. The Randstad region hosts precision-fermentation facilities qualifying for EU Green Deal transition financing.
Plant-Based Shrimp Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue coastal food service specialization and direct-procurement relationships. The market structure concentrates around three maturity tiers: venture-stage specialists with completed regulatory dossiers, mid-scale co-manufacturers leveraging shared protein-extraction infrastructure, and diversified protein conglomerates with captive distribution networks. Dominant competitive moves include food service co-manufacturing agreements and precision-fermentation capacity expansion.
Among North American specialists, Beyond Meat, Gathered Foods Corp, and New Wave Foods exemplify distinct strategic archetypes. Beyond Meat represents diversified infrastructure leverage, deploying existing protein-extraction capabilities across co-manufacturing partnerships. Gathered Foods Corp anchors direct-relationship positioning with regional restaurant groups seeking formulation collaboration. New Wave Foods occupies coastal distribution density specialization rather than national retail breadth expansion.
| Leading Market Players |
|---|
| Beyond Meat |
| Gathered Foods Corp |
| Maple Leaf Foods |
| New Wave Foods |
| Finless Foods |
| Ocean Hunger Foods |
| Thai Union |
| Nestlé |
| Impossible Foods |
| Others |
Value Network & Pricing Analysis
Food service distributor consolidation across the United States is forcing suppliers to absorb certification and transparency documentation costs that previously flowed through to buyers, compressing margins for mid-tier producers while rewarding incumbents with captive algal-protein sourcing infrastructure.
Pricing Analysis
Volume procurement through national broadline distributors operates on thin margins, while direct-to-restaurant relationships capture premium pricing through formulation collaboration. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic-certified suppliers from conventional legume-protein operators and imported commodity analogs. Cost compression in the economy tier is intensifying because of wild-caught shrimp price anchoring from Southeast Asian aquaculture. QSR chains exhibit the highest price sensitivity, whereas coastal metropolitan restaurant groups prioritize texture performance over unit cost.
Supply Chain Analysis
Regional distribution centers in the United States Northeast and Pacific Northwest anchor hub-and-spoke patterns for frozen product delivery. Algal-protein concentrate production centers on the Netherlands, United States, and Iceland, while high-moisture extrusion equipment manufacturing draws from Germany and Italy. Single-source vulnerability in fermentation-derived astaxanthin from North Atlantic bioreactor operators exposes margins to batch-yield fluctuations. Distribution runs through broadline food service distributors, though direct-to-operator channels are accelerating.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over precision-fermentation infrastructure and algal-protein extraction capacity determines who captures margin in the premium tier.
For Market Incumbents: Anticipate patent litigation risk on binding hydrocolloid combinations by accelerating freedom-to-operate assessments and defensive filing in advance of venture-stage entrants. Secure backward integration into legume-protein processing through acquisition of regional organic-certified suppliers before EU organic transition requirements tighten further. Control over captive algal-protein sourcing is the critical defensive lever. For New Entrants and Emerging Players: Regional restaurant groups in United States Southwest markets seeking taco-format co-manufacturing partnerships represent the most penetrable buyer archetype with limited incumbent saturation. Meal-kit subscription services evaluating formulation stability through variable temperature exposure offer a second white-space target with lower certification barriers than food service broadline. A direct-procurement positioning with transparent sourcing documentation provides the strongest go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors venture-stage specialists with completed EFSA novel-food dossiers and demonstrated coastal food service traction. Long-term viability hinges on whether precision-fermentation capacity can achieve cost parity with commodity extraction before animal-protein price anchors shift. Watch for stabilization in algal-protein batch yields as the inflection signal separating scalable platforms from stranded assets.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Capacity Expansion | Qualifying facilities for IRA clean-energy tax credits offsets capital intensity in United States bioprocessing hubs. |
| EFSA Novel-Food Dossier Completion | Pre-submission consultation investments enable predictable multi-year planning for European market access. |
| Direct Co-Manufacturing Agreements | Regional restaurant groups bypass distributor intermediaries to capture formulation collaboration and margin. |
| High-Moisture Extrusion Line Retrofit | Shrimp-specific die configurations on existing meat-analog equipment compress pilot-to-production scale-up timelines. |
| Algal-Protein Sourcing Certification | EU organic and transparent fermentation documentation satisfies procurement screening from consolidated distributors. |
Research Methodology
Independent corroboration across food service procurement executives, high-moisture extrusion equipment specialists, regulatory affairs leads at algal-protein suppliers, and restaurant group culinary directors underwrites the qualitative findings. Secondary validation draws from FDA allergen-labeling guidance documents, EFSA novel-food authorization registers, USDA organic certification databases, and United States customs trade records. Bottom-up volume estimates from segment-level procurement interviews triangulate against top-down market sizing from distributor consolidation patterns.
Comparable-period anchoring to historical extrusion technology adoption curves and regulatory authorization timelines structures the projection framework. Segmentation modeling spans product format, end-user procurement sophistication, distribution channel margin capture, and application-specific temperature performance across the analysis window. CAGRs derive from fitted growth curves against validated adoption inflection points, with inputs including coastal metropolitan operator testing velocity and EFSA procedural timeline stability.
Revisions become necessary when algal-protein batch-yield volatility triggers supply rationing, when FDA allergen-labeling requirements expand to novel protein categories, or when wild-caught shrimp commodity pricing collapses below plant-based production cost floors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Plant-Based Food and Beverages Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Flax-Based Protein Market
Plant Based Food
France Plant Protein Market
Plant Based Food
United Kingdom Tofu Market
Plant Based Food
South America Rice Protein Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
Plant Based Meat Market
Plant Based Food
Plant Based Collagen Market
Plant Based Food
Plant-Based Wellness Foods Market
Plant Based Food
Vegan Drink Mixes Market
Plant Based Food
Plant Based Pork Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
India Pea Protein Market