
 Acetylated Distarch Phosphate Market | 2026-2036
Acetylated Distarch Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Acetylated Distarch Phosphate Market Outlook
European modified starch production capacity is broadening as wet-milling investments expand across the Netherlands and France. AGRANA Beteiligungs-AG leverages its Austrian beet-sugar and starch co-location to secure backward integration into acetylated derivatives. Ingredion Incorporated sustains technical leadership through its specialty texture solutions laboratory in Bridgewater, New Jersey. Roquette Frères anchors supply security via its Lestrem biorefinery complex, the largest pea and starch processing site in Europe.
Acetylated distarch phosphate is a modified starch produced by esterification with acetic anhydride and cross-linking with sodium trimetaphosphate, yielding a compound with enhanced freeze-thaw stability, acid resistance, and viscosity retention under shear. Its primary industrial purpose centers on delivering consistent rheological performance in retorted, frozen, and high-acid food systems where native starches degrade. The food and beverage application segment occupies the dominant margin pool due to volume concentration in processed sauces, dressings, and dairy analogs, while pharmaceutical-grade specifications command premium positioning through compendial purity requirements. Thickening agents lead product-type revenue as formulators prioritize viscosity build over emulsification in cost-sensitive categories.
FDA food additive regulations under 21 CFR 172.892 govern acetylated distarch phosphate usage limits and labeling in the United States, while EFSA evaluates modified starch safety dossiers for European market authorization under Regulation (EC) No 1333/2008. BIS certification requirements in India and FSSAI food additive standards create layered compliance obligations for exporters targeting multiple jurisdictions. Stakeholders must monitor evolving clean-label definitions and phosphate-content disclosure mandates that threaten to reclassify traditionally accepted modified starches.
Market Dynamics
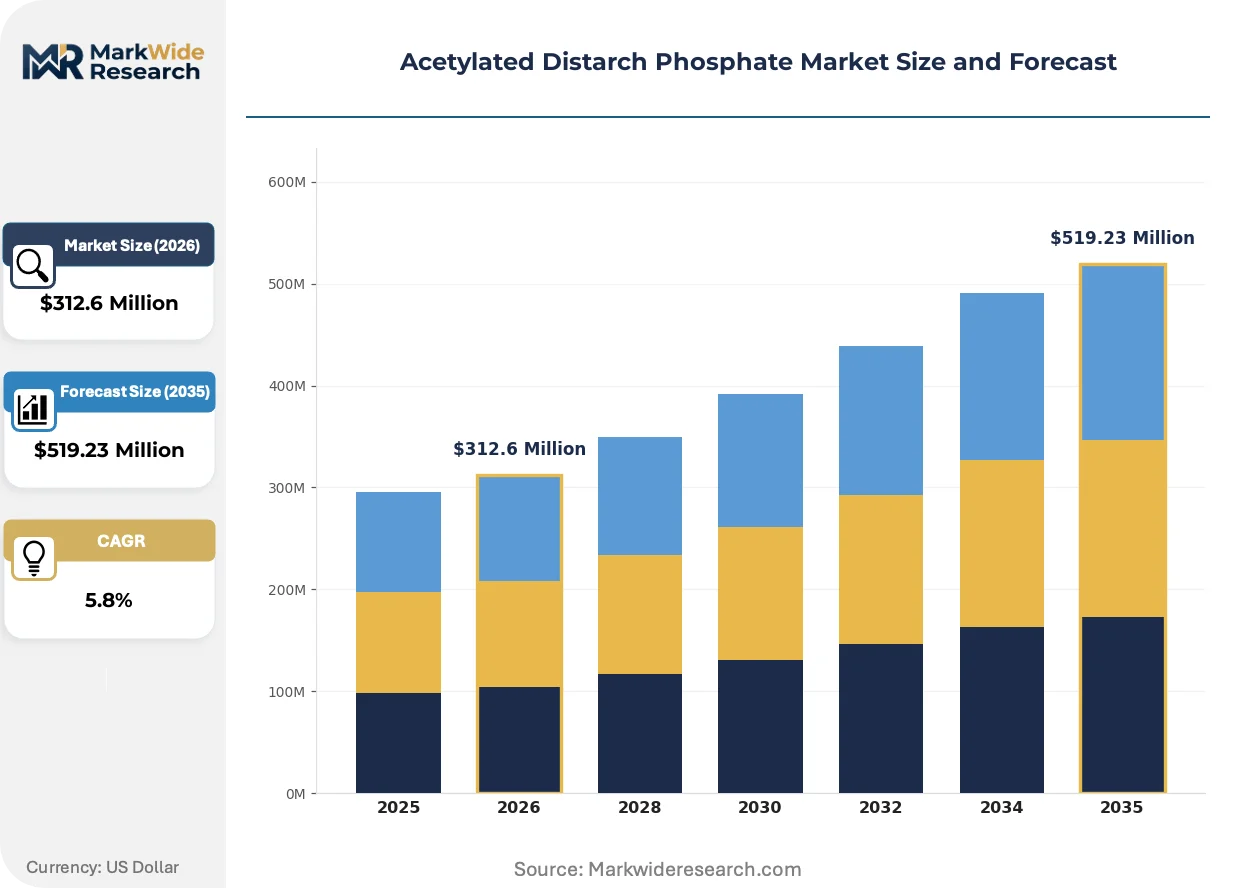
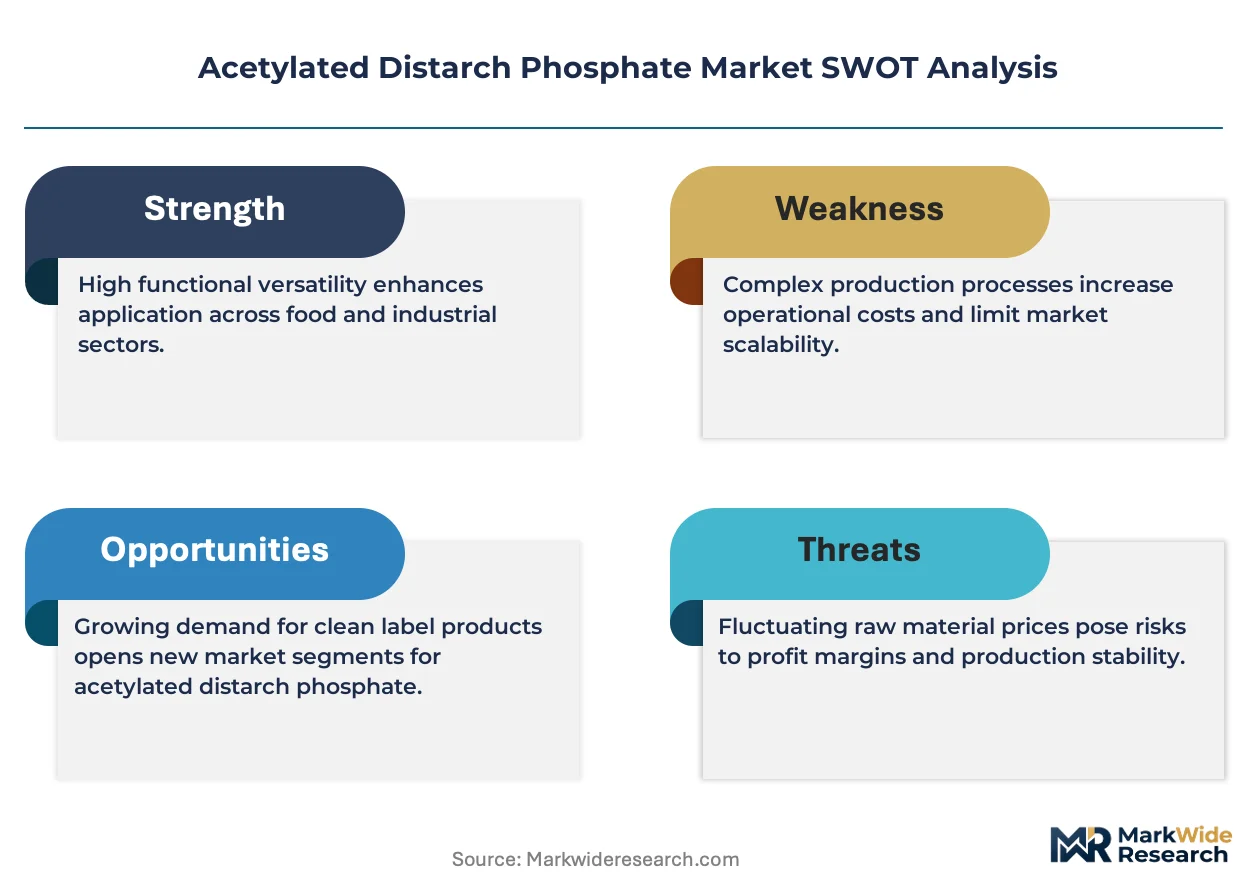
Clean-label reformulation mandates and phosphate-content disclosure requirements are forcing food manufacturers to reassess their modified starch portfolios, while wet-milling capacity expansion in the Netherlands and France tightens supply-side concentration among European processors.
Growth Catalysts
- EU F-Gas Regulation:Industrial refrigeration standards are accelerating demand for freeze-thaw stable modified starches in cold-chain sauces and dressings, as formulators seek alternatives to gum-based stabilizers.
- Thailand's ready-meal export sector:Processed food manufacturers are scaling acetylated distarch phosphate procurement to meet retort pouch specifications for Japanese and Australian retail channels.
- Acid-resistant starch technology:Esterification process improvements enable clean-label positioning in high-acid condiments without sacrificing shelf stability, opening formulation latitude previously restricted to synthetic stabilizers.
Market Restraints
- Phosphate input volatility:Sodium trimetaphosphate supply concentrates among Chinese chemical processors, exposing derivative manufacturers to export licensing disruptions and freight cost spikes.
- REACH compliance burden:ECHA registration dossier requirements for modified starch intermediates extend lead times for new product introductions, compressing innovation cycles.
- Native starch substitution:Cold-water swelling tapioca and waxy maize variants are capturing cost-sensitive sauce applications where freeze-thaw performance is secondary.
Strategic Opportunities
- Indonesia's processed food corridor:Domestic sauce and instant noodle manufacturers lack backward-integrated starch modification capabilities, creating white space for technical partnership models.
- Pharmaceutical compendial grades:USP-NF and EP monograph alignment for excipient applications commands 40-60% price premiums over food-grade specifications.
- Biorefinery co-location:Pea and potato starch processors in France and Canada can retrofit acetylation units onto existing wet-milling infrastructure with marginal capital deployment.
Industry Challenges
- Cross-functional formulation expertise:Food manufacturers lack internal rheology specialists capable of optimizing acetylated distarch phosphate dosage across variable shear and thermal processing conditions.
- Multi-jurisdiction certification timelines:Simultaneous BIS, FSSAI, and FDA food additive approvals for new derivative grades extend commercialization cycles by 18-24 months.
- Legacy ERP integration:Modified starch procurement systems at mid-tier food processors cannot accommodate real-time viscosity specification tracking from supplier certificates of analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetylated Distarch Phosphate Market |
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $519.23 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Food & Beverage, Pharmaceuticals, Personal Care, Industrial Product Type: Thickening Agents, Stabilizers, Emulsifiers, Binders End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Chemical Processors Packaging Type: Bags, Pails, Drums, Bulk Containers |
| Companies Covered | AGRANA Beteiligungs-AG, Ingredion Incorporated, Roquette Frères, Tate & Lyle Plc, Cargill, Incorporated, Archer-Daniels-Midland Company, DAWU CORPORATION, Universal Starch Chem Allied Ltd., Samyang Genex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetylated Distarch Phosphate Market Strategic Shifts
Process intensification in starch modification is compressing reaction times and solvent recovery costs, while regulatory disclosure mandates are reshaping how formulators communicate ingredient functionality to consumers.
Enzymatic debranching prior to acetylation is converging with conventional chemical modification to produce starches with dual-functionality: enhanced clarity for dressings alongside superior freeze-thaw stability for frozen desserts. Specialty sauce manufacturers in Japan and South Korea are piloting these hybrid derivatives at 500-ton annual volumes. This convergence is compressing the historical trade-off between optical properties and mechanical stability that forced formulators to choose between native and chemically modified starches.
REACH authorization requirements for phosphate-containing substances are tightening substance volume tracking and downstream user communication obligations across European modified starch supply chains. ECHA's 2024 updated guidance on polymer registration boundaries is forcing importers to reassess whether acetylated distarch phosphate qualifies as a polymer or requires full substance registration. Food-grade starch distributors serving German and Dutch manufacturers are investing in regulatory data management systems to maintain import continuity.
Direct technical service engagement is displacing traditional distributor-led specification selling in Southeast Asian processed food markets. Indonesian and Thai sauce manufacturers now expect on-site rheology testing and formulation troubleshooting from modified starch suppliers, compressing margins for intermediaries lacking technical capabilities. This shift concentrates procurement relationships with suppliers maintaining regional application laboratories, particularly in Jakarta and Bangkok industrial zones.
Acetylated Distarch Phosphate Market Segmentation
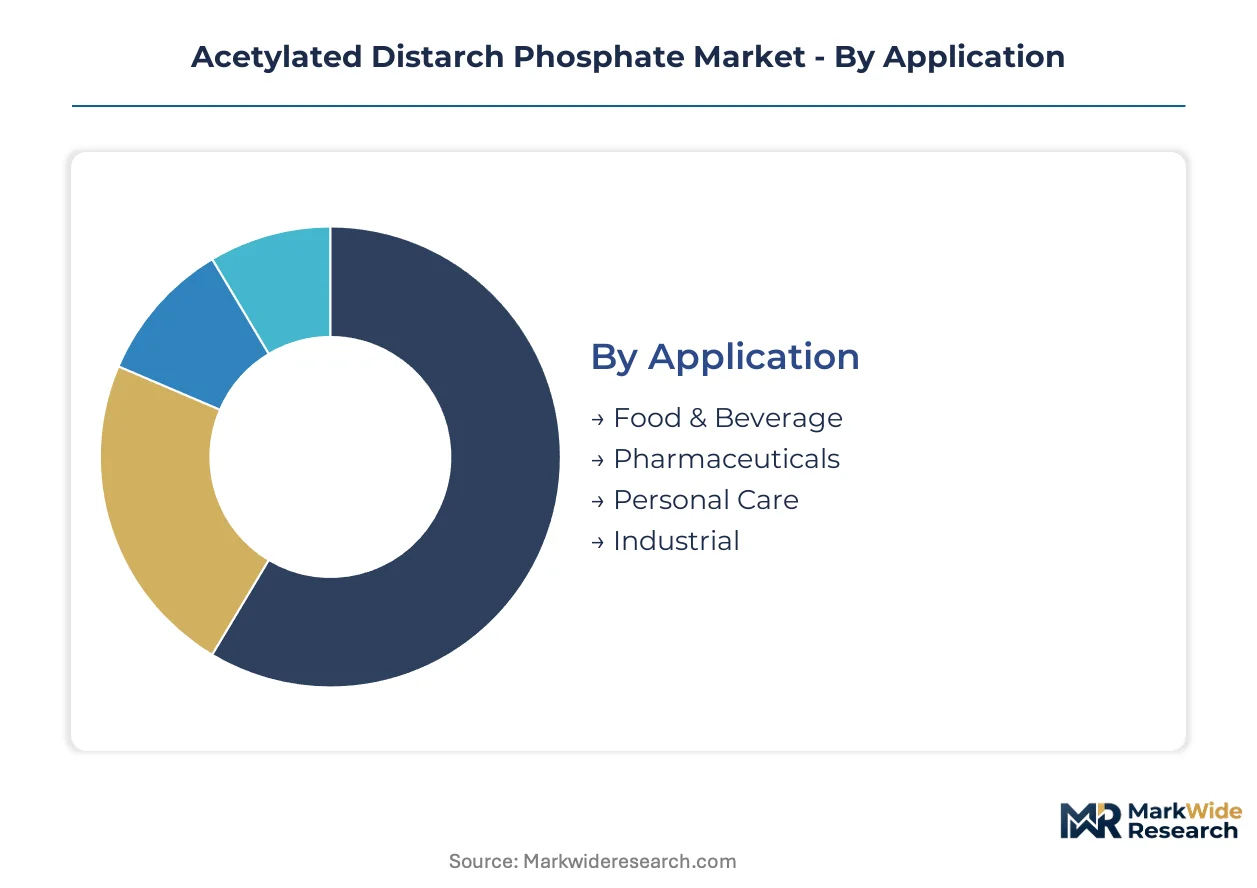
Formulators select acetylated distarch phosphate grades based on shear stability requirements, regulatory jurisdiction, and thermal processing conditions. Segment boundaries blur as pharmaceutical-grade specifications migrate into premium food applications and clean-label positioning reshapes traditional category definitions.
Application:
End-use selection hinges on freeze-thaw cycle frequency and acid exposure severity during processing.
- Food & Beverage:Retort sauces, dressings, and dairy analogs demand acid-resistant viscosity retention under shear. Southeast Asian sauce manufacturers in Indonesia and Thailand scale procurement for clean-label reformulations targeting Japanese export specifications.
- Pharmaceuticals:USP-NF and EP compendial grades command premium positioning through excipient purity requirements. Tablet binders and controlled-release matrices concentrate procurement among European contract manufacturers facing EMA quality mandates.
- Personal Care:Cream and lotion formulators leverage emulsion stabilization in pH-variable systems.
- Industrial:Adhesive and textile sizing applications prioritize cost-optimized viscosity build over freeze-thaw performance.
Food & Beverage leads on scale; Pharmaceuticals leads on momentum.
Product Type:
Functional hierarchy reflects formulation cost sensitivity against performance tier requirements.
- Thickening Agents:Dominant volume share concentrates in cost-sensitive sauce and gravy applications where viscosity build outweighs emulsification needs. Indonesian instant noodle manufacturers specify mid-range acetylation levels to balance hydration speed with texture retention.
- Stabilizers:Freeze-thaw stability specifications drive premium positioning in frozen dessert and ready-meal segments. Thai exporters to Australian retail channels prioritize cross-linked variants for extended cold-chain integrity.
- Emulsifiers:Dual-functionality grades penetrate salad dressing and mayonnaise systems requiring oil-water interface stability.
- Binders:Compression characteristics and disintegration profiles govern pharmaceutical tablet and granule applications.
Thickening Agents dominates procurement volume; Stabilizers climbs fastest on clean-label frozen food demand.
End User:
Technical service intensity varies sharply across buyer sophistication and formulation capability.
- Food Manufacturers:Processed sauce and ready-meal producers in Southeast Asia drive specification complexity. Direct supplier engagement replaces distributor relationships as Jakarta and Bangkok manufacturers demand on-site rheology testing and shear optimization protocols.
- Pharmaceutical Firms:Compendial compliance burdens concentrate procurement among European and North American excipient specialists with dedicated regulatory affairs functions.
- Cosmetic Companies:Mid-tier personal care formulators in South Korea and Japan prioritize optical clarity and skin-feel modulation.
- Chemical Processors:Industrial adhesive and textile manufacturers emphasize bulk volume pricing and consistent lot-to-lot viscosity.
Food Manufacturers anchor demand scale; Pharmaceutical Firms expand most quickly on excipient premiumization.
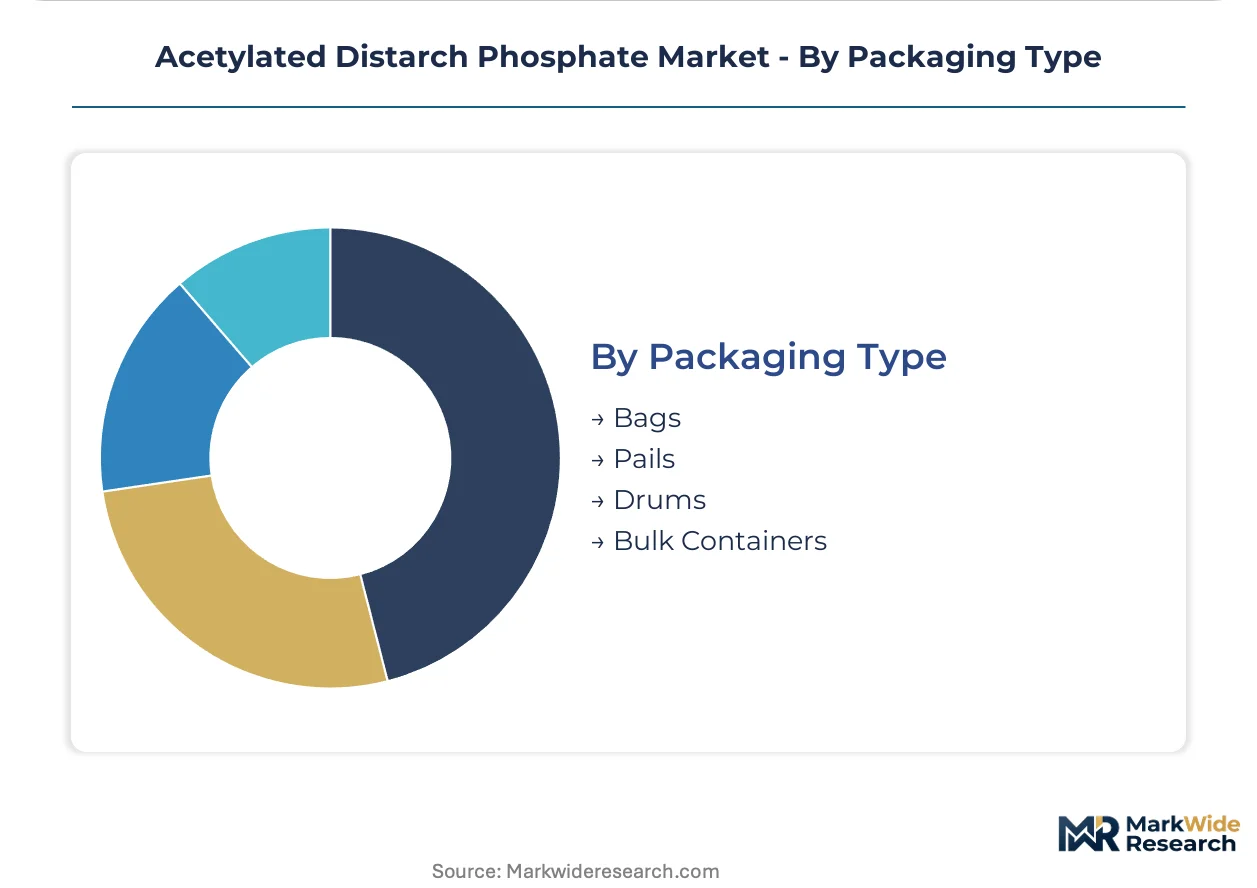
Packaging Type:
Supply chain configuration reflects handling automation levels and contamination risk thresholds.
- Bags:Standard 25kg multi-wall paper sacks serve mid-volume food manufacturers with manual handling capabilities. Indonesian sauce producers favor this format for warehouse flexibility and lot traceability.
- Bulk Containers:Food-grade totes and silo deliveries align with wet-milling co-location strategies and large-scale continuous processing lines.
- Pails:Smaller batch requirements from cosmetic compounders and pharmaceutical R&D labs favor sealed plastic pails with desiccant protection.
- Drums:Steel and fiber drums accommodate intermediate volumes for regional distributors serving fragmented processor bases.
Bags retains volume leadership; Bulk Containers gains share fastest on biorefinery integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate acetylated distarch phosphate capacity toward jurisdictions with streamlined chemical registration protocols and lower compliance overhead. Wet-milling investments concentrate in the Netherlands and France where REACH dossier consolidation reduces per-substance administrative burden relative to multi-jurisdiction filing requirements elsewhere.
United States
FDA food additive regulations under 21 CFR 172.892 govern usage limits for retort sauces and frozen desserts. Domestic sauce manufacturers in New Jersey and California scale procurement for clean-label reformulations targeting retail channels. Bridgewater laboratory facilities anchor technical service delivery to Northeast corridor food processors.
Germany
ECHA registration requirements for modified starch intermediates extend lead times for new derivative introductions. Frankfurt and Hamburg chemical distributors invest in regulatory data management systems to maintain import continuity under evolving polymer registration guidance. Food-grade starch supply chains serving Bavarian sauce producers face heightened substance volume tracking obligations.
China
Sodium trimetaphosphate supply concentrates among domestic chemical processors, exposing derivative manufacturers to export licensing disruptions. Shanghai and Guangdong wet-milling operations retrofit acetylation capacity onto existing infrastructure. NMPA-equivalent food additive standards create layered certification requirements for starch derivatives entering pharmaceutical excipient channels.
Indonesia
Domestic sauce and instant noodle manufacturers lack backward-integrated starch modification capabilities, creating partnership opportunities for technical service providers. BIS certification requirements for imported food additives extend procurement qualification timelines. Jakarta industrial zones concentrate demand from processed food corridors serving Southeast Asian retail distribution.
Thailand
Ready-meal exporters to Japanese and Australian retail channels scale acetylated distarch phosphate procurement for retort pouch specifications. Bangkok manufacturers demand on-site rheology testing and shear optimization protocols from suppliers. Cold-chain infrastructure expansion accelerates demand for freeze-thaw stable modified starches in dressing and sauce applications.
Acetylated Distarch Phosphate Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade specialization and biorefinery co-location strategies. The vendor base stratifies across three maturity levels: multinational starch processors with integrated wet-milling assets, regional modifiers serving single-country food manufacturing clusters, and specialty chemical distributors lacking technical service capabilities. Strategic archetypes include backward-integrated agricultural processors, application-focused technical service providers, and regulatory compliance specialists managing multi-jurisdiction certification portfolios. Dominant competitive moves center on wet-milling capacity expansion in the Netherlands and France, plus direct technical service engagement displacing traditional distributor relationships in Southeast Asian markets.
Among European agricultural processors, AGRANA Beteiligungs-AG and Roquette Frères exemplify the backward-integrated archetype, leveraging co-located beet-sugar and pea starch operations to secure captive feedstock supply. Ingredion Incorporated occupies a position within the technical service tier, anchoring specialty texture solutions capabilities through Northeast corridor laboratory infrastructure. These three entities represent distinct competitive positioning vectors: Austrian and French biorefinery integration versus American application development focus.
| Leading Market Players |
|---|
| AGRANA Beteiligungs-AG |
| Ingredion Incorporated |
| Roquette Frères |
| Tate & Lyle Plc |
| Cargill, Incorporated |
| Archer-Daniels-Midland Company |
| DAWU CORPORATION |
| Universal Starch Chem Allied Ltd. |
| Samyang Genex Corporation |
| Others |
Value Chain & Pricing Dynamics
Mid-tier Southeast Asian sauce manufacturers concentrate procurement volumes, locking in contract-based long-term offtake agreements with European biorefinery operators to secure freeze-thaw stable supply tiers.
Pricing Analysis
Distributor margin compression reshapes channel economics as direct technical service engagement displaces traditional intermediary relationships. Three-tier pricing structure across pharmaceutical-grade, food-grade premium, and economy industrial specifications reflects certification burden differentials. Pricing pressure stems from sodium trimetaphosphate input volatility and REACH compliance cost pass-through. Pharmaceutical-grade buyers exhibit least price sensitivity due to compendial purity mandates, while industrial adhesive manufacturers prioritize bulk volume discounts.
Supply Chain Analysis
BIS certification requirements in India and domestic-content preferences in Indonesia reshape sourcing patterns toward regional modification facilities. Supply concentrates in the Netherlands, France, and China, with wet-milling capacity expansion in Europe tightening processor concentration. Raw material dependencies center on acetic anhydride, sodium trimetaphosphate, and native tapioca or waxy maize feedstock. Single-source vulnerability concentrates in Chinese phosphate chemical processors exposed to export licensing disruptions. Distribution runs through technical service providers maintaining regional application laboratories in Jakarta and Bangkok.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with pharmaceutical-grade excipient specifications and clean-label positioning commanding sustained premium capture over commodity food-grade alternatives.
For Market Incumbents: To counter native starch substitution in cost-sensitive sauce applications, deepen captive supply of acetylation-ready feedstock through biorefinery co-location in the Netherlands and France. Prioritize certification investment for USP-NF and EP monograph alignment to defend margin position in pharmaceutical channels against emerging specialty chemical entrants. For New Entrants and Emerging Players: Launch via technical partnership models targeting Indonesia's processed food corridor, where domestic manufacturers lack backward-integrated starch modification capabilities. Penetrate pharmaceutical compendial grades for tablet binder applications, leveraging regulatory data management systems to compress multi-jurisdiction approval timelines relative to established competitors. For Investors and Strategic Acquirers: Agricultural processors with wet-milling assets are the most active acquirer in this space, seeking application laboratories and regional formulation expertise. Target mid-cap modifiers with Southeast Asian technical service presence and existing BIS/FSSAI certification portfolios. Monitor ECHA polymer registration guidance evolution as inflection indicator for European import continuity risk.| Strategic Initiative | Industry Significance |
|---|---|
| Wet-Milling Capacity Expansion | Roquette Frères and AGRANA anchor supply security through Lestrem and Austrian biorefinery complexes. |
| Pharmaceutical Compendial Certification | USP-NF and EP alignment commands 40-60% price premiums over food-grade specifications in excipient channels. |
| Technical Service Laboratory Deployment | Direct engagement in Jakarta and Bangkok displaces distributor-led specification selling for Southeast Asian sauce manufacturers. |
| Backward Integration into Feedstock | Pea and potato starch processors in France and Canada retrofit acetylation units with marginal capital deployment. |
| Regulatory Data Management Investment | Frankfurt and Hamburg distributors maintain import continuity under evolving ECHA polymer registration boundaries. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with modified starch procurement leads, regulatory affairs directors at food additive distributors, plant managers at wet-milling facilities, and technical R&D specialists at sauce manufacturers. Secondary validation draws from FDA 21 CFR filings, EFSA safety dossiers, BIS certification records, customs trade data, and SEC 10-K disclosures from listed agricultural processors. Bottom-up volume modeling triangulates against top-down industry absorption estimates.
Granularity-level modeling disaggregates demand across application segments, product type tiers, end-user sophistication levels, and packaging format configurations. CAGRs derive from segment-level volume build-ups and price trajectory assumptions across the analysis window. Industry-specific forecast inputs incorporate REACH compliance cost pass-through rates and clean-label reformulation adoption curves in Southeast Asian export channels.
Forecast precision tightens around the base case; tail outcomes carry wider variance under phosphate export licensing disruptions and evolving EFSA clean-label disclosure mandates. Forecasts reflect documented assumptions regarding wet-milling capacity expansion timelines and pharmaceutical excipient premium sustainability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
Invertase Market
Food Additives and Ingredients
Russia Feed Additives Market
Food Additives and Ingredients
Hydrocolloids Market
Food Additives and Ingredients
Filling Fat Market
Food Additives and Ingredients
Protective Cultures Market
Food Additives and Ingredients
Starch-Based Edible Coatings Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
China Food Emulsifiers Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
Food Grade Calcium Phosphate Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
Lecithin Market