
 Vietnam Fruits and Vegetables Market | 2026-2036
Vietnam Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Fruits and Vegetables Market Analytics
Mekong Delta horticulture is consolidating as commercial farms expand controlled-environment acreage for year-round supply. U&I Agricultural Corporation leverages its integrated cold-chain network to lock in supermarket contracts across southern provinces. Nafoods Group specializes in dragon fruit and passion fruit processing for export markets. Tien Thinh Group anchors its position through direct farm-gate sourcing that bypasses traditional wholesale layers.
Vietnam fruits and vegetables encompass fresh and minimally processed plant products harvested for human consumption, typically graded by Brix content, firmness, and cosmetic standards before distribution. The sector serves domestic food security needs and foreign exchange generation through export-oriented cultivation. Leafy greens and stone fruits occupy distinct margin pools, with premium-grade stone fruits commanding higher export unit economics while local markets absorb volume-grade leafy greens. Distribution through online retail channels is expanding fastest among structural segments, though export channels still capture the largest absolute value flows.
Vietnam's Ministry of Agriculture and Rural Development enforces pesticide maximum residue limits that shape farm-level input decisions and market access eligibility for EU and US buyers. The national food safety authority coordinates with plant protection departments to certify growing regions for export qualification. Stakeholders must monitor how tightening phytosanitary protocols in destination markets reshape investment requirements for packing house upgrades and traceability systems.
Market Dynamics
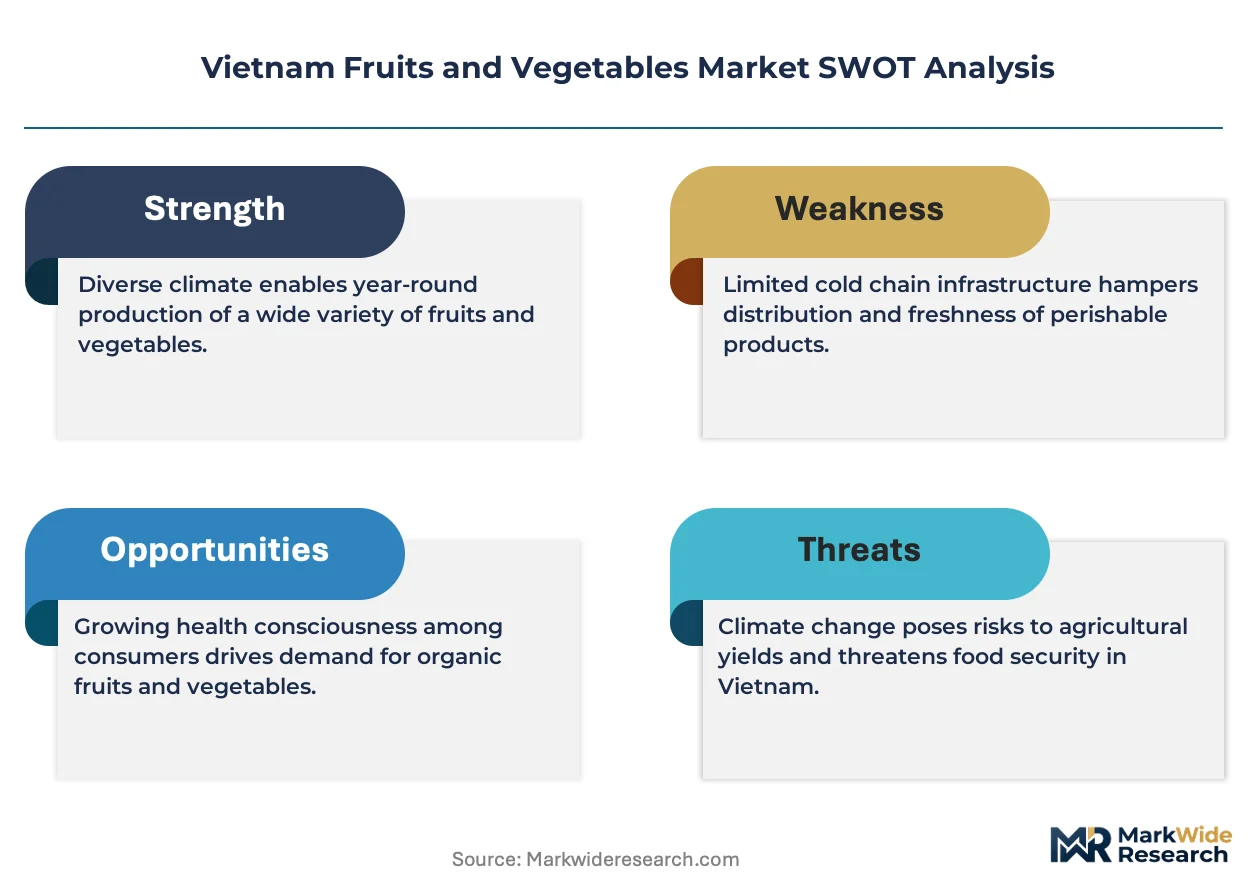
Vietnam's Ministry of Agriculture and Rural Development is tightening pesticide residue standards under national food safety protocols, forcing processors to upgrade traceability systems and cold-chain infrastructure to maintain EU and US market access eligibility.
Growth Catalysts
- EU-Vietnam Free Trade Agreement tariff schedules:Elimination of import duties on fresh dragon fruit and passion fruit shipments creates margin expansion for Mekong Delta exporters targeting Rotterdam and Hamburg distribution hubs.
- Controlled-environment agriculture acreage:Commercial farms in Long An and Tien Giang provinces are expanding greenhouse and net-house coverage for year-round supply continuity to domestic supermarket chains.
- Urban fresh-format retail expansion:Convenience store networks in Ho Chi Minh City and Can Tho are dedicating floor space to pre-packaged vegetable SKUs, pulling volume through direct farm contracts.
Market Restraints
- Input cost volatility:Fertilizer and agrochemical prices fluctuate with global energy markets, compressing margins for smallholder growers in An Giang and Dong Thap provinces who lack forward-contracting power.
- Phytosanitary certification backlog:Vietnam's plant protection department faces inspection capacity constraints, delaying export qualification for new growing regions seeking EU and US entry.
- Substitute protein sourcing:Imported frozen vegetables from Thailand and China compete on price in food service channels, displacing domestic volume in institutional catering contracts.
Strategic Opportunities
- Central Highlands expansion:Lam Dong and Dak Lak provinces offer untapped highland terrain for temperate vegetable cultivation targeting domestic supermarket premium tiers.
- E-commerce direct-to-consumer channels:Fresh produce platforms are bypassing traditional wet-market intermediaries, enabling farm-branded packaging and subscription box models in Hanoi and Da Nang.
- Post-harvest technology convergence:Integration of ethylene scrubbing with modified atmosphere packaging extends shelf life for dragon fruit exports to Middle Eastern markets.
Industry Challenges
- Traceability system integration:Smallholder cooperatives struggle to deploy blockchain-based lot-tracking platforms required by EU retailers, creating compliance gaps in export supply chains.
- Certification timeline compression:GlobalGAP and VietGAP audit backlogs delay market entry for new commercial farms, locking capital in pre-revenue cultivation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Fruits and Vegetables Market |
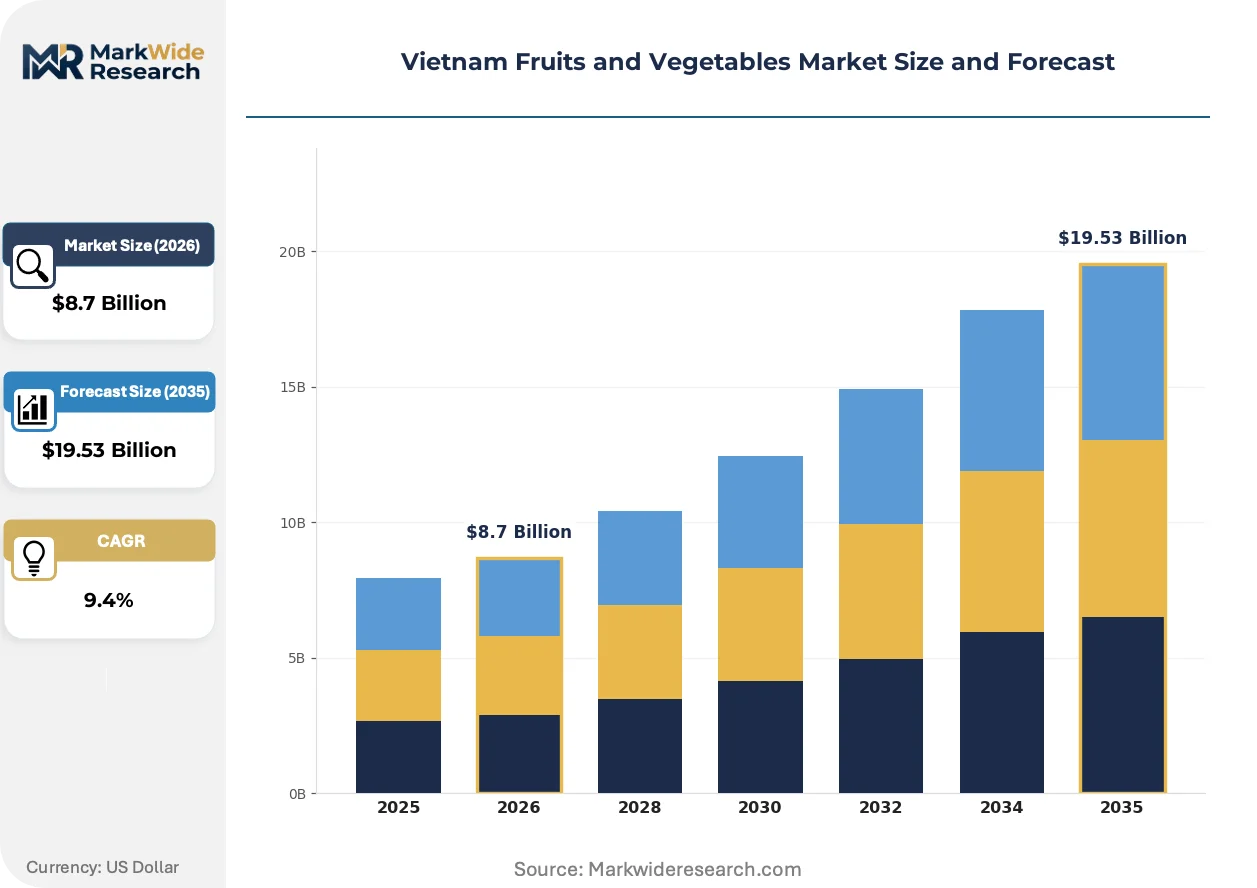
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leafy Greens, Root Vegetables, Berries, Stone Fruits Distribution Channel: Supermarkets, Local Markets, Online Retail, Export End User: Restaurants, Households, Food Processors, Retailers Quality Grade: Organic, Conventional, Premium, Standard |
| Companies Covered | U&I Agricultural Corporation, Tien Thinh Group, Hoang Anh Gia Lai Group, Vina T&T, Hoa Phat Agriculture Development, Nafoods Group, Hoang Anh Gia Lai Agricultural, Kingfoodmart, Antesco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Fruits and Vegetables Market Evolving Landscape
Technology adoption is fragmenting traditional supply hierarchies as digital platforms and precision agriculture tools redistribute power between growers, processors, and retail buyers across Vietnam's horticulture value chain.
Internet-of-things sensor networks deployed in Mekong Delta greenhouses are decentralizing quality control authority away from centralized packing houses. Commercial farms in Vinh Long province now transmit real-time humidity and temperature data directly to supermarket procurement teams. This shift compresses rejection rates at receiving docks and collapses the information advantage traditionally held by wholesale intermediaries.
Vietnam's Ministry of Agriculture and Rural Development is enforcing tightened maximum residue limits for organophosphate and carbamate compounds under revised national food safety protocols. Exporters to Germany and the Netherlands must now demonstrate laboratory testing from accredited domestic facilities. Mekong Delta processors are responding by consolidating supplier bases to farms with documented integrated pest management compliance.
Food service buyers are unbundling procurement from traditional wholesale market layers, establishing direct farm-gate contracts with volume guarantees and quality specifications. Hotel and restaurant chains in Ho Chi Minh City now source leafy greens through dedicated supplier agreements rather than spot-market purchases. This behavioral shift concentrates procurement volume among larger commercial farms with cold-chain capabilities, marginalizing smallholder participation in premium channels.
Vietnam Fruits and Vegetables Market Segmentation
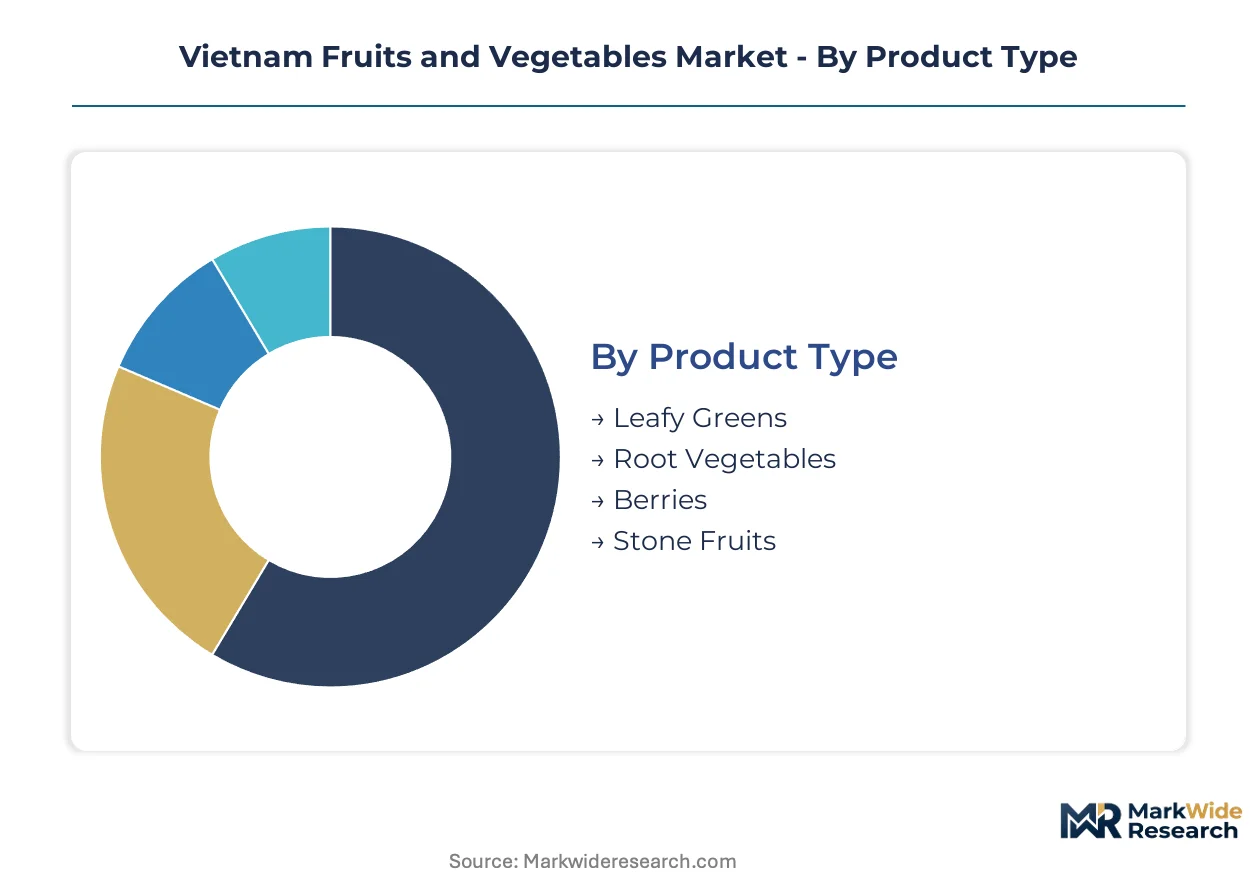
Segmentation reveals how procurement power, shelf-life requirements, and certification thresholds split Vietnam's horticulture sector into distinct margin pools. Buyers prioritize different attributes—traceability for export channels, freshness for food service, price for household wet-market purchases—creating non-overlapping competitive arenas.
Product Type:
Buyers distinguish crop categories by perishability windows, labor intensity, and climate adaptation requirements.
- Leafy Greens:Spinach, water morning glory, and mustard greens dominate household consumption with 48-hour harvest-to-plate cycles. Mekong Delta smallholders supply Ho Chi Minh City wet markets through predawn wholesale auctions, though supermarket chains now contract directly for pre-packaged SKUs.
- Root Vegetables:Sweet potato, cassava, and carrot cultivation spans longer growing cycles with mechanized harvesting potential. Da Lat highland farms ship carrots to Japanese importers under strict diameter and sugar-content specifications, capturing premium export margins unavailable to lowland suppliers.
- Berries:Strawberry and mulberry production concentrates in Lam Dong province greenhouse clusters for domestic premium retail.
- Stone Fruits:Mango, lychee, and longan face 14-day cold-chain requirements for EU compliance.
Root vegetables lead volumes today; berries are gaining share fastest through controlled-environment acreage expansion.
Distribution Channel:
Channel selection determines cold-chain investment depth, traceability system requirements, and payment terms for suppliers.
- Supermarkets:VinMart, Co.opmart, and WinMart enforce VietGAP certification, barcode traceability, and fixed delivery windows. Their procurement teams audit farms directly, consolidating supplier bases to 50-100 core commercial operations per chain.
- Local Markets:Traditional wet markets in Can Tho, My Tho, and Long Xuyen operate on cash-based spot trading with minimal quality standardization. Smallholders access these channels through layer-3 intermediaries who aggregate sub-ton volumes across 15-20 farms.
- Online Retail:Tiki, Shopee, and specialized platforms like Greenie connect Mekong Delta farms to Hanoi and Da Nang households through subscription box models.
- Export:Rotterdam, Hamburg, and Dubai-bound shipments require GlobalGAP, SMETA, and phytosanitary certificates from Vietnam's plant protection department.
Local markets dominate transaction volume; online retail is expanding most quickly among domestic channels.
End User:
User categories separate by volume scale, specification tolerance, and substitution flexibility.
- Restaurants:Hotel chains and casual dining groups in Ho Chi Minh City source through annual contracts with volume guarantees and rejection clauses for cosmetic defects. Pho and banh xeo establishments prioritize leafy green freshness over certification, accepting shorter shelf life for price advantage.
- Households:Urban consumers split between wet-market price sensitivity and supermarket convenience premiums, with e-commerce capturing younger demographics in Hanoi and Da Nang.
- Food Processors:Nafoods Group and similar operators contract dragon fruit and passion fruit at farm-gate for IQF and puree production, requiring Brix minimums and pesticide residue documentation.
- Retailers:Convenience store networks expand fresh-format sections, pulling pre-cut vegetable SKUs through direct farm agreements.
Households absorb the largest volume absolute; food processors are climbing the fastest as value-added export capacity expands.
Quality Grade:
Grade stratification aligns with certification cost, buyer audit intensity, and price realization spread.
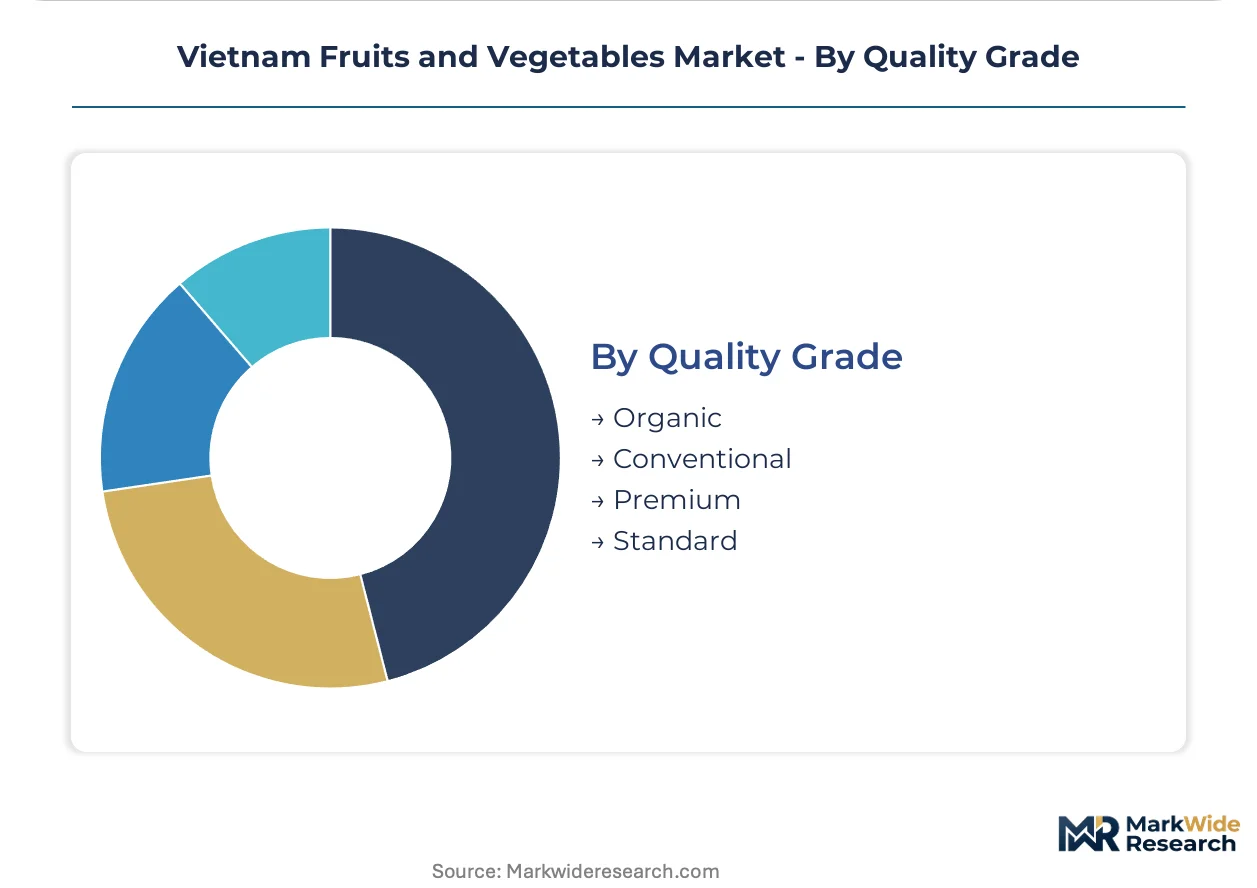
- Organic:Certified operations under EU organic or USDA NOP standards occupy under 2% of cultivated area but command 40-60% price premiums in German and Dutch retail. Lam Dong and Dak Lak highland farms dominate this tier due to lower pest pressure reducing conversion costs.
- Conventional:Standard pesticide-managed production serves domestic mass retail and food service with minimal certification burden. This tier captures 70% of national output volume.
- Premium:Export-grade stone fruits and berries meeting cosmetic and Brix specifications without full organic certification.
- Standard:Volume-grade produce for institutional catering and wet-market channels with basic sorting but no residue testing.
Conventional grade leads volumes today; organic is gaining share fastest through EU-Vietnam Free Trade Agreement tariff advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward provinces where compliance costs align with certification requirements for destination markets. Vietnam's Ministry of Agriculture and Rural Development enforces tiered pesticide residue standards that create cost-of-compliance gaps between Mekong Delta commercial farms and Central Highlands emerging operations.
Mekong Delta
Intensive horticulture clusters in Long An and Tien Giang provinces supply year-round dragon fruit and passion fruit to export channels. Vietnam's Ministry of Agriculture and Rural Development operates regional plant protection laboratories in Can Tho to accelerate phytosanitary certification for EU-bound shipments. Commercial farms around Vinh Long deploy controlled-environment acreage to lock in supermarket contracts across southern provinces.
Southeast Region
Ho Chi Minh City anchors domestic demand through convenience store networks expanding fresh-format retail floor space. The national food safety authority coordinates with municipal health departments to enforce VietGAP standards in urban distribution hubs. Farm-gate sourcing agreements in Cu Chi and Hoc Mon districts bypass traditional wholesale layers for restaurant and hotel chains.
Central Highlands
Lam Dong and Dak Lak provinces offer highland terrain for temperate vegetable cultivation targeting domestic premium tiers. Lower pest pressure reduces conversion costs for organic certification under EU-equivalent standards. Da Lat greenhouse clusters ship carrots to Japanese importers under strict diameter and sugar-content specifications.
Red River Delta
Hanoi households drive e-commerce subscription box models for leafy greens through platforms connecting to northern growing regions. The national food safety authority coordinates cross-provincial traceability requirements for supermarket chains expanding into Bac Ninh and Hai Duong. Direct farm contracts with VinMart and Co.opmart consolidate supplier bases among commercial operations with cold-chain capabilities.
Vietnam Fruits and Vegetables Market Competitive Landscape
Mekong Delta producers anchor one tier; Central Highlands specialists hold emerging positions in premium-grade supply. The vendor base splits between integrated agricultural corporations with captive cold-chain networks and farm-gate sourcing specialists bypassing wholesale intermediaries. Three archetypes dominate: integrated operators controlling post-harvest infrastructure, processing-focused exporters converting fresh produce into value-added formats, and retail-facing distributors with direct supermarket contracts. Competitive moves concentrate on backward integration into farm-gate sourcing and consolidation of supplier bases to meet tightening traceability requirements.
Within the integrated operator tier, U&I Agricultural Corporation and Tien Thinh Group exemplify archetypes of cold-chain network control and direct sourcing respectively. Nafoods Group occupies a position representing processing-focused export orientation. These entities illustrate how market participants structure around either infrastructure ownership or processing specialization to defend margin positions under tightening phytosanitary protocols.
| Leading Market Players |
|---|
| U&I Agricultural Corporation |
| Tien Thinh Group |
| Hoang Anh Gia Lai Group |
| Vina T&T |
| Hoa Phat Agriculture Development |
| Nafoods Group |
| Hoang Anh Gia Lai Agricultural |
| Kingfoodmart |
| Antesco |
| Others |
Value Network & Pricing Analysis
Controlled-environment agriculture expansion across Long An and Tien Giang provinces simultaneously compresses per-unit cultivation costs and consolidates supply power among capitalized commercial farms. This production-method transition collapses traditional smallholder price-setting authority while concentrating procurement leverage with supermarket chains and export processors.
Pricing Analysis
Direct farm-gate contracting discounts eliminate traditional wholesale markups for volume buyers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and cold-chain capability. Cost compression in the standard tier is intensifying because imported frozen substitutes from Thailand and China undercut domestic fresh supply in institutional catering. Wet-market smallholders exhibit highest price sensitivity; EU-bound exporters with GlobalGAP certification face least.
Supply Chain Analysis
Regional distribution centers in Can Tho and Ho Chi Minh City operate hub-and-spoke patterns radiating into Mekong Delta growing clusters. Supply concentrates in Vietnam's southern provinces, with emerging highland capacity in Lam Dong and Dak Lak. The chain draws from fertilizer and agrochemical inputs, greenhouse infrastructure, and cold-chain equipment. Single-source vulnerability sits with phytosanitary certification capacity at Vietnam's plant protection department. Distribution runs through supermarket direct contracts, export packing houses, and e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's fruits and vegetables market compounds steadily as EU-Vietnam Free Trade Agreement tariff elimination locks in export demand growth.
For Market Incumbents: Anticipate tightening pesticide residue enforcement by Vietnam's Ministry of Agriculture and Rural Development through backward integration into documented integrated pest management farms. Consolidate supplier bases to 50-100 core operations per chain to meet traceability requirements. Prioritize cold-chain capacity expansion in Vinh Long and Can Tho distribution nodes. For New Entrants and Emerging Players: Begin with organic certification conversion in Lam Dong and Dak Lak highlands where lower pest pressure reduces compliance costs. Target e-commerce subscription box channels in Hanoi and Da Nang where farm-branded packaging bypasses wholesale intermediaries. Pursue direct-to-consumer platforms as the most penetrable entry vector. For Investors and Strategic Acquirers: Valuations sit cheapest among smallholder cooperatives struggling with blockchain traceability deployment. Long-term viability rests on EU market access retention through accredited laboratory testing infrastructure. Watch phytosanitary certification backlog resolution as the inflection signal for export channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Gate Sourcing | Bypasses wholesale intermediaries and secures traceability documentation for EU buyers. |
| Cold-Chain Network Expansion | Extends shelf life for dragon fruit exports to Middle Eastern markets through ethylene scrubbing integration. |
| Controlled-Environment Acreage Buildout | Locks in year-round supply contracts with VinMart and Co.opmart across southern provinces. |
| Organic Certification Program | Captures 40-60% price premiums in German and Dutch retail under EU-equivalent standards. |
| E-Commerce Platform Partnership | Connects Mekong Delta farms to Hanoi households through Tiki and Shopee subscription models. |
Research Methodology
Multiple input streams — primary interviews, customs and trade databases, regulatory filings — were reconciled to construct market estimates. Conversations with commercial farm operators, supermarket procurement managers, export packing house supervisors, and plant protection department officials informed demand-side and supply-side dynamics. Secondary validation drew from Vietnam's Ministry of Agriculture and Rural Development publications, EU phytosanitary entry notifications, and supermarket chain sustainability reports. Bottom-up cultivation area and yield estimates were triangulated against top-down export value flows.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end user category, and quality grade tier. CAGRs were derived from trend extrapolation of historical export volumes and domestic retail expansion rates. Forecast inputs incorporated EU-Vietnam Free Trade Agreement tariff phase-out schedules and controlled-environment agriculture adoption curves.
Several conditions sit outside the modeled scope, including weather-induced crop failures, abrupt phytosanitary protocol changes in destination markets, and currency volatility effects on export competitiveness. Forecasts reflect documented assumptions about certification timeline compression and cold-chain infrastructure buildout. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
North Africa Table Olives Market
Fruits and Vegetables
Dried Figs Market
Fruits and Vegetables
Mulberry Market
Fruits and Vegetables
Dehydrated Green Beans Market
Fruits and Vegetables
Global Organic Fruits and Vegetables Market
Fruits and Vegetables
Global Jalapeno Pepper Market
Fruits and Vegetables
Avocado-Based Products Market
Fruits and Vegetables
Apple Concentrate Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
North America Fruits & Vegetables Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Dried Grapes Market
Fruits and Vegetables
Europe Freeze-Dried Fruits and Vegetable Market
Fruits and Vegetables
Jujube Market