
 Kuwait Dairy Products Market | 2026-2036
Kuwait Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Dairy Products Market Foresight
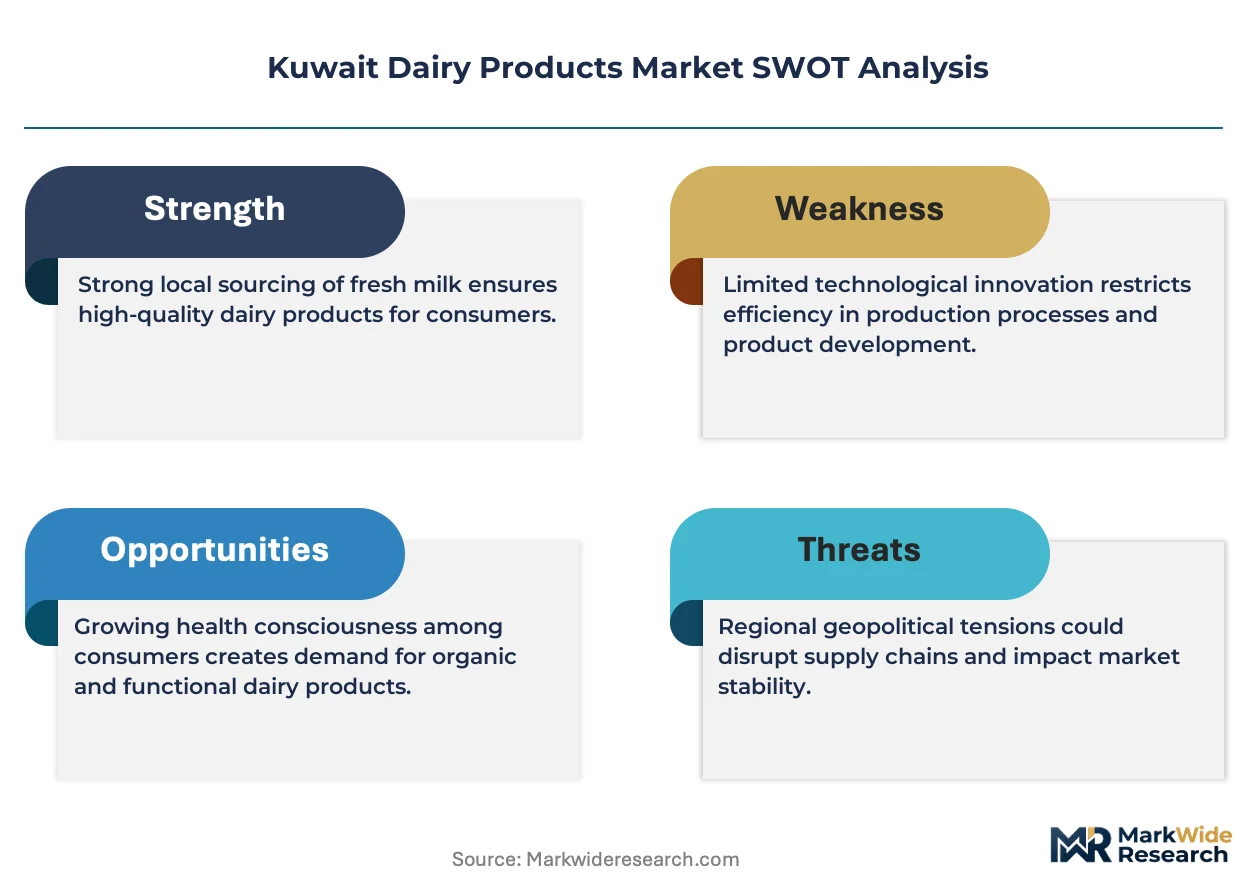
Plant-based fat blends is rebalancing traditional butter formulations as manufacturers seek cost stability and halal-certification alignment. Almarai Company leverages backward integration into feed production and captive dairy farming to secure raw milk supply across the Gulf. Al-Othman Group Holding Co. (NADA Dairy) anchors its position through chilled distribution networks that dominate modern trade shelves in Kuwaiti supermarkets. Kuwait Dairy Co. differentiates via localized flavor variants targeting regional palate preferences in labneh and strained yogurt.
Dairy products encompass fluid milk, fermented goods, and fat-based derivatives processed through pasteurization, homogenization, and bacterial culture fermentation, with standardized fat content ranging from skim (0.5%) to full-cream (3.5%) and shelf-life parameters dictating chilled or UHT pathways. These products serve nutritional, culinary, and industrial formulation functions across household and commercial food preparation. Milk retains the largest volume share in Kuwait due to per-capita consumption habits and school nutrition program inclusion, while yogurt generates premium margin pools through probiotic positioning and single-serve packaging formats. The food service end-user channel shows structural momentum as restaurant chains and café operators expand dairy-forward menu offerings.
Kuwait's Public Authority for Food and Nutrition (PAFN) enforces GSO technical regulations that mandate Salmonella and E. coli absence in fresh dairy, while the Ministry of Commerce and Industry oversees import licensing for foreign dairy brands entering the Kuwaiti market. These frameworks elevate compliance costs for new entrants but reinforce quality benchmarks that benefit established domestic producers with in-house testing laboratories. Stakeholders must monitor evolving Gulf Cooperation Council harmonization efforts on dairy labeling and origin disclosure requirements.
Market Dynamics
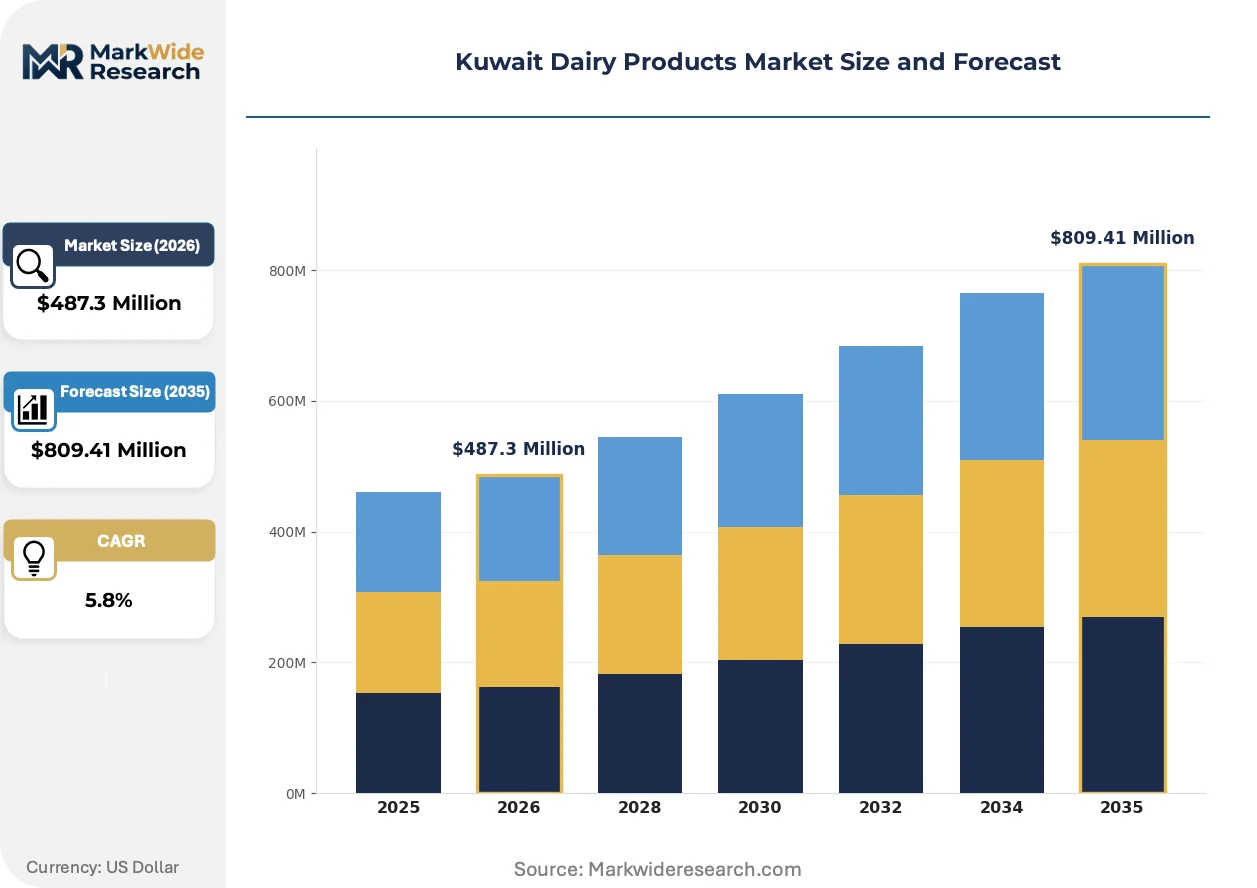
Chilled distribution infrastructure is consolidating procurement power around vertically integrated domestic producers who control farm-to-shelf cold chains, compressing margin capture for import-dependent competitors and reshaping shelf-space negotiations in Kuwaiti retail.
Growth Catalysts
- School nutrition program inclusion:Government-mandated milk distribution in public education institutions locks in baseline fluid milk offtake and creates predictable institutional demand pipelines.
- GSO 1016/2015 microbiological standards:Mandatory pathogen testing protocols elevate quality benchmarks that favor domestic producers with in-house laboratory capabilities over foreign entrants facing compliance delays.
- Food service channel expansion:Café and restaurant chains in Kuwait City and Hawalli Governorate are expanding dairy-forward menu offerings, driving premium SKU procurement.
Market Restraints
- Feed input cost volatility:Alfalfa and soybean meal prices fluctuate with global commodity markets, squeezing raw milk production economics for domestic dairy farming operations.
- Fresh milk supply concentration:Captive dairy farming operations controlled by major integrated producers limit independent processor access to locally sourced raw milk.
- Plant-based fat substitution:Palm and coconut oil blends are displacing butter fat in industrial bakery applications, eroding traditional dairy fat demand.
Strategic Opportunities
- Ahmadi and Jahra Governorate retail penetration:Modern trade infrastructure remains underdeveloped in these peripheral regions relative to Kuwait City, creating whitespace for chilled distribution network expansion.
- Probiotic strain differentiation:Fermented dairy with documented gut health claims commands shelf price premiums in pharmacy and health-focused retail channels.
- Single-serve packaging format innovation:Portion-controlled yogurt and labneh products align with on-the-go consumption patterns in office and school environments.
Industry Challenges
- Cold chain technician scarcity:Specialized refrigeration maintenance and HACCP compliance auditing skills are concentrated among a limited pool of certified professionals.
- Halal certification timeline compression:GSO harmonization requirements for slaughter-free dairy processing documentation are extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Dairy Products Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Food Service Packaging Type: Bottles, Tetra Packs, Jars, Pouches End User: Households, Restaurants, Cafés, Educational Institutions |
| Companies Covered | Almarai Company, Al-Othman Group Holding Co. (NADA Dairy), Kuwait Dairy Co., Al Faisaliah Group, SADAFCO, Kuwait United Dairy Company, Kuwait Danish Dairy, KuwaitAgro Co., Al Safat Fresh Dairy Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Dairy Products Market Shifts & Advancements
Automation and digital traceability systems are penetrating dairy processing floors, enabling real-time quality monitoring that reduces batch rejection rates and strengthens compliance documentation for regulator audits.
Extended shelf-life processing technology is modularizing production line configurations, allowing mid-scale Kuwaiti processors to switch between fresh pasteurized and UHT pathways on shared equipment. Food service buyers in the hospitality sector are adopting these flexible supply contracts to balance working capital against spoilage risk. The structural consequence is compressing minimum efficient scale thresholds and enabling regional processor entry.
GSO technical regulations on dairy labeling and origin disclosure are tightening enforcement timelines, requiring manufacturers to retrofit packaging lines with automated coding systems. Domestic producers with captive printing capabilities are absorbing compliance costs faster than importers reliant on external label suppliers. Fresh dairy categories face the steepest retrofit burden due to shorter production cycles.
Buyer concentration in modern trade retail is consolidating category management authority around hypermarket and supermarket chains in Salmiya and Shuwaikh. Traditional independent grocers are losing assortment influence as centralized procurement teams dictate shelf resets and promotional calendars. This shift is most visible in yogurt and labneh segments where planogram compliance determines distribution access.
Kuwait Dairy Products Market Segmentation
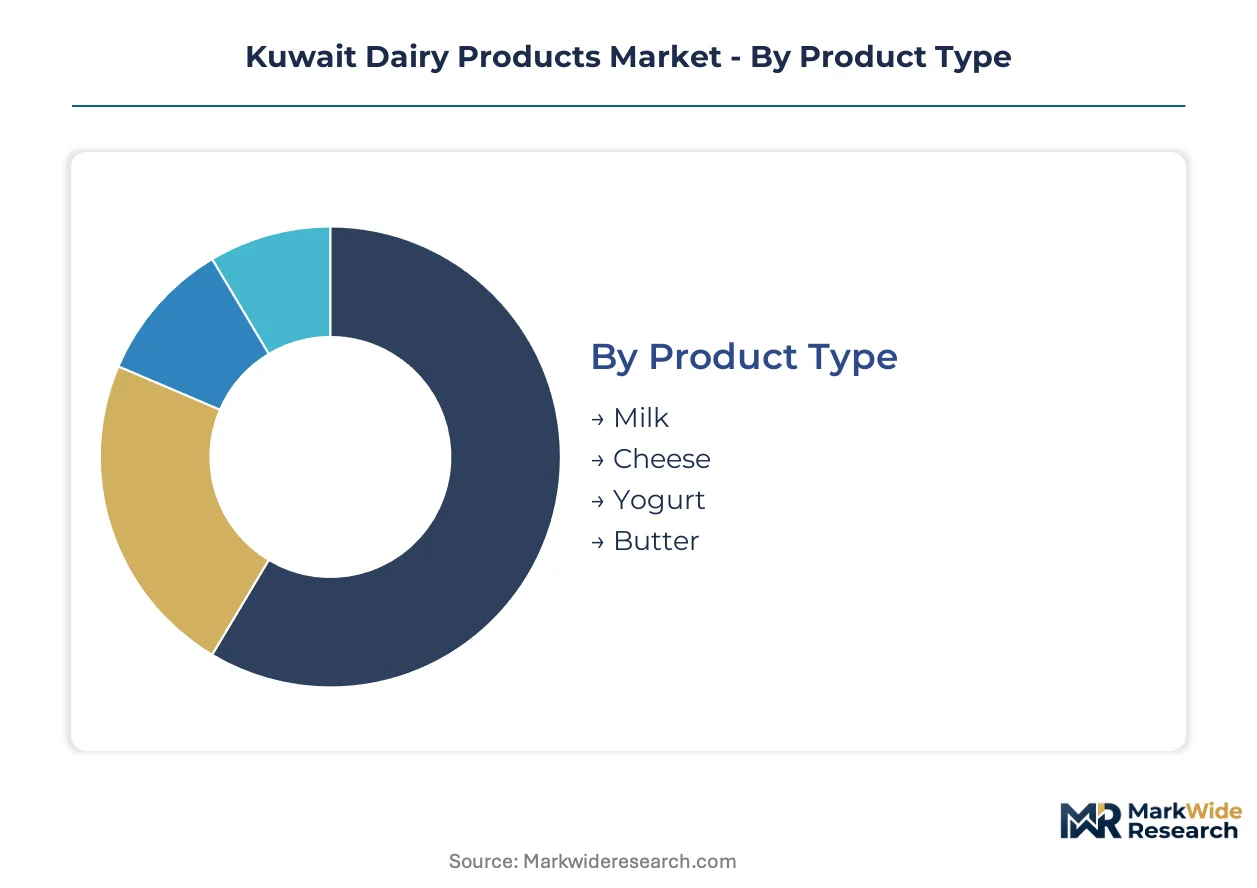
Kuwait's dairy market fragments across four distinct axes that shape procurement patterns and margin capture. Product specifications determine shelf-life logistics and cold chain intensity. Distribution channels concentrate purchasing power differently across Kuwait City and peripheral governorates.
Product Type:
Technical specifications around fat content and fermentation pathways define processing economics and storage requirements for each dairy category.
- Milk:Fluid milk spans standardized fat tiers from skim through full-cream, with UHT processing enabling ambient distribution versus chilled pasteurized variants requiring continuous refrigeration. Per-capita consumption in Kuwait City households and school nutrition program procurement lock in predictable baseline volumes, though feed input cost volatility squeezes raw milk production margins for domestic farming operations.
- Yogurt:Fermented dairy with defined bacterial culture specifications commands premium positioning through probiotic health claims and single-serve packaging formats. Pharmacy and health-focused retail channels in Salmiya concentrate demand for documented gut-health strains, while food service buyers adopt flexible supply contracts balancing working capital against spoilage risk.
- Cheese:Processed and natural cheese variants serve culinary preparation and direct consumption functions across household and commercial segments.
- Butter:Fat-based derivatives face displacement pressure from plant-based alternatives in industrial bakery applications.
Mature deployment sits with Milk. Newer deployment is concentrated in Yogurt.
Distribution Channel:
Channel economics vary sharply by cold chain requirements and buyer concentration, reshaping shelf-space negotiations across Kuwait's retail landscape.
- Supermarkets:Modern trade chains in Shuwaikh and Salmiya centralize category management authority, with centralized procurement teams dictating planogram compliance and promotional calendars that determine distribution access for yogurt and labneh segments.
- Food Service:Café and restaurant chains in Kuwait City and Hawalli Governorate are expanding dairy-forward menu offerings, driving premium SKU procurement through flexible supply contracts.
- Online Retail:Digital platforms are gaining traction for subscription-based milk delivery and bulk yogurt purchases.
- Convenience Stores:Independent grocers are losing assortment influence as hypermarket consolidation accelerates.
Volume concentrates in Supermarkets. Margin expansion is climbing the fastest in Food Service.
Packaging Type:
Material specifications and barrier properties determine shelf-life extension capabilities and logistics economics across the supply chain.
- Tetra Packs:Aseptic carton technology enables ambient distribution for UHT milk, reducing cold chain burden and extending reach into Jahra and Ahmadi Governorates where chilled infrastructure remains underdeveloped.
- Bottles:HDPE and PET formats dominate fresh pasteurized milk distribution, requiring continuous refrigeration but offering consumer transparency on product quality.
- Jars:Glass containers preserve labneh and strained yogurt texture while supporting premium positioning in modern trade.
- Pouches:Flexible packaging reduces material costs for portion-controlled yogurt products targeting on-the-go consumption.
Standard deployment sits with Bottles. Expansion deployment is concentrated in Tetra Packs.
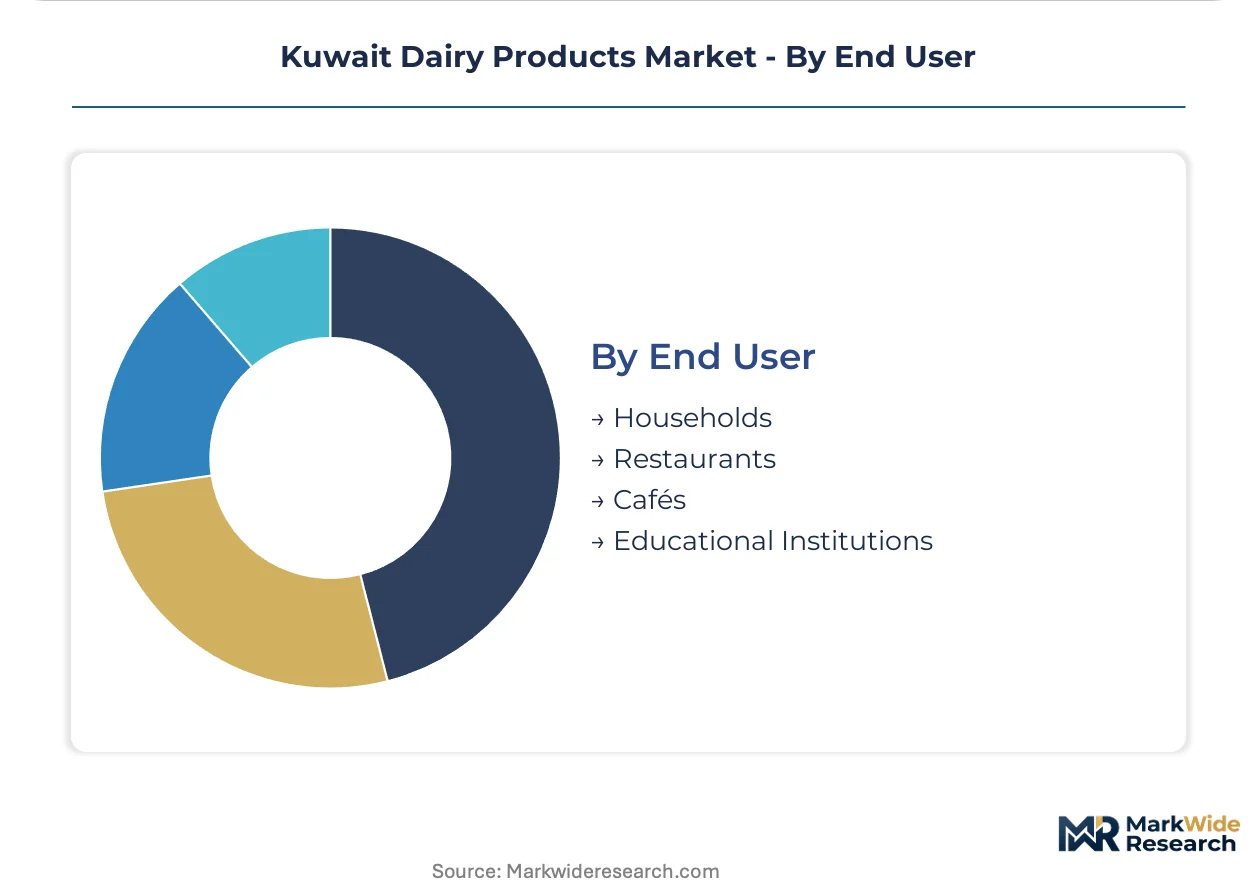
End User:
Consumption context shapes product format preferences, purchase frequency, and price sensitivity across institutional and individual buyers.
- Households:Family-size packaging and value-oriented pricing dominate residential procurement in Kuwait City and surrounding governorates, with per-capita consumption habits sustaining milk as the largest volume category.
- Restaurants:Commercial food preparation demands industrial-format dairy with consistent fat content for recipe standardization.
- Cafés:Specialty coffee culture drives demand for premium milk variants with specific foaming properties.
- Educational Institutions:Government-mandated milk distribution programs create predictable institutional demand pipelines with locked-in procurement specifications.
Established demand sits with Households. Emerging demand is gaining share fastest in Cafés.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Kuwait City and its surrounding governorates where retail infrastructure and food service density remain highest. Peripheral regions present whitespace for chilled distribution network expansion. The national food safety regulator enforces Gulf Standardization Organization standards that mandate pathogen testing and labeling compliance across all sub-regions.
Kuwait City
School nutrition program procurement and hypermarket consolidation drive fluid milk and yogurt volumes. The Public Authority for Food and Nutrition enforces GSO microbiological standards that elevate quality benchmarks. Salmiya and Shuwaikh industrial zones concentrate dairy processing facilities and modern trade distribution hubs.
Hawalli Governorate
Café and restaurant chains expand dairy-forward menu offerings, creating premium SKU demand pipelines. Ministry of Commerce and Industry import licensing frameworks apply uniformly across commercial food service operations. The governorate's retail corridors host centralized procurement teams dictating planogram compliance for yogurt and labneh segments.
Ahmadi Governorate
Modern trade infrastructure remains underdeveloped relative to Kuwait City, creating distribution whitespace. GSO technical regulations on dairy labeling and origin disclosure extend enforcement timelines uniformly. Industrial zones near Ali Al Salem host emerging chilled logistics facilities serving peripheral retail penetration.
Jahra Governorate
Population dispersion and lower retail density constrain fresh pasteurized milk distribution economics. National feed input cost volatility affects domestic dairy farming operations regardless of sub-region. UHT processing capabilities enable ambient distribution through Tetra Pack formats where cold chain infrastructure remains limited.
Kuwait Dairy Products Market Competitive Landscape
Backward integration into captive dairy farming dominates the current landscape as producers secure raw milk supply against import dependency. The market structure consolidates around vertically integrated domestic operators who control farm-to-shelf cold chains, compressing margin capture for import-reliant competitors. Three strategic archetypes emerge: Gulf-based integrated agribusiness conglomerates, Kuwaiti family-owned dairy specialists, and regional import-dependent distributors. Capacity expansion in chilled distribution networks and strategic partnerships with modern trade retailers constitute the dominant competitive moves reshaping shelf-space negotiations.
Within the integrated agribusiness tier, Almarai Company and Al-Othman Group Holding Co. exemplify archetypes built on upstream control over feed production and captive farming operations. Almarai, a Riyadh-based joint stock company, anchors regional scale through backward integration strategies spanning multiple Gulf markets. Al-Othman Group Holding Co., operating NADA Dairy, represents the Kuwaiti family-owned specialist model with concentrated domestic distribution infrastructure. Kuwait Dairy Co. occupies a position emphasizing localized product differentiation rather than vertical integration depth.
| Leading Market Players |
|---|
| Almarai Company |
| Al-Othman Group Holding Co. (NADA Dairy) |
| Kuwait Dairy Co. |
| Al Faisaliah Group |
| SADAFCO |
| Kuwait United Dairy Company |
| Kuwait Danish Dairy |
| KuwaitAgro Co. |
| Al Safat Fresh Dairy Co. |
| Others |
Supply & Pricing Matrix
GSO 1016/2015 microbiological standards gate both qualified supply and premium-tier pricing access in Kuwait's dairy market. Domestic producers with in-house laboratory capabilities capture shelf price premiums while import-dependent competitors absorb compliance delays and margin compression.
Pricing Analysis
Fluid milk trades on thin margins driven by school nutrition program procurement volume, while yogurt and probiotic SKUs command premium positioning through documented health claims and single-serve formats. Three-tier pricing structure across premium, standard, and economy levels separates GSO-certified domestic production from import-dependent mid-tier offerings and private-label economy alternatives. Cost compression in standard-tier fluid milk is intensifying because feed input cost volatility squeezes raw milk production economics. Households in Kuwait City exhibit highest price sensitivity, while food service buyers in Hawalli Governorate prioritize consistency over unit cost.
Supply Chain Analysis
Regional distribution centers in Shuwaikh and Salmiya industrial zones anchor hub-and-spoke chilled logistics patterns radiating into peripheral governorates. Geographic supply concentrates in Saudi Arabia through Almarai's backward integration, Kuwait via NADA Dairy's captive farming, and UAE re-export channels serving import-dependent processors. Raw material dependencies rest on alfalfa and soybean meal feed inputs, Tetra Pack aseptic carton materials, and bacterial culture strains for fermentation. Single-source vulnerability in locally sourced raw milk supply elevates procurement risk for independent processors lacking captive dairy farming. Distribution runs through vertically integrated cold chains controlled by domestic producers, compressing shelf-space access for import-reliant competitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fresh milk supply concentration around captive dairy farming operations props pricing power for integrated incumbents, creating structural barriers for competitors dependent on imported raw material or finished goods.
For Market Incumbents: Cement farm-to-shelf cold chain dominance through capacity addition in Ahmadi Governorate distribution infrastructure, insulating against plant-based fat substitution threats in industrial bakery channels. Deepen upstream control over feed production to buffer alfalfa and soybean meal price volatility squeezing raw milk margins. Prioritize GSO certification investment to extend compliance cost advantages over import-dependent challengers facing extended product launch cycles.
For New Entrants and Emerging Players: Capture whitespace in Jahra Governorate UHT milk distribution where cold chain infrastructure gaps favor ambient-stable Tetra Pack formats over fresh pasteurized alternatives. Target pharmacy and health-focused retail channels in Salmiya for probiotic strain differentiation with documented gut health claims commanding shelf price premiums. Deploy subscription-based online retail go-to-market angles for bulk yogurt purchases bypassing hypermarket planogram gatekeepers.
For Investors and Strategic Acquirers: GSO harmonization timeline extensions on halal certification documentation are the leading indicator that regulatory compliance capabilities will separate viable acquisition targets from stranded assets. Long-term viability centers on vertically integrated operators with captive dairy farming and in-house laboratory testing infrastructure. Watch cold chain technician scarcity as the inflection signal for operational risk accumulation in mid-scale processors lacking certified maintenance capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Chilled Distribution Network Expansion | Extends farm-to-shelf control into underdeveloped Ahmadi and Jahra Governorate retail corridors. |
| Probiotic Strain Differentiation | Commands pharmacy channel price premiums through documented gut health claims in Salmiya. |
| Backward Integration into Feed Production | Secures raw milk supply economics against global alfalfa and soybean meal volatility. |
| Single-Serve Packaging Innovation | Aligns portion-controlled labneh with on-the-go consumption in Kuwait City office environments. |
| GSO Compliance Infrastructure Investment | Accelerates product launch cycles versus import-dependent competitors facing documentation delays. |
Research Methodology
Independent corroboration across dairy processing executives, cold chain logistics managers, modern trade category buyers, and PAFN regulatory officials underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with Kuwaiti supermarket procurement teams and food service operators with secondary validation through GSO technical regulations, Ministry of Commerce import licensing records, and Gulf agribusiness SEC disclosures. Bottom-up demand modeling from household consumption patterns and institutional procurement specifications triangulates against top-down value chain analysis.
Comparable-period anchoring to historical consumption baselines shaped the projection methodology across the analysis window. Segmentation dimensions span product type, distribution channel, packaging format, and end-user context with regional governorates as a geographic overlay. CAGRs derive from trend extrapolation moderated by feed input cost elasticity and cold chain infrastructure penetration assumptions. Forecast inputs incorporate school nutrition program procurement specifications and food service channel expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GSO regulatory harmonization timelines and global commodity feed price cycles. Outputs reflect documented assumptions around captive dairy farming capacity expansion and halal certification processing speeds. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Skimmed Milk Market
Dairy Products
Sheep Milk Market
Dairy Products
South America Dairy Protein Market
Dairy Products
Europe Dairy Market
Dairy Products
Cheese Crumbles Market
Dairy Products
Germany Casein and Caseinates Market
Dairy Products
Global Dairy Cream Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
United States Dairy Desserts Market
Dairy Products
Sweetened Condensed Milk Market
Dairy Products
Evaporated Milk Market
Dairy Products
Organic Milk Powder Market
Dairy Products
Organic Dairy Market
Dairy Products
Global Cultured Dairy Products Market
Dairy Products
Sweet Whey Market
Dairy Products
North America Cheese Market