
 Air and Gas Compressor Market | 2026-2036
Air and Gas Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Air and Gas Compressor Market Intelligence
Demand from smaller, service-focused buyers like construction firms is rotating market share away from large-scale capital projects by energy producers. Atlas Copco AB leverages its extensive service network to capture this evolving customer base. Ingersoll Rand sustains its market position through a diversified portfolio serving both large and small end-users. Kaeser Kompressoren differentiates with its focus on energy-efficient, turnkey solutions for mid-sized industrial clients.
An air and gas compressor is a mechanical device designed to increase the pressure of a gas by reducing its volume, often achieving specific pressure ratings measured in pounds per square inch (PSI). These machines are fundamental for applications ranging from powering pneumatic tools in manufacturing plants to handling process gases in petrochemical facilities. Rotary screw compressors dominate the general industrial segment due to their reliability and cost-effectiveness. The oil-free technology segment, however, represents the fastest-growing category, driven by stringent quality requirements in food packaging and pharmaceutical production.
Energy efficiency and environmental standards, enforced by bodies like the US Environmental Protection Agency (EPA) and through frameworks like the EU's F-Gas Regulation, are shaping product development. Concurrently, ISO 8573 standards for air purity directly influence compressor selection in sensitive applications. Navigating the transition to low-GWP refrigerants and integrating advanced variable speed drive technologies are critical decisions for equipment manufacturers and end-users alike.
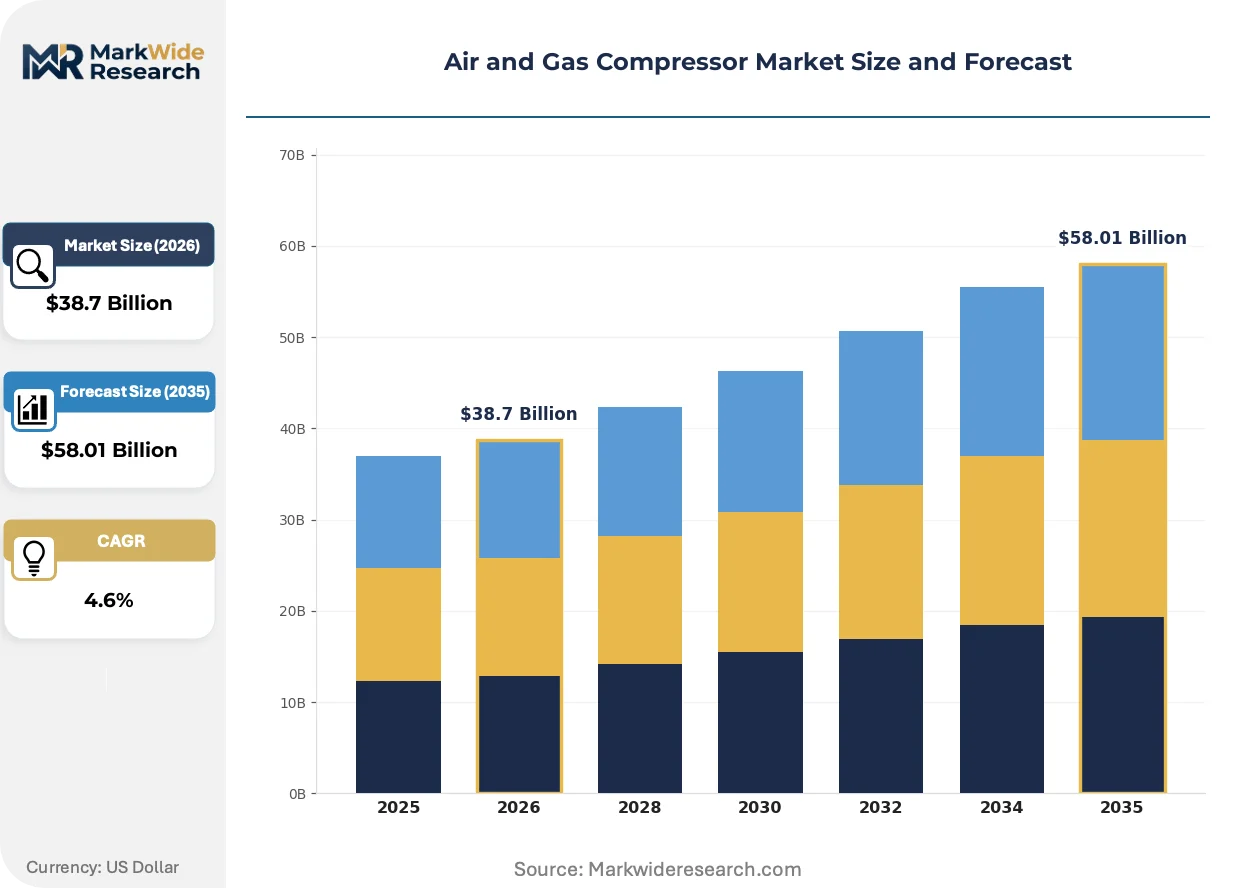
Market Dynamics
The fundamental dynamic shaping the compressor market is the tension between stringent energy efficiency mandates and the high capital cost of advanced equipment. End-users face pressure from regulations like the EU's F-Gas Regulation and standards from the US EPA to upgrade, while simultaneously managing investment cycles.
Growth Catalysts
- Industrial Expansion in China:Continued investment in manufacturing and infrastructure projects across China concentrates demand for a high volume of industrial compressors, particularly rotary screw types for general factory applications.
- Food Safety Standards:Heightened quality requirements in food and beverage packaging, driven by standards like ISO 8573 for air purity, are accelerating the switch to premium-priced oil-free compressor technology.
- Environmental Regulations:The EU's F-Gas Regulation is forcing the phase-out of high-GWP refrigerants in air dryers, creating a replacement cycle and pushing development of equipment compatible with new, compliant cooling agents.
Market Restraints
- High Capital Outlay:The significant upfront investment required for energy-efficient technologies, such as compressors with integrated variable speed drives (VSDs), deters adoption among smaller enterprises with constrained capital budgets.
- Input Material Volatility:Price fluctuations in specialty steels and rare earth magnets, essential for high-efficiency motors, create margin pressure and introduce uncertainty into production planning for manufacturers.
- Technical Hurdles for Alternatives:Some low-GWP refrigerants exhibit reduced performance or require higher operating pressures, posing design and reliability challenges for equipment intended for high-ambient-temperature environments.
Strategic Opportunities
- Predictive Maintenance Services:The integration of IIoT sensors and cloud analytics into compressors opens new revenue streams from subscription-based remote monitoring and predictive maintenance services, increasing customer lifetime value.
- Green Energy Infrastructure:Emerging applications in green hydrogen production, transportation, and carbon capture projects create a new, high-growth market for specialized, high-pressure gas compressors.
- Service-Led Models for SMEs:A shift away from large capital projects allows for a focus on smaller, service-oriented buyers in sectors like construction and automotive repair, captured through extensive dealer and service networks.
Industry Challenges
- Technician Skill Gaps:A shortage of service technicians proficient in both traditional mechanical engineering and the advanced electronic controls of modern VSD compressors hampers maintenance and after-sales support capabilities.
- Legacy System Integration:Integrating new, digitally-enabled smart compressors into existing factory automation systems and legacy compressed air networks often presents significant technical complexity and interoperability issues.
- Compliance Documentation:Navigating the complex and fragmented landscape of global and regional certifications for energy performance and air purity, such as ISO 8573, adds significant administrative overhead and testing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air and Gas Compressor Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Rotary Screw, Centrifugal, Axial Technology: Oil-Lubricated, Oil-Free, Variable Speed Drive, Magnetic Bearing Application: Petrochemical Processing, Food Packaging, HVAC Systems, Water Treatment End User Industry: Manufacturing Plants, Construction Firms, Energy Producers, Chemical Facilities |
| Companies Covered | Atlas Copco AB, Ingersoll Rand, Ariel Corporation, ELGi Equipments Limited, Hitachi Ltd., Siemens AG, General Electric Company, Burckhardt Compression Holding AG, Kaeser Kompressoren, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air and Gas Compressor Market Strategic Shifts & Innovations
Digitalization and sustainability are the twin forces guiding product innovation and procurement behavior. The drive for lower energy consumption is matched by a growing preference for service models that guarantee performance and uptime, shifting focus from capital expenditure to operational expenditure.
Variable Speed Drive (VSD) technology enables a compressor to precisely match its motor speed and power consumption to fluctuating air demand. Manufacturing facilities and general industrial users are adopting VSDs to reduce energy waste. This on-demand performance capability is supplanting the inefficient fixed-speed, load-unload cycle of older equipment, directly lowering a facility's operational electricity costs.
The EU's F-Gas Regulation mandates a progressive phase-down of refrigerants with high Global Warming Potential (GWP). This directly forces equipment manufacturers to redesign systems and qualify new, climate-friendlier refrigerants. The refrigerated air dryer segment is most affected, compelling operators in Europe to either replace aging equipment or undertake complex retrofits to remain compliant.
A transition toward outcome-based contracts for compressed air supply is gaining momentum, challenging traditional equipment sales. This "Air-as-a-Service" model, where a provider guarantees air quality and uptime for a monthly fee, displaces the capital expenditure burden from the end-user. The model sees its strongest uptake in the pharmaceutical and food packaging sectors, where air purity and system reliability are critical operational priorities.
Air and Gas Compressor Market Segmentation
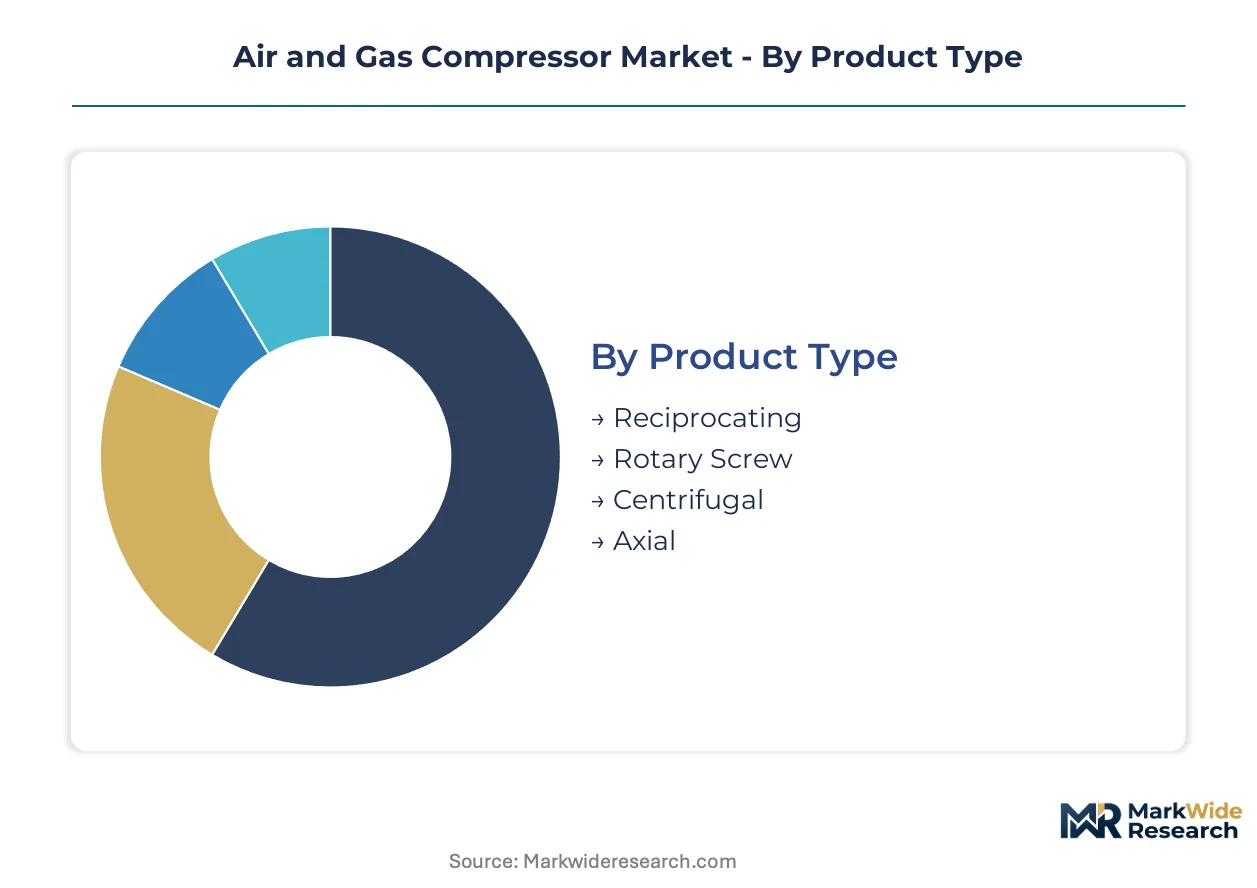
The Air and Gas Compressor Market exhibits diverse operational requirements across various industries. Understanding these distinct segments clarifies the specific technological demands and procurement priorities driving equipment choices. This detailed segmentation highlights where innovation and investment are currently concentrated.
Product Type:
The product type segment faces substitution pressure from alternative gas compression technologies and evolving end-user preferences for reliability and efficiency. Each design offers distinct advantages for specific operational envelopes.
- Rotary Screw:These compressors use two meshing helical rotors to compress gas, offering continuous flow and high efficiency for industrial applications. Demand concentrates in general manufacturing plants across China, driven by ongoing industrial expansion and a need for reliable, cost-effective air supply.
- Centrifugal:Operating at high speeds, these dynamic compressors use a rotating impeller to accelerate gas, converting velocity into pressure. Petrochemical processing facilities in the Middle East drive demand for these large-capacity units, requiring high-volume, oil-free air for critical processes.
- Reciprocating:These positive displacement compressors use pistons for gas compression, suitable for high-pressure applications in smaller industrial settings.
- Axial:Axial compressors achieve compression through rotating and stationary blades, used in high-volume, continuous flow applications like gas turbines and large industrial processes.
Reciprocating compressors anchor the volume base while Rotary Screw models gain share at the steepest rate.
Technology:
Technology segmentation reflects varying capital expenditure levels and operational cost structures, with advanced solutions commanding a premium for enhanced efficiency and performance. End-users balance upfront investment against long-term energy savings.
- Oil-Free:These compressors deliver compressed air without oil contamination in the compression chamber, vital for sensitive applications. Food packaging and pharmaceutical production in Europe drive demand, where ISO 8573 air purity standards are strictly enforced.
- Variable Speed Drive:VSD technology adjusts motor speed to match air demand, significantly reducing energy consumption compared to fixed-speed units. Manufacturing facilities globally adopt VSDs to lower operational electricity costs and meet energy efficiency mandates.
- Oil-Lubricated:These traditional compressors use oil for sealing and cooling, suitable for general industrial needs where air purity is less critical.
- Magnetic Bearing:This advanced technology eliminates friction, offering ultra-efficient, oil-free operation for specialized, high-performance applications.
Oil-Lubricated technologies maintain a broad installed base, but Variable Speed Drive solutions are expanding most quickly.
Application:
Application segmentation highlights the specific operational environments and gas purity requirements that dictate compressor design and selection. The criticality of the compressed gas varies significantly across these diverse uses.
- Food Packaging:Compressors in this sector provide clean, oil-free air for processes like product handling, nitrogen generation, and packaging. Heightened food safety standards, particularly in North America, necessitate ISO 8573 Class 0 air, driving demand for premium oil-free units.
- Petrochemical Processing:These applications require robust compressors for handling process gases, inerting, and utility air in harsh environments. Industrial expansion in China and the Middle East fuels demand for high-capacity, reliable units in new and expanding chemical facilities.
- HVAC Systems:Compressors are integral to air conditioning and refrigeration, circulating refrigerants for temperature control in commercial and industrial buildings.
- Water Treatment:Compressors supply air for aeration in wastewater treatment plants and for driving filter presses in purification processes.
HVAC Systems represent a stable, mature segment, while Food Packaging applications are climbing the fastest.
End User Industry:
End-user industry segmentation reveals distinct purchasing behaviors and service requirements, ranging from large-scale capital projects to smaller, service-oriented operational needs. Each sector prioritizes different aspects of compressor performance and support.
- Manufacturing Plants:This broad category encompasses diverse industrial processes requiring compressed air for pneumatic tools, automation, and general utility. Global industrial expansion, particularly in emerging economies, drives sustained demand for robust and energy-efficient compressors.
- Construction Firms:These buyers require portable, durable compressors for powering pneumatic tools and equipment on job sites. The shift towards smaller, service-focused buyers, particularly in Europe, creates opportunities for suppliers with extensive rental and maintenance networks.
- Energy Producers:This segment uses compressors for gas transmission and process gas handling in refineries, often requiring specialized high-pressure units.
- Chemical Facilities:Compressors handle process gases, inert gases, and utility air in chemical production, demanding high reliability and often oil-free operation.
Manufacturing Plants provide the largest installed base, with Construction Firms showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global network of shipping lanes and industrial corridors underwrites the distributed demand for air and gas compressors. Diverse regulatory frameworks influence technology adoption and market growth across major manufacturing hubs and energy-producing regions. This market sees significant activity driven by industrial expansion, environmental mandates, and infrastructure development across several key economies.
China
Continued industrial expansion across China drives significant demand for industrial compressors, particularly rotary screw types. China's dual carbon goals promote the adoption of more energy-efficient equipment in manufacturing facilities. The Yangtze River Delta region, a major manufacturing hub, concentrates demand for high-volume industrial compressors.
United States
Manufacturing plants and food packaging sectors in the United States require robust compressor systems for various applications. The US Environmental Protection Agency (EPA) regulations influence the design and selection of environmentally compliant equipment. Industrial clusters across the Midwest and Southeast regions see consistent demand for advanced compressed air solutions.
Germany
German industrial sectors prioritize energy-efficient and technologically advanced compressor solutions for their mid-sized industrial clients. The European Union's F-Gas Regulation significantly impacts refrigerant choices and equipment design for air dryers in the region. The industrial heartland of North Rhine-Westphalia actively adopts variable speed drive technology to reduce operational electricity costs.
India
India's expanding manufacturing base and ongoing infrastructure projects generate substantial demand for general industrial compressors. Government initiatives, such as the Production Linked Incentive (PLI) scheme, encourage domestic manufacturing, further increasing the need for industrial equipment. Major industrial corridors near Delhi-NCR and Mumbai require high-capacity compressors for diverse factory operations.
United Arab Emirates
The petrochemical processing sector and construction firms in the United Arab Emirates drive demand for specialized, high-pressure gas compressors. National energy efficiency standards guide equipment selection in new infrastructure projects and industrial facilities. The industrial complex at Ruwais, a significant energy hub, utilizes large-scale compressors for gas processing and utility air.
Air and Gas Compressor Market Key Industry Players
Concentration sits with established global manufacturers offering comprehensive portfolios and extensive service networks. The market structure exhibits a tiered consolidation, with a few large players dominating premium segments and numerous regional specialists serving niche applications. Strategic archetypes include diversified industrial conglomerates and specialized compressor technology providers. Companies pursue portfolio diversification and geographic expansion to maintain market presence and capture emerging opportunities.
Atlas Copco AB and Ingersoll Rand represent global industrial powerhouses. These firms offer extensive product ranges and service networks across diverse end-user industries. Kaeser Kompressoren, a German-based manufacturer, exemplifies a specialist archetype, focusing on energy-efficient, turnkey solutions for mid-sized industrial clients. These leading entities anchor market share through their brand recognition and technological leadership in various compressor segments.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Ingersoll Rand |
| Ariel Corporation |
| ELGi Equipments Limited |
| Hitachi Ltd. |
| Siemens AG |
| General Electric Company |
| Burckhardt Compression Holding AG |
| Kaeser Kompressoren |
| Others |
Cost & Logistics Intelligence
Economies of scale in compressor manufacturing drive consolidation among global players, which in turn shapes price floors for high-volume units. This concentration of production capacity influences the overall pricing environment and market accessibility.
Pricing Analysis
Volume-discount tiering structures characterize pricing in the air and gas compressor market, particularly for standard industrial units. Price differentiation stems from factors like ISO 8573 air purity certification and integrated variable speed drive technology. Margins are tightening due to intense competition from regional manufacturers, especially in the general industrial segment. Smaller enterprises, such as construction firms, exhibit higher price sensitivity compared to large petrochemical facilities.
Supply Chain Analysis
China produces a significant volume of rotary screw compressors and standard components, anchoring a large portion of the global supply chain. The supply chain draws from specialty steels for high-pressure vessels and rare earth magnets essential for efficient motors. Commodity price volatility in these input materials presents a structural risk for manufacturers. Distribution runs through a dual model of direct sales to large industrial clients and extensive dealer networks serving smaller end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air and gas compressor market is entering a cyclical recovery, driven by renewed industrial expansion across emerging economies like India. This upswing presents strategic opportunities for various market participants.
For Market Incumbents: Secure long-term service contracts, especially for advanced VSD compressors, to counter margin pressure from new market entrants. Invest in R&D for next-generation low-GWP refrigerants to mitigate regulatory threats like the EU's F-Gas Regulation. Expand extensive service networks in emerging markets, leveraging existing brand recognition. Develop modular, interoperable solutions to ease legacy system integration challenges for manufacturing plants.
For New Entrants and Emerging Players: Lead with specialized, energy-efficient solutions for mid-sized industrial clients in underserved regions of Southeast Asia. Target the construction firms segment with robust, portable units bundled with flexible 'Air-as-a-Service' models. Focus on digital integration capabilities, offering cloud analytics and predictive maintenance to differentiate from traditional offerings. Penetrate the water treatment application segment by providing reliable, low-maintenance aeration compressors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized providers of oil-free and VSD compressor technologies with strong intellectual property. Long-term viability rests on firms demonstrating leadership in green energy infrastructure applications, such as hydrogen compression. Acquisition targets should possess strong regional service networks and advanced IIoT integration capabilities. The signal to watch is the accelerated adoption rate of outcome-based contracts in sensitive applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | ELGi Equipments Limited plans new manufacturing facilities to meet rising demand for rotary screw compressors in India. |
| Strategic Partnership | Atlas Copco AB forms alliances with energy producers for specialized high-pressure gas compressors in the UAE. |
| Service Network Enhancement | Ingersoll Rand invests in technician training programs to support advanced VSD compressor installations across the US. |
| Product Line Diversification | Kaeser Kompressoren develops specialized oil-free units for pharmaceutical production, meeting ISO 8573 standards. |
| Digital Integration | Hitachi Ltd. integrates IIoT sensors for predictive maintenance services, enhancing uptime for manufacturing plants. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory documents, industry association reports, and company financial disclosures. Primary interviews involved plant engineers, procurement leads at manufacturing facilities, R&D directors focused on compressor technology, and aftermarket service managers. This approach employed both bottom-up aggregation of segment data and top-down validation against overall market trends. Key insights were derived from these triangulated data points.
Segmentation dimensions modeled include product type, technology, application, end-user industry, and compressor capacity tier, all analyzed across the projection horizon. Compound annual growth rates were derived through historical trend analysis and projected demand scenarios for each segment. Forecast inputs incorporate industrial production indices from China and Europe, alongside food safety regulatory enforcement data. This framework provides a granular view of market evolution.
The analysis sits within stated boundaries; outcomes outside significant geopolitical shifts or unforeseen technological breakthroughs would require recalibration. Forecasts reflect assumptions concerning stable raw material supply chains and consistent energy efficiency mandates. Recalibration cycles align with material shifts in global industrial investment or environmental policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Asia-Pacific Booster Compressor Market
Compressors
Positive-Displacement Hydrogen Compressor Market
Compressors
Europe Compressor Market
Compressors
Automotive Compressors Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Booster Compressor Market
Compressors
Compressed Air Lubricators Market
Compressors
Axial Compressor Market
Compressors
CNG Compressor Market
Compressors
Rotary Lobe Compressor Market
Compressors
North America Air Compressor Market
Compressors
Portable Compressor Market
Compressors
Process Gas Compressors Market
Compressors
Air Compressor Market
Compressors
Rotary Air Compressor Market
Compressors
Chlorine Compressors Market