
 Asia-Pacific Centrifugal Compressor Market | 2026-2036
Asia-Pacific Centrifugal Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Centrifugal Compressor Market Outlook
ISO 8573-1 Class 0 certification for oil-free compressed air is reorganizing supplier eligibility across the Asia-Pacific Centrifugal Compressor Market, disqualifying legacy entrants who lack validated clean-air architectures. Atlas Copco Ltd leverages its Swedish-rooted oil-free technology pedigree to anchor premium positioning in pharmaceutical and food-grade installations across East Asia. Ingersoll Rand plc competes through sustained R&D intensity in magnetic bearing systems, while Mitsubishi Heavy Industries Ltd dominates large-frame multi-stage units for LNG baseload applications in Japan and Australia.
A centrifugal compressor accelerates gas through an impeller rotating at speeds typically exceeding 20,000 RPM, converting kinetic energy into pressure rise via a diffuser and volute casing; this dynamic compression principle suits continuous-duty flows above 500 cubic feet per minute in petrochemical, power, and industrial gas circuits. Oil-free configurations command widening preference as end users in chemical and water treatment sectors face tightening contamination protocols, while multi-stage architectures capture margin pools in high-pressure natural gas processing duties where single-stage machines face efficiency ceilings. HVAC applications within the application dimension are absorbing smaller-frame units as district cooling networks proliferate across tropical Southeast Asian cities.
Japan's METI enforces Top Runner efficiency standards that compel compressor replacements in heavy manufacturing, while China's MEE integrates rotating equipment into provincial carbon intensity audits that penalize above-threshold energy consumption. Australia's TGA and state-level WorkSafe frameworks impose pressure vessel inspection regimes that shape aftermarket service contracts and spare parts demand. Stakeholders must track how India's BIS adoption of ISO-aligned efficiency grades will alter import competitiveness for European and Japanese suppliers against emerging domestic assembly operations.
Market Dynamics
China's dual carbon goals under MEE oversight are compressing replacement cycles across coastal petrochemical corridors, forcing facilities to retire energy-intensive legacy units ahead of depreciation schedules. This regulatory acceleration is redistributing procurement budgets toward oil-free architectures and magnetic bearing systems that trim operational carbon intensity.
Growth Catalysts
- MEE Carbon Intensity Audits:China's provincial environmental ministry embeds rotating equipment into carbon accounting frameworks that penalize above-threshold energy consumption, compelling compressor replacements in Jiangsu and Shandong chemical clusters.
- India Western Coastal Buildout:Refinery and LNG terminal expansions across Gujarat and Maharashtra are accelerating procurement cycles for large-frame multi-stage units in natural gas processing duties.
- ISO 8573-1 Class 0 Certification:Pharmaceutical and food-grade installations across East Asia now mandate validated oil-free compressed air architectures, disqualifying legacy suppliers lacking clean-air credentials.
Market Restraints
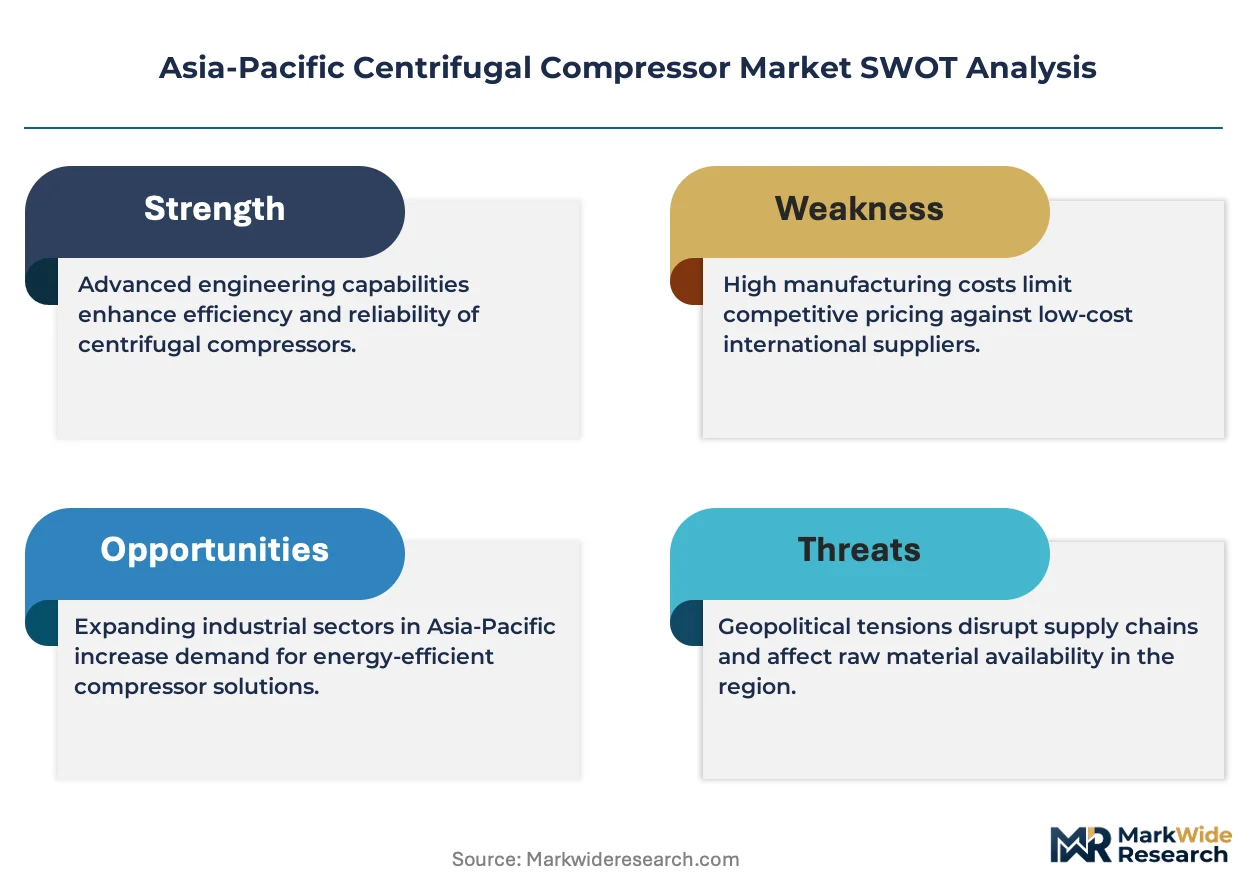
- Rare Earth Magnet Supply Concentration:Magnetic bearing systems depend on neodymium and dysprosium supply chains concentrated in Chinese processing facilities, exposing procurement to export control volatility.
- High-Pressure Alloy Input Costs:Multi-stage impeller fabrication requires specialized titanium and nickel-based superalloys subject to aerospace-industry demand competition and price instability.
- Technical Limitation in Heavy Feedstock Handling:Oil-free designs face efficiency penalties when processing sour gas streams with elevated hydrogen sulfide content, restricting deployment in certain Southeast Asian petrochemical configurations.
Strategic Opportunities
- Vietnam Petrochemical Expansion:Greenfield complexes in Ba Ria-Vung Tau and Long An provinces lack installed compressor bases, creating first-mover positioning for suppliers offering integrated service contracts.
- Japan METI Top Runner Standards:Mandatory efficiency upgrades in heavy manufacturing are generating aftermarket demand for retrofit packages that improve specific energy consumption in existing installations.
- Digital Twin Convergence:Integration of real-time vibration monitoring with predictive maintenance algorithms is opening subscription revenue streams for compressor OEMs serving Australia's remote LNG baseload facilities.
Industry Challenges
- Magnetic Bearing Specialist Scarcity:Installation and commissioning of active magnetic bearing systems requires technicians trained in electromagnetic rotor dynamics, a skill set concentrated in European and Japanese service networks with limited Asia-Pacific coverage.
- ISO 8573-1 Class 0 Certification Timelines:Third-party validation of oil-free architectures demands extended testing protocols that delay product launches and compress competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Centrifugal Compressor Market |
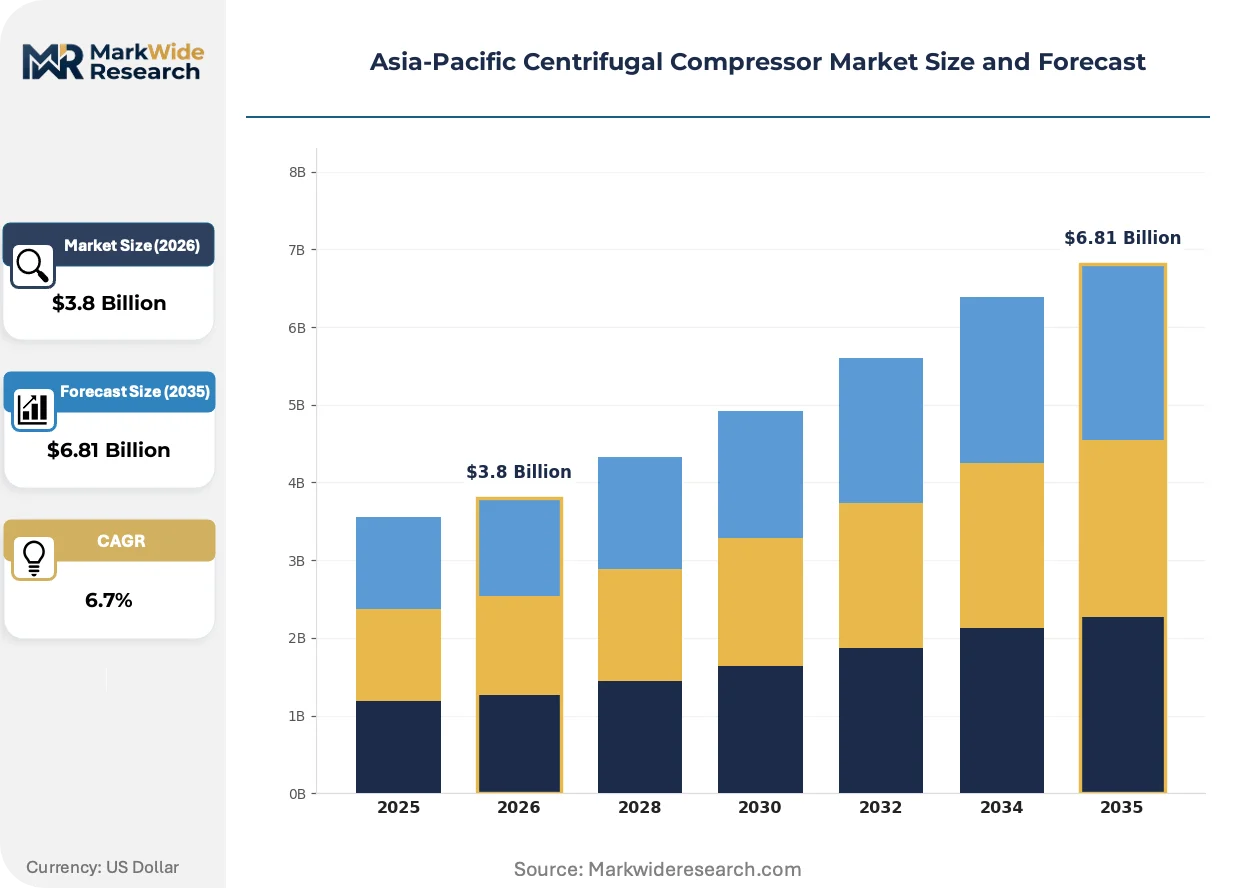
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-stage, Multi-stage, Oil-injected, Oil-free End User: Oil & Gas, Power Generation, Chemical, Water Treatment Application: Natural Gas Processing, HVAC, Refrigeration, Industrial Processes Technology: Centrifugal, Axial, Hybrid, Reciprocating |
| Companies Covered | Atlas Copco Ltd, Ingersoll Rand plc, General Electric Company, BAUER Compressors Inc, Gardner Denver Holdings Inc, Boge Compressors Ltd, Hitachi Ltd, Siemens Energy AG, Mitsubishi Heavy Industries Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Centrifugal Compressor Market Strategic Shifts
Active magnetic bearing technology is compressing maintenance intervals and enabling dry gas seal elimination across high-speed centrifugal applications. Three interconnected developments are restructuring competitive positioning in the Asia-Pacific centrifugal compressor market.
Magnetic bearing systems eliminate mechanical contact between rotor and stator through electromagnetic suspension, enabling operation without lubrication oil systems. Petrochemical facilities in South Korea and Singapore are adopting these configurations for continuous-duty hydrogen compression duties. This architecture is supplanting conventional oil-film bearing designs in applications above 15,000 RPM where maintenance access is constrained.
Japan's METI enforces Top Runner efficiency standards that compel compressor replacements in heavy manufacturing sectors including steel and chemicals. The regulation mandates that new installations exceed the efficiency performance of the top-performing existing equipment in each category. Australian LNG producers are responding by specifying aerodynamically optimized impeller designs that reduce specific energy consumption in baseload refrigeration cycles.
End users in India's refining sector are unbundling aftermarket service contracts from initial equipment procurement, creating standalone negotiations for spare parts and maintenance. This behavior fragments supplier revenue streams and exposes OEMs to third-party service competition. The pattern is most visible in Gujarat's private refinery complexes where procurement teams separate capital and operating expenditure approvals.
Asia-Pacific Centrifugal Compressor Market Segmentation
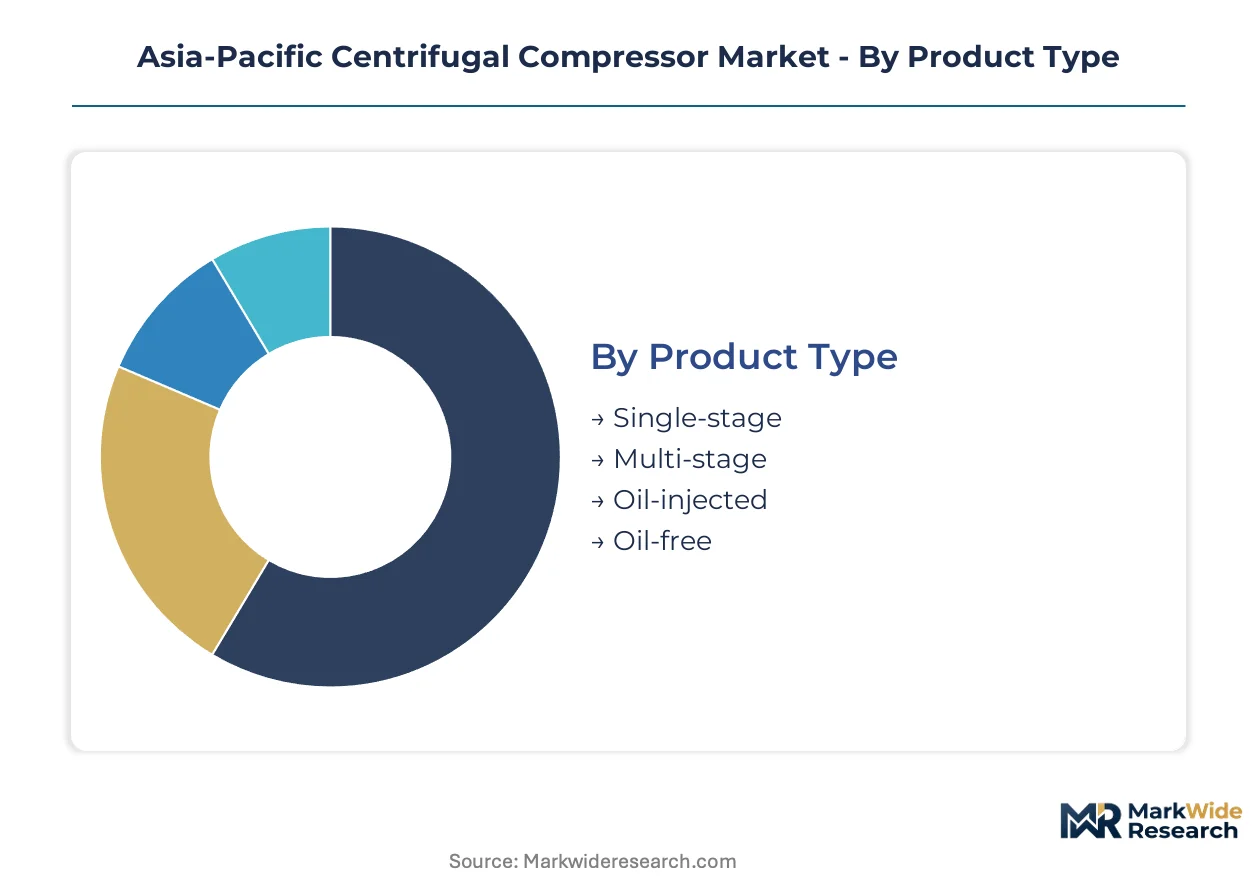
Segmentation in the Asia-Pacific centrifugal compressor market reveals how technology choices and application requirements fragment procurement behavior across petrochemical corridors and industrial clusters. Understanding these divisions exposes where specification premiums concentrate and where commoditization pressures dominate.
Product Type:
Multi-stage and oil-free configurations face the strongest substitution pressure from magnetic bearing turbocompressors in high-speed hydrogen duties, while single-stage units compete against screw and rotary vane alternatives in lower-pressure industrial air systems.
- Multi-stage:Sequential impeller arrays generate pressure ratios exceeding 10:1 through intercooling between compression stages. Demand concentrates in Australia's Queensland LNG trains and Japan's Chiba refinery complexes where baseload refrigeration cycles require specific energy consumption below 18 kW per thousand cubic meters. Carbon intensity audits under METI and MEE frameworks are accelerating replacement of aging multi-stage fleets.
- Oil-free:Air compression architectures validated to ISO 8573-1 Class 0 eliminate hydrocarbon contamination risk through dry-running impeller designs and air-cooled bearings. Pharmaceutical installations across South Korea's Songdo biotech cluster and Singapore's Tuas food-grade facilities now mandate these specifications, disqualifying legacy oil-injected alternatives.
- Single-stage:Single impeller configurations suit moderate pressure ratios below 4:1 with simpler maintenance protocols.
- Oil-injected:Lubricated bearing systems retain cost advantage in non-critical industrial air applications where contamination tolerance permits.
Multi-stage units anchor the volume base in natural gas processing while oil-free configurations gain share at the steepest rate across East Asian pharmaceutical and food manufacturing.
End User:
Cost tier stratification separates specification-intensive oil and gas procurement from price-sensitive water treatment installations, with chemical sector buyers occupying the contested middle ground where total cost of ownership calculations determine supplier selection.
- Oil & Gas:Upstream, midstream, and downstream hydrocarbon operations require continuous-duty compression for gas lift, pipeline transport, and refining. India's Reliance-operated Jamnagar complex and Petronas' Pengerang integrated refinery in Malaysia are expanding multi-stage procurement for sour gas handling and LNG liquefaction trains.
- Chemical:Petrochemical crackers and ammonia synthesis loops demand corrosion-resistant materials for hydrogen-rich process streams. BASF's Verbund site in Nanjing and SCG Chemicals' Rayong complex in Thailand are specifying titanium impeller alloys for chlorine-alkali and methanol duties.
- Power Generation:Combined cycle plants and coal gasification facilities use centrifugal compression for combustion air and syngas processing.
- Water Treatment:Municipal and industrial wastewater aeration systems favor smaller-frame single-stage units with minimal maintenance requirements.
Oil and gas anchors the revenue base through large-frame unit procurement while chemical sector demand expands most quickly on petrochemical capacity additions across Southeast Asia.
Application:
Geographic concentration in tropical coastal cities is driving divergent specification patterns between natural gas processing and HVAC applications, with the former demanding maximum efficiency and the latter prioritizing compact footprint and acoustic containment.
- Natural Gas Processing:Acid gas removal, dehydration, and liquefaction cycles require multi-stage compression with dry gas seals and variable speed drives. Australia's Ichthys and Prelude floating LNG facilities and Indonesia's Tangguh expansion are specifying magnetic bearing turbocompressors to eliminate lube oil systems in offshore environments.
- HVAC:District cooling networks in tropical Southeast Asian cities deploy smaller-frame centrifugal chillers for centralized air conditioning. Singapore's Marina Bay district cooling plant and Bangkok's central business district networks are absorbing oil-free compressor packages to meet green building certification requirements.
- Refrigeration:Industrial cold storage and process cooling applications favor ammonia-compatible compressor designs with specialized sealing systems.
- Industrial Processes:General manufacturing air systems span automotive paint lines, electronics clean rooms, and pneumatic conveying operations with varying purity requirements.
Natural gas processing commands the premium specification tier while HVAC applications climb the fastest on urban district cooling buildouts.
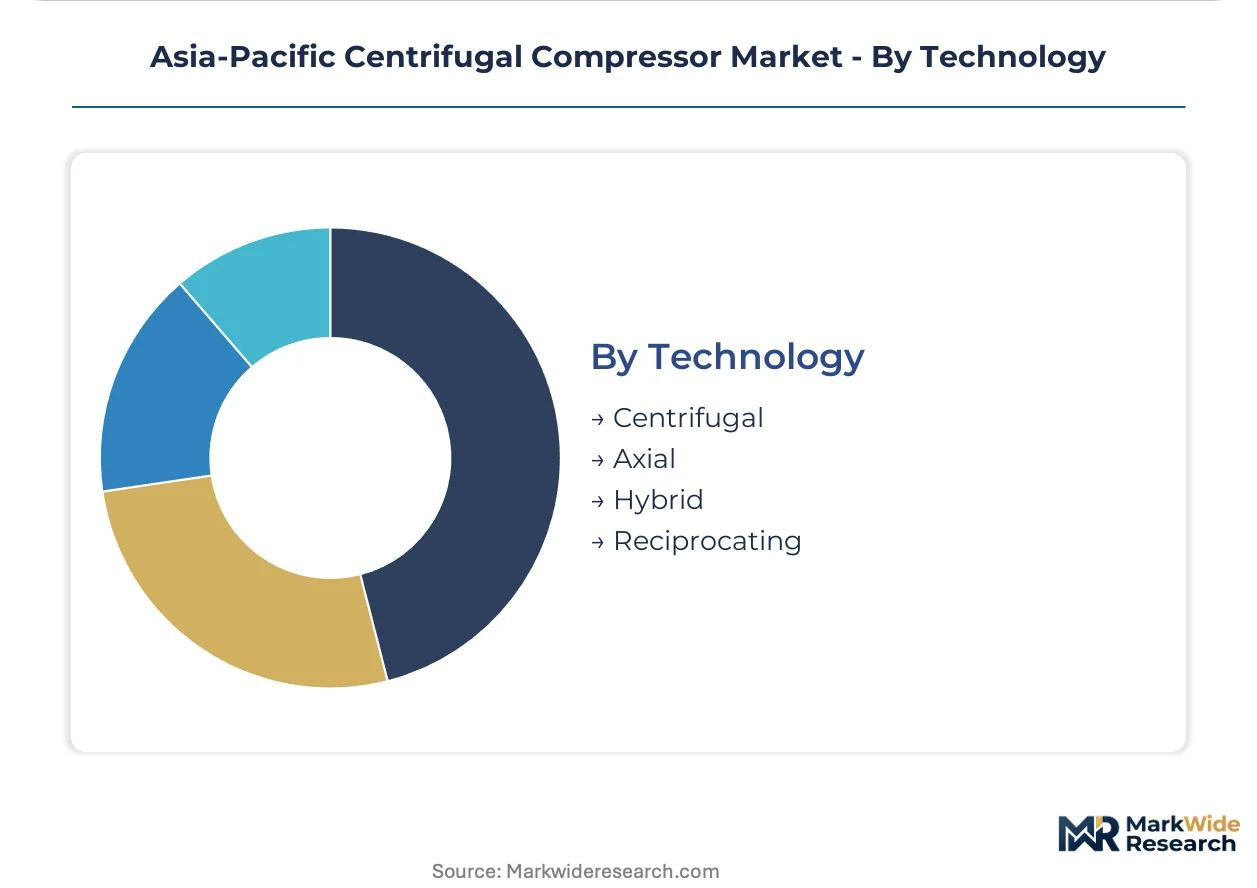
Technology:
Maturity differentials separate established centrifugal architectures from emerging hybrid configurations, with axial and reciprocating alternatives capturing niche positions where pressure ratio or flow range requirements fall outside centrifugal efficiency envelopes.
- Centrifugal:Dynamic compression through radial impeller acceleration dominates continuous-duty applications above 500 cubic feet per minute. The technology retains default specification status across Asia-Pacific petrochemical and power generation procurement.
- Axial:Alternating rotating and stationary blade rows achieve higher flow rates at lower pressure ratios, suiting combustion air and flue gas handling in combined cycle plants.
- Hybrid:Combined centrifugal-axial stages or integrated magnetic bearing systems are penetrating high-speed hydrogen and carbon capture duties.
- Reciprocating:Positive displacement piston compression retains position in intermittent duty and very high-pressure applications below centrifugal economic thresholds.
Pure centrifugal designs anchor installed capacity while hybrid configurations show the steepest specification growth on emerging hydrogen economy applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE carbon intensity audits and India's western coastal refinery buildouts are compressing procurement cycles across Asia-Pacific petrochemical corridors. Japan's METI Top Runner standards and Australia's TGA pressure vessel regimes add regulatory complexity to aftermarket service demand. Vietnam's greenfield petrochemical complexes lack installed bases, creating first-mover positioning for integrated service providers.
China
Jiangsu and Shandong chemical clusters are retiring legacy compressors ahead of depreciation schedules under MEE provincial carbon audits. The ministry's dual carbon goals penalize above-threshold energy consumption in rotating equipment. Facilities in Ningbo and Dalian are redirecting procurement budgets toward oil-free architectures and magnetic bearing systems.
India
Reliance-operated Jamnagar and Gujarat refinery expansions are accelerating large-frame multi-stage unit procurement for sour gas handling. The Bureau of Indian Standards is adopting ISO-aligned efficiency grades that will alter import competitiveness. Maharashtra's LNG terminal buildouts near Mumbai are concentrating demand for natural gas processing compression.
Japan
METI enforces Top Runner efficiency standards that compel compressor replacements in Chiba and Yokkaichi refinery complexes. The regulation mandates new installations exceed top-performing existing equipment efficiency. Steel and chemical sector buyers in the Keihin industrial belt are specifying aerodynamically optimized impeller designs.
Australia
Queensland LNG trains and offshore floating facilities at Ichthys and Prelude are specifying magnetic bearing turbocompressors to eliminate lube oil systems. TGA and state-level WorkSafe frameworks impose pressure vessel inspection regimes. Perth-based service networks are capturing aftermarket contracts for remote baseload refrigeration cycles.
Vietnam
Greenfield petrochemical complexes in Ba Ria-Vung Tau and Long An provinces lack installed compressor bases entirely. Provincial industrial zone incentives are attracting foreign direct investment in integrated refining and chemical capacity. First-mover suppliers are positioning integrated service contracts before equipment standardization locks in.
Asia-Pacific Centrifugal Compressor Market Competitive Environment
Listed leaders compete with private specialists across technology certification and aftermarket service depth. The Asia-Pacific centrifugal compressor market structures around three tiers: premium-positioned oil-free specialists, scale-driven multi-stage fabricators, and regional service integrators. Strategic moves concentrate on magnetic bearing technology licensing and vertical integration into predictive maintenance platforms.
Within the premium oil-free tier, Atlas Copco Ltd and Ingersoll Rand plc exemplify divergent technology pedigrees. Atlas Copco's Swedish-rooted heritage anchors pharmaceutical and food-grade positioning across East Asian installations. Ingersoll Rand's sustained R&D intensity in magnetic bearing systems represents an alternative competitive vector. Mitsubishi Heavy Industries Ltd occupies the large-frame multi-stage segment for LNG baseload applications in Japan and Australia.
| Leading Market Players |
|---|
| Atlas Copco Ltd |
| Ingersoll Rand plc |
| General Electric Company |
| BAUER Compressors Inc |
| Gardner Denver Holdings Inc |
| Boge Compressors Ltd |
| Hitachi Ltd |
| Siemens Energy AG |
| Mitsubishi Heavy Industries Ltd |
| Others |
Value Chain & Pricing Dynamics
ISO 8573-1 Class 0 certification gates both supplier qualification and price differentiation across Asia-Pacific procurement committees, forcing facilities to pay specification premiums for validated oil-free architectures while disqualifying uncertified competitors from pharmaceutical and food-grade tenders. This regulatory filter simultaneously concentrates supply-side pricing power among credentialed OEMs and fragments procurement budgets across compliance tiers.
Pricing Analysis
Certification level creates the primary spread between premium oil-free units and standard oil-injected alternatives, with ISO 8573-1 Class 0 validation commanding project-based pricing that bundles extended testing protocols and aftermarket service contracts. Price differentiation reflects magnetic bearing integration and titanium impeller grades alongside geographic delivery costs to Australian offshore facilities. Pricing pressure stems from India's BIS adoption of ISO-aligned efficiency grades, which exposes European and Japanese suppliers to emerging domestic assembly competition. Water treatment municipalities exhibit highest price sensitivity, while LNG baseload operators prioritize lifecycle efficiency over capital expenditure.
Supply Chain Analysis
China and Japan anchor rare earth magnet processing and precision casting for impeller fabrication, with South Korean specialty steel producers supplying corrosion-resistant alloys for hydrogen-rich process streams. Magnetic bearing systems draw from neodymium and dysprosium supply chains concentrated in Chinese processing facilities, while multi-stage impeller fabrication rests on titanium and nickel-based superalloy inputs subject to aerospace-industry demand competition. Single-source vulnerability runs through rare earth export control exposure. Distribution runs through OEM-direct channels for large-frame units and authorized service networks for aftermarket spares.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts and predictive maintenance subscriptions are expanding faster than hardware sales across Asia-Pacific compressor installations, creating recurring-revenue layers that alter strategic positioning for suppliers and investors alike.
For Market Incumbents: Consolidate magnetic bearing service capabilities through technician training investments in European and Japanese networks, addressing specialist scarcity that constrains Asia-Pacific commissioning capacity. Deepen backward integration into titanium alloy sourcing to defend margin position against aerospace demand competition. Lock in long-term service contracts at Vietnam's greenfield complexes before equipment standardization freezes procurement relationships. For New Entrants and Emerging Players: ISO 8573-1 Class 0 certification fast-tracks unlock pharmaceutical and food-grade specifications across South Korea's Songdo biotech cluster and Singapore's Tuas facilities, where incumbent disqualification creates immediate white-space. Target Vietnam's Ba Ria-Vung Tau and Long An petrochemical corridors through integrated service contracts that bundle installation, commissioning, and spare parts management. Pursue joint venture structures with established magnetic bearing technology licensors to bypass R&D capital intensity. For Investors and Strategic Acquirers: China's MEE provincial carbon audit expansion reshapes the acquisition landscape by accelerating replacement cycles and concentrating demand for efficiency-compliant equipment. Five-to-ten year viability favors suppliers with validated oil-free architectures and captive service networks over pure hardware fabricators. Watch India's BIS efficiency grade enforcement as the inflection signal determining import competitiveness for European and Japanese assets against domestic assembly operations.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Bearing Technology Licensing | Enables oil-free operation in Australian offshore LNG facilities without lube oil systems. |
| Backward Integration into Rare Earth Sourcing | Reduces exposure to Chinese export control volatility for neodymium-dependent bearing systems. |
| Predictive Maintenance Platform Development | Captures subscription revenue from Australia's remote baseload refrigeration cycle operators. |
| Vietnam Greenfield Service Contract Positioning | Locks in integrated relationships before Ba Ria-Vung Tau equipment standardization crystallizes. |
| ISO 8573-1 Class 0 Certification Investment | Qualifies suppliers for pharmaceutical tenders across South Korea's Songdo biotech cluster. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across Asia-Pacific petrochemical corridors. Secondary validation incorporated customs and trade data, SEC filings from listed compressor manufacturers, MEE provincial carbon audit disclosures, and METI efficiency standard documentation. Bottom-up unit shipment estimates were triangulated against top-down energy consumption projections for rotating equipment.
Across the analysis window, forecasts model product type segmentation across multi-stage, oil-free, single-stage, and oil-injected configurations alongside end-use splits in oil and gas, chemical, power generation, and water treatment sectors. Technology dimensions capture centrifugal, axial, hybrid, and reciprocating architectures. CAGRs were derived from regression analysis against industrial capacity expansion pipelines and regulatory compliance deadlines. Forecast inputs include MEE carbon intensity audit enforcement schedules and India's BIS efficiency grade adoption timelines.
Decision-makers should treat outputs as directional under assumptions of sustained MEE audit enforcement and stable rare earth supply availability; material deviation in either driver would warrant model refresh. Specific risk factors include magnetic bearing specialist training bottlenecks, ISO 8573-1 Class 0 certification timeline delays, and aerospace-industry superalloy demand spikes. Recalibration cycles align with material shifts in provincial carbon accounting frameworks and efficiency grade enforcement milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Liquid Ring Compressors Market
Compressors
Asia-Pacific Compressor Oil Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Chlorine Compressors Market
Compressors
Rotary Lobe Compressor Market
Compressors
Portable Compressor Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Automotive Compressors Market
Compressors
Axial Compressor Market
Compressors
Positive Displacement Gas Compressor Market
Compressors
Scroll Compressor Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Gas Compressors Market
Compressors
Compressor Wheel Market
Compressors
High Speed Blowers Market
Compressors
Hydrogen Compressor Market