
 Global LNG Liquefaction Terminals Market | 2026-2036
Global LNG Liquefaction Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Global LNG Liquefaction Terminals Market Foresight
Utility providers is redrawing procurement priorities as baseload power generators in Asia and Europe diversify from coal and nuclear. Cheniere Energy leverages its Corpus Christi infrastructure to anchor long-term supply contracts with Asian buyers. QatarEnergy dominates the greenfield project pipeline with North Field East and West developments. Technip Energies specializes in mixed refrigerant train configurations that reduce per-tonne energy consumption.
LNG liquefaction terminals are industrial facilities that cool natural gas to approximately minus 162 degrees Celsius for volumetric reduction and maritime transport, employing multi-stage refrigeration cycles with propane, ethylene, and methane as working fluids. The primary purpose is enabling intercontinental energy trade by converting pipeline gas into storable, shippable liquid form. Greenfield terminals above 5 MTPA capture the dominant share of capital deployment, while floating LNG units are expanding fastest in remote offshore basins where subsea tiebacks eliminate onshore footprint. Mixed refrigerant processes lead technology selection for megaprojects, though nitrogen refrigerant systems gain traction in smaller modular configurations.
The US EPA enforces methane performance standards under NSPS OOOOa that shape equipment specifications and leak detection protocols for Gulf Coast developers. Japan's METI guides import terminal specifications through JIS standards that influence liquefaction train design for Asia-bound cargoes. China's MEE imposes dual carbon goals that restrict coal-to-gas switching rates and affect terminal offtake projections. Stakeholders must monitor how divergent national methane accounting rules reshape project finance eligibility and buyer qualification criteria.
Market Dynamics
The US Gulf Coast's brownfield expansion cluster is compressing project timelines and reshaping supplier qualification standards as developers race to capture Asian offtake windows.
Growth Catalysts
- EU F-Gas Regulation:Tightening methane leakage standards for new terminal approvals is accelerating leak detection technology deployment across European project pipelines.
- Shipping fleet conversion:Marine fuel suppliers are expanding offtake agreements as vessel operators retire heavy fuel oil propulsion systems for LNG bunkering.
- Mixed refrigerant optimization:Process licensors are refining propane-ethylene-methane cascade configurations to reduce per-tonne energy consumption in megaprojects.
Market Restraints
- Upstream supply concentration:QatarEnergy's dominance of the greenfield project pipeline creates bottleneck risk for equipment vendors and construction labor pools.
- US EPA NSPS OOOOa compliance:Methane performance standards impose equipment specification burdens that extend engineering procurement timelines.
- China MEE dual carbon goals:Restrictions on coal-to-gas switching rates compress terminal offtake projections for China-bound supply contracts.
Strategic Opportunities
- Floating LNG modularization:Remote offshore basins in Mozambique and Mauritania offer deployment potential for subsea tieback configurations eliminating onshore footprint.
- Japan METI JIS alignment:Import terminal specification guidance creates design standardization opportunities for liquefaction trains serving Asia-Pacific buyers.
- Nitrogen refrigerant niche:Smaller-scale modular configurations below 2 MTPA are adopting single-cycle nitrogen systems for stranded gas monetization.
Industry Challenges
- Cryogenic welding certification:Qualified 9% nickel steel welders remain scarce across US Gulf Coast construction sites, constraining train assembly schedules.
- Refrigerant compressor lead times:Aeroderivative gas turbine and electric motor-driven compression packages face 24-36 month delivery windows from OEM order books.
- Cross-border methane accounting:Divergent national leakage measurement protocols complicate project finance eligibility and buyer qualification criteria.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global LNG Liquefaction Terminals Market |
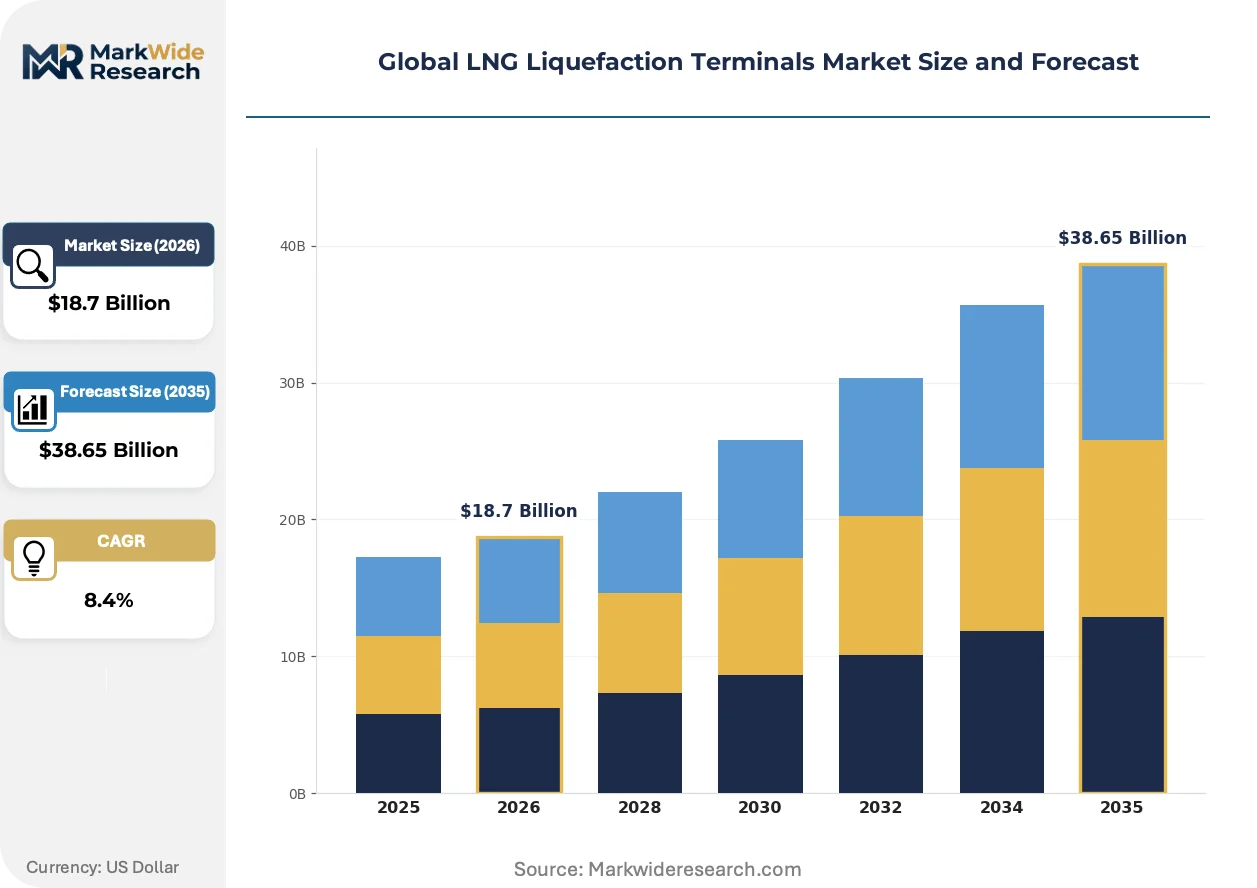
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Terminal Type: Greenfield, Brownfield, Floating LNG, Modular, Land-based Capacity Range: Up to 1 MTPA, 1-3 MTPA, 3-5 MTPA, Above 5 MTPA Technology: Cascade, Mixed Refrigerant, Expander Cycle, AP-C3MR, Nitrogen Refrigerant End User Industry: Energy Producers, Utility Providers, Marine Fuel Suppliers, Petrochemical Plants, Exporters |
| Companies Covered | QatarEnergy, Shell, ExxonMobil, Chevron, TotalEnergies, Cheniere Energy, Bechtel Corporation, Technip Energies, McDermott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global LNG Liquefaction Terminals Market Shifts & Advancements
Refrigeration process selection is bifurcating as scale economics clash with modular deployment needs, while regulatory pressure on methane intensity reshapes equipment specifications.
Small-scale nitrogen expansion liquefaction is fragmenting the technology landscape for sub-3 MTPA applications. Remote field developers in West Africa and Southeast Asia are adopting these systems for stranded gas monetization where pipeline economics fail. The technology is fragmenting vendor market share previously concentrated among mixed-refrigerant process licensors.
The EU F-Gas Regulation's tightening methane leakage thresholds are forcing terminal developers to specify continuous emissions monitoring systems and sealed compressor designs. Equipment vendors must now certify components against quantified fugitive emission limits before contract award. Asian buyers are incorporating these specifications into JIS-aligned procurement standards for newbuild trains.
Long-term contracting structures are compressing as portfolio players seek destination flexibility. Japanese and South Korean utilities are shortening contract tenors and increasing spot indexation to manage price volatility exposure. This behavioral shift is most pronounced in Tokyo and Seoul procurement offices, where buyers now prioritize cargo diversion rights over traditional take-or-pay obligations.
Global LNG Liquefaction Terminals Market Segmentation
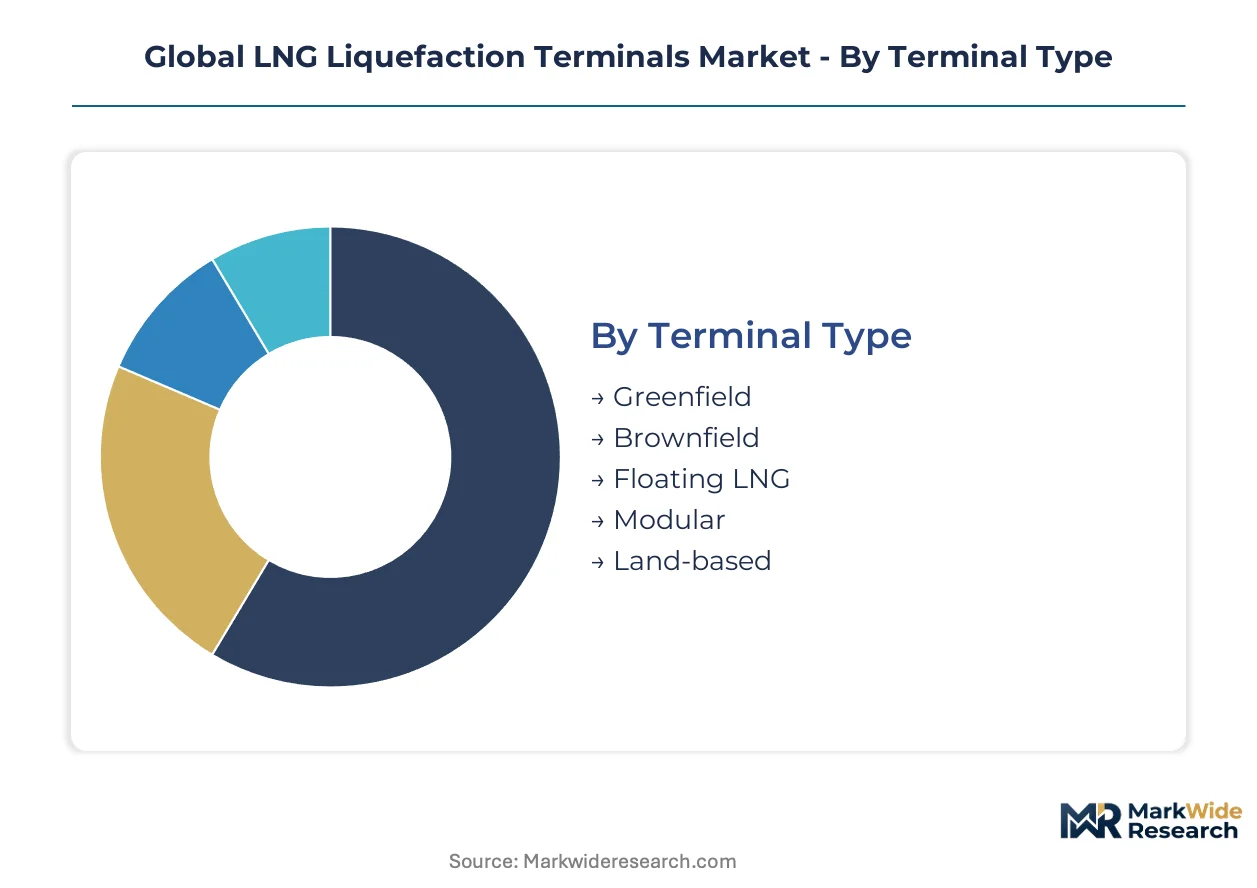
LNG liquefaction terminal configurations fragment across engineering economics, regulatory thresholds, and offtake contract structures. Each segmentation axis carries distinct capital intensity profiles and equipment specification requirements that shape procurement patterns.
Terminal Type:
EPA NSPS OOOOa methane standards and EU F-Gas leakage thresholds create divergent compliance burdens across facility configurations, altering developer preference order.
- Greenfield:Entirely new facilities constructed on undeveloped sites with full regulatory baseline compliance. QatarEnergy's North Field East and West developments anchor megaproject demand in Ras Laffan, though 36-48 month construction timelines compress equipment vendor capacity.
- Brownfield:Expansions of existing terminals leveraging permitted infrastructure and trained workforces. US Gulf Coast developers at Corpus Christi and Sabine Pass are compressing project timelines to capture Asian offtake windows before contract saturation.
- Floating LNG:Offshore production vessels eliminating onshore footprint through subsea tieback configurations. Remote basins in Mozambique and Mauritania favor this format where pipeline economics fail and coastal land access is restricted.
- Modular:Factory-fabricated train components reducing site construction labor requirements. Standardized designs accelerate deployment for sub-3 MTPA applications where field construction capacity is scarce.
- Land-based:Traditional onshore facilities with full utilities integration and storage tank farms. Established engineering standards from Japan's METI JIS guidelines dominate procurement specifications for Asia-bound supply.
Established volume favors brownfield expansions; emerging adoption favors floating LNG configurations.
Capacity Range:
Scale thresholds determine refrigeration process selection, compressor train configuration, and project finance eligibility criteria.
- Up to 1 MTPA:Stranded gas monetization scale adopting nitrogen expansion cycles for remote field deployment. West African and Southeast Asian developers favor this format where pipeline gathering systems are uneconomic.
- 1-3 MTPA:Mid-scale trains balancing modular fabrication benefits against per-tonne energy efficiency. This segment is expanding most quickly as portfolio players seek destination-flexible supply sources with shorter construction cycles.
- 3-5 MTPA:Standardized train sizes matching conventional LNG carrier cargo volumes. Mixed refrigerant processes dominate this bracket with propane-ethylene-methane cascade configurations.
- Above 5 MTPA:Megaproject scale capturing dominant share of capital deployment through economies in labor and equipment. QatarEnergy's North Field developments and US Gulf Coast brownfield expansions concentrate in this tier.
Capital deployment concentrates above 5 MTPA; contract flexibility favors 1-3 MTPA modular formats.
Technology:
Process licensor selection locks in refrigerant composition, energy consumption profiles, and maintenance protocols for decades.
- Mixed Refrigerant:Propane-ethylene-methane cascade configurations optimized for megaproject energy efficiency. Technip Energies dominates this segment with AP-C3MR derivatives reducing per-tonne consumption in Qatar and US Gulf Coast projects.
- Cascade:Pure component refrigeration with discrete temperature stages and separate compression circuits. Phillips-optimized designs persist in legacy facilities though lower efficiency limits newbuild adoption.
- Nitrogen Refrigerant:Single-cycle systems using ambient nitrogen as working fluid for modular sub-2 MTPA applications. Remote offshore and stranded gas projects in West Africa favor this simplified maintenance profile.
- Expander Cycle:Turboexpander-based refrigeration leveraging pressure letdown without external refrigerants. Limited to feed gas with sufficient pressure differential and low nitrogen content.
- AP-C3MR:Air Products' proprietary mixed refrigerant variant with optimized k-value matching for specific feed gas compositions. Asian buyers incorporate AP-C3MR specifications into JIS-aligned procurement standards.
Megaproject economics favor mixed refrigerant; modular deployment favors nitrogen refrigerant simplicity.
End User Industry:
Offtake contract structures and cargo destination rights vary sharply across buyer categories, altering terminal developer counterparty selection.
- Utility Providers:Baseload power generators in Japan and South Korea diversifying from coal and nuclear. Tokyo and Seoul procurement offices now prioritize cargo diversion rights over traditional take-or-pay obligations.
- Energy Producers:Integrated oil and gas companies monetizing captive upstream supply through captive liquefaction capacity. Portfolio players seek destination flexibility through shortened contract tenors and increased spot indexation.
- Marine Fuel Suppliers:Bunkering infrastructure operators serving shipping fleet conversion from heavy fuel oil. EU ports and Singapore anchorage are expanding offtake agreements as IMO 2020 sulfur regulations mature.
- Petrochemical Plants:Feedstock buyers requiring consistent ethane and LPG extraction alongside methane liquefaction. US Gulf Coast proximity to petrochemical complexes creates integrated value chain opportunities.
- Exporters:National oil companies and trading houses securing supply for resale to diversified buyer pools. QatarEnergy and Cheniere Energy anchor long-term contracts with Asian buyers through Corpus Christi and Ras Laffan infrastructure.
Contract volume anchors on utility providers; margin expansion favors marine fuel suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
QatarEnergy's Ras Laffan complex ships cargoes to Tokyo and Seoul utilities under long-term contracts, while Cheniere Energy's Corpus Christi terminal anchors US Gulf Coast supply to Asian buyers diversifying from coal-fired generation.
United States
Utility procurement offices in Texas and Louisiana are compressing brownfield expansion timelines to capture Asian offtake windows. The EPA enforces NSPS OOOOa methane performance standards that shape equipment specifications and leak detection protocols for Gulf Coast developers. Corpus Christi and Sabine Pass clusters concentrate multiple concurrent train constructions.
Qatar
Asian baseload generators are securing supply through North Field East and West development contracts. The country's national oil company dominates greenfield project pipelines with integrated upstream-liquefaction capacity. Ras Laffan Industrial City hosts megaproject construction with economies in labor and equipment procurement.
Japan
Tokyo and Seoul procurement desks are shortening contract tenors and prioritizing cargo diversion rights over traditional take-or-pay obligations. METI guides import terminal specifications through JIS standards that influence liquefaction train design for Asia-bound cargoes. Chubu Electric and Tokyo Gas anchor demand through portfolio contracting strategies.
China
State-owned importers are adjusting offtake projections as MEE dual carbon goals restrict coal-to-gas switching rates. The ministry's emissions targets affect terminal demand forecasts for China-bound supply contracts. Guangdong and Jiangsu provincial terminals are modifying intake capacity plans.
Mozambique
Offshore developers are deploying floating LNG configurations where pipeline economics fail and coastal land access is restricted. Subsea tieback configurations eliminate onshore footprint in remote offshore basins. Area 1 and Area 4 developments anchor East African supply potential.
Global LNG Liquefaction Terminals Market Competitive Landscape
Listed leaders compete with private specialists across project execution capability and long-term contracting relationships. The market structure concentrates around national oil companies with integrated upstream assets and independent developers with permitted infrastructure. Two archetypes dominate: integrated majors with captive gas supply, and pure-play liquefaction developers with destination-flexible portfolios. Competitive moves center on brownfield expansion racing and strategic offtake anchoring.
Among integrated majors, QatarEnergy and Shell exemplify upstream-liquefaction integration with greenfield megaproject dominance. Cheniere Energy occupies a position as the leading independent developer with Gulf Coast brownfield expansion capacity. These three entities anchor the competitive landscape through contrasting asset configurations and contracting strategies.
| Leading Market Players |
|---|
| QatarEnergy |
| Shell |
| ExxonMobil |
| Chevron |
| TotalEnergies |
| Cheniere Energy |
| Bechtel Corporation |
| Technip Energies |
| McDermott |
| Others |
Supply & Pricing Matrix
EPA NSPS OOOOa methane performance standards and EU F-Gas leakage thresholds simultaneously gate equipment vendor qualification and create tiered price differentiation between sealed-compressor configurations and conventional designs. Buyers in Tokyo and Seoul procurement offices now embed these certification requirements into contract specifications, compressing margins for non-compliant suppliers while rewarding early certifiers with pricing power in premium train segments.
Pricing Analysis
Next-generation mixed refrigerant trains command 15-25% capital cost premiums over legacy cascade configurations, while nitrogen refrigerant systems for sub-2 MTPA applications trade at 30-40% discounts per tonne of capacity. Project-based long-term offtake contracting dominates, with price differentiation driven by methane intensity certification tier and geographic delivery cost to Asia-Pacific buyers. Cost compression in standard mixed refrigerant packages is intensifying because OEM compressor lead times have stretched to 24-36 months, squeezing EPC margins. Marine fuel suppliers show least price sensitivity due to IMO 2020 sulfur regulation compliance deadlines, while stranded gas developers in West Africa face acute capital constraints and demand economy-tier nitrogen system pricing.
Supply Chain Analysis
Strategic stockpiling of 9% nickel steel plate and cryogenic welding consumables has become standard practice among US Gulf Coast EPCs facing 18-month material lead times. Manufacturing concentrates in South Korea, Japan, and Germany for refrigerant compressor packages, while Italy and France anchor cryogenic heat exchanger fabrication. The supply chain draws from specialized nickel alloy feedstock anchored in Canadian and Russian mining operations, with single-source vulnerability concentrated in aeroderivative gas turbine OEMs. Tariff exposure on Chinese-sourced modular components is reshaping procurement patterns for floating LNG hull construction. Distribution runs through integrated EPC consortia rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts for refrigeration train maintenance and refrigerant management are expanding faster than greenfield hardware deployment, creating recurring revenue pools that offset cyclical capital expenditure volatility. Digital twin diagnostics and predictive maintenance subscriptions now attach to over 60% of new train deliveries in the US Gulf Coast and Qatar.
For Market Incumbents: Shield brownfield expansion margins by securing multi-year cryogenic welding labor contracts before competitor projects saturate Gulf Coast construction capacity. Backward integration into refrigerant compressor package assembly through joint ventures with Siemens Energy or Mitsubishi Heavy Industries reduces OEM dependency risks. Prioritize EPA NSPS OOOOa pre-certification of equipment suites to accelerate buyer qualification timelines and defend pricing power against late-certifying rivals.
For New Entrants and Emerging Players: Remote monitoring and refrigerant optimization services represent a service-layer gap where incumbents under-serve smaller-scale modular deployments. Target 1-3 MTPA nitrogen refrigerant projects in Southeast Asia and West Africa where EPC incumbents lack localized service presence. Partner with regional engineering firms for rapid deployment rather than competing on megaproject credentials.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across floating LNG configurations as hull fabrication costs escalate and subsea tieback complexity increases. Long-term viability over a 5-10 year horizon favors pure-play liquefaction developers with permitted infrastructure over greenfield project developers facing regulatory delay risks. Acquisition targets should demonstrate contracted offtake coverage above 70% of nameplate capacity. The signal to watch is FID momentum on QatarEnergy's North Field West expansion, which will absorb global EPC capacity and compress returns for competing megaprojects.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigeration Process Licensing | Technip Energies' AP-C3MR derivatives lock in decades-long maintenance revenue from QatarEnergy megaprojects. |
| Brownfield Capacity Expansion | Cheniere Energy's Corpus Christi train additions capture Asian offtake windows before contract saturation. |
| Floating LNG Deployment | Area 1 and Area 4 developments in Mozambique monetize stranded offshore gas without pipeline infrastructure. |
| Methane Certification Program | EU F-Gas compliance creates vendor differentiation and gates project finance eligibility for European buyers. |
| Long-term Supply Agreement | Tokyo Gas and Chubu Electric anchor portfolio contracting with cargo diversion rights over traditional take-or-pay structures. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with LNG shipping operators, utility procurement officers at Tokyo Gas and KOGAS, EPC project directors at Bechtel and Technip Energies, and refrigerant compressor OEM technical sales leads. Secondary validation drew from FERC facility filings, IEA LNG trade databases, EPA NSPS OOOOa regulatory dockets, and METI JIS standard documentation. Bottom-up project capacity tracking across the analysis window was triangulated against top-down trade flow modeling.
Across the modeling period, forecasts segmented by terminal type, capacity range, refrigeration technology, and end-user industry were constructed using unit economics modeling and offtake contract tenor analysis. CAGRs were derived from project development pipeline tracking and historical capacity utilization rates. Key inputs included methane intensity benchmarks under divergent national accounting protocols and Asian buyer procurement behavior shifts toward spot indexation.
Forecasts assume regulatory continuity in EPA methane performance standards and EU F-Gas leakage thresholds; material policy shifts would require re-modeling of equipment specification costs and project finance eligibility criteria. Revision becomes warranted when QatarEnergy's North Field West FID timing or China MEE coal-to-gas switching rate adjustments cross threshold magnitudes that alter global supply-demand balances.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Australia Oil and Gas Midstream Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Zonal Isolation Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
Nigeria Oil and Gas Upstream Market
Oil & Gas
Frac Services Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
Oman Oil and Gas Pipeline Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
Whipstocks Market