
 Turbocompressor Market | 2026-2036
Turbocompressor Market Size, Share, and Industry Trends Forecast 2026-2036
Turbocompressor Market Analysis
Downstream chemical processors is collapsing as the dominant buyer archetype while upstream LNG exporters capture procurement momentum. Atlas Copco leverages its aftermarket service density to anchor recurring revenue across installed bases. Siemens Energy competes through electrically driven turbocompressor architectures for carbon-intensive sites. MAN Energy Solutions dominates the gas-driven segment with proprietary axial-radial hybrid designs.
A turbocompressor is a dynamic compressor that uses a rotating impeller to accelerate gas to high velocity before converting kinetic energy into pressure through a diffuser, typically achieving pressure ratios from 2:1 to 20:1 depending on staging configuration. The device serves critical functions in process industries where continuous, oil-free gas compression is required for pipeline transport, chemical synthesis, or cryogenic separation. Air turbocompressors lead product type demand due to their ubiquity in general industrial applications, while multi-stage turbocompressors command premium positioning in high-pressure gas injection and LNG liquefaction cycles. Electrically driven technology is displacing gas-driven alternatives as grid decarbonization and site electrification mandates reshape capital planning.
EPA New Source Performance Standards and API 617 mechanical integrity requirements shape equipment procurement specifications for US installations, while EU F-Gas Regulation and REACH chemical compliance frameworks govern material selection and refrigerant handling protocols for European deployments. OSHA process safety management rules mandate predictive maintenance instrumentation integration. Stakeholders must monitor how carbon border adjustment mechanisms alter total cost of ownership calculations for cross-border project sourcing.
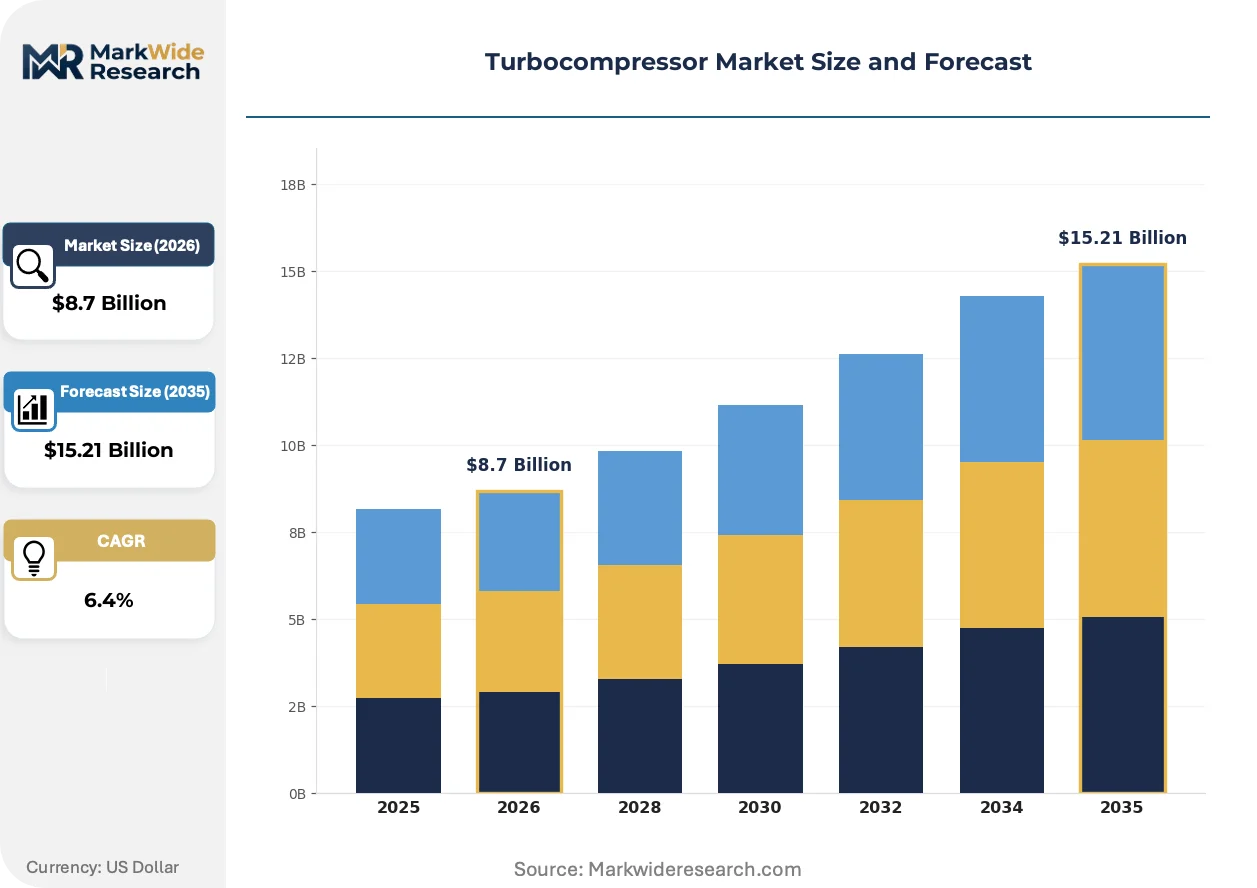
Market Dynamics
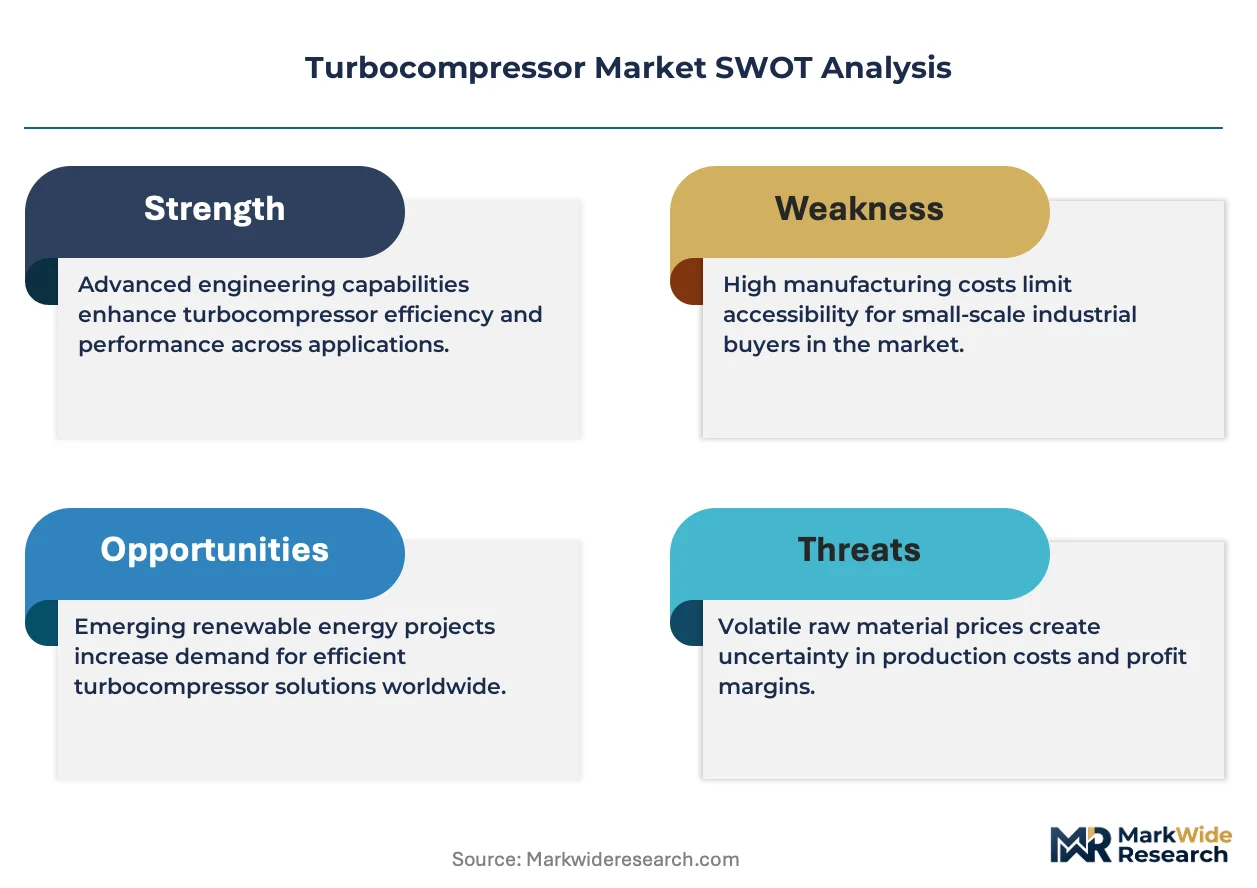
Electric drive architectures are displacing gas turbine-driven compression trains as grid decarbonization mandates and carbon accounting rules reshape capital allocation across process industries.
Growth Catalysts
- EPA New Source Performance Standards:Methane emission limits for new and modified sources are compelling facility operators to upgrade compression equipment, creating replacement demand cycles across US petrochemical corridors.
- LNG liquefaction expansion:Export terminal operators along the US Gulf Coast are procuring multi-stage turbocompressors for refrigeration cycles, anchoring procurement volumes for high-pressure gas injection applications.
- Axial-radial hybrid impeller designs:Advanced aerodynamic configurations are achieving pressure ratios above 15:1 in single casings, reducing footprint and capital cost for offshore platform installations.
Market Restraints
- Specialized alloy supply concentration:Nickel-based superalloys for high-temperature impellers face sourcing bottlenecks from a limited supplier base concentrated in Western European forging operations.
- API 617 seventh edition compliance:Enhanced mechanical integrity requirements for critical service applications are extending engineering review cycles and qualification timelines.
- Electrification infrastructure gaps:Grid capacity limitations at remote upstream sites constrain adoption of electrically driven alternatives despite operational efficiency advantages.
Strategic Opportunities
- Carbon capture and storage integration:CO2 compression for pipeline transport and sequestration represents an emerging application segment requiring pressure ratios above 100:1 in multi-stage configurations.
- Hydrogen blending infrastructure:Natural gas pipelines adapting to hydrogen service need turbocompressor retrofits with modified sealing systems and materials compatibility.
- EU Green Deal industrial decarbonization funding:Carbon contracts for difference and innovation fund allocations are subsidizing electrification retrofits at German and Dutch chemical complexes.
Industry Challenges
- Rotordynamics specialist scarcity:Engineering expertise in high-speed bearing design and torsional vibration analysis is concentrated among retiring practitioners, constraining OEM expansion.
- Legacy control system integration:Digital twin implementations for predictive maintenance must interface with decades-old distributed control architectures at established process plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbocompressor Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Turbocompressors, Gas Turbocompressors, Steam Turbocompressors, Multi-stage Turbocompressors End User: Oil & Gas, Chemical Processing, Power Generation, Water Treatment Technology: Electrically Driven, Steam Driven, Gas Driven, Hybrid Systems Application: Gas Compression, Air Separation, Refrigeration, Fuel Gas Treatment |
| Companies Covered | Atlas Copco, Ingersoll Rand, Siemens Energy, Elliott Group, Sulzer, Howden Group, MAN Energy Solutions, Kobe Steel, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbocompressor Market Emerging Trajectories
Active magnetic bearing technology is reshaping maintenance economics and operational envelopes. Digital instrumentation layers are embedding machine learning for real-time performance optimization. Procurement patterns are compressing vendor qualification cycles as buyer risk tolerance shifts.
Active magnetic bearing systems are supplanting oil-lubricated tilt-pad bearings in high-speed turbocompressor applications. LNG baseload operators are adopting these configurations to eliminate lube oil systems and reduce platform weight. The technology is supplanting conventional bearing designs across North Sea and Australian offshore developments where maintenance access is severely constrained.
EU F-Gas Regulation phase-down schedules are restricting refrigerant options for turbocompressor-driven refrigeration cycles. Chemical processors must evaluate alternative working fluids with modified thermodynamic properties and material compatibility profiles. The regulation most directly affects German and Belgian petrochemical clusters where existing propylene refrigeration systems face retrofit or replacement decisions.
Performance-based service contracting is compressing traditional spare parts and overhaul revenue models. Operators are transferring operational risk to OEMs through availability guarantees and energy consumption benchmarks. This shift is most pronounced among US Gulf Coast independent LNG exporters with limited in-house rotating equipment expertise.
Turbocompressor Market Segmentation
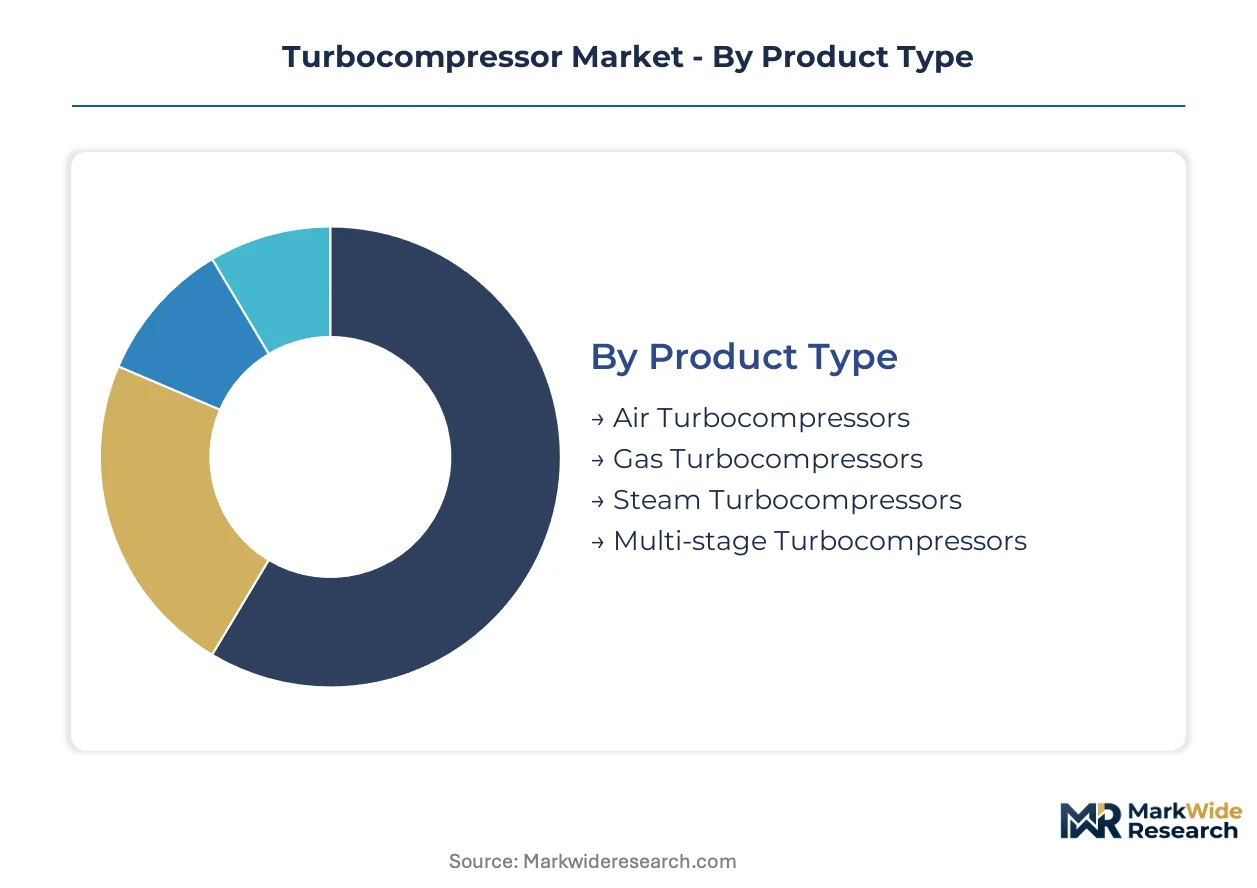
Turbocompressor procurement patterns diverge sharply across product architectures and drive technologies. End-use concentration in LNG export infrastructure and chemical processing corridors creates distinct margin profiles that reward specialization over breadth.
Product Type:
Margin pools concentrate in multi-stage configurations where pressure ratio requirements exceed single-casing limits and engineering premiums apply.
- Air Turbocompressors:Oil-free dynamic compression for general industrial service, typically achieving pressure ratios below 4:1 in single-stage arrangements. Demand clusters in automotive paint shops and food packaging facilities across the US Midwest and German manufacturing belts, where contamination-free air supply is non-negotiable.
- Multi-stage Turbocompressors:Cascaded impeller arrangements delivering pressure ratios above 15:1 through intercooled configurations. Procurement is accelerating at US Gulf Coast LNG terminals for refrigeration cycle service, driven by baseload export capacity additions and EPA methane compliance deadlines.
- Gas Turbocompressors:Process gas compression for pipeline transport and chemical synthesis loops.
- Steam Turbocompressors:Cogeneration-integrated designs leveraging waste heat recovery for compression duty.
Air turbocompressors hold installed capacity across general industry. Multi-stage configurations are rotating up the share rankings.
End User:
Volume concentration tilts toward upstream gas handling where compression train counts scale with liquefaction train additions.
- Oil & Gas:Upstream production, midstream pipeline, and LNG liquefaction applications requiring continuous gas compression at pressure ratios from 2:1 to 20:1. Procurement momentum sits with US Gulf Coast export terminal operators expanding baseload capacity, anchored by FERC permitting timelines and long-term offtake contracting.
- Chemical Processing:Process gas recycle and synthesis loop applications in ammonia, methanol, and olefin production. German and Belgian petrochemical clusters are retrofitting electrically driven alternatives under EU Green Deal funding mechanisms, displacing gas-turbine drives for carbon accounting compliance.
- Power Generation:Fuel gas compression for gas turbine power plants and integrated gasification combined cycle facilities.
- Water Treatment:Aeration and ozone generation applications in municipal and industrial wastewater systems.
Oil & Gas anchors procurement volume. Chemical Processing is climbing the fastest as electrification retrofits accelerate.
Technology:
Cost tier stratification separates electrically driven premium offerings from gas-driven baseline economics.
- Electrically Driven:Motor-driven configurations eliminating fuel gas consumption and enabling grid-sourced renewable power integration. Adoption is displacing alternatives at Netherlands and German chemical complexes where carbon contracts for difference subsidize capital cost premiums.
- Gas Driven:Turbine-driven compression trains leveraging on-site fuel gas availability for remote upstream locations. MAN Energy Solutions dominates this segment with proprietary axial-radial hybrid impeller architectures optimized for offshore platform weight constraints.
- Steam Driven:Turbine configurations integrated with process heat recovery systems.
- Hybrid Systems:Dual-drive arrangements enabling fuel switching between gas turbine and electric motor operation.
Gas-driven technology holds installed capacity. Electrically driven architectures are rotating up the share rankings.
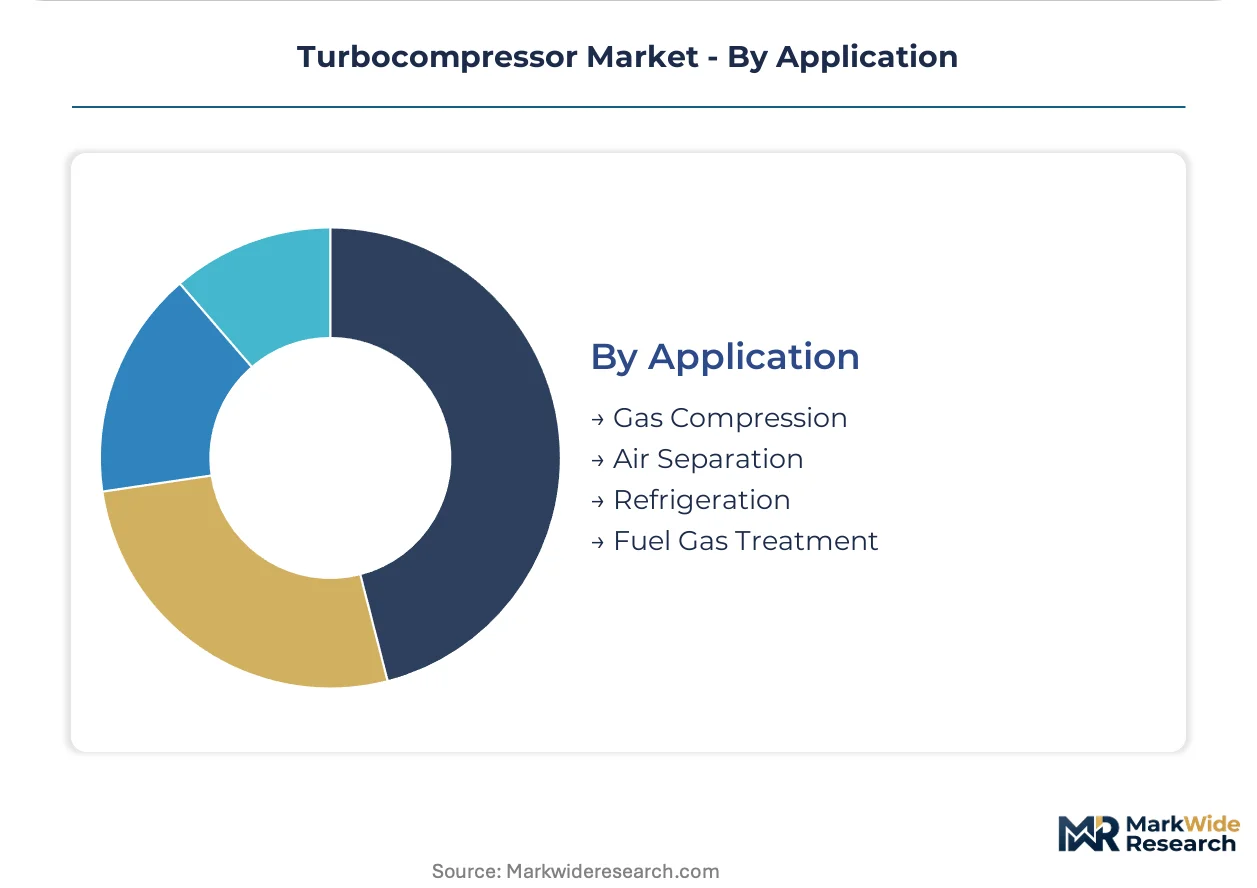
Application:
Customer type differentiation separates project-based LNG procurement from recurring chemical industry replacement cycles.
- Gas Compression:Pipeline transport, reservoir injection, and process pressure boosting across upstream and midstream operations. Demand concentrates in US Permian Basin gas gathering systems and Appalachian midstream expansions, where EPA New Source Performance Standards mandate equipment upgrades.
- Refrigeration:Turbocompressor-driven cycles for LNG liquefaction and petrochemical cold box applications. EU F-Gas Regulation phase-down schedules are restricting refrigerant options at German and Belgian clusters, forcing working fluid substitutions with modified thermodynamic properties.
- Air Separation:Cryogenic oxygen and nitrogen production for steelmaking and chemical synthesis.
- Fuel Gas Treatment:Compression and conditioning for power generation and industrial combustion applications.
Gas Compression holds installed capacity. Refrigeration is gaining share fastest as LNG liquefaction capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German turbocompressor fabricators supply LNG export infrastructure along the US Gulf Coast, while Japanese and Korean engineering houses capture orders from Australian offshore developments.
United States
EPA methane emission rules and FERC permitting timelines drive replacement cycles across petrochemical corridors. The IRA production tax credits subsidize electrification retrofits at Texas and Louisiana chemical complexes. Houston anchors procurement volume for multi-stage compression trains serving LNG baseload export terminals.
Germany
EU Green Deal carbon contracts for difference accelerate electrically driven turbocompressor adoption at chemical complexes. REACH compliance frameworks govern material selection for high-temperature impeller alloys. The Ruhr industrial belt and Ludwigshafen chemical cluster retrofit gas-driven trains for carbon accounting compliance.
Japan
METI hydrogen roadmap investments stimulate turbocompressor procurement for ammonia synthesis and hydrogen liquefaction infrastructure. JIS standards certification requirements shape equipment qualification protocols. Chubu and Kansai industrial corridors host retrofit programs at steel and chemical facilities.
Australia
Offshore LNG developments demand axial-radial hybrid designs optimized for platform weight constraints. The country's national environmental regulator enforces stringent emission thresholds for compression equipment. North West Shelf and Browse Basin projects anchor procurement for gas-driven refrigeration cycles.
Netherlands
Rotterdam port hydrogen import terminal construction creates demand for high-pressure CO2 and hydrogen compression systems. EU F-Gas Regulation phase-down schedules restrict refrigerant options for existing petrochemical cold boxes. The Chemelot industrial cluster in Limburg electrifies process gas compression under innovation fund allocations.
Turbocompressor Market Vendor Landscape
Listed leaders compete with private specialists across technology licensing and aftermarket service density. The vendor base stratifies into three tiers: diversified industrial conglomerates with full-lifecycle capabilities, mid-scale engineering specialists focused on axial-radial hybrid architectures, and regional fabricators serving maintenance-heavy installed bases. Competitive positioning depends on M&A activity targeting rotordynamics expertise and strategic partnerships securing nickel-based superalloy supply.
Among European engineering conglomerates, Siemens Energy and MAN Energy Solutions exemplify divergent technology bets. Siemens Energy occupies a position on the electrically driven vector, while MAN Energy Solutions anchors the gas-driven segment with proprietary axial-radial configurations. Atlas Copco represents the aftermarket-centric archetype, leveraging service density across installed bases for recurring revenue capture.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Siemens Energy |
| Elliott Group |
| Sulzer |
| Howden Group |
| MAN Energy Solutions |
| Kobe Steel |
| Mitsubishi Heavy Industries |
| Others |
Supply Flow & Price Mechanics
Twenty-four-month order backlogs for nickel-based superalloy forgings concentrate pricing power among Western European mills serving high-temperature impeller applications, while LNG terminal operators absorb premiums for API 617 seventh edition compliance. This supply rigidity transmits directly into multi-stage turbocompressor quotations where material costs dominate landed equipment value.
Pricing Analysis
Next-generation electrically driven architectures command 35-50% capital premiums over incumbent gas-driven trains, though operational savings compress total cost of ownership differentials across project lifecycles. Three-tier pricing structure across premium active magnetic bearing configurations, standard oil-lubricated designs, and economy single-stage units reflects engineering complexity gradients and aftermarket bundling intensity. Cost compression in standard-tier equipment intensifies as Chinese fabricators enter mid-pressure air compression segments. Independent LNG exporters exhibit highest price sensitivity due to project finance leverage constraints, while integrated majors prioritize availability guarantees over upfront capital.
Supply Chain Analysis
Germany and Austria anchor precision forging capacity for high-temperature impeller alloys, while Japan and South Korea dominate active magnetic bearing component fabrication. Nickel-based superalloy supply draws from concentrated Western European sources, with cobalt and chromium sourcing tethered to geopolitically exposed jurisdictions. Single-source vulnerability permeates large-diameter forging capacity above 2,500 millimeters. Distribution runs through OEM-direct project contracting for LNG infrastructure, with aftermarket parts flowing through authorized service networks anchored by Atlas Copco density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect as digital twin interoperability becomes mandatory for predictive maintenance contracting, compressing standalone equipment margins and elevating ecosystem-integrated vendors.
For Market Incumbents: Fortify aftermarket service density through predictive maintenance platform acquisitions before digitally native entrants capture instrumentation layers. Anchor rotordynamics expertise retention programs against specialist retirement waves. Defend position by deepening backward integration into nickel-based superalloy forging partnerships, securing material allocation priority as capacity constraints persist. For New Entrants and Emerging Players: Differentiate on carbon accounting transparency tools for electrification retrofit projects where incumbents lack native software capabilities. Target hydrogen blending infrastructure retrofits in Netherlands and German pipeline corridors where material compatibility expertise gaps persist. Pursue performance-based contracting models transferring operational risk from cash-constrained chemical processors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to monetize non-core turbomachinery divisions with stranded engineering talent. Long-term viability centers on electrification architecture pivots and carbon capture compression exposure. Monitor FERC permitting velocity for US Gulf Coast LNG terminals as inflection indicator for multi-stage procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Active Magnetic Bearing Platform Integration | Eliminates lube oil systems for offshore weight-constrained installations at North Sea developments. |
| Backward Integration into Superalloy Forging | Secures nickel-based material allocation priority against Western European capacity bottlenecks. |
| Carbon Capture Compression Train Development | Captures emerging CO2 pipeline transport demand requiring 100:1 pressure ratio configurations. |
| Performance-Based Service Contracting | Transfers operational risk from independent LNG exporters lacking rotating equipment expertise. |
| Hydrogen Service Materials Certification | Enables natural gas pipeline retrofits for hydrogen blending under EU Green Deal funding. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with turbocompressor OEM product managers, LNG terminal engineering directors, chemical plant maintenance heads, and aftermarket service executives; and secondary validation through API 617 technical committee proceedings, EPA New Source Performance Standards regulatory filings, FERC LNG export authorization databases, and customs trade data for compression equipment imports. Bottom-up equipment shipment tallies and top-down energy infrastructure investment flows were triangulated against disclosed order backlogs.
Across the analysis window, the forecasting framework modeled demand trajectories by product architecture, drive technology, end-use concentration, and regional regulatory cluster. CAGRs were derived from equipment procurement cycles tied to LNG liquefaction train additions and EPA methane compliance deadlines. Input assumptions incorporated electrification retrofit subsidies under EU Green Deal carbon contracts for difference and IRA production tax credit eligibility for Texas and Louisiana chemical complexes.
Material uncertainties — nickel superalloy supply disruptions, FERC permitting delays, or grid capacity constraints at remote upstream sites — sit outside the modeled envelope. Forecasts reflect assumptions about electrification infrastructure buildout velocity and carbon accounting rule harmonization. Recalibration cycles align with material shifts in EPA enforcement intensity and EU F-Gas Regulation phase-down schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Booster Compressor Market
Compressors
Positive-Displacement Hydrogen Compressor Market
Compressors
Axial Compressor Market
Compressors
Reciprocating Air Compressor Market
Compressors
Gas Compressors Market
Compressors
Rental Air Compressors Market
Compressors
LNG Compressor Market
Compressors
Chlorine Compressors Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Compressed Air Lubricators Market
Compressors
Portable Air Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Europe Centrifugal Compressor Market
Compressors
High Speed Blowers Market
Compressors
Middle East and Africa Booster Compressor Market
Compressors
Portable Compressor Market